Hi, I'm Asif Khan, the voice behind paisakmao.de. For the past two years, I’ve been blogging about financial education, income skills, and mindset development for students and young minds. My mission is to empower every youth with financial literacy and practical money-making skills at an early age. Through paisakmao.de, I share actionable guides for students to start earning early, money wisdom that schools don’t teach, and mindset lessons from successful people and modern psychology. Whether you're a teenager looking to earn your first income or a student exploring side hustles, you're in the right place. Financial freedom begins with the right mindset and the right knowledge. Let’s grow, earn, and evolve together — welcome to the movement!
Imagine you suddenly need ₹10,000 for a medical bill, urgent travel, a job gap, or an unexpected repair. If all your money is sitting in the same account you use for everyday spending, you may end up using money meant for other goals—or worse, borrowing to cover the expense.
That’s where an emergency fund becomes important. But there’s one question many beginners have: should an emergency fund be kept in a regular savings account, or should you keep it somewhere else?
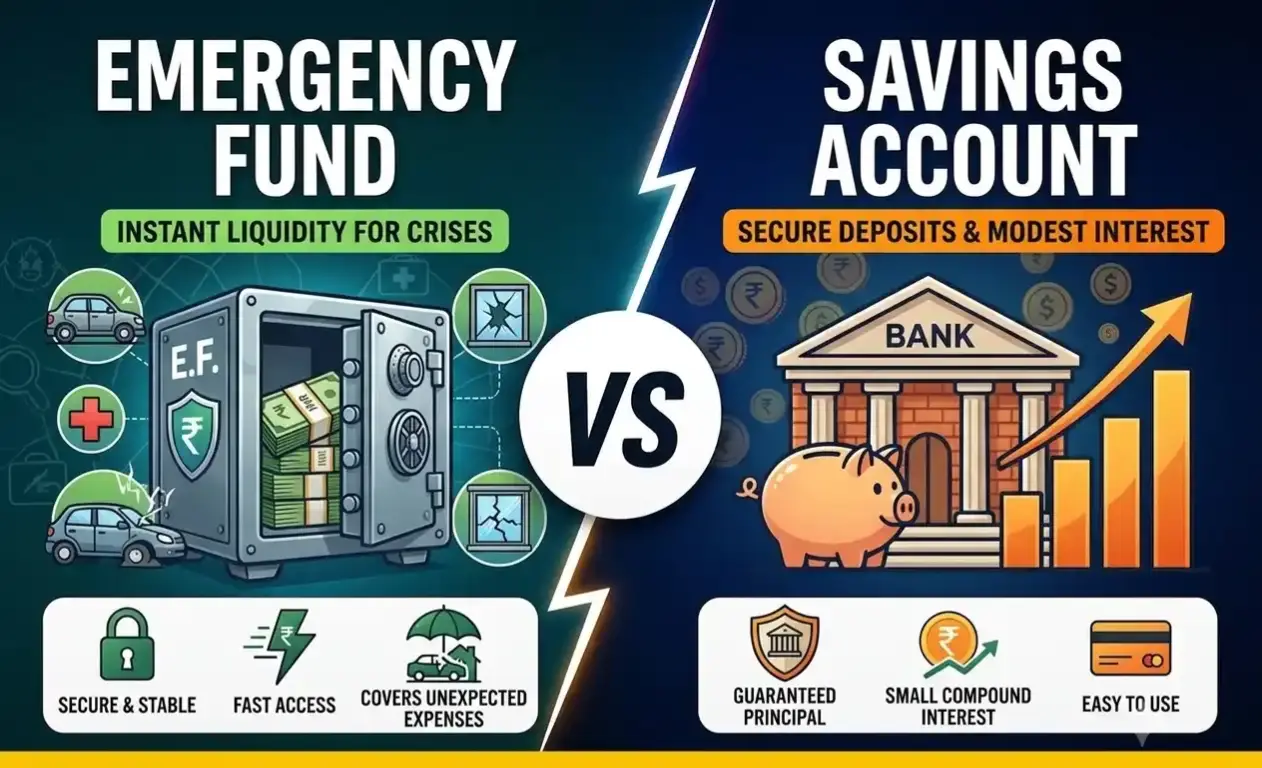
The important thing to understand is that an emergency fund and a savings account are not competing products. An emergency fund is money reserved for unexpected expenses, while a savings account is one of the places where you can keep that money.
In this guide, we’ll break down emergency fund vs savings account, how much you should keep aside, and the practical places where you can keep your emergency money in India—without sacrificing safety and easy access.
What You’ll Learn in This Guide
By the end of this guide, you’ll know:
Emergency fund vs savings account — dono mein kya difference hai aur emergency money ke liye kya purpose hai.
How much emergency fund you need — 3–6 months ke expenses ka target kaise calculate karein.
Risks of keeping all your money in one account — low returns aur everyday spending ka emergency savings par kya effect ho sakta hai.
Where to keep your emergency fund in India — savings account, sweep-in FD aur liquid mutual funds jaise options ko samjhenge.
How to build an emergency fund with a low or irregular income — fixed salary na hone par bhi backup fund kaise banayein.
Common emergency fund mistakes — PPF, ELSS ya ghar par bahut zyada cash rakhne jaise mistakes se kaise bachein.
Practical FAQs — credit card aur digital gold ko emergency backup ke liye use karna chahiye ya nahi.
What Is an Emergency Fund and Why Do You Need It?
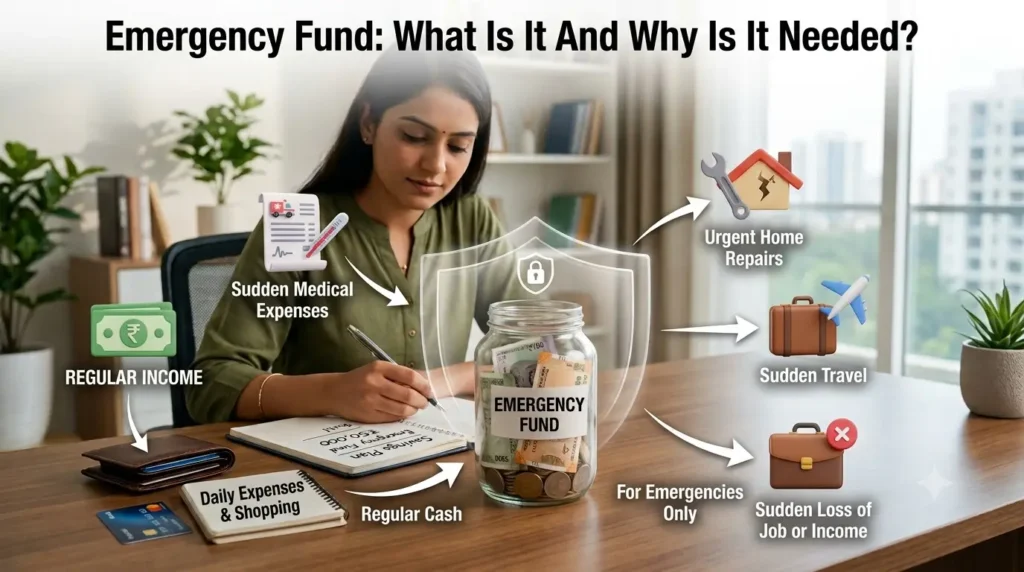
An emergency fund is money kept aside for unexpected expenses that can disturb your normal budget. It can help you handle things like a medical bill, urgent travel, essential repair, job loss, or a temporary income gap without immediately borrowing money.
Think of it as your financial safety net. Your regular income already has many jobs—food, rent, bills, transportation, savings and investments. An emergency fund is there for the expenses you didn’t see coming.
Emergency Fund vs Regular Savings: What’s the Difference?
The main difference between an emergency fund and regular savings is their purpose. Emergency savings are for unexpected problems, while regular savings are often used for planned expenses or goals.
For example, if you’re saving ₹40,000 for a laptop, that’s goal-based savings. But if you keep ₹60,000 aside in case your income stops temporarily or an unexpected expense appears, that’s your emergency fund.
Money Type
Purpose
Example
Emergency fund
Unexpected expenses
Medical bill, job gap, repair
Regular savings
General saving
Money you’re building up
Goal savings
Planned expense
Laptop, education, travel
Investments
Long-term goals
Retirement, wealth building
One important thing: an emergency fund doesn’t have to be a special financial product. You can keep it in a savings account. What makes it an emergency fund is the purpose you’ve given that money.
Can an Emergency Fund Be Kept in a Savings Account?
Yes, an emergency fund can be kept in a savings account, and a separate account can make it easier to avoid spending that money accidentally.
I learned this from my own saving habit too. Instead of keeping all my money in the account I used for everyday expenses, I started putting some money into a separate account. The amount wasn’t always big, but keeping it separate made me think twice before touching it.
Gradually, that separate balance became my backup money.
This is a simple idea that can work for beginners: when your income comes in, move a small amount into your emergency fund before you start spending on non-essential things.
For example, if you receive ₹25,000 and can comfortably save ₹2,000, you could move that ₹2,000 into your separate emergency savings account.
The U.S. Consumer Financial Protection Bureau also recommends keeping emergency savings specifically for unplanned expenses and notes that even a small amount can provide some financial security.
You can use our Budget Calculator to understand your monthly expenses and decide how much you can realistically save.
For eligible bank deposits in India, DICGC deposit insurance currently covers up to ₹5 lakh per depositor per bank, subject to its applicable rules.
How Many Months of Expenses Should You Save?
A common starting target is 3–6 months of essential expenses, but the right amount depends on your income, responsibilities and financial situation.
Use this simple formula:
Monthly essential expenses × Number of months = Emergency fund target
For example, if your essential expenses are ₹20,000 per month:
3 months = ₹60,000
6 months = ₹1,20,000
You don’t have to save ₹1.2 lakh immediately. Start with a smaller milestone:
₹10,000 → ₹25,000 → ₹50,000 → 3 months → 6 months
If your income is irregular, you may need a larger cushion because your monthly income can change. For example, if you earn ₹18,000 one month and ₹30,000 the next, you can save more during stronger months and a smaller amount during difficult months.
MoneyHelper in the UK also uses three to six months of essential outgoings as a common rule of thumb for emergency savings.
Why Is an Emergency Fund Important?
An emergency fund gives you money to fall back on when something unexpected happens, reducing the need to immediately borrow or disturb other financial goals.
Imagine you suddenly need ₹15,000.
Without an emergency fund, you might need to borrow, use a credit card, delay another payment, or sell an investment.
With an emergency fund, you can use part of your reserve and then rebuild it later.
That’s why the first priority of emergency money should be safety and accessibility, rather than chasing the highest possible return.
☐ I have started saving a separate emergency fund.
☐ I have calculated my initial target.
☐ I can access the money when a genuine emergency happens.
☐ I’m not treating the fund as normal spending money.
☐ I’m gradually working toward 3–6 months of essential expenses, if appropriate for my situation.
☐ I review the target when my income or expenses change.
You don’t need a huge amount to start. The important thing is to create the habit of keeping some money aside for the unexpected.
The Hidden Risks of Keeping All Your Emergency Cash in a Regular Savings Account
Keeping your emergency fund in a savings account is not automatically a bad idea. In fact, easy access and safety are more important than chasing high returns when it comes to emergency money.
The problem is usually not the savings account itself. The bigger issues are keeping your emergency money mixed with everyday spending money and ignoring how inflation affects its purchasing power.
If you’re still trying to understand where your money goes every month, you can first use our Budget Calculator to calculate your regular expenses.
Why Low Interest Rates Are Losing You Money to Inflation
When your savings earn less than the rate at which prices are rising, your money can lose purchasing power over time. Your account balance may stay the same or increase slightly, but the same amount may buy fewer things later.
For example, imagine you keep ₹1,00,000 in a savings account for several years.
If the interest you earn is lower than inflation, the ₹1,00,000 may not have the same purchasing power in the future. This is why simply looking at your account balance doesn’t tell the whole story.
The U.S. Bureau of Labor Statistics tracks changes in consumer prices through the Consumer Price Index (CPI), which is one way economists measure inflation.
But this does not mean you should put your emergency fund into risky investments just to beat inflation.
Your emergency fund has a different job.
Think about its priorities like this:
Safety
Easy access
Reasonable return
Higher return only when the first two aren’t compromised
The Consumer Financial Protection Bureau recommends keeping emergency savings somewhere safe and accessible because the money may be needed when an unexpected expense occurs.
So instead of asking only:
“Where can I get the highest return?”
Ask:
“Where can I keep this money safe and access it quickly when I actually need it?”
That question is much more useful when you’re dealing with an emergency fund.
The Temptation of Impulse Spending with Debit Cards
Keeping your emergency fund in the same account you use for everyday spending can make it easier to spend the money without realising it.
Suppose your bank balance shows ₹80,000.
You know that ₹50,000 of it is actually your emergency fund, but the entire amount is sitting in the same account you use for UPI payments, shopping, food and entertainment.
Then you see something you want to buy.
Your brain sees:
“I have ₹80,000.”
But your actual spending money is only ₹30,000.
This is one reason a separate emergency savings account can be useful. You can still access the money when there’s a genuine emergency, but it isn’t constantly sitting in front of you while you’re making everyday purchases.
The CFPB also discusses keeping emergency savings in a dedicated place that is safe and accessible while reducing the temptation to spend it on non-emergency purchases.
A simple setup could look like this:
Main account: salary, UPI, bills and daily expenses
Emergency fund: unexpected expenses only
Goal savings: laptop, education, travel or other planned purchases
Investments: long-term financial goals
This separation doesn’t have to be complicated.
For example, if you receive ₹25,000, you might decide that ₹2,000 goes toward your emergency fund, while the remaining money is used for your regular budget and other goals.
The exact amount will depend on your income and expenses. The important part is giving your emergency money a clear purpose.
If you’re managing several financial goals at the same time, our guide on How to Organize Multiple Savings Goals Before 2027 can help you separate different savings targets instead of mixing everything together.
How to Keep Your Emergency Fund Accessible Without Making It Easy to Spend
The simplest approach is to keep your emergency money separate from your everyday spending account while making sure you can still access it when a genuine emergency happens.
For example, suppose your essential expenses are ₹30,000 per month.
A 3-month starter target would be:
₹30,000 × 3 = ₹90,000
Instead of keeping that ₹90,000 mixed with your normal spending balance, you could keep it in a separate suitable account or another low-risk, accessible option.
Don’t choose an emergency-fund option only because it offers a higher return. Choose a place where your money is reasonably safe, accessible and less likely to be spent accidentally.
Your emergency fund isn’t designed to make you rich.
Its job is to make an unexpected financial problem easier to handle.
3 Best and Safest Places to Keep Your Emergency Fund in India
The best place for an emergency fund should give you two things: easy access and reasonable safety. You don’t necessarily need to keep the entire fund in one account. You can divide it between a regular savings account and another low-risk option depending on how much money you have.
1. Sweep-in Fixed Deposits: A Balance Between Liquidity and Returns
A sweep-in fixed deposit can be useful for keeping part of your emergency fund while still having relatively easy access to the money.
For example, suppose you have a ₹1 lakh emergency fund. You could keep ₹30,000 in a savings account for immediate expenses and place the remaining ₹70,000 in a sweep-in FD, depending on the bank’s rules and terms.
The advantage is that the FD portion may earn more interest than money sitting entirely in a normal savings account. When you need money, the linked sweep facility may automatically break the required portion of the FD, depending on the bank’s conditions.
However, don’t assume every sweep-in FD works the same way. Check the bank’s rules for minimum balance, premature withdrawal, sweep limits, interest calculation and how quickly the money becomes available.
Also, eligible bank deposits such as savings and fixed deposits are covered by DICGC deposit insurance up to ₹5 lakh per depositor per bank, subject to the applicable rules.
Best suited for: People who already have some emergency savings and want part of it to earn more while keeping access reasonably convenient.
2. A Separate Savings Account from a Scheduled Bank
A separate savings account is one of the simplest ways to keep an emergency fund away from your everyday spending money.
For example:
Main account → salary, UPI and regular expenses
Emergency account → medical bills, job gap and urgent repairs
Goal account → travel, education or a future purchase
This separation can make your emergency fund easier to protect because you are less likely to accidentally spend it on everyday purchases.
Before opening a separate account, compare things such as interest rate, minimum balance requirements, account charges, ATM/UPI access and withdrawal convenience.
If you’re keeping a larger amount in bank deposits, also understand the DICGC limit. Deposits in different accounts at the same bank and same ownership capacity are generally aggregated when calculating the ₹5 lakh insurance limit. Deposits held with different banks have separate coverage limits.
You can also use your Budget Calculator to estimate your monthly essential expenses and work out how much emergency money you need.
Best suited for: Beginners who want a simple, accessible and easy-to-manage emergency fund.
3. Liquid Mutual Funds: An Option to Understand Carefully
Liquid mutual funds can be considered for some short-term money, but they should not be treated as the same thing as a bank savings account or FD.
A liquid mutual fund invests in short-term money-market and debt instruments. Its value can change, and mutual funds are not covered by DICGC deposit insurance. DICGC specifically lists mutual funds among the products that are not covered by its deposit insurance scheme.
SEBI’s investor disclosures also make clear that mutual fund investments involve investment risks and that returns are not guaranteed.
So, if you’re building your first emergency fund, you don’t need to move everything into a liquid mutual fund just to chase a potentially higher return. The first priority should be having money available when you genuinely need it.
If you already have a well-built emergency fund and understand how liquid mutual funds work, you can decide whether they fit a portion of your short-term money.
Best suited for: Someone who understands mutual funds and wants to consider a separate short-term investment option—not someone looking for a guaranteed emergency-fund product.
Which Option Should You Choose?
Option
Access
Main Benefit
Important Limitation
Separate savings account
Very easy
Simple and accessible
Interest may be modest
Sweep-in FD
Relatively easy
Combines FD with linked access
Bank-specific conditions
Liquid mutual fund
Through redemption
Potential short-term return
Market-linked and not DICGC-insured
For most beginners, the important thing isn’t finding the option with the highest possible return. Your emergency money exists for one reason: to be available when something unexpected happens.
If you’re still building your first emergency fund, start small and make the habit automatic. You can later increase the amount as your income grows.
How to Connect Your Emergency Fund with Your Budgeting Strategy?
Your emergency fund works best when it is built into your regular budget instead of being treated as something you will save only when extra money is left over. Even a small amount saved consistently can gradually create a useful financial cushion.
The RBI’s financial education material recommends keeping an emergency fund in a separate, easily accessible savings account and building it gradually if you cannot fund the entire amount at once.
For example, if you earn ₹20,000 per month, you don’t have to wait until you can save ₹60,000 or ₹1 lakh. You could start with ₹500, ₹1,000, or whatever amount your budget can comfortably handle.
Applying the Cash Stuffing Method for Emergency Cash
The cash stuffing method can help you control everyday spending, but your main emergency fund does not need to be kept as physical cash at home.
Cash stuffing usually means dividing your spending money into separate categories so you know how much you can spend on things such as groceries, transport, entertainment and other expenses.
You can use the same idea digitally for your emergency fund.
For example:
Money Category
Example Amount
Monthly expenses
₹15,000
Emergency fund
₹2,000
Short-term goals
₹1,500
Flexible spending
₹1,500
Instead of putting ₹2,000 into an envelope and keeping it at home, you could transfer it to a separate savings account labelled for emergencies.
This gives you the psychological benefit of separating your money without keeping a large amount of cash physically at home.
The CFPB also recommends keeping emergency savings somewhere that is safe, accessible and less tempting to spend on non-emergency purchases.
If you want to learn the complete budgeting technique, you can also read our Cash Stuffing Method guide.
How to Build a Backup Fund with an Irregular Income
If your income changes every month, use a flexible savings target instead of forcing yourself to save the exact same amount every month.
For example, imagine your income looks like this:
January: ₹18,000
February: ₹25,000
March: ₹14,000
April: ₹30,000
Saving ₹5,000 every month may not be realistic. Instead, you could save a smaller amount during low-income months and put more aside when your income is higher.
For example:
Monthly Income
Possible Emergency Saving
₹14,000
₹500
₹18,000
₹1,000
₹25,000
₹2,000
₹30,000
₹3,000
These are only examples—not fixed rules. Your actual amount should depend on your essential expenses and what your budget can comfortably handle.
The CFPB specifically notes that people with fluctuating income can use cash-flow management and save more during periods when they have extra money available.
You can also use our Budget Calculator to estimate your monthly expenses and see how much you can realistically put toward your emergency fund.
If your income changes frequently, our guide How to Budget with an Irregular Income can also help you build a more flexible monthly plan.
A Simple Emergency-Fund Budget Rule
A simple approach is to treat your emergency fund as a regular budget category.
For example:
Income → Essential expenses → Emergency savings → Other goals → Flexible spending
You don’t have to start with a large amount. The important part is creating a system that you can repeat.
Once your emergency fund reaches your first target—perhaps ₹10,000 or ₹25,000—you can continue building it toward several months of essential expenses.
And if you ever need to use the fund, that’s exactly what it is there for. After the emergency is handled, make rebuilding the fund one of your next savings priorities.
This approach turns your emergency fund from a one-time goal into a habit that becomes part of your overall budgeting system.
Common Emergency Fund Mistakes to Avoid
Building an emergency fund is a great step, but where and how you keep the money matters too. Some common mistakes can make your emergency fund difficult to access when you actually need it.
Here are two mistakes beginners should avoid when setting up an emergency backup.
Locking Your Money in Long-Term Investments Like PPF or ELSS
Your main emergency fund should generally not be locked into long-term investments such as PPF or ELSS, because an emergency can happen before the money becomes easily accessible.
PPF is designed as a long-term savings scheme. The account has a 15-year maturity period, although certain withdrawals and other facilities are available under specific conditions. (indiapost.gov.in)
ELSS mutual funds have a 3-year lock-in period for each investment. That means you cannot simply redeem your ELSS investment whenever you want during the applicable lock-in period. SEBI also describes mutual funds as market-linked investments where returns are not guaranteed. (sebi.gov.in)
Imagine you suddenly need ₹30,000 for an urgent expense. If that money is sitting inside a product with access restrictions, you may have to find another source of money.
That’s why it helps to separate your financial goals:
Money
Suitable Purpose
Emergency fund
Unexpected expenses
PPF
Long-term savings
ELSS
Long-term investment/tax-saving goals
Goal savings
Planned expenses
Other investments
Long-term wealth building
Your emergency fund doesn’t need to generate the highest possible return. Accessibility and safety are more important for money you may need unexpectedly.
Keeping a small amount of cash for immediate needs can be practical, but your entire emergency fund should generally not be stored as physical cash at home.
For example, keeping ₹2,000–₹5,000 at home for situations where digital payments aren’t available may be different from keeping ₹1 lakh in cash at home.
Large amounts of physical cash can be exposed to risks such as theft, loss, fire or simply being forgotten or spent. It also doesn’t earn interest while sitting unused.
A better approach can be to keep a small cash buffer for immediate situations and store the larger emergency fund in an appropriate separate bank account or other suitable accessible option.
For bank deposits, DICGC provides deposit insurance up to ₹5 lakh per depositor per bank, subject to the applicable rules. This is another reason to understand how your bank deposits are covered rather than assuming every type of financial product has the same protection. (dicgc.org.in)
A Simple Way to Avoid Both Mistakes
You can keep your money organised into three simple buckets:
1. Immediate cash: A small amount for situations where cash is necessary.
2. Emergency fund: Money kept in an easily accessible, suitable savings option for unexpected expenses.
3. Long-term investments: Money invested for goals that are years away.
This separation makes your financial system easier to understand and reduces the chance of using long-term investments for short-term emergencies.
And remember, an emergency fund is not supposed to make you rich. Its job is to protect your financial plan when life doesn’t go according to plan.
How Much Emergency Fund Should I Have?
A common starting target is 3–6 months of essential living expenses. But you don’t have to reach that amount immediately.If your essential expenses are ₹20,000 per month, a 3-month emergency fund would be ₹60,000, while 6 months would be ₹1.2 lakh. If that feels too large, start with a smaller target such as ₹10,000 or ₹25,000 and build it gradually.
Where Should I Keep My Emergency Fund?
Keep your emergency fund somewhere safe and easily accessible, such as a separate savings account or another suitable low-risk option.The main goal is not to get the highest possible return. You want the money to be available when an unexpected expense happens without taking unnecessary investment risk.
Should I Keep My Emergency Fund in One Bank Account?
You don’t necessarily have to keep the entire emergency fund in one account. You can keep some money immediately accessible in a savings account and use another suitable option for the remaining amount, depending on your needs.For larger bank deposits, remember that DICGC deposit insurance has an applicable limit of ₹5 lakh per depositor per bank, subject to its rules.
Conclusion: Take the First Step Towards Financial Peace of Mind An emergency fund is one of the simplest ways to protect yourself from unexpected financial problems. Whether it’s a medical expense, urgent repair, sudden travel, or a temporary loss of income, having money set aside can help you handle these situations without immediately depending on credit or loans. The key is to understand that an emergency fund is different from your regular savings goals. Your emergency money should be kept separate, easily accessible, and in a place where you can use it when you genuinely need it. For many people, a separate savings account can be a simple starting point. A sweep-in FD can be considered for part of the fund, while liquid mutual funds are an option that should be understood carefully because they are market-linked and not the same as bank deposits. You also don’t need to build your emergency fund overnight. Start with whatever amount your budget allows and gradually work toward 3–6 months of essential expenses. If your income is irregular, adjust your contribution according to your income instead of forcing yourself to save the same amount every month. Most importantly, avoid common mistakes such as locking your emergency money into long-term investments or keeping a large amount of physical cash at home. Start small, keep it separate, and keep building it. A well-planned emergency fund may not feel exciting, but when an unexpected expense arrives, it can give you something much more valuable: financial breathing room.
Hi, I’m Asif Khan, the voice behind paisakmao.de. For the past two years, I’ve been blogging about financial education, income skills, and mindset development for students and young minds. My mission is to empower every youth with financial literacy and practical money-making skills at an early age. Through paisakmao.de, I share actionable guides for students to start earning early, money wisdom that schools don’t teach, and mindset lessons from successful people and modern psychology. Whether you’re a teenager looking to earn your first income or a student exploring side hustles, you’re in the right place. Financial freedom begins with the right mindset and the right knowledge. Let’s grow, earn, and evolve together — welcome to the movement!
Planning for multiple financial goals can feel overwhelming. This simple guide shows you how to prioritize your goals, set realistic targets, calculate monthly savings, and stay on track for 2027.
Saving for one goal is simple. But when you have several goals at the same time—such as an emergency fund, annual expenses, a new laptop, a trip, or future needs—it can become difficult to know where your money should go first.
The key is not to save for everything equally. You need to organize multiple savings goals, set priorities, and decide how much to save for each goal based on its deadline and importance.
In this guide, you’ll learn how to organize your savings goals, set realistic targets, calculate your monthly savings, and create a simple plan you can follow before 2027.
Step 1: List All Your Savings Goals
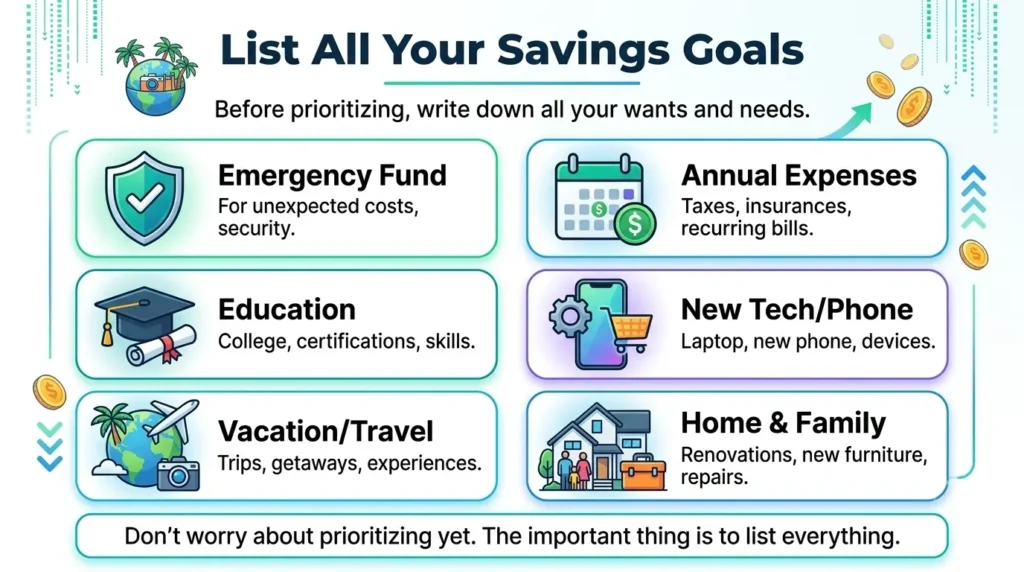
Before deciding how much to save for each goal, write down everything you want or need to save for.
Include both important financial goals and upcoming expenses, such as:
Emergency fund
Annual bills or expenses
Education
New phone or laptop
Vacation or travel
Home or family expenses
Other planned purchases
Don’t worry about prioritizing them yet. The first goal is simply to get a clear picture of where your money may need to go.
Once you have listed everything, you can group the goals by time frame, importance, and deadline. This makes it much easier to decide which goals should receive more attention first.
Step 2: Separate Short-Term, Medium-Term, and Long-Term Savings Goals
Not every savings goal has the same deadline. A bill due next month needs a different approach from a car you want to buy in three years or a future financial goal that may take much longer.
That is why one of the easiest ways to organize multiple savings goals is to separate them by time frame.
Short-Term Savings Goals
Short-term goals are goals you expect to reach relatively soon, such as annual bills, emergency expenses, a phone, or a planned purchase.
These goals usually need more immediate attention because their deadlines are closer.
Medium-Term Savings Goals
Medium-term savings goals sit between immediate expenses and long-term financial goals. They may take several months or a few years to complete, depending on the size and deadline of the goal.
Common examples include:
Buying a car
Saving for education or training
A major home expense
Starting a small business
Saving for a wedding or major event
Preparing for a large planned purchase
The advantage of a medium-term goal is that you have more time to build the money. Instead of trying to save a large amount at once, you can break the target into smaller monthly savings contributions.
For example, suppose your goal is to save $3,000 in 30 months.
$3,000 ÷ 30 = $100 per month
So your basic monthly savings target would be $100.
Goal
Target
Time Remaining
Monthly Target
Priority
Education
$3,000
30 months
$100
High
Car fund
$6,000
36 months
$167
Medium
Major purchase
$1,500
24 months
$63
Low
This gives you a clearer picture of how much each goal requires instead of simply saving money without knowing whether you are on track.
What If the Monthly Amount Is Too High?
This is where a realistic savings plan matters.
If your calculated monthly contribution does not fit your budget, you have several options:
Extend the deadline if possible.
Reduce the target amount.
Give the goal a lower priority.
Temporarily focus on a more important goal.
Look for ways to reduce expenses or increase available savings.
You do not have to abandon a goal just because the first calculation does not fit your current cash flow.
The Consumer Financial Protection Bureau recommends breaking savings goals into manageable targets and considering the amount needed and the time available when creating a savings plan.
For a broader reference, you can also review the CFPB’s savings and goal-setting tools, which include tools for setting goals, planning savings, tracking money, and preparing for large purchases.
For your own numbers, you can use our budget calculator to see how your income and expenses affect the amount available for different savings goals.
The important point is simple: medium-term goals should have a target, deadline, and monthly contribution. Once those three numbers are clear, a large future expense becomes much easier to manage.
Step 3: Prioritize Your Savings Goals
Once you have separated your goals by time frame, the next step is to decide which savings goals should come first.
When you have multiple savings goals, you do not always need to divide your money equally. Some goals are more important because they protect your financial stability, have a fixed deadline, or could create a bigger problem if you do not prepare for them.
A simple priority system can help you decide where your monthly savings should go first.
Start With Financial Safety
Before putting a large amount toward optional goals, consider whether you have enough money set aside for unexpected expenses.
An emergency fund can help cover unexpected costs such as an urgent repair, medical expense, or temporary loss of income without forcing you to depend on debt.
Your financial priorities will depend on your situation, but building a basic financial safety net is often an important starting point.
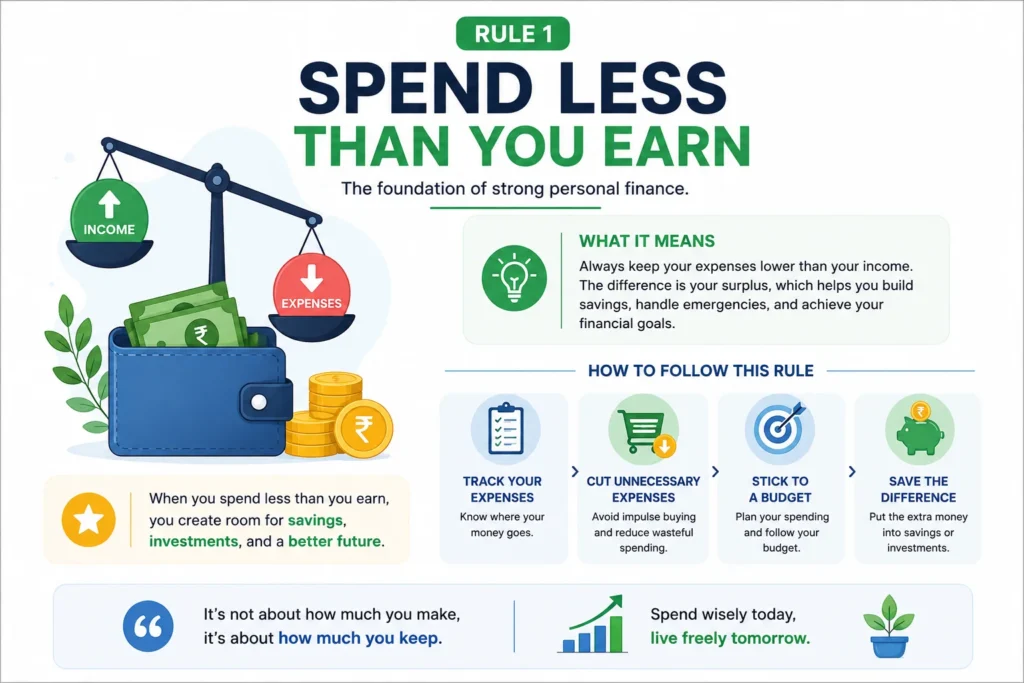
For a broader overview, read our guide to the 7 rules of personal finance, which explains the role of budgeting, emergency savings, debt management, and long-term financial goals.
Consider the Deadline and Consequences
Not every savings goal has the same level of urgency. A goal with a fixed deadline may need more attention than a goal that can be delayed.
Before deciding how to divide your savings, ask yourself:
Does this expense have a fixed deadline?
What happens if I do not save enough by that date?
Is the goal essential or optional?
Can I delay the goal without creating a financial problem?
Could failing to prepare lead to debt or another financial cost?
Does this goal protect my basic financial needs?
For example, an annual insurance payment due in three months may deserve more attention than a vacation planned for next year.
The vacation can still be an important savings goal, but its deadline and consequences are different.
Use a High, Medium, and Low Priority System
A simple three-level priority system makes it easier to manage multiple savings goals without feeling overwhelmed.
Priority
Type of Goal
Example
High
Financial safety or essential deadline
Emergency fund, essential annual expense
Medium
Important planned expense
Education, major repair, vehicle
Low
Optional or flexible goal
Vacation, new gadget, entertainment
This does not mean low-priority goals should never receive money. It simply means they should not take money away from a more important financial need when your available savings are limited.
How to Divide Money Between Savings Goals
If your monthly savings amount is limited, a useful starting order is:
Financial safety
Essential upcoming expenses
Important planned goals
Optional goals
For example, suppose you can save $300 per month and you have three goals:
Emergency fund — High priority
Education — Medium priority
Vacation — Low priority
Instead of automatically giving each goal $100, you could direct more of your available savings toward the emergency fund and education while making a smaller contribution toward the vacation.
The exact amounts depend on your income, essential expenses, current savings, and the deadlines of your goals.
One common mistake when managing multiple savings goals is assuming that every goal should receive the same amount of money.
For example, imagine you have $500 available for savings and the following goals:
Goal
Amount Needed
Deadline
Priority
Emergency fund
$1,500
Flexible
High
Annual bill
$600
4 months
High
Laptop
$1,000
10 months
Medium
Vacation
$1,200
12 months
Low
An equal split would give each goal $125. But the annual bill has a much closer deadline, while the vacation may be more flexible.
Your savings plan should reflect importance and urgency, not simply equality.
What If Two Savings Goals Have the Same Priority?
When two goals are equally important, use their deadlines to decide which one should receive more attention.
As a simple rule, consider the goal that:
Has the earlier deadline.
Requires a larger monthly contribution.
Has greater consequences if you miss the target.
You can also change the priority later. Your income, expenses, deadlines, and financial goals may change, so your savings plan should be flexible enough to change with them.
Keep Your Savings Priorities Simple
You do not need a complicated financial planning system to organize multiple savings goals.
For each goal, know these four things:
What you are saving for
How much you need
When you need it
How important it is compared with your other goals
Once these details are clear, it becomes much easier to decide where your money should go each month.
The goal is not to create a perfect plan that never changes. The goal is to build a practical savings plan that gives every dollar a purpose while keeping your most important financial goals on track.
Step 4: Set a Target Amount and Deadline for Every Savings Goal
Once you know which savings goals are most important, give each goal a specific target amount and deadline.
“I want to save more money” is a good intention, but it is difficult to follow because there is no clear finish line. A better savings plan tells you exactly how much you need, when you need it, and how much you should save each month.
This approach can make multiple savings goals much easier to organize and track.
Give Every Financial Goal a Specific Target
Start by deciding the approximate amount you need for each goal.
For example, instead of writing:
Save for a laptop
Save for a trip
Save for education
Turn them into measurable goals:
Laptop — $1,000
Trip — $1,500
Education — $3,000
A specific target gives you something you can calculate against. It also makes it easier to see whether your current monthly savings are enough.
Set a Realistic Savings Deadline
After deciding the target amount, choose when you want or need to reach it.
Your deadline can be based on:
A fixed bill or payment date
A planned purchase
A school or education deadline
A planned trip or event
A personal financial milestone
A timeframe that is realistic for your income
Try not to choose a deadline simply because it sounds good. A deadline should be realistic enough that you can continue making the required monthly contribution without putting your essential expenses under pressure.
Calculate the Time You Have Left
Once you know the target and deadline, calculate how many months you have remaining.
For example:
Goal
Target
Time Available
Approx. Monthly Saving
Laptop
$1,000
10 months
$100
Trip
$1,500
12 months
$125
Education
$3,000
24 months
$125
These numbers give you a starting point for building your monthly savings plan. In the next step, we will use the same information to calculate the required monthly contribution more precisely.
Use the SMART Approach for Savings Goals
A useful way to make a savings goal clearer is to make it specific and measurable, with a realistic timeframe.
For example:
Vague goal: “I want to save for a laptop.”
Clear goal: “I want to save $1,000 for a laptop within 10 months.”
The second goal gives you three important pieces of information:
You do not need to convert these amounts into one currency. Keep each goal in the currency you will actually spend.
What If the Target Is Too High for Your Income?
This is where your savings plan becomes practical.
Suppose you calculate that you need to save $400 per month for several goals, but after essential expenses you can realistically save only $250.
Do not simply assume you have failed. Rework the plan.
You could:
Extend the deadline
Reduce the target amount
Give higher priority to the most important goal
Temporarily pause a lower-priority goal
Reduce unnecessary expenses
Increase your savings contribution when your income rises
A realistic savings target that you can consistently follow is usually more useful than an aggressive target that makes your monthly budget impossible to maintain.
Keep Your Savings Goals in One Simple Table
Once you have several goals, put the important numbers in one place. This makes it easier to see the complete picture instead of keeping separate notes in your head.
Goal
Target
Saved
Remaining
Deadline
Priority
Emergency fund
$1,500
$600
$900
Flexible
High
Laptop
$1,000
$250
$750
10 months
Medium
Vacation
$1,200
$300
$900
12 months
Low
This simple savings tracker gives you a quick view of what you are saving for, how much you have already saved, what remains, and which goals deserve the most attention.
Once every goal has a target and deadline, the next step is to calculate exactly how much you need to save each month.
Step 5: Calculate Your Monthly Savings for Each Goal
Now that every savings goal has a target amount and deadline, you can calculate how much you need to save each month.
This is the point where a list of financial goals becomes an actual savings plan. Instead of guessing how much to put aside, you can work backward from the amount you need and the time available.
For example, suppose you want to save $1,200 for a planned purchase and you have 12 months remaining.
$1,200 ÷ 12 = $100 per month
So, you would need to set aside approximately $100 each month to reach the target, assuming the money you save does not earn additional returns and there are no extra costs.
Calculate Each Savings Goal Separately
When you have multiple savings goals, calculate the monthly contribution for each one instead of combining all the targets into one number.
Goal
Amount Remaining
Months Remaining
Monthly Savings
Emergency fund
$1,000
10
$100
Laptop
$900
9
$100
Vacation
$1,200
12
$100
In this example, the total monthly requirement would be:
$100 + $100 + $100 = $300 per month
Now you can compare that $300 requirement with the amount your monthly budget can realistically provide.
Check Your Monthly Savings Capacity
Before committing to a savings target, look at your actual cash flow.
If your savings goals require $300 per month and you can realistically save $400, the plan has some room for unexpected expenses or faster progress.
If your goals require $550 but your realistic savings capacity is only $400, you need to adjust the goals rather than forcing an unrealistic budget.
Use a Budget Calculator to Find Your Available Savings
Working out your income and expenses manually can become difficult when you have several financial goals.
You can use our Budget Calculator to organize your income and spending and get a clearer idea of how much money may be available for savings each month.
Once you know your available savings amount, you can compare it with the monthly contribution required for each goal.
What If Your Monthly Savings Requirement Is Too High?
This is one of the most important parts of creating a realistic savings plan.
If the numbers do not fit your budget, do not simply cut essential expenses or put yourself under unnecessary financial pressure. Rework the plan.
You can:
Extend the deadline: Give yourself more months to reach the target.
Reduce the target: Look for a lower-cost version of the planned purchase.
Prioritize: Put more money toward essential or time-sensitive goals.
Pause a lower-priority goal: Temporarily stop funding a flexible goal.
Increase your savings capacity: Reduce unnecessary spending or direct future extra income toward the goal.
Review the target: Make sure the original amount is still realistic.
A savings plan should fit your real financial situation. A target that looks impressive on paper but cannot be maintained every month is not a useful target.
Use the Deadline to Adjust Your Monthly Contribution
Your monthly savings requirement can change when the deadline changes.
Target
Deadline
Monthly Savings
$1,200
6 months
$200
$1,200
12 months
$100
$1,200
18 months
About $67
This shows why the deadline matters. The same savings goal can require very different monthly contributions depending on how much time you have.
Do Not Forget the Amount You Have Already Saved
If you have already saved part of the money, calculate the monthly requirement using the remaining amount, not the original target.
This makes your savings target more accurate and prevents you from saving more than necessary for the same goal.
Keep a Small Buffer for Real Life
Monthly budgets do not always go exactly as planned. An unexpected expense can temporarily reduce the amount you are able to save.
For that reason, avoid building a savings plan that uses every available dollar with no flexibility.
If your calculations show that you can save $400 per month, but your goals require exactly $400, consider whether you need some breathing room for irregular expenses before committing to the full amount.
This is especially important when your income changes from month to month.
Once you calculate the monthly requirement for every goal, add them together and compare the total with your realistic monthly savings capacity.
If required savings ≤ available savings: Your plan may be realistic.
If required savings > available savings: Prioritize the goals and adjust the deadlines, targets, or contributions.
This simple comparison can prevent a common problem: creating too many savings goals without checking whether your income can actually support them.
In the next step, we will look at how to divide your available money between multiple savings goals when you cannot fully fund every goal at the same time.
Step 6: How to Divide Money Between Multiple Savings Goals
Knowing how much you need to save each month is only half the job. When you have several financial goals, you also need to decide how to divide your available savings between them.
You do not have to give every goal the same amount. The right approach depends on each goal’s priority, deadline, target amount, and how much you can realistically save after your regular expenses.
The aim is to create a savings plan that is realistic enough to follow every month while still moving your most important financial goals forward.
First, Know How Much You Can Save Each Month
Before deciding how much goes into each goal, calculate your available monthly savings.
For example, if your monthly income is $2,500, essential expenses are $1,700, and other required payments and regular spending total $400, you may have around $400 available for savings.
You can use our Budget Calculator to organize your income and expenses and get a clearer picture of how much you may be able to save each month.
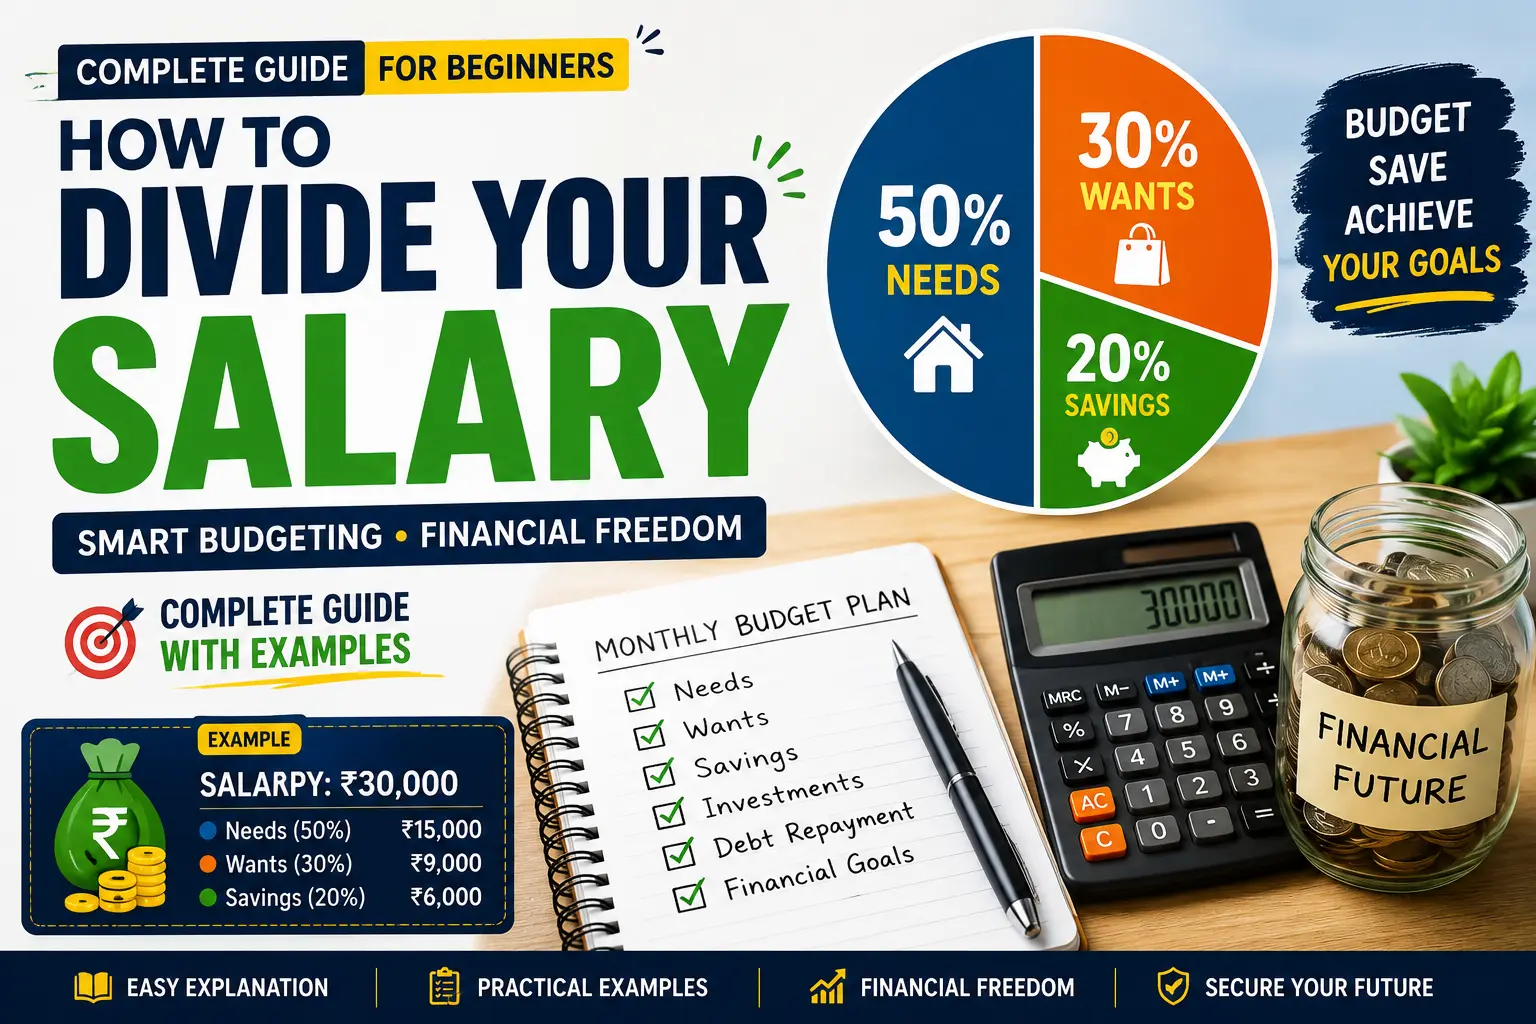
If you want a broader approach to dividing your income between spending, savings, and financial priorities, you can also read our guide on how to divide your salary for beginners.
Method 1: Equal Contribution for Multiple Savings Goals
The simplest approach is to divide your available savings equally between your goals.
For example, if you can save $300 per month and have three goals, you could contribute:
Goal 1 — $100 per month
Goal 2 — $100 per month
Goal 3 — $100 per month
This method is easy to understand and can work well when the goals have similar importance and similar deadlines.
However, equal contributions are not always the best option. If one goal has a much earlier deadline or greater financial importance, it may need a larger share of your monthly savings.
Method 2: Priority-Based Savings
With a priority-based savings plan, you give more of your available money to goals that are more important and reduce contributions to goals that can wait.
A simple order could be:
Financial safety
Essential upcoming expenses
Important planned goals
Optional goals
For example, if you are building an emergency fund while also saving for a vacation, you may decide that the emergency fund deserves a larger contribution because it provides greater financial protection.
This method can be especially useful when your monthly savings are limited and you cannot fully fund every goal at the same time.
Method 3: Deadline-Based Savings
Another practical method is to divide your savings according to how soon each goal needs to be funded.
Suppose you have the following goals:
Goal
Amount Remaining
Time Remaining
Priority
Annual bill
$600
4 months
High
Laptop
$1,000
10 months
Medium
Vacation
$1,200
12 months
Low
The annual bill has the closest deadline, so it may need more immediate attention. The laptop and vacation goals have more time, which gives you greater flexibility with their contributions.
This method is particularly useful for short-term and medium-term savings goals where missing a deadline could create a financial problem.
Which Savings Method Should You Choose?
There is no single method that works for every person or every savings goal. You can choose one method or combine several.
Method
Best For
Main Advantage
Equal contribution
Goals with similar importance
Simple and easy to maintain
Priority-based
Limited monthly savings
Focuses money on important goals
Deadline-based
Goals with different due dates
Helps prevent missed deadlines
For example, you could use a priority-based approach for your emergency fund and essential expenses, then divide whatever remains between flexible goals.
Example: Dividing $500 Between Multiple Savings Goals
Suppose you have $500 available for savings each month and four goals:
Goal
Priority
Monthly Contribution
Emergency fund
High
$200
Annual expenses
High
$150
Laptop
Medium
$100
Vacation
Low
$50
Total
$500
This is only an illustrative example, not a universal rule. Your own allocation should be based on your income, expenses, current savings, deadlines, and priorities.
The important idea is that you do not need to divide your money equally just because you have multiple goals.
Match Your Savings Allocation With Your Financial Plan
Your savings goals should not exist separately from the rest of your budget. They should fit into your overall financial plan.
Consider:
Your monthly income
Essential living expenses
Existing debt or required payments
Emergency savings
Upcoming annual expenses
Short-term financial goals
Longer-term goals
Our guide to financial planning for beginners explains how different money priorities can be organized into a broader financial plan.
This is completely normal. Having several savings goals does not mean you have to make progress on all of them at the same speed.
If your required monthly contributions are higher than your available savings, you can:
Focus on the highest-priority goal first.
Give more time to a flexible goal.
Reduce the target amount if appropriate.
Temporarily pause a lower-priority goal.
Redirect money to another goal after completing one target.
Increase contributions later when your financial situation improves.
A realistic savings plan is better than a complicated plan that consistently leaves you short of money.
Review and Rebalance Your Savings Goals
Your savings allocation does not need to remain unchanged throughout the year.
Review your plan at least once a month and consider whether:
Your income has changed.
Your regular expenses have increased or decreased.
A deadline is getting closer.
You have already reached one of your targets.
A new essential expense has appeared.
One goal has become more or less important.
For example, once you finish saving for an annual expense, you can redirect that monthly contribution toward your next priority instead of leaving the money unassigned.
A Simple Rule for Dividing Your Savings
If you are unsure where your money should go, ask yourself three questions every month:
What is most important right now?
Which goal has the nearest deadline?
How much can I realistically save this month?
Your answers can help you decide how to divide money between multiple savings goals without making your budget unnecessarily complicated.
The goal is not to save the same amount for everything. The goal is to give your available money a clear purpose while keeping your most important financial goals on track.
How many savings goals should I have at one time?
There is no fixed number of savings goals you should have. Start with the goals that are most important and realistic for your current income. Too many goals can make it harder to stay consistent, so focus on your priorities first.
Should I save for multiple goals at the same time?
Yes. If your budget allows, you can save for several goals at the same time. Give more money to urgent or essential goals and smaller amounts to flexible goals.
What should I do if I cannot save enough for all my goals?
Prioritize your most important goals instead of trying to fund everything equally. You can reduce optional targets, extend deadlines, or increase your monthly savings later when your income improves.
How often should I review my savings goals?
Review your savings plan at least once a month. Check your progress, remaining amount, deadlines, and monthly contributions. Adjust the plan whenever your income, expenses, or priorities change
Final Thoughts: How to Organize Multiple Savings Goals
Managing multiple savings goals becomes much easier when every goal has a clear target, deadline, and priority. Instead of trying to save for everything equally, focus your money on what matters most and adjust your plan as your situation changes.
Start small, stay consistent, and review your progress each month. A simple plan you can follow is more valuable than a complicated plan you cannot maintain.
Hi, I’m Asif Khan, the voice behind paisakmao.de. For the past two years, I’ve been blogging about financial education, income skills, and mindset development for students and young minds. My mission is to empower every youth with financial literacy and practical money-making skills at an early age. Through paisakmao.de, I share actionable guides for students to start earning early, money wisdom that schools don’t teach, and mindset lessons from successful people and modern psychology. Whether you’re a teenager looking to earn your first income or a student exploring side hustles, you’re in the right place. Financial freedom begins with the right mindset and the right knowledge. Let’s grow, earn, and evolve together — welcome to the movement!
Managing money can feel difficult when small purchases keep adding up throughout the month. The cash stuffing method offers a simple way to give each spending category a clear limit and make your budget easier to see and follow.Instead of keeping your entire spending budget in one place, you divide cash into separate categories such as groceries, transportation, eating out, or personal spending. When an envelope gets low, you know exactly how much is left for that category.In this guide, you’ll learn how cash stuffing works, how to set up your first envelopes, how much to allocate to each category, and how to adapt the method for different budgets and payment habits.
What Is the Cash Stuffing Method for Beginners?
The cash stuffing method for beginners is a simple way to organize your spending by separating money into different categories. Instead of keeping all your spending money together, you decide how much you want to use for groceries, transportation, eating out, entertainment, or other everyday expenses.
The basic idea is simple: give your money a purpose before you spend it.
For example, if you have $500 available for flexible spending, you might divide it between several categories instead of treating the entire $500 as available for anything. In India, the same idea could be applied to ₹40,000 of monthly income or spending money. The actual amounts depend on your income, bills, and personal circumstances.
How Does Cash Stuffing Work
Traditional cash stuffing uses physical envelopes. Each envelope represents a spending category, and you place the amount you’ve budgeted for that category inside it.
A simple setup might include:
Groceries
Transportation
Eating out
Entertainment
Personal spending
Miscellaneous
When you spend money, you take it from the relevant category. If your grocery envelope has $150 left, for example, you know that $150 is what remains for groceries under that budget.
The system is closely related to the cash envelope system and traditional envelope budgeting. The Consumer Financial Protection Bureau (CFPB) has also discussed the envelope approach as a way of separating money for different spending categories.
Why Do People Use Cash Stuffing?
The main attraction is visibility.
When your spending money is separated into categories, it can be easier to notice how much you have left before making another purchase.
That doesn’t mean cash stuffing will automatically stop overspending. It simply gives you a clear spending boundary to work with.
For someone who regularly wonders, “Where did my money go this month?”, seeing separate amounts for different categories can make budgeting feel more concrete.
Does Cash Stuffing Mean Using Only Physical Cash?
Not necessarily.
Physical envelopes are the traditional version, but the underlying idea can also work with digital budgeting.
Someone in the US might use cash envelopes for groceries and entertainment while keeping rent and online bills in a bank account.
A UK reader might use digital “pots” for some categories.
In India, where UPI and digital payments are widely used, someone may prefer a hybrid approach—keeping some categories in cash while tracking other spending digitally.
The important principle is separating money by purpose, not carrying every expense in your wallet.
Cash Stuffing at a Glance
Element
What it means
Income
Money available for your budget
Categories
Different types of spending
Envelopes
Separate places for each category
Spending limit
Amount assigned to a category
Tracking
Recording what you spend
Review
Checking what worked and what needs adjusting
This is only the basic idea. The next step is understanding how to actually set up a cash stuffing budget, choose the right categories, and decide how much money should go into each one.
How Much Money Should You Put in Each Cash Stuffing Envelope?
Once you know your income and regular expenses, the next step is deciding how much money to put into each envelope.
There is no single amount that works for everyone. Your cash stuffing budget should reflect your income, essential expenses, family situation, location, and normal spending habits.
A good starting point is to look at what you actually spend rather than copying someone else’s envelope amounts.
Start With Your Real Spending
Before setting your limits, look at your recent bank statements, receipts, or budgeting records.
You might notice that groceries regularly cost more than you expected, while entertainment spending is much smaller.
That information is useful.
Try to identify the categories where your spending is both variable and controllable.
Common examples include:
Groceries
Eating out
Transportation
Entertainment
Clothing
Personal spending
Household purchases
Miscellaneous expenses
If you don’t know your spending patterns yet, track them for a few weeks before creating strict limits.
This makes the cash envelope system more realistic and easier to maintain.
Separate Fixed Bills From Flexible Spending
Cash stuffing doesn’t require you to put every expense into a physical envelope.
Some expenses are already predictable or automatically paid from your bank account.
For example:
Rent or mortgage
Insurance
Loan payments
Subscriptions
Internet and phone bills
Other recurring payments
Cash envelopes are usually more useful for spending that can change from week to week.
The goal is not to make your finances complicated. It’s to create a clear boundary around the spending you can control.
A Simple Cash Stuffing Example
Imagine someone in the US takes home $2,500 a month.
After accounting for essential bills, savings, and other financial commitments, they have $600 available for selected flexible expenses.
They might start with:
Category
Example Amount
Groceries
$300
Transportation
$100
Eating out
$75
Personal spending
$75
Miscellaneous
$50
Total
$600
These numbers are only an example. They are not recommended spending limits.
A person in the UK might work with £500, while someone in India might have ₹10,000 available for similar variable categories.
The currency and cost of living change, but the basic idea remains the same: divide the money according to your own spending needs.
Don’t Set Unrealistic Envelope Limits
One common beginner mistake is trying to make the budget look perfect on paper.
Suppose you normally spend around $350 on groceries but decide to put only $200 into your grocery envelope because you want to save more.
If you run out of money halfway through the month, the problem may not be the cash stuffing method. Your original limit may simply have been unrealistic.
A better approach is to start with your actual spending and make gradual adjustments
What If Your Income Changes?
The cash stuffing method for beginners can also be adapted for irregular income.
If you receive money weekly, work freelance, or have changing monthly income, you don’t necessarily need to decide your entire month’s envelope amounts at once.
Instead, you can allocate money when you actually receive it.
This helps prevent a common mistake: filling your envelopes first and discovering later that you don’t have enough money for an important bill.
Start Small
You don’t need ten or twenty envelopes on your first attempt.
Start with three to five categories that are genuinely useful for your spending habits.
For example:
Groceries
Transportation
Eating out
Personal spending
Miscellaneous
After a month, review what happened.
If one envelope consistently has money left over, you can reconsider its limit.
If another runs out too quickly, look at your actual spending before simply adding more money.
Your first cash stuffing budget doesn’t need to be perfect. It needs to be realistic enough to help you understand and control your spending.
What Categories Should You Use for Cash Stuffing?
You don’t need a separate envelope for every expense. Start with the spending categories where you are most likely to overspend.
Best Cash Stuffing Categories for Beginners
Common categories include:
Groceries — food and household shopping
Transportation — fuel, bus, train, or local travel
Eating Out — restaurants, snacks, and coffee
Personal Spending — small personal purchases
Entertainment — movies, games, and hobbies
Gifts — birthdays, festivals, and special occasions
Category
Example
Groceries
$250 / £200 / ₹8,000
Transportation
$100 / £80 / ₹3,000
Eating Out
$75 / £60 / ₹2,500
Personal
$75 / £60 / ₹2,500
These amounts are only examples. Your actual budget should depend on your income and regular spending.
Don’t Put Every Expense in an Envelope
Fixed expenses such as rent, mortgage payments, electricity bills, and subscriptions usually don’t need physical cash envelopes. You can continue paying them digitally or through your bank account.
For irregular expenses like gifts, clothing, or annual costs, a sinking fund can be useful. MoneyHelper explains sinking funds as a way to prepare for expenses that don’t happen every month.
If you are unsure how much you can actually afford for each category, first use the Budget Calculator.
Start small: 3–5 useful categories are usually easier to manage than 15–20 envelopes. Once the system becomes a habit, you can add more categories if needed.
How to Start Cash Stuffing: A Step-by-Step Setup
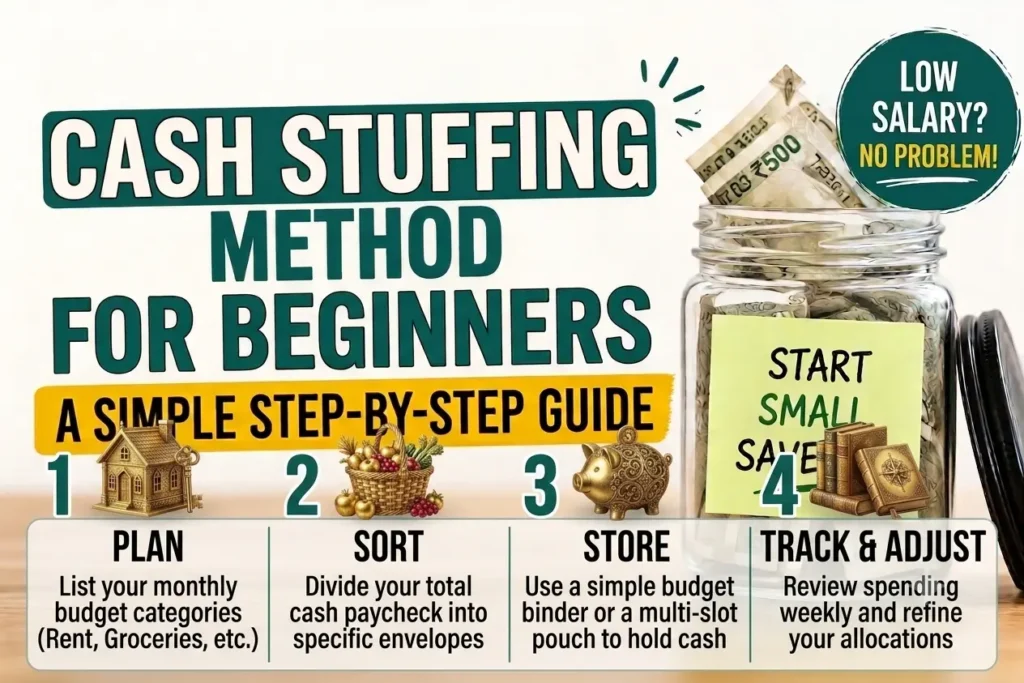
Starting the cash stuffing method is easier when you follow a simple routine instead of trying to change all your spending habits at once. The basic idea is to decide your limits, separate the money into categories, and track what you spend.
1. Choose Your Budget Period
First, decide how often you want to organize your envelopes.
You can use a:
Weekly system if you prefer tighter spending control
Biweekly system if you get paid every two weeks
Monthly system if you receive a monthly salary
Your choice should match your income schedule and spending pattern.
If your income is very tight and covering basic expenses is already difficult, see our paycheck-to-paycheck budgeting guide for a more focused approach.
The goal is not to follow a perfect envelope system. The goal is to create a spending system that you can realistically follow every pay period.
What Happens When a Cash Stuffing Envelope Runs Out?
One of the biggest questions beginners have is: What should you do when an envelope reaches $0 before the end of the month?
It doesn’t automatically mean your budget has failed. It may simply mean that your spending limit needs to be reviewed.
Check Before Moving Money
First, ask whether the expense is actually necessary.
For example, if your entertainment envelope is empty, you may decide to wait until the next budget period. But if your grocery budget is short because food prices were higher than expected, the situation may be different.
A simple rule is:
Needs first, wants second.
Situation
What You Can Do
Non-essential spending
Wait until the next period
Essential expense
Consider moving money from a lower-priority category
Unexpected expense
Use an appropriate emergency/savings fund
Budget repeatedly runs short
Recalculate your category limits
Can You Move Money Between Envelopes?
Yes. Your budget doesn’t have to be completely rigid.
Suppose your Eating Out envelope has $40 left, while your Groceries envelope needs another $25. If groceries are the priority, you could move $25 from Eating Out to Groceries.
The important part is to record the transfer so you know where your money went.
What If This Happens Every Month?
If the same envelope runs out repeatedly, don’t simply keep adding money to it.
Look at your actual spending and adjust the budget.
For example, if you regularly spend $300 on groceries but your budget allows only $250, your original limit may not reflect your real situation.
Our salary division guide can help you review how your income is being allocated across different priorities.
What About Leftover Money?
If an envelope still has money at the end of the period, you have several options:
Carry it into the next period
Move it toward a planned expense
Add it to savings
Keep a small buffer for future spending
For irregular expenses, a sinking-fund approach can make budgeting easier. MoneyHelper’s sinking-fund guidance explains how setting money aside over time can help prepare for expenses that don’t happen every month.
The goal of cash stuffing isn’t to punish yourself for spending. It’s to make your spending choices visible and intentional. If you’re already struggling to cover essential expenses, our paycheck-to-paycheck budgeting guide covers a more focused approach for tight budgets.
Cash Stuffing vs. Digital Budgeting: Which Is Better?
Cash stuffing works by making your spending limits visible through separate cash envelopes. Digital budgeting uses bank accounts, budgeting apps, spreadsheets, or digital savings pots to organize the same idea electronically.
Neither method is automatically better. The right choice depends on how you normally spend and how often you use cash.
Feature
Cash Stuffing
Digital Budgeting
Spending visibility
Very high
High
Physical cash needed
Yes
No
Card/UPI payments
Limited unless hybrid
Easy
Tracking
Manual
Often automatic
Best for
Controlling flexible spending
Digital-first spending
When Cash Stuffing Can Work Well
Physical cash can make a spending limit feel more concrete. Once the envelope is nearly empty, you can immediately see that you’re approaching your limit.
This can be particularly useful for categories such as groceries, eating out, entertainment, or personal spending.
When Digital Budgeting Makes More Sense
Cash isn’t practical for every expense. Rent, subscriptions, online shopping, bills, and many everyday transactions are normally paid digitally.
That’s why a hybrid cash stuffing system can be useful. You might use cash for flexible spending while keeping fixed bills and other payments in your bank account.
For readers in the UK, MoneyHelper’s jam jar approach shows how separating money into different pots can also be done digitally.
In India, where digital payments are widely used, you can combine cash envelopes with separate bank-account or savings categories rather than forcing every expense into physical cash.
Which Should Beginners Choose?
Start with the method you are most likely to follow consistently.
If you often overspend on small purchases, physical envelopes may give you stronger spending awareness. If you rarely use cash, a digital or hybrid approach may be more practical.
The goal isn’t to use cash simply because it’s called “cash stuffing.” The goal is to give every spending category a clear limit and make your money easier to manage.
Common Cash Stuffing Mistakes Beginners Should Avoid
Cash stuffing looks simple, but a few common mistakes can make the system difficult to maintain. The good news is that most of them are easy to fix.
1. Creating Too Many Envelopes
You don’t need an envelope for every small expense.
Starting with 15–20 categories can make your budget feel like another chore. Begin with 3–5 important spending categories and add more only when necessary.
2. Setting Unrealistic Limits
A budget shouldn’t be based on what you wish you spent. It should reflect your actual situation.
If you normally spend $300 on groceries but set a $150 limit without a realistic plan to reduce costs, the envelope may run out quickly.
Review your real spending before changing your limits. Our Budget Calculator can help you organize your numbers.
3. Trying to Use Cash for Everything
Not every expense needs a physical envelope.
Rent, subscriptions, online payments, and many bills can remain digital. A hybrid budgeting system can be more practical than forcing every payment into cash.
4. Forgetting to Track Spending
Cash can disappear quickly when you make several small purchases.
Write down each transaction or keep a simple note on your phone. This makes it easier to understand where your money is actually going.
5. Taking Money From Other Envelopes Without Recording It
Moving money between categories is sometimes reasonable. But repeatedly doing it without tracking the changes can hide the real problem.
If you keep taking money from groceries to cover entertainment, for example, your category limits may need to be reviewed.
6. Ignoring Irregular Expenses
Some expenses don’t appear every month but still need planning.
Gifts, annual subscriptions, clothing, repairs, and seasonal expenses can be handled through a sinking fund rather than pretending they don’t exist.
Don’t try to make your cash stuffing system perfect. Make it sustainable.
Start with a few categories, use realistic limits, track your spending, and adjust the system when your circumstances change. That’s what turns cash stuffing from a budgeting experiment into a habit you can actually maintain.
Is cash stuffing good for beginners?
Yes. Cash stuffing can be beginner-friendly because it gives each spending category a clear limit and makes it easier to see how much money is available.
How much money should I put in cash stuffing envelopes?
Use an amount that fits your actual budget. After essential expenses, divide your flexible spending money between categories such as groceries, transportation, personal spending, and entertainment.
What happens if I run out of money in an envelope?
Check whether the expense is essential. If it is, you can move money from a lower-priority category and record the transfer. For non-essential spending, waiting until the next budget period may be the better option.
Can I do cash stuffing without using physical cash?
Yes. You can use a digital or hybrid system with bank accounts, savings pots, spreadsheets, or budgeting apps. The principle remains the same: separate your money into spending categories with clear limits
Conclusion
The cash stuffing method can be a simple way to make everyday spending easier to understand and control. Instead of treating your entire budget as one amount, you give different spending categories clear limits.
You don’t need to start with a complicated system. Choose a few categories, set realistic amounts, track your spending, and adjust your envelopes when your real spending doesn’t match your original plan.
And remember, cash stuffing doesn’t have to mean using physical cash for everything. A digital or hybrid approach can work too, especially for bills and online payments.
The best budgeting system is the one you can understand, follow, and maintain consistently. Start small, learn from each budget period, and improve your system over time.
Hi, I’m Asif Khan, the voice behind paisakmao.de. For the past two years, I’ve been blogging about financial education, income skills, and mindset development for students and young minds. My mission is to empower every youth with financial literacy and practical money-making skills at an early age. Through paisakmao.de, I share actionable guides for students to start earning early, money wisdom that schools don’t teach, and mindset lessons from successful people and modern psychology. Whether you’re a teenager looking to earn your first income or a student exploring side hustles, you’re in the right place. Financial freedom begins with the right mindset and the right knowledge. Let’s grow, earn, and evolve together — welcome to the movement!
If your paycheck runs out before your next payday, budgeting can feel almost impossible—especially when your income is already low. The problem may not be unnecessary spending; your essential expenses may simply leave too little room.This guide explains how to budget when living paycheck to paycheck on a low income, find where your money is actually going, and create a practical plan to make each paycheck last longer.
Find Out Why Your Paycheck Runs Out Before Payday
Before changing your budget, first find out why your money is running out. If you don’t know where the shortage is coming from, cutting random expenses may not solve the problem.
Start with your take-home income for one pay period. Then list the expenses that must be paid before your next paycheck, such as housing, food, transportation, utilities, and required payments.
For example, if you receive ₹10,000 and need ₹4,000 for housing, ₹2,000 for food, ₹1,000 for transportation, and ₹1,500 for essential bills, you have ₹1,500 left.
Now ask yourself: Can that ₹1,500 realistically cover everything until your next payday?
If yes, the problem may be how the remaining money is being spent or when certain expenses occur. If no, your essential costs may already be leaving too little income available.
The same calculation works whether your paycheck is ₹10,000, $1,000, or £900. The amounts will differ, but the question stays the same: how much income is left after the expenses you cannot avoid?
This simple check helps you identify whether your main problem is spending, payment timing, or an income that is not enough to cover essential costs. Once you know the actual problem, you can build a budget around it instead of guessing where your money is going.
Calculate Your Minimum Amount Needed Until the Next Paycheck
Once you know why your paycheck is disappearing, calculate the minimum amount you actually need before the next payday. This gives you a clear spending limit instead of treating your whole paycheck as available money.
Start with the expenses that cannot reasonably be postponed until later. For example, if your next paycheck is 10 days away, include the food, transportation, bills, and other essential payments you need during those 10 days.
Suppose you receive ₹10,000 and your next paycheck is 10 days away:
Essential food: ₹2,000
Transportation: ₹1,000
Upcoming bill: ₹2,500
Other required expense: ₹1,000
Your minimum amount needed is ₹6,500.
That means the remaining ₹3,500 should not automatically be treated as spending money. It can become a buffer, cover an upcoming expense, or help reduce the pressure on your next paycheck.
The same method works with $1,000 or £900. The numbers will change depending on your location and expenses, but the principle remains the same: separate money you must use from money you can safely leave untouched.
This small calculation can change the way you look at each paycheck. Instead of asking, “How much money do I have?” you start asking, “How much of this money is actually available?”
Build a Paycheck Plan Around Your Essential Expenses
When you are living paycheck to paycheck, a budget should do more than divide your income into categories. It should help you control the timing of your money so that an expense due next week does not compete with today’s spending.
After calculating what you need until your next paycheck, give each important amount a specific job. This creates a simple cash-flow plan without forcing every household into the same percentage-based budget.
Reserve Money for Bills Before They Are Due
Start with bills that will need to be paid before your next paycheck arrives. These might include rent, utilities, phone bills, transportation payments, or other unavoidable commitments.
For example, suppose you receive ₹10,000 today and ₹3,500 of bills are due before your next payday. That ₹3,500 should be treated as committed money even though it is still sitting in your account.
The same idea applies to a $1,000 or £900 paycheck. The currency changes, but the problem is the same: money can look available simply because the bill has not arrived yet.
Once upcoming bills are protected, calculate what you need for essential day-to-day spending until payday.
Imagine you have 10 days remaining and expect to spend about ₹200 per day on necessary food and transportation:
₹200 × 10 days = ₹2,000
Instead of treating your whole account balance as spendable, ₹2,000 becomes the working amount for those essentials.
You can use the same calculation with dollars or pounds. For example, if your essential daily spending is $12 and you have 8 days until payday, your basic requirement would be $96.
This creates a useful distinction: your account balance shows what you have, while your spending limit shows what you can safely use.
Leave Room for Small Unplanned Expenses
A budget that leaves no flexibility can be difficult to follow. A small unexpected expense can force you to take money from a bill or another essential category.
After covering your required expenses, keep a modest flexible amount that fits your situation.
₹500 for a ₹10,000 example paycheck
$30 for a $1,000 example paycheck
£25 for a £900 example paycheck
These numbers are examples, not recommended percentages. Your flexible amount should depend on your actual income and expenses.
The important rule is simple: once this amount is used, do not automatically increase it by taking money reserved for essential expenses.
Give the Remaining Money a Specific Job
After protecting bills, essential daily spending, and a small flexible amount, look at what remains. Do not automatically label it as “extra money.” Decide what that money is supposed to do.
₹10,000 Paycheck
Amount
Purpose
Upcoming bills
₹3,500
Protect until due date
Food + transportation
₹2,000
10-day essentials
Flexible spending
₹500
Small unexpected needs
Remaining amount
₹4,000
Protect for the next financial need
The ₹4,000 remaining in this example should not automatically become shopping or entertainment money. It could help cover an upcoming expense, provide breathing room for the next pay period, or be directed toward another priority once your immediate needs are secure.
This is similar to the basic idea behind MoneyHelper’s jam-jar budgeting approach, where money is separated into different pots for different purposes so that spending money is less likely to interfere with money reserved for bills.
When Money Is Unassigned
When Money Has a Job
The full balance feels available
Only the appropriate amount feels available
Upcoming bills are easy to forget
Upcoming bills are protected
Daily spending can consume future money
Daily spending has a defined limit
Payday feels like a reset
Each paycheck is planned around the next one
If you want to understand broader salary allocation, you can also read your existing guide to dividing your salary. That article covers percentage-based allocation and salary budgeting; this section focuses specifically on protecting cash between paychecks, so the two articles serve different purposes.
The goal is not to make every paycheck fit a perfect formula. It is to make sure money needed for the next few days and weeks is protected before you decide what you can actually spend.
Create a Survival Budget for the Lowest-Income Weeks
When you live paycheck to paycheck, your budget cannot depend on every paycheck being the same. A week with fewer working hours, lower overtime, or an unexpected expense can leave you with much less money than usual.
Instead of rebuilding your entire budget whenever income falls, create a survival budget based on the minimum amount you need to keep your essential expenses covered.
Find Your Bare-Minimum Monthly Cost
Start by identifying the expenses you cannot reasonably stop or postpone when your income is lower.
Housing and essential household costs
Basic food
Necessary transportation
Essential utilities and communication
Required debt or other unavoidable payments
For example, if your normal monthly income is ₹20,000 but your essential expenses are ₹13,000, then ₹13,000 is much more important for your survival budget than your usual spending level.
A person earning $2,500 or £2,000 would use the same method: first identify the minimum cost of keeping essential needs covered, rather than copying someone else’s budget percentages.
Separate Fixed Costs From Expenses You Can Adjust
Not every expense has the same level of flexibility. When income falls, knowing which costs can actually be reduced is more useful than simply cutting everything by the same percentage.
Type of Expense
Usually Harder to Change Quickly
Often More Flexible
Housing
Rent or essential housing payment
Some optional housing-related spending
Food
Basic groceries
Takeaways and non-essential purchases
Transportation
Necessary travel to work
Optional trips
Subscriptions
Essential communication services
Entertainment subscriptions
This gives you a priority order. You are not trying to make every category smaller. You are protecting the expenses that keep your household functioning and adjusting the areas where you have genuine control.
What to Cut First When Your Paycheck Is Smaller
When a paycheck comes in lower than expected, make the adjustment based on priority rather than emotion.
For example, suppose your usual income is ₹20,000 but this month you receive only ₹15,000. If essential expenses remain around ₹12,000, you have only ₹3,000 available for everything else.
Monthly Situation
Income
Essential Costs
Amount Left
Normal month
₹20,000
₹12,000
₹8,000
Lower-income month
₹15,000
₹12,000
₹3,000
The lesson is not to spend the extra ₹8,000 simply because it was available in the normal month. Your flexible spending has to respond when your income changes.
The same principle applies if income falls from $2,500 to $2,000 or from £2,000 to £1,600. The actual figures differ by country and household, but the budgeting decision is the same: protect essential costs first, then reduce flexible spending.
What to Do When the Budget Still Doesn’t Balance
Sometimes cutting flexible spending is not enough. If your essential expenses are already higher than your income, the problem is no longer simply about better budgeting.
At that point, look at the gap itself.
Check whether any payment can be moved to a more suitable date.
Look for temporary reductions in non-essential commitments.
Review recurring expenses that are no longer necessary.
Consider realistic ways to increase income if the shortfall continues.
Contact the relevant provider early if you are struggling with an important payment rather than waiting until it becomes overdue.
Do not treat every low-income month as a failure. A temporary income drop requires a different spending plan. If the gap continues for several months, however, it is a signal that the underlying income-versus-expense problem needs to be addresse provide practical information for managing income and expenses. UK readers can also use MoneyHelper’s budgeting guidance for country-specific budgeting information.
If you already have a broader article about dividing your salary, use it as a supporting internal link for the normal-income budgeting side. This section has a different purpose: it explains how to adapt when your income falls below normal.
A survival budget is not meant to be your permanent lifestyle. It is a practical fallback system that helps you protect essential expenses during a low-income period without pretending that every month will look the same.
Build a Small Buffer Between Your Paychecks
When you are living paycheck to paycheck, even a small unexpected expense can create a problem because most of your income is already committed before the next payday arrives.
The solution is not to suddenly save a large amount. A more realistic approach is to create a small buffer between paychecks and increase it gradually as your cash flow improves.
Why Every Paycheck Should Not Be Fully Spent
If your entire paycheck is allocated before the next one arrives, there is no room for a small surprise expense. A transport problem, higher grocery bill, or unexpected household purchase can force you to reduce something else or depend on borrowing.
For example, if you receive ₹20,000 and normally spend almost all of it before the next payday, try leaving a small amount untouched instead of treating the full balance as available spending money.
The same idea applies to someone earning $2,000 or £1,600. The amount of the buffer will depend on local costs and income, but the purpose is the same: create a little space between what you earn and what you immediately spend.
Start With a Buffer You Can Actually Keep
Your first target does not need to be a large emergency fund. If money is already tight, setting an unrealistic target can make the system impossible to maintain.
Start with an amount that would make one small unexpected expense easier to handle.
Stage
Illustrative Buffer
Main Purpose
Starting point
₹300 / $5 / £5
Creates the first small cushion
Small cushion
₹1,000 / $25 / £20
Handles minor unexpected costs
Several days of essentials
Based on your actual costs
Provides more breathing room
Larger buffer
Based on your income and expenses
Reduces pressure between paychecks
These are illustrative examples, not recommended savings targets for every country or household. Your starting point should match what you can realistically leave untouched.
Turn Leftover Money Into Next-Paycheck Protection
One useful habit is to stop treating every leftover amount as permission to spend more.
Suppose you planned to spend ₹2,000 during a week but actually spent ₹1,750. Instead of automatically using the remaining ₹250, you can leave it available for the next pay period.
Over time, several small amounts can create a useful cushion without requiring one large contribution from a low income.
If you want a separate collection of practical saving strategies, you can read how to save money fast in 30 days. That article covers broader saving techniques; this section is specifically about creating protection between paychecks.
How a Buffer Changes Your Next Paycheck
Situation
Without a Buffer
With a Small Buffer
Small unexpected expense
May reduce money available for essentials
Can be covered from the cushion
Lower-than-usual paycheck
Immediate pressure on spending
Previous buffer provides some breathing room
Money left at the end of the week
May be spent automatically
Can remain available for the next period
Next payday
Starts with little or no flexibility
Starts with some money already protected
The goal is not to make your bank balance look bigger. The goal is to make your next payday less fragile.
Increase the Buffer Gradually
Once your first small cushion becomes easy to maintain, increase it only when your budget can support the change.
Keep the first small amount untouched.
Add a little more when you genuinely have money left over.
Use part of the buffer only for situations that actually need it.
Rebuild the buffer after using it.
Increase the target when your income becomes more stable.
This creates a simple cycle:
Paycheck → essential spending → controlled flexible spending → small amount protected → next paycheck starts with a cushion.
If you are still struggling to keep any money aside despite earning a reasonable income, the problem may be different from simply needing a larger buffer. In that situation, why you can’t save money despite earning a good salary is a more relevant supporting guide.
When a Buffer Is Not Enough
A small buffer can help with timing problems and minor unexpected expenses, but it cannot solve a permanent gap between income and essential costs.
If your essential expenses are consistently higher than your reliable income, calculate the shortfall instead of simply trying to save more.
Essential expenses − reliable income = monthly shortfall
For example, if essential expenses are ₹16,000 and reliable income is ₹14,000, there is a ₹2,000 monthly gap. A buffer can temporarily reduce pressure, but the underlying gap still needs to be addressed.
For broader personal-finance fundamentals, you can also use this beginner’s personal finance guide to review the wider system without repeating those topics here.
A buffer is not about becoming wealthy overnight. It is about creating a small gap between your income and your immediate spending so that one minor problem does not automatically become a next-paycheck problem.
Start small, protect the amount, rebuild it when you use it, and increase it only when your actual budget allows.
Handle a Shortfall Before It Becomes a Bigger Problem
Sometimes a low-income budget does not fail because of unnecessary spending. The real problem can be that your essential expenses are already close to, or higher than, your reliable income.
When that happens, the first step is not to cut random expenses. Find the exact size of the gap and determine whether it is temporary or happening repeatedly.
Calculate Your Exact Monthly Shortfall
Start with your reliable take-home income and subtract only the expenses you genuinely need to keep covered.
Reliable income − essential expenses = money available for everything else
For example, if your reliable income is ₹15,000 and essential expenses are ₹13,500, you have ₹1,500 available for flexible spending and other priorities.
But if essential expenses are ₹16,000, you already have a ₹1,000 shortfall before discretionary spending begins.
Situation
Income
Essential Expenses
Result
Expenses fit income
₹15,000
₹13,500
₹1,500 remaining
Small shortfall
₹15,000
₹16,000
₹1,000 gap
Larger shortfall
₹15,000
₹18,000
₹3,000 gap
The same calculation works for other currencies. Someone earning $2,000 with $2,200 of essential expenses has a $200 gap. Someone earning £1,600 with £1,750 of essential expenses has a £150 gap.
Separate a Temporary Gap From a Recurring Problem
Not every shortfall requires the same response.
Temporary Shortfall
Recurring Shortfall
Income was unusually low for one period
Income is regularly below essential costs
An unusual expense caused the problem
Basic monthly costs are structurally too high
Normal income may solve it next payday
The underlying income-expense gap needs attention
Small adjustments may be enough
Both expenses and income may need to change
This distinction matters because repeatedly using a credit card, borrowing money, or taking from your next paycheck can hide a recurring shortfall instead of solving it.
Decide What Can Be Delayed or Reduced
If the gap is temporary, review your expenses according to priority rather than cutting everything equally.
Reduce: flexible food spending, entertainment, shopping, and other non-essential categories.
Delay: purchases or goals that are useful but not urgent.
Review: recurring subscriptions and commitments that may no longer provide enough value.
The purpose is to create enough breathing room to get through the weaker income period without sacrificing expenses that keep your basic needs covered.
If the issue is connected to inconsistent income rather than a single low paycheck, your guide on budgeting with an irregular income is the more relevant supporting resource. It covers a different situation, so this section does not need to repeat that system.
When Cutting Expenses Is No Longer Enough
There is a point where reducing discretionary spending cannot solve the problem. If your essential expenses are already higher than your reliable income, the budget needs to address the gap itself.
For example, if your essential expenses are ₹18,000 and your reliable income is ₹15,000, cutting ₹500 of entertainment does not remove the entire ₹3,000 shortfall.
At that stage, consider both sides of the equation:
Can an essential cost be reduced or changed?
Can a payment date be adjusted where appropriate?
Is there a temporary expense that can be postponed?
Can reliable working hours or income be increased?
Is the shortfall temporary or likely to continue?
If debt payments are part of the problem, avoid treating new borrowing as income. A recurring gap financed by new debt can make future paychecks even harder to manage.
Know When Your Budget Needs a Structural Change
A budget is useful when it reflects reality. If your income repeatedly cannot cover your essential expenses, changing the spreadsheet without changing the underlying situation will not fix the problem.
Track the shortfall for several pay periods and look for a pattern. If the same gap keeps appearing, you have identified a structural problem rather than a one-time budgeting mistake.
For broader financial planning, you can refer to your financial planning guide for beginners. Keep this article focused on the paycheck-to-paycheck problem instead of repeating the full financial-planning framework.
official guidance on managing income and expenses. UK readers can use MoneyHelper’s budgeting guidance for additional country-specific information.
The key is to identify the problem early. A one-time ₹1,000, $100, or £100 shortfall can be handled differently from a gap that appears every month. Once you know which situation you have, you can choose the appropriate next step instead of repeatedly starting over on payday.
Create a Simple Weekly System That Keeps You Ahead of Payday
A budget only works when you can follow it after the planning is finished. If you are living paycheck to paycheck, you do not need to check your finances every hour. A short weekly routine can be enough to see what has been spent, what is still available, and what needs attention before the next payday.
The goal of this system is simple: make your money decisions before your balance becomes a problem.
Check Your Available Money Once a Week
Choose one fixed day each week to check your bank balance and recent spending. Sunday can work well, but the best day is the one you can repeat consistently.
Do not look only at your total balance. Separate the money that is already committed from the money you can actually use during the next few days.
Check your current balance.
Check essential payments due before the next review.
Check what you spent during the previous week.
Check how much flexible money remains.
Move any genuine leftover amount into your protected buffer when appropriate.
This five-minute check can reveal a problem while it is still small instead of waiting until the final days before payday.
Set a Spending Limit for the Next Seven Days
Once you know what money is already committed, give yourself a realistic limit for the coming week.
For example, if you have ₹2,800 available for flexible spending and four weeks remain in your planning period, you might initially work with a limit of around ₹700 per week. Your actual number should come from your own expenses rather than a fixed budgeting rule.
A US reader might work with a $150 weekly limit, while a UK reader might use £100. The currency does not matter as much as giving the remaining money a clear time period.
Weekly Check
Question to Ask
Action
Balance
How much money is available?
Record the amount
Upcoming bills
What must be paid before next week?
Protect that money
Recent spending
Where did last week’s money go?
Identify unusual spending
Flexible money
How much can I safely spend?
Set the week’s limit
Buffer
Did any money genuinely remain?
Keep it protected when possible
Check Upcoming Bills Before You Spend
A weekly spending limit is not enough if a large payment is due in the same week.
Before using your available balance, look at the next few days and check whether rent, utilities, transportation, insurance, debt payments, or another essential expense is approaching.
The Consumer Financial Protection Bureau’s bill-calendar guidance recommends putting income and bill dates together so you can see when money comes in and when payments leave your account. That cash-flow view is especially useful when the timing of your income creates pressure before payday. 1
This is different from simply asking, “How much money is in my bank account?” The better question is, “How much of that balance is actually available after the money I already need to protect?”
Adjust the Next Week Instead of Giving Up on the Budget
Suppose you planned to spend ₹700 during the week but ended up spending ₹900. Do not treat the entire monthly budget as failed.
First, identify why the extra ₹200 was spent. Was it a necessary expense, a one-time purchase, or something you could have avoided?
If the expense was genuinely necessary, adjust the following week’s flexible spending if your overall cash flow allows it. If it was avoidable, use the information to prevent the same pattern from repeating.
What Happened
Better Response
Necessary expense was higher
Adjust the next week’s flexible amount
One-time unexpected cost
Use the buffer if appropriate and rebuild it later
Repeated unnecessary spending
Identify the category and reduce it
Essential costs exceed income
Recalculate the shortfall instead of cutting random expenses
This makes the budget a feedback system rather than a punishment system.
Use a Simple Payday-to-Payday Checklist
At the beginning of each pay period, run through the same short checklist:
☐ Confirm your actual take-home income.
☐ Protect bills due before the next paycheck.
☐ Set aside the amount needed for essential daily spending.
☐ Decide your flexible spending limit.
☐ Keep your existing buffer protected.
☐ Check your finances once during each week.
☐ Review what changed before the next payday.
If your income changes from one pay period to another, use the lower reliable income as the safer starting point rather than assuming your best paycheck will arrive every time.
For a broader system covering salary management across the month, your Day 1 to Day 30 salary management guide can support the reader after this article. This article has a narrower purpose: keeping a low-income paycheck under control between paydays. 2
Make the System Easier Every Payday
You do not need a complicated spreadsheet or a new financial rule every week. The system becomes useful when the same few decisions become automatic.
Each payday, protect essential money. Each week, check your actual spending. When income falls, reduce flexible spending before essential needs. When money remains, protect part of it instead of automatically spending it.
Over time, this changes the way you experience payday. Instead of starting every pay period wondering how long your money will last, you start with a clear picture of what is committed, what is available, and what needs to happen next.
That is the real purpose of a paycheck-to-paycheck budget: not perfection, but enough control to make the next payday less stressful than the last one.
Can you budget if you
Yes. When your income baseline is low, structural percentage allocations become even more critical to safeguard your primary needs and prevent cascading high-interest debt cycles.
What is the 70/20/10 rule for low income?
This alternate budgeting blueprint allocates 70% of total funds for essential living needs, 20% to clear debts or build savings, and exactly 10% for variable personal lifestyle choices.
How do I start an emergency fund on a tight budget
Begin by automating microscopic milestones. Setting aside just $5 or ₹500 immediately on Day 1 establishes consistent behavioral habits without fracturing your day-to-day liquidity.
What is the fastest way to break the paycheck cycle
The fastest way is shifting to physical cash tracking via the envelope system for variable costs and performing a immediate subscription audit to reclaim lost margins.
Hi, I’m Asif Khan, the voice behind paisakmao.de. For the past two years, I’ve been blogging about financial education, income skills, and mindset development for students and young minds. My mission is to empower every youth with financial literacy and practical money-making skills at an early age. Through paisakmao.de, I share actionable guides for students to start earning early, money wisdom that schools don’t teach, and mindset lessons from successful people and modern psychology. Whether you’re a teenager looking to earn your first income or a student exploring side hustles, you’re in the right place. Financial freedom begins with the right mindset and the right knowledge. Let’s grow, earn, and evolve together — welcome to the movement!
Getting a salary every month feels good, but managing that money wisely can be challenging, especially when you are just starting to manage your finances. Bills, daily expenses, savings, debt, and personal spending can quickly compete for the same income.
Learning how to divide your salary for beginners can make this much easier. Instead of spending first and trying to save whatever is left, you can give each part of your income a clear purpose from the beginning.
In this guide, you’ll learn practical ways to divide your salary, how the 50/30/20 rule works, when other budgeting methods may be better, and how to adjust your plan based on your income and expenses. You’ll also see real salary examples and simple steps you can use every month.
The goal is not to follow a percentage blindly, but to build a salary plan that works in your real life.
How Should a Beginner Divide Their Salary?
Getting started with salary budgeting does not mean following one fixed percentage. A beginner should first understand how much money comes in, what must be paid, what should be saved, and how much can be used for personal spending.
A simple starting order is:
Take-home salary → Essential expenses → Savings → Debt and financial goals → Personal spending → Monthly review
Start With Your Take-Home Salary
Use the amount you actually receive in your bank account each month, not your gross salary. This gives you a realistic starting point for your monthly budget.
Separate Needs From Wants
Start by identifying essential expenses such as rent, food, utilities, transportation, insurance, and necessary family expenses. Then separate them from wants such as shopping, entertainment, eating out, and hobbies.
This helps you see where your salary is actually going before deciding how much you can spend or save.
Set Aside Savings Before Extra Spending
Instead of waiting until the end of the month to see what is left, decide on a savings amount in advance. This makes saving a planned part of your salary rather than something you do only when extra money remains.
You can divide this money between short-term goals, emergency savings, and other financial goals based on your situation.
Include Debt and Financial Goals
If you have debt, loan payments should be included in your monthly salary allocation. You may also need to set aside money for goals such as education, a major purchase, or long-term financial plans.
Your allocation should change when your priorities change.
Keep a Realistic Amount for Personal Spending
A good budget should still leave room for reasonable personal spending. Giving yourself a clear limit for wants can make your plan easier to follow without feeling unnecessarily restrictive.
Use Percentages as a Starting Point
Percentage-based budgeting can make salary allocation simpler for beginners. However, percentages are not strict rules. Your ideal allocation may be different because of your income, living costs, debt, family responsibilities, and financial goals.
For example, a person with high rent may need to spend more on essential expenses, while someone with lower fixed costs may be able to save more.
Example: Dividing a ₹30,000 Monthly Salary
A simple starting example could look like this:
Category
Percentage
Amount
Essential expenses
50%
₹15,000
Wants and personal spending
30%
₹9,000
Savings and financial goals
20%
₹6,000
This is only a starting example. If your essential expenses are higher, you can adjust the percentages instead of forcing your budget to fit a rule.
The 50/30/20 rule is one of the most popular ways beginners can structure their salary, so let’s look at how it works in detail.
What is the 50/30/20 rule for splitting your salary?
The 50/30/20 rule is a simple way to budget your take-home pay by splitting it into 50% for needs, 30% for wants, and 20% for savings or financial goals. The Consumer Financial Protection Bureau (CFPB) describes it as an easy method to help you organize your spending and saving.
If you’re just getting started with money management, this rule helps you give every rupee a job instead of spending first and saving whatever is left. If you’re new to this, our Personal Finance for Beginners guide covers the basics of budgeting and saving.
50% for Needs
Needs are the things you can’t really avoid in daily life, like:
Rent or housing
Groceries
Utilities
Transportation
Phone and internet
Insurance
Minimum debt payments
For a ₹30,000 salary, 50% comes to ₹15,000. If your actual essential expenses are lower, you can put the extra into savings or investments.
30% for Wants
Wants are the fun or optional things you spend on, like:
Eating out
Entertainment
Shopping
Subscriptions
Travel
Hobbies
For a ₹30,000 salary, 30% is ₹9,000. If you don’t use it all, you can move the leftover into savings or use it to pay off debt.
20% for Savings and Goals
This part is for your future and financial security, such as:
Emergency fund
Debt repayment
Investments
Retirement savings
Big planned purchases
For a ₹30,000 salary, 20% is ₹6,000. It’s usually a good idea to start with an emergency fund or high-interest debt first. The SEC’s Investor.gov also talks about why saving and investing regularly matters.
50/30/20 Salary Breakdown
Monthly Salary
Needs (50%)
Wants (30%)
Savings (20%)
₹20,000
₹10,000
₹6,000
₹4,000
₹30,000
₹15,000
₹9,000
₹6,000
₹50,000
₹25,000
₹15,000
₹10,000
These are just examples, not strict rules.
What If It Doesn’t Fit?
The 50/30/20 rule isn’t fixed—you can tweak it based on your situation. If your needs take up more of your income, you could try something like:
How to Allocate Your Salary Based on Actual Expenses
The 50/30/20 rule is a good starting point, but your budget should really match your actual income and spending habits. Fixed percentages don’t always work well when rent, EMIs, and basic living costs vary a lot from person to person.
A better way is to build a salary plan based on what you actually spend.
Start With Your Take-Home Salary
Start with your net (in-hand) salary after taxes and deductions.
For example, if you earn ₹30,000 a month, use that amount for planning instead of your gross salary.
Identify Fixed Expenses
Fixed expenses are the things you pay every month, such as:
Rent
Loan EMIs
Insurance
Internet and mobile bills
Subscriptions
Adding these up helps you see how much of your income is already committed.
Assess Variable Expenses
Variable expenses change from month to month, such as:
Groceries
Transportation
Eating out
Shopping
Entertainment
Looking at your past spending can help you figure out a realistic average and spot where you might cut back if needed.
Distinguish Between Needs and Wants
Needs are the essentials like rent, food, and utilities. Wants are things like dining out, shopping, and entertainment.
This makes it easier to see whether your lifestyle spending is affecting your savings.
Define Savings and Financial Goals
After covering expenses, decide how much you can put toward savings and goals like:
Emergency fund
Loan repayment
Investments
Retirement savings
For example, with a ₹30,000 salary: ₹16,000 needs + ₹6,000 wants = ₹8,000 savings
That comes out to roughly a 53% / 20% / 27% split, which is often more realistic than sticking to a fixed rule.
The main idea is to build a budget that actually fits your life and adjust it as your income or expenses change.
How to Create a Monthly Salary Budget That Actually Works
A good monthly salary budget is not about tracking every rupee perfectly. It is about knowing where your money should go before you start spending it.
Start With Your Take-Home Salary
Start with your take-home salary—the amount that actually reaches your bank account after taxes and other deductions.
For example, if you take home ₹30,000 per month, use ₹30,000 as the starting point for your budget instead of your gross salary.
Then list your regular expenses, such as:
Rent or housing
Groceries
Utilities and phone bills
Transportation
Loan EMIs
Subscriptions
Other regular spending
This gives you a clear picture of where your income is going.
If you are still learning the basics, our Personal Finance for Beginners guide can help you understand how budgeting fits into your overall financial plan.
Set Realistic Spending Limits
Once you know your regular expenses, set a realistic spending limit for each major category.
Instead of simply telling yourself to “spend less,” decide how much you can reasonably spend on groceries, eating out, shopping, entertainment, and other flexible expenses.
For example, you might set limits for:
Groceries: ₹4,000
Eating out: ₹1,500
Entertainment: ₹1,000
Shopping: ₹1,500
The exact numbers will depend on your income and lifestyle.
A good budget should feel manageable. If your limits are too strict, you may find it difficult to follow them consistently.
Prioritize Savings and Financial Goals
Do not wait until the end of the month to see whether you have money left to save.
Decide in advance how much you want to put toward important financial goals, such as:
Emergency savings
Debt repayment
Investments
Retirement
A planned purchase
If possible, move your planned savings soon after receiving your salary. This makes saving a regular habit instead of something you do only when extra money is available.
The Consumer Financial Protection Bureau (CFPB) recommends getting a clear picture of your income and spending, creating a realistic working budget, and updating it when your income or spending habits change.
Review What You Actually Spent
A monthly budget becomes more useful when you compare what you planned to spend with what you actually spent.
For example, suppose you planned to spend ₹4,000 on groceries but ended the month at ₹5,000.
Instead of simply calling it overspending, ask why it happened. Maybe prices increased, you made extra purchases, or you underestimated your normal grocery costs.
Then use that information to make next month’s budget more realistic.
Adjust Your Budget When Your Life Changes
Your salary budget should not remain fixed forever.
A salary increase, new EMI, higher rent, family responsibility, or change in daily expenses can affect how you should divide your money.
If your income increases, you do not necessarily need to increase your lifestyle spending by the same amount. You could direct part of the extra income toward savings, debt repayment, or long-term financial goals.
The same applies when your expenses increase. Instead of abandoning your budget, review your categories and adjust them based on your new situation.
The goal is not to create a perfect budget. It is to build a simple monthly spending plan that fits your real life, gives every rupee a purpose, and is realistic enough to follow consistently.
How Much Should You Save From Your Salary?
There is no single savings amount that works for everyone. The right amount depends on your income, essential expenses, debt, and financial goals.
The 20% in the 50/30/20 rule can be a useful starting point, but you do not have to force yourself to save exactly 20% if your current situation does not allow it.
Start With an Amount You Can Maintain
If you cannot save 20% of your salary right now, start with an amount you can consistently set aside.
For example, if you earn ₹25,000 and can comfortably save ₹2,500 each month, that is still a good starting point. As your income increases or your expenses decrease, you can gradually increase the amount.
The important part is to make saving a regular habit rather than waiting for a month when you have extra money.
Build an Emergency Fund First
Before focusing heavily on long-term goals, build money that can help you handle unexpected expenses.
An emergency fund can be useful for situations such as:
Unexpected medical or household expenses
Temporary loss of income
Urgent repairs
Other necessary costs you did not plan for
The Consumer Financial Protection Bureau (CFPB) explains that an emergency fund is money set aside for unplanned expenses and that even a small amount can provide some financial security.
Keep this money separate from your normal spending account so you are less likely to use it for everyday purchases.
Save for Short-Term and Long-Term Goals
Not every savings goal has the same time frame.
Short-term goals might include a planned purchase, travel, education, or an upcoming expense. Long-term goals may include retirement or building long-term wealth.
Giving each goal a purpose makes it easier to decide where your savings should go instead of treating all saved money as one large amount.
If you are building your broader financial plan, our Financial Planning for Beginners guide can help you connect saving with other financial priorities.
Increase Your Savings When Your Income Grows
You do not have to keep the same savings amount forever.
If you receive a raise, bonus, or additional income, consider directing part of the increase toward savings before increasing your lifestyle spending.
For example, if your salary rises from ₹30,000 to ₹35,000, you could increase your monthly savings by ₹2,000 and use the remaining increase for other priorities.
This allows your savings rate to grow without making your monthly budget feel dramatically tighter.
The goal is not to save the highest possible percentage of your salary. It is to build a savings habit that is realistic today and can grow with your income over time.
How to Divide Your Salary Between Bills, Spending, and Savings
Once you know your income and your financial priorities, the next step is to decide how much of your salary should go toward bills, everyday spending, savings, and other financial goals.
The exact percentages do not have to match the 50/30/20 rule. Your rent, debt, family responsibilities, and income may require a different balance.
Cover Essential Bills First
Start by separating the expenses you need to pay every month from the expenses you can control or reduce.
Essential expenses may include:
Rent or housing
Electricity, water, and other utilities
Groceries and basic food
Transportation
Insurance
Minimum debt or EMI payments
These expenses should come first because missing essential bills or debt payments can create bigger financial problems later.
If your essential expenses already consume more than 50% of your salary, do not force yourself to follow the 50/30/20 rule. Instead, look for areas where you can gradually reduce costs while keeping your basic needs covered.
The FDIC explains that budgeting can help you track income, expenses, and savings while making better decisions about needs and wants.
Set a Limit for Everyday Spending
After covering essential bills, decide how much you can reasonably spend on things that are not necessary for basic living.
This may include:
Eating out
Entertainment
Shopping
Hobbies
Subscriptions
Social activities
Giving these expenses a limit does not mean you have to remove all enjoyment from your budget. It simply prevents optional spending from taking money away from important financial goals.
For example, instead of spending whenever you feel like it, you might give yourself a fixed monthly amount for eating out and entertainment. Once that amount is used, you can wait until the next month.
Give Savings a Fixed Place in Your Salary
Savings should not depend entirely on whatever money is left after spending.
Choose an amount that you can realistically save every month and treat it as one of your regular financial commitments.
You can divide your savings between different goals, such as:
Emergency fund
Short-term purchases
Debt repayment
Investments
Retirement
If you are still building your overall financial plan, our Financial Planning for Beginners guide can help you connect your monthly budget with longer-term goals.
Use a Realistic Salary Example
Suppose your monthly take-home salary is ₹40,000.
You might create a starting allocation like this:
₹20,000 for essential bills and needs
₹5,000 for flexible spending
₹15,000 for savings, debt repayment, and financial goals
That gives you a 50% / 12.5% / 37.5% split. It is very different from a strict 50/30/20 allocation, but it may work well if your lifestyle allows you to save more.
The numbers are only an example. Someone with higher rent or family responsibilities may need to allocate much more toward essential expenses.
Keep Your Salary Budget Flexible
Your salary allocation does not have to remain exactly the same every month.
You may have a higher electricity bill one month, a medical expense the next, or an unexpected repair. These changes are part of real life.
Instead of abandoning your budget when something unexpected happens, adjust your flexible spending first and protect your essential bills and important financial goals as much as possible.
As your income changes, review the whole allocation again. A salary increase can create an opportunity to increase savings, while a new EMI may require you to reduce discretionary spending.
The goal is not to divide your salary perfectly. It is to create a system where your bills are covered, your spending stays under control, and your money continues moving toward your financial goals.
How to Adjust Your Salary Budget When Your Income or Expenses Change
Your salary budget should not be treated as a fixed formula. Your income and expenses can change over time, so your budget should change with them.
A raise, new EMI, higher rent, unexpected expense, or change in your family responsibilities can all affect how much money you have available each month.
Review Your Budget After a Salary Increase
When your income increases, it can be tempting to immediately increase your lifestyle spending.
Instead, give the extra income a purpose before you start spending it. You could divide the increase between savings, debt repayment, investments, and a reasonable increase in your lifestyle spending.
For example, if your salary increases from ₹30,000 to ₹35,000, you do not have to spend the entire ₹5,000 increase. You might put ₹2,500 toward savings or investments and use the remaining ₹2,500 for other priorities.
This helps prevent lifestyle inflation, where spending rises every time your income rises.
Adjust When Your Expenses Increase
Sometimes your income stays the same while your expenses increase. Rent may go up, an EMI may start, or household costs may become more expensive.
When this happens, review your flexible spending before cutting important financial goals completely.
For example, you might temporarily reduce eating out, shopping, entertainment, or unused subscriptions to make room for a necessary increase in expenses.
Plan for Irregular Expenses
Not every expense arrives every month. Insurance renewals, repairs, annual subscriptions, travel, and other occasional costs can catch you off guard if you only budget for regular monthly bills.
A simple solution is to estimate these expenses in advance and set aside a small amount each month.
For example, if you expect an annual expense of ₹12,000, setting aside around ₹1,000 per month can make the eventual payment much easier to handle.
Review Your Budget Regularly
You do not need to rebuild your entire budget every week. A monthly review is usually enough for most people.
At the end of each month, check three things:
What did I actually spend?
Which category went over budget?
Did I save the amount I planned to save?
Use the answers to make small adjustments for the following month. If you are struggling to save despite having a reasonable income, our guide to why you can’t save money can help you identify common spending and saving problems.
Do Not Abandon Your Budget After One Bad Month
One expensive month does not mean your entire financial plan has failed.
Unexpected expenses happen. The important thing is to understand what caused the overspending and adjust your next month’s plan instead of giving up completely.
A useful salary budget is a flexible system that changes as your financial situation changes. The goal is to keep your spending under control while continuing to make progress toward your savings and financial goals.
Common Salary Budgeting Mistakes to Avoid
Even with a basic salary budget, it is easy to make mistakes that slowly affect your savings and financial progress. The problem is usually not the budgeting rule itself, but how the budget is used in real life.
1. Budgeting With Your Gross Salary
One common mistake is creating a budget using your gross salary instead of the amount you actually receive.
Your budget should start with your take-home salary because that is the money available for your monthly expenses, savings, and financial goals.
2. Saving Only What Is Left
If you spend first and plan to save whatever remains at the end of the month, there may be very little left.
A better approach is to decide your savings amount in advance and treat it as part of your monthly financial plan.
3. Following a Percentage Too Strictly
The 50/30/20 rule is a useful framework, but it is not a requirement that every person must follow exactly.
Someone paying high rent or supporting a family may need a different allocation. The goal is to create a budget that fits your actual circumstances rather than forcing your expenses into fixed percentages.
4. Ignoring Small and Irregular Expenses
Small purchases can look harmless individually but become significant when they happen repeatedly.
Subscriptions, frequent food deliveries, small online purchases, and convenience spending can quietly reduce the money available for savings.
Irregular expenses can cause another problem. Annual insurance payments, repairs, travel, or other occasional costs should be considered before they arrive.
5. Forgetting to Build an Emergency Fund
A budget that only covers normal monthly expenses can still leave you vulnerable when something unexpected happens.
Building an emergency fund gives you a separate pool of money for necessary unplanned expenses instead of forcing you to rely on credit or new debt.
6. Increasing Lifestyle Spending Too Quickly
When your salary increases, it is natural to want a better lifestyle. But increasing every expense at the same time can prevent your savings from growing.
Instead, consider putting part of every raise or bonus toward savings, investments, or debt repayment before increasing discretionary spending.
A budget is not something you create once and forget about.
Your income, bills, priorities, and spending habits can change. Review your actual spending regularly and make small adjustments when necessary.
If you notice that a particular category repeatedly goes over budget, do not simply keep setting the same unrealistic limit. Find the reason and change the plan.
8. Giving Up After One Bad Month
Unexpected expenses can make one month look completely different from your original plan. That does not mean your entire budget has failed.
Look at what caused the difference, make the necessary adjustment, and start again the following month.
The best salary budget is not the one that looks perfect on paper. It is the one you can actually follow, review, and adjust as your financial life changes.
What is the 50/30/20 rule for salary?
The 50/30/20 rule suggests using 50% of your take-home income for needs, 30% for wants, and 20% for savings and financial goals. It is a flexible starting point rather than a strict rule.
How much of my salary should I save each month?
A 20% savings target can be a useful starting point if your budget allows it. If 20% is not realistic, start with an amount you can consistently save and increase it over time.
How should I budget a ₹30,000 monthly salary?
Start by calculating essential expenses such as rent, food, transportation, utilities, and EMIs. Then control flexible spending and allocate the remaining amount toward savings and financial goals.
Is the 50/30/20 rule realistic for a low salary?
Not always. If essential expenses consume most of your income, focus on covering your needs, controlling flexible expenses, and saving whatever amount you can consistently.
Conclusion: Build a Salary Budget That Fits Your Life
Dividing your salary is not about following one perfect formula. The 50/30/20 rule can give you a useful starting point, but your actual budget should reflect your income, essential expenses, debt, lifestyle, and financial goals.
Start with your take-home salary, cover your essential needs, set a realistic limit for flexible spending, and give your savings a clear place in your monthly plan. Then review your actual spending and adjust the budget whenever your income or expenses change.
Most importantly, do not worry if your numbers do not perfectly match a standard percentage. A simple budget that you can follow consistently, review regularly, and improve over time is more useful than a perfect-looking budget that does not work in real life.
Start with what you can manage today, and let your salary budget grow with your income and financial goals.
Post Summary Learn how to divide your salary effectively with this beginner-friendly guide. Discover the 50/30/20 rule, practical salary allocation examples, savings strategies, budgeting tips, common mistakes, and simple ways to build a monthly budget that fits your real income and expenses.
7 Rules of Personal Finance? Managing money can be difficult, especially when you are just starting to take control of your finances. You may earn a regular income but still struggle to save, deal with unexpected expenses, manage debt, or know where to invest your money.
The problem is often not simply how much you earn, but how you manage the money you have. Without a clear system, it is easy to spend too much, delay saving, depend on debt, or make financial decisions without knowing what should come first.
So, what are the 7 rules of personal finance? These rules provide a simple framework for managing your money, from controlling spending and building an emergency fund to managing debt, investing, protecting your finances, and setting financial goals.
In this complete beginner’s guide, we’ll explain each rule with practical examples, common mistakes, and actionable steps so you can build a stronger financial foundation step by step.
Quick Answer: What Are the 7 Rules of Personal Finance?
The 7 rules of personal finance are:
Spend Less Than You Earn — Keep your expenses below your income so you can create room for saving and investing.
Create and Follow a Budget — Plan where your money should go and track your spending.
Build an Emergency Fund — Keep savings available for unexpected expenses or a temporary loss of income.
Manage High-Interest Debt — Pay attention to expensive debt because high interest can slow down your financial progress.
Save and Invest Consistently — Save for short-term needs and invest appropriately for long-term financial goals.
Protect Your Finances — Reduce major financial risks with appropriate insurance and other safeguards.
Set Financial Goals and Review Your Progress — Give your money clear goals and regularly check whether you are moving toward them.
These seven rules work together. The goal is not to follow them perfectly from day one, but to build each habit step by step and create a financial system that fits your income, expenses, priorities, and long-term goals.
Rule 1: Spend Less Than You Earn
The first rule of personal finance is simple: spend less than you earn. It may sound obvious, but this basic habit creates the financial space you need to save money, handle unexpected expenses, repay debt, and work toward long-term goals.
If you earn ₹30,000 a month and spend ₹30,000, you have no financial surplus. But if you earn ₹30,000 and spend ₹25,000, you have ₹5,000 left that can be given a specific purpose.
The goal is not to stop enjoying your money. It is to make sure your spending does not consume everything you earn.
What Does “Spend Less Than You Earn” Mean?
At its simplest:
Income − Expenses = Financial Surplus
For example:
Monthly Money
Amount
Take-home income
₹30,000
Essential expenses
₹18,000
Lifestyle spending
₹5,000
Other expenses
₹2,000
Money remaining
₹5,000
That ₹5,000 is your financial surplus. Instead of allowing it to disappear through unplanned spending, you can direct it toward savings, an emergency fund, debt repayment, or an appropriate long-term financial goal.
Most important financial goals require money to remain after your regular expenses have been paid.
Saving requires a portion of your income to remain available.
An emergency fund requires regular contributions.
Debt repayment becomes easier when you have extra cash flow.
Investing requires money that you do not need for immediate expenses.
Financial goals become easier when your spending stays below your income.
Consider two people who both earn ₹30,000 per month.
Person A: earns ₹30,000 and spends ₹29,500, leaving ₹500.
Person B: earns ₹30,000 and spends ₹24,000, leaving ₹6,000.
They earn the same amount, but Person B has created much more financial breathing room.
This does not mean Person A is necessarily irresponsible. Their higher expenses could be caused by rent, healthcare, family responsibilities, transportation, or other essential costs. The important lesson is that income alone does not determine financial progress.
Spending Less Does Not Mean Living Miserably
A common misunderstanding about personal finance is that spending less means eliminating everything you enjoy.
That is not the goal.
You can still spend money on entertainment, hobbies, eating out, travel, or things that genuinely improve your quality of life. The important question is whether those expenses fit within your financial situation.
Before making a non-essential purchase, ask yourself:
Do I actually need this?
Does it provide enough value for its cost?
Is this purchase delaying an important financial goal?
Could I get similar value for less money?
Can I comfortably afford it without using debt?
Good personal finance is not about saying “no” to everything. It is about deciding what deserves your money.
Understand Needs, Wants, and Desires
One practical way to control spending is to separate your expenses into needs, wants, and desires.
Needs
Needs are essential expenses required for basic living and important responsibilities. Examples include food, housing, basic clothing, healthcare, and necessary transportation.
Wants
Wants are things that improve comfort or lifestyle but are not essential. Examples include dining out, entertainment, vacations, and some subscriptions.
Desires
Desires are stronger aspirations or luxury purchases that can usually be delayed, such as an expensive phone, luxury car, or high-end electronics.
The point is not to eliminate wants and desires. It is to make sure they do not consume money that should first go toward essential expenses and important financial priorities.
Track Your Spending Before Trying to Fix It
Many people know exactly how much they earn but cannot explain where most of their money goes.
That makes it difficult to improve your finances.
For the next 30 days, record every expense. You can divide your spending into categories such as:
Housing
Food and groceries
Transportation
Utilities and bills
Debt payments
Shopping
Entertainment
Subscriptions
Savings
Investments
Do not worry about changing everything while you are tracking. First understand your actual spending pattern. Once you can see where your money goes, you can decide what needs to change.
Create a Monthly Spending Gap
After tracking your expenses, calculate your monthly surplus.
For example:
Income = ₹35,000
Total expenses = ₹29,000
Surplus = ₹6,000
Now the ₹6,000 needs a purpose.
Depending on your situation, it might be used for an emergency fund, high-interest debt repayment, a short-term financial goal, or long-term investing.
There is no single percentage that works for everyone. Your income, responsibilities, debt, location, goals, and financial stability all matter.
What If You Spend More Than You Earn?
Suppose your income is ₹30,000 but your monthly expenses are ₹32,000.
₹30,000 − ₹32,000 = −₹2,000
You have a monthly deficit of ₹2,000.
Do not immediately try to remove every small expense. First identify the biggest causes of the deficit.
Calculate your actual take-home income.
List all your monthly expenses.
Identify your three largest discretionary expenses.
Review recurring payments and subscriptions.
Look for expenses that can realistically be reduced.
Consider whether your income needs to increase.
Use the money you free up to eliminate the deficit first.
One of the biggest challenges to spending less than you earn is lifestyle inflation.
Imagine your salary increases from ₹30,000 to ₹40,000. Instead of allowing some of that additional ₹10,000 to improve your savings or financial position, you increase your lifestyle by ₹10,000 as well.
Your income increased, but your financial surplus did not.
A better approach is to enjoy part of an income increase while directing another part toward savings, debt repayment, or other financial goals.
Build a System Instead of Depending on Willpower
Trying to remember every financial decision throughout the month can become exhausting. A simple system is easier to maintain.
You can think of your money flow like this:
Income → Essential expenses → Financial priorities → Flexible spending
When your financial priorities are decided in advance, you are less likely to spend the entire income before thinking about your future.
If your income changes from month to month, your system needs to be more flexible. In that situation, your existing guide on How to Budget with an Irregular Income can help you build a more suitable monthly approach.
Don’t Ignore Small Repeated Expenses
A single ₹100 expense may not look important. But repeated spending can become significant.
For example:
₹100 × 20 purchases = ₹2,000
This does not mean every ₹100 purchase is bad. The point is to identify spending patterns that happen automatically or provide very little value.
Investor.gov also highlights that small everyday expenses can add up over time, which is why tracking spending can reveal opportunities to save.
What Should You Do With the Money You Don’t Spend?
Creating a surplus is only the first step. The next step is giving that surplus a purpose.
Depending on your circumstances, your priorities might include:
Building an emergency fund
Paying down high-interest debt
Saving for short-term goals
Preparing for major future expenses
Investing for appropriate long-term goals
An emergency fund can be especially useful because unexpected expenses can otherwise force you to rely on credit or loans. The Consumer Financial Protection Bureau’s emergency-fund guide explains how dedicated emergency savings can help people handle unplanned expenses and financial shocks.
Common Mistakes Beginners Make
1. Saving Only What Is Left
If you spend first and save whatever happens to remain, saving may become inconsistent.
2. Increasing Spending Every Time Income Increases
A higher income can improve your financial position, but only if some of the increase remains available for financial goals.
3. Ignoring Recurring Expenses
Subscriptions, memberships, EMIs, and automatic payments can quietly reduce your monthly surplus.
4. Using Debt for Unnecessary Lifestyle Spending
Borrowing can make something affordable today while creating a financial obligation for the future.
5. Following Someone Else’s Budget Exactly
A budget that works for another person may not work for you. Your income, responsibilities, expenses, and goals are different.
A Simple 30-Day Action Plan
Week 1: Track
Record every expense without trying to judge or change your behaviour immediately.
Week 2: Analyze
Separate needs from wants and identify your largest spending categories.
Week 3: Reduce
Choose one or two realistic expenses that you can reduce without creating an unsustainable lifestyle.
Week 4: Redirect
Give the money you saved a specific purpose, such as emergency savings, debt repayment, or another financial goal.
The goal is not to become perfect in 30 days. The goal is to build a system you can continue every month.
Quick Checklist
☐ I know my actual monthly take-home income.
☐ I track my monthly expenses.
☐ My total spending is lower than my income.
☐ I understand the difference between needs and wants.
☐ I am aware of lifestyle inflation.
☐ I have a plan for my monthly surplus.
☐ I am building financial security instead of spending everything I earn.
Key Takeaway
Spending less than you earn is not about living a miserable or extremely restrictive life. It is about creating financial breathing room.
When you consistently maintain a gap between your income and expenses, that surplus can become savings, emergency protection, debt reduction, and long-term wealth.
Earn → Spend intentionally → Keep a surplus → Give the surplus a purpose.
Once you understand how to create that surplus, the next question is how to control and organize your monthly spending. That brings us to Rule 2: Create and Follow a Budget.
Rule 2: Build an Emergency Fund Before You Need It
An emergency fund is one of the most important foundations of personal finance for beginners. It is money kept aside specifically for unexpected expenses or financial emergencies, so you do not have to depend immediately on credit cards, loans, or money meant for other goals.
The purpose is not to make you afraid of unexpected expenses. The purpose is to make sure that an unexpected expense does not completely destroy your monthly budget.
What Is an Emergency Fund?
An emergency fund is a separate pool of money reserved for expenses that are unexpected, necessary, and difficult to postpone. Examples can include an urgent medical bill, essential home or vehicle repair, sudden job loss, or an unexpected period of reduced income.
The Consumer Financial Protection Bureau (CFPB) describes an emergency fund as a cash reserve specifically set aside for unplanned expenses and financial emergencies. It also notes that even a small amount of emergency savings can provide some financial security.
Without emergency savings, one unexpected expense can turn into a much larger financial problem. You may have to borrow money, use a credit card, sell investments at the wrong time, or delay important bills.
For example, imagine that you earn $2,000 a month and normally manage your expenses successfully. Then your car suddenly needs a $600 repair. If you have no emergency savings, that $600 may have to come from debt or money intended for rent, investing, or another financial goal.
With an emergency fund, the same problem can be handled using money that was already reserved for unexpected situations.
This is why an emergency fund is not simply another savings goal. It is a financial protection system.
How Much Should You Keep in an Emergency Fund?
There is no single emergency-fund amount that is perfect for everyone. Your target should depend on your essential monthly expenses, income stability, debt obligations, dependents, and how difficult it would be to replace your income.
A useful way to think about your target is in stages:
Starter fund: Build a small first layer that can handle common minor emergencies.
Basic emergency fund: Work toward several months of essential living expenses.
Higher safety buffer: Consider a larger reserve if your income is unstable, you have dependents, or replacing your income would take longer.
FDIC consumer guidance notes that a common recommendation is to keep around three to six months of expenses in emergency savings, while also emphasizing that the appropriate amount depends on factors such as income and expenses.
Calculate Your Emergency Fund From Essential Expenses
Do not automatically calculate your emergency fund from your total monthly spending. Start by identifying the expenses you would still need to pay if your income suddenly became limited.
Your essential monthly expenses might include:
Rent or housing costs
Basic groceries
Utilities
Essential transportation
Insurance premiums
Minimum debt payments
Essential medical expenses
Other necessary household costs
For example, if your essential expenses are $1,500 per month and you decide that your initial target is three months of essential expenses:
$1,500 × 3 = $4,500
Your target would therefore be $4,500 for a three-month emergency reserve.
This is only an example. Your actual target should reflect your own circumstances rather than blindly copying someone else’s number.
Start Small If You Cannot Save Thousands
One of the biggest mistakes beginners make is believing that an emergency fund is useless unless they can immediately save several months of expenses.
That mindset can prevent people from starting at all.
If your income is limited, begin with an amount that is realistic for you. Even a small reserve can be useful when an unexpected expense appears.
For example, you could create milestones such as:
First goal: build your first small emergency buffer.
Second goal: cover one common unexpected expense.
Third goal: build one month of essential expenses.
Long-term goal: gradually increase the fund toward several months of essential expenses.
The important principle is progress. Your emergency fund does not have to be perfect on day one.
Where Should You Keep Your Emergency Fund?
An emergency fund should be safe, accessible, and separated enough from everyday spending that you are not tempted to use it for unnecessary purchases.
A dedicated savings or bank account can make the purpose of the money clearer. The best place will depend on your country, available accounts, access requirements, fees, and applicable protections.
The CFPB recommends considering safety and accessibility when deciding where to keep emergency savings.
Keep Your Emergency Fund Separate From Everyday Spending
If your emergency money sits in the same account you use for shopping, entertainment, subscriptions, and daily spending, it can become very easy to spend it without realizing it.
A simple system is:
Everyday money: regular bills and daily expenses.
Emergency money: unexpected and necessary expenses only.
Goal-based savings: planned purchases and short-term goals.
Investment money: long-term wealth-building.
This separation makes the purpose of each dollar easier to understand and reduces accidental spending.
What Counts as a Financial Emergency?
Not every unexpected purchase is an emergency. A useful test is to ask three questions:
Was the expense genuinely unexpected?
Is it necessary or financially important?
Can the expense reasonably wait until it can be paid from normal income?
Examples that may qualify include:
Unexpected essential medical costs
Urgent home repairs
Necessary vehicle repairs
Unexpected loss or reduction of income
Essential emergency travel
Other major unplanned expenses that cannot reasonably be postponed
What Should You NOT Use an Emergency Fund For?
An emergency fund should not become a general-purpose spending account.
It is usually better not to use emergency savings for:
A new phone when your current phone works
Shopping during a sale
Planned vacations
Entertainment
Luxury purchases
Regular monthly bills that you already knew about
Investments that you simply want to make
Planned expenses should normally have their own savings category instead of being taken from your emergency reserve.
Emergency Fund vs. Regular Savings: What Is the Difference?
Regular savings and emergency savings both involve putting money aside, but they serve different purposes.
Emergency Fund
Regular Savings
Unexpected financial problems
Planned future expenses
Medical emergency or urgent repair
Vacation or new phone
Unexpected income loss
Planned purchase
Used only when necessary
Used according to your savings goal
Keeping these purposes separate helps you avoid spending your emergency reserve on expenses that could have been planned for in advance.
How Can You Build an Emergency Fund on a Low Income?
Building emergency savings on a low income can be difficult, but the strategy does not have to be complicated.
Start by choosing a small amount that you can consistently save. It could be a fixed amount from every paycheck or a percentage of your income.
For example, if you can comfortably save $25 from each paycheck, do not dismiss it because it seems small. Consistency turns small contributions into a growing financial buffer.
You can also direct occasional extra money toward the fund, such as bonuses, gifts, refunds, or income from temporary work, while still keeping enough money available for your essential needs.
The CFPB also recommends starting with what you can afford and building the emergency fund over time rather than waiting until you can save a large amount at once.
What If Your Income Is Irregular?
If your income changes from month to month, an emergency fund becomes even more useful because your financial risk is different from someone with a highly predictable paycheck.
Instead of depending on a fixed monthly savings amount, you can use a flexible system:
Save a minimum amount during low-income months.
Save more during stronger-income months.
Send part of unexpected extra income to your emergency fund.
Protect the fund from unnecessary withdrawals.
If your income is irregular, you can also learn more about creating a survival budget and managing variable income in your related guide:
Should You Build an Emergency Fund Before Investing?
For many beginners, building at least an initial emergency buffer before taking significant investment risk can make the overall financial system more stable.
The reason is simple: investments are designed for longer-term goals and can fluctuate in value. An emergency fund is designed for money you may need unexpectedly and should therefore prioritize accessibility and stability.
This does not mean every person must stop investing completely until they reach a large emergency-fund target. Your decision should consider your income, debt, financial responsibilities, and risk tolerance.
The key principle is to avoid putting money into investments that you may suddenly need for an emergency.
What Should You Do If You Have to Use Your Emergency Fund?
Using your emergency fund does not mean you failed.
That is exactly what the fund is designed for.
If a genuine emergency happens and you need to use the money, focus first on solving the emergency. After the situation is under control, make rebuilding your emergency fund your next financial priority.
For example:
Emergency → Use the fund → Stabilize your finances → Rebuild the fund → Return to normal saving and investing.
The CFPB specifically recommends rebuilding emergency savings after you have used it for an unexpected expense.
Common Emergency Fund Mistakes Beginners Make
1. Waiting Until You Can Save a Large Amount
Waiting for the perfect income level can delay your emergency savings for years. Start with what is realistic today.
2. Keeping the Money Too Easy to Spend
If emergency savings are mixed with everyday spending money, you may accidentally treat them as available spending money.
3. Using the Fund for Wants
A discount, vacation, gadget, or entertainment purchase is not automatically an emergency just because it was unexpected.
4. Never Rebuilding the Fund
After using emergency savings, some people simply continue with their normal budget. That leaves them exposed to the next unexpected expense.
5. Copying Someone Else’s Target
Your emergency-fund requirement depends on your own expenses, income stability, responsibilities, and financial situation. A target that works for one household may be too small or unnecessarily large for another.
A Simple Emergency Fund Building System
You can turn the rule into a simple system instead of relying on motivation.
Calculate essential monthly expenses.
Choose your first realistic savings milestone.
Create a separate place for emergency savings.
Automate or schedule contributions when possible.
Add extra money when your income allows.
Use the fund only for genuine emergencies.
Rebuild it after every major withdrawal.
Review the target whenever your income or responsibilities change.
Automatic transfers can make saving easier because the money is moved before you have an opportunity to spend it. FDIC consumer guidance also highlights automatic transfers as a practical way to build savings over time.
A Practical Example: Building an Emergency Fund Step by Step
Imagine a beginner has essential monthly expenses of $1,200.
Instead of thinking, “I need thousands of dollars immediately,” the person can create milestones.
Stage 1: Build a small starter buffer.
Stage 2: Increase the fund until it can handle a common unexpected expense.
Stage 3: Reach one month of essential expenses.
Stage 4: Continue building toward several months of essential expenses.
This approach makes a large financial goal feel more achievable because you are focusing on the next milestone rather than the entire journey at once.
Emergency Fund Quick Checklist
☐ I know my essential monthly expenses.
☐ I have a separate emergency savings location.
☐ I have chosen a realistic first savings target.
☐ I contribute regularly, even if the amount is small.
☐ I know what qualifies as an emergency.
☐ I avoid using emergency savings for wants.
☐ I increase my target when my financial responsibilities increase.
☐ I rebuild the fund after using it.
Key Takeaway
An emergency fund is not about predicting exactly when something will go wrong. It is about preparing before something goes wrong.
The strongest approach is to start with an amount you can realistically save, keep the money accessible and separate from everyday spending, use it only for genuine emergencies, and gradually increase the reserve as your financial situation improves.
Once you have a basic financial safety net, the next rule becomes important: protecting that progress by managing debt carefully and avoiding financial decisions that can push you backward.
Rule 3: Pay Off High-Interest Debt
One of the most important rules of personal finance is to control and pay off high-interest debt. Debt itself is not always bad, but expensive debt can quietly consume your income and make it much harder to save, invest, or build financial security.
If a large part of your monthly income goes toward interest and debt payments, you have less money available for your future. That is why understanding which debt deserves the most attention is an essential part of personal finance for beginners.
Why High-Interest Debt Can Hold You Back
Imagine you have ₹50,000 of debt carrying a very high interest rate. Even if you make regular payments, a significant portion of your money may go toward interest instead of reducing the amount you originally borrowed.
This creates a cycle:
Debt → Interest → Higher payments → Less money available for saving → More dependence on credit.
The problem becomes even worse when you continue borrowing while trying to repay the old debt.
Paying expensive debt down can therefore improve your monthly cash flow and give you more control over your money.
Not All Debt Is the Same
A common beginner mistake is treating every type of debt as equally dangerous.
Instead, look at three things:
Interest rate: How expensive is the debt?
Balance: How much do you still owe?
Purpose: What did the borrowed money pay for?
High-interest consumer debt generally deserves more urgent attention because the cost of carrying it can grow quickly.
Lower-cost debt used for an important long-term purpose may require a different strategy. The right decision depends on the interest rate, repayment terms, your cash flow, and your overall financial situation.
Find Your Most Expensive Debt First
Make a simple list of everything you owe.
Debt
Balance
Interest Rate
Priority
Credit card
₹40,000
High
High
Personal loan
₹80,000
Medium
Medium
Lower-rate loan
₹2,00,000
Lower
Lower
This simple comparison can reveal where your money is being lost most quickly.
Do not choose a repayment strategy based only on the size of the balance. A smaller debt with a much higher interest rate can sometimes be costing you more than a larger, lower-rate debt.
Two Popular Ways to Pay Off Debt
Once you know which debts you have, two common approaches are the debt avalanche and the debt snowball.
Debt Avalanche
With the avalanche method, you continue making required payments on all debts while directing extra money toward the debt with the highest interest rate.
After that debt is cleared, you move the extra payment toward the next-highest-rate debt.
Best suited for: people who want to focus primarily on reducing interest costs.
Debt Snowball
With the snowball method, you continue required payments on all debts but direct extra money toward the smallest balance first.
Once that debt disappears, you move the payment toward the next-smallest balance.
Best suited for: people who benefit from quick psychological wins and visible progress.
Neither method is automatically perfect for everyone. The most useful strategy is the one you can consistently follow while meeting all required payments.
Never Ignore Minimum Payments
While aggressively paying one debt, do not simply stop paying your other debts.
Your repayment system should first protect you from missed payments, penalties, and additional financial damage. Then any extra amount can be directed toward your priority debt.
A simple system is:
Pay required amounts on all debts → Choose one priority debt → Put extra money toward it → Clear it → Move to the next.
Should You Stop Saving While Paying Debt?
This is where many beginners make an extreme decision.
They either ignore debt completely while investing, or they put every available rupee into debt and keep absolutely no emergency savings.
A more balanced approach is often better.
Try to maintain at least a basic emergency buffer while aggressively dealing with expensive debt. Otherwise, one unexpected expense could force you to borrow again and undo your progress.
Your exact balance between debt repayment and saving depends on the interest rate, income stability, emergency needs, and financial responsibilities.
Stop the Debt From Coming Back
Paying off debt is only half the solution.
If the behaviour that created the debt continues, the balance can return.
Before using credit for a purchase, ask:
Can I afford this from my current income?
Is this purchase necessary?
Am I borrowing because I genuinely need it or because I want it immediately?
Will the repayment make next month’s budget harder?
If you repeatedly use debt to cover normal living expenses, the underlying problem may be that your spending is too high compared with your income. In that situation, return to the reasons you may be struggling to save money and identify the root cause instead of treating every new loan as a separate problem.
A Simple Debt-Payoff Plan
List every debt with its balance, interest rate, and required payment.
Protect your required payments so you do not create additional problems.
Choose one priority debt using the avalanche or snowball approach.
Put extra money toward that debt whenever your budget allows.
Avoid taking new unnecessary debt while paying the old debt.
Move the freed-up payment toward your next financial priority after the debt is cleared.
Quick Debt Checklist
☐ I know exactly how much I owe.
☐ I know the interest rate on each debt.
☐ I make all required payments on time.
☐ I have chosen a debt-payoff strategy.
☐ I am prioritising expensive debt.
☐ I am avoiding unnecessary new borrowing.
☐ I have a plan for the money freed after a debt is cleared.
Key Takeaway
Debt becomes dangerous when its cost prevents you from moving forward financially. The goal is not simply to become debt-free as quickly as possible at any cost. The goal is to reduce expensive debt while protecting your basic financial stability.
Know what you owe, understand the interest you are paying, choose a repayment strategy, and prevent unnecessary new debt from replacing the old debt.
Know your debt → Prioritise expensive debt → Pay consistently → Avoid new unnecessary borrowing → Redirect the freed-up money.
Rule 4: Save and Invest for Your Future
Saving money gives you financial stability today, but saving and investing for the future helps you prepare for tomorrow.
This is where personal finance starts moving beyond simply “spending less.” Once your basic expenses are under control and expensive debt is being managed, you need a plan for the money you want to keep for future goals.
You do not need to become an investing expert overnight. As a beginner, the first goal is to understand why you are saving, when you will need the money, and how much risk you can realistically handle.
Saving and Investing Are Not the Same Thing
Saving and investing are connected, but they serve different purposes.
Saving
Investing
Usually for short-term or near-term needs
Usually for longer-term goals
Focuses more on safety and accessibility
Focuses on potential long-term growth
Useful for emergencies and planned expenses
Useful for long-term wealth-building
Generally lower risk
Can involve market risk
For example, money you may need next month should not normally be treated the same way as money you do not expect to need for many years.
That simple difference can prevent a common beginner mistake: putting short-term money into something that can fluctuate significantly when you actually need it.
Give Every Saving Goal a Purpose
Instead of simply saying, “I want to save more money,” give your savings a specific job.
You might have separate goals for:
Emergency expenses
Upcoming purchases
Education or skill development
Travel
Major household expenses
Long-term financial independence
A goal becomes easier to act on when you know how much you need and when you need it.
For example, if you want ₹24,000 for a purchase in 12 months:
₹24,000 ÷ 12 = ₹2,000 per month
Now “save ₹24,000” becomes a simple monthly target of ₹2,000.
Start Investing Only After Understanding the Basics
Investing can help your money grow over long periods, but it is not a guaranteed way to make money quickly.
Different investments have different levels of risk. The value of market-linked investments can rise and fall, sometimes significantly.
That is why beginners should avoid choosing an investment simply because someone online says it will give high returns.
Before investing, understand at least these four things:
What are you investing in?
What risks are involved?
How long can you keep the money invested?
What fees or costs are involved?
SEBI’s investor education resources also emphasize understanding investments and their risks before making investment decisions.
Imagine you need ₹50,000 in six months for an important expense. Taking substantial market risk with that money may not make sense because you have very little time to recover if the investment falls.
Now imagine you are investing money for a goal that is decades away. You have much more time to handle short-term market fluctuations.
So instead of asking:
“Which investment gives the highest return?”
Start with:
“When will I need this money, and how much risk can I afford?”
That is a much healthier starting point for a beginner.
Use Compounding to Your Advantage
One reason people invest for the long term is the potential effect of compounding.
Compounding means that returns can themselves generate returns over time. The longer money remains invested and the more consistently you contribute, the more important this effect can become.
For example, suppose you invest ₹2,000 every month for many years. You are not only contributing your own money; over time, investment growth can also contribute to the value of the portfolio.
The exact result will depend on the investment, returns, fees, taxes, and market conditions. There is no guaranteed return.
The important lesson is simple:
Time can be one of an investor’s biggest advantages.
Do Not Wait for the “Perfect” Time to Start
Many beginners keep waiting.
“I will start when my salary increases.”
“I will invest after I understand everything.”
“I will start next year.”
Learning before investing is good. But waiting forever for perfect conditions can become another form of procrastination.
You do not need to know everything before beginning your financial education. Start by understanding basic concepts, building good money habits, and making decisions that match your situation.
What If You Can Only Invest a Small Amount?
Do not compare your beginning with someone else’s portfolio.
If you can invest only ₹500 or ₹1,000 per month right now, that does not make your effort meaningless.
Your first goal is to build the habit of consistently setting money aside while improving your income and financial knowledge.
As your income grows, your contribution can grow too.
The bigger mistake is not starting small. It is believing that small amounts do not matter and therefore never developing the habit at all.
Don’t Invest Money You May Need Soon
This is one of the simplest rules beginners can remember.
If money has an important short-term job, keep its risk appropriate to that job.
For example:
Emergency money → prioritise safety and accessibility.
Long-term goal money → consider suitable long-term investments after understanding the risks.
This separation makes your financial system much easier to manage because every pool of money has a clear purpose.
A Simple Saving and Investing System
You do not need a complicated portfolio or dozens of financial products.
Start with a simple sequence:
Control your monthly spending.
Build an emergency buffer.
Deal with expensive debt.
Define your financial goals.
Decide when you will need each goal’s money.
Choose saving or investing according to the goal and risk.
Contribute consistently and review your plan periodically.
The point is not to create the most complicated financial system. The point is to create one you can actually maintain.
Common Mistakes Beginners Make
1. Chasing High Returns
A higher potential return usually comes with higher risk. “High return with no risk” should immediately make you cautious.
2. Investing Without an Emergency Buffer
If every unexpected expense forces you to sell investments, your long-term plan can become difficult to maintain.
3. Copying Someone Else’s Portfolio
Another person’s income, goals, age, responsibilities, and risk tolerance may be completely different from yours.
4. Constantly Switching Investments
Changing investments every time you hear a new prediction can turn long-term investing into emotional decision-making.
5. Ignoring Fees and Taxes
Returns are not the only thing that matters. Costs and taxes can affect the amount of money you actually keep.
Quick Checklist
☐ I have clear financial goals.
☐ I know when I will need the money for each goal.
☐ I understand the difference between saving and investing.
☐ I understand the basic risks of what I am investing in.
☐ I am not investing emergency money unnecessarily.
☐ I am investing according to my time horizon.
☐ I am focusing on consistency rather than quick profits.
☐ I review my financial plan when my circumstances change.
Key Takeaway
Saving protects your financial stability, while appropriate long-term investing can help your money work toward future goals.
You do not need a huge salary or a complicated investment strategy to begin. Start with clear goals, understand your risk, keep short-term money appropriately safe, and build the habit of putting money aside consistently.
Save for near-term needs → Protect your emergency fund → Understand risk → Invest for appropriate long-term goals → Stay consistent.
Rule 5: Set Clear Financial Goals
Saving money without knowing why you are saving can make personal finance feel frustrating. You may put money aside every month, but after a while you may still wonder, “What am I actually working toward?”
That is why the fifth rule of personal finance is to set clear financial goals.
A financial goal gives your money a direction. Instead of simply trying to “save more,” you know what the money is for, how much you need, and when you want to reach it.
Turn “I Want to Save Money” Into a Real Goal
Compare these two statements:
Goal A: “I want to save more money.”
Goal B: “I want to save ₹60,000 for an emergency fund within the next 12 months.”
Goal B is much easier to act on because it gives you three important pieces of information:
What: ₹60,000
Why: Emergency fund
When: 12 months
Once a goal becomes specific, you can turn it into a monthly plan.
₹60,000 ÷ 12 months = ₹5,000 per month.
Now you are no longer simply “trying to save.” You have a measurable target.
Use Three Time Horizons
You do not need dozens of financial goals. A simple way to organise them is to divide them into three time horizons.
This separation matters because money needed soon should generally be managed differently from money you do not expect to need for many years.
It also prevents a common mistake: treating every financial goal as if it has the same deadline and the same risk requirements.
Give Your Goals a Number and a Deadline
A goal becomes much more useful when you can measure it.
For every important goal, write down:
Target amount
Target date
Current amount
Monthly contribution
Priority
For example:
Goal
Target
Deadline
Monthly Amount
Emergency fund
₹60,000
12 months
₹5,000
Education
₹36,000
12 months
₹3,000
Vacation
₹24,000
12 months
₹2,000
Now your money has a job instead of simply sitting inside a vague “savings” category.
Not Every Goal Should Be a Priority
This is where real-life personal finance becomes important.
You may want to build an emergency fund, buy a new phone, invest for retirement, repay debt, travel, and save for education—all at the same time.
But your income may not be large enough to fully fund everything simultaneously.
That is okay.
Instead of trying to do everything at once, rank your goals.
A simple priority order could be:
Essential financial stability
Emergency protection
Expensive debt reduction
Important short- and medium-term goals
Long-term wealth-building
Optional lifestyle goals
Your exact order can change depending on your circumstances. Someone with expensive debt may need a different priority from someone who has stable income and no significant debt.
Use the “Why” Behind the Goal
A number alone may not keep you motivated.
Knowing why the goal matters to you can make it easier to stay consistent.
For example:
“I want ₹50,000” is just a number.
“I want ₹50,000 so that an unexpected expense does not force me to borrow money” has a clear purpose.
The second version connects the financial target with a real problem you want to solve.
When you feel tempted to spend the money unnecessarily, that purpose can remind you what you are working toward.
Break Big Goals Into Small Wins
A ₹5 lakh goal can feel overwhelming when you look at the entire number.
Each milestone gives you something measurable to celebrate.
This is particularly useful when the final goal may take several years. You do not need to mentally carry the entire target every day. Focus on the next milestone.
What If Your Income Is Too Small for Your Goals?
This is a situation many beginners face.
You calculate your goals and realise that the required monthly amount is higher than what you can realistically save.
For example:
Required monthly saving = ₹10,000
Affordable monthly saving = ₹4,000
That does not mean the goal is impossible.
You have several options:
Extend the deadline.
Reduce the target amount.
Temporarily lower the priority of another goal.
Reduce unnecessary expenses.
Look for ways to increase income.
Combine several of these approaches.
A realistic goal that takes longer is usually better than an unrealistic goal that makes you give up after two months.
Keep Planned Goals Separate From Emergency Money
Suppose you are saving for a vacation and also building an emergency fund.
If you keep both amounts in one mental bucket, it becomes easy to spend emergency money on the vacation—or postpone your emergency savings because the vacation feels more exciting.
Give different goals different names and, where practical, separate them into different savings categories or accounts.
This simple separation makes it easier to see what money is actually available for each purpose.
Review Your Goals When Your Life Changes
A financial goal is not a contract that can never change.
Your income may increase. Your expenses may change. You may get married, move to another city, change jobs, start a business, or take on new responsibilities.
When your situation changes, your goals should be reviewed too.
A good habit is to review your major financial goals periodically and ask:
Is this goal still important?
Has the target amount changed?
Is the deadline still realistic?
Am I contributing enough?
Has another goal become more important?
Changing a goal does not mean you failed. It means your financial plan is adapting to your actual life.
A Simple Goal-Setting System
You can turn this entire rule into a simple five-step process:
Choose the goal. Decide exactly what you want your money to accomplish.
Put a number on it. Estimate the amount you will need.
Choose a deadline. Decide when you want to reach it.
Calculate the monthly contribution. Divide the required amount by the available time, while adjusting for your current savings.
Review and adjust. Increase, decrease, or extend the plan when your circumstances change.
For example:
Goal: ₹1,20,000
Current savings: ₹20,000
Remaining: ₹1,00,000
Time: 20 months
Required average contribution: ₹5,000 per month
Now the goal is no longer abstract. You know exactly what needs to happen.
Quick Goal-Setting Checklist
☐ I know what I am saving or investing for.
☐ Each important goal has a target amount.
☐ Each goal has a realistic deadline.
☐ I know how much I need to contribute regularly.
☐ I have prioritised my goals.
☐ I have separated emergency money from planned spending.
☐ I review my goals when my circumstances change.
Key Takeaway
Money becomes easier to manage when it has a clear destination.
You do not need twenty different financial goals. Start with the goals that matter most, give each one a number and a deadline, and turn the large target into smaller monthly actions.
Choose the goal → Give it a number → Set a deadline → Prioritise it → Take small consistent steps → Review and adjust.
The next step is to make sure your financial plan does not depend only on your current income. That brings us to Rule 6: Increase Your Income and Protect Your Financial Progress.
Rule 6: Increase Your Income and Protect Your Financial Progress
There is a limit to how much you can improve your finances by cutting expenses alone. You can cancel subscriptions, reduce unnecessary spending, and create a strict budget—but if your income stays too low while your responsibilities keep increasing, eventually you may feel stuck.
That is why an important part of personal finance for beginners is learning how to increase your earning power while protecting the financial progress you have already made.
The goal is not simply to earn more money and then spend more money. The real goal is to create a gap between what you earn and what you need, then use that gap to build savings, reduce debt, and invest for the future.
Why Increasing Income Matters
Imagine two people.
Person A earns ₹20,000 per month and spends ₹19,500.
Person B earns ₹40,000 per month and spends ₹25,000.
Person B has much more room to save, invest, handle emergencies, and work toward financial goals.
This does not mean earning more automatically makes someone financially successful. Someone can earn ₹1 lakh and still spend ₹1.1 lakh. The important number is the gap between income and spending.
Income − Essential and controlled spending = Money available for financial progress
Increasing that gap gives your financial plan more room to breathe.
Do Not Depend on Only One Income Strategy
When people hear “increase your income,” they often immediately think about starting a side hustle.
But there are several ways to improve your earning power:
Increase your main income: improve your skills, take on better responsibilities, negotiate when appropriate, or move toward better-paying work.
Add a second income stream: freelance work, services, digital products, or another legitimate source of income.
Monetise a useful skill: writing, design, programming, editing, research, teaching, or another skill people are willing to pay for.
Reduce income leaks: make sure money is not disappearing through unnecessary fees, poor financial decisions, or repeated avoidable expenses.
You do not need to pursue all of these at once. Choose the option that fits your current skills, available time, and situation.
Build Skills That Increase Your Earning Power
A useful long-term approach is to treat some of your time and money as an investment in your ability to earn more.
For example, learning a skill that helps you qualify for better work can have a much larger long-term effect than saving a few hundred rupees by cutting every small expense.
Ask yourself:
What skill could make me more valuable in my current work?
What skill could help me move into a better-paying role?
What service could I realistically offer to other people?
What skill can I practise consistently with the time I have available?
The best skill is not necessarily the trendiest one. It is the one you can actually learn, practise, demonstrate, and eventually use to create value.
Turn Extra Income Into Financial Progress
Suppose your income increases by ₹10,000 per month.
You now have a choice.
You could increase your lifestyle by the full ₹10,000, or you could use part of the increase to improve your financial position.
For example:
₹3,000 → emergency savings
₹3,000 → debt repayment
₹2,000 → long-term investing
₹2,000 → lifestyle improvement
The exact numbers do not matter. The principle does.
When income increases, do not automatically allow spending to increase by the same amount.
Give your extra income a job before it disappears into lifestyle spending.
Watch Out for Lifestyle Inflation
Lifestyle inflation happens when your spending rises as your income rises.
You get a raise, so you upgrade your phone. Then you move to a more expensive apartment. Then you start eating out more often. Soon your salary is higher, but your financial situation has barely improved.
This can create a frustrating situation where someone earns significantly more than before but still says:
“I don’t know where my money goes.”
You do not have to live exactly the same way forever. Enjoying some of your increased income is perfectly reasonable. The problem is allowing every income increase to become a permanent increase in expenses.
A useful rule is:
Let your lifestyle improve slower than your income.
That creates room for your savings, investments, and financial security to grow.
What If You Have Very Little Time?
You do not need to create a complicated second business after working all day.
If your available time is limited, focus on one realistic improvement instead of trying five different income ideas simultaneously.
For example:
Current situation: 1 hour available each evening.
Bad approach: Start freelancing, YouTube, blogging, trading, dropshipping, and five courses at the same time.
Better approach: Choose one skill, practise it consistently, create a few examples of your work, and gradually look for opportunities to earn from it.
Financial progress does not require doing everything. It requires doing the right things consistently.
Protect Your Higher Income
Earning more is useful only if the additional money actually improves your financial position.
Once your income rises, protect the progress by keeping a simple system:
Increase your savings rate.
Pay down expensive debt.
Continue building your emergency reserve.
Invest appropriately for long-term goals.
Allow some money for enjoyment.
This balance matters. A financial plan that gives you no room to enjoy your money can become so restrictive that you eventually abandon it.
A Simple Income-Growth Experiment
Instead of thinking about increasing your income as a huge life-changing project, try a 90-day experiment.
Days 1–30: Identify one skill that could increase your earning potential and start learning or improving it.
Days 31–60: Practise the skill and create something that demonstrates what you can do.
Days 61–90: Look for realistic opportunities to use that skill—additional work, freelance projects, clients, better job opportunities, or another legitimate route.
You may not double your income in 90 days. That is not the point.
The point is to create a repeatable process for increasing your earning ability instead of waiting for your income to magically improve.
When Your Income Increases, Ask These Questions
Before changing your lifestyle after a raise or new income source, stop for a moment and ask:
How much of this additional income will improve my financial security?
Do I have expensive debt that should receive more money?
Is my emergency fund strong enough?
What long-term goal could this money accelerate?
How much can I enjoy without damaging my financial plan?
These questions help you enjoy progress without accidentally spending all of it.
Quick Checklist
☐ I know how much money I earn each month.
☐ I know how much of my income is actually available after essential expenses.
☐ I am working on at least one skill that can improve my earning power.
☐ I am not depending entirely on lifestyle cuts to improve my finances.
☐ I avoid automatically increasing my lifestyle whenever my income increases.
☐ I give extra income a specific purpose.
☐ I balance saving, debt repayment, investing, and reasonable enjoyment.
☐ I am focusing on one realistic income-growth opportunity at a time.
Key Takeaway
Cutting unnecessary expenses can help you create financial breathing room, but increasing your earning power can expand that room much further.
The goal is not to chase money endlessly. It is to become more valuable, increase your income over time, and make sure that higher income actually improves your financial life.
Increase your skills → Increase your earning potential → Control lifestyle inflation → Give extra income a purpose → Build long-term financial strength.
Once your income, spending, saving, and investing systems are working together, the final rule is about bringing everything into one simple financial system you can maintain for years.
Rule 7: Create a Simple Financial System and Review It Regularly
Knowing the rules of personal finance is useful, but knowing them is not enough. The real difference comes from turning those rules into a system that works in your everyday life.
You can know how to budget, save, invest, manage debt, and increase your income—but if all of these things are happening randomly, your money can still feel difficult to control.
The seventh and final rule is therefore simple: create a financial system you can actually follow and review it regularly.
Put Your Money on a Simple Path
Think of your personal finances as a series of steps rather than seven completely separate rules.
Earn → Plan → Spend → Save → Protect → Invest → Review → Improve
Each part has a job.
Earn: Bring money into your financial system.
Plan: Decide where your money needs to go.
Spend: Cover your needs without consistently spending more than you earn.
Save: Build money for emergencies and planned goals.
Protect: Reduce the damage unexpected events can cause.
Invest: Put appropriate long-term money to work according to your goals and risk.
Review: Check what is working and what is not.
Improve: Make small changes as your income, expenses, and goals change.
This is much easier to maintain than trying to remember dozens of financial rules every day.
Give Every Part of Your Income a Job
When money comes into your account, you should have a basic idea of where it needs to go before you start spending it.
For example, your monthly income might be divided between:
Essential living expenses
Debt payments
Emergency savings
Financial goals
Long-term investing
Personal and entertainment spending
The exact percentages will depend on your income and circumstances. There is no universal formula that works perfectly for everyone.
The important idea is to give your money a purpose before your spending decides its purpose for you.
Automate What You Can
One of the easiest ways to make a financial system easier is to remove unnecessary decisions.
If you know that you want to save ₹3,000 every month, you can arrange an automatic transfer when your bank or financial service allows it.
Instead of thinking every month, “Should I save this month?” the system helps make saving part of your normal routine.
The same principle can apply to recurring bill payments and other predictable financial commitments.
Automation does not replace financial awareness. You still need to check your accounts and make sure the amounts are appropriate.
Use a Weekly Money Check
You do not need to spend hours analysing your finances every day.
A short weekly check can be enough to catch problems before they become bigger.
Once a week, look at:
How much money you spent
Whether any unusual expense appeared
Your upcoming bills
Your current account balance
Whether you stayed within your spending plan
This is not about judging yourself for every small purchase. It is about staying aware.
If you notice that you spent too much in one category, you can adjust early instead of discovering the problem at the end of the month.
Do a Deeper Monthly Review
Your weekly check keeps you aware. Your monthly review helps you make decisions.
At the end of each month, ask yourself:
Did I spend more or less than I earned?
Did my savings increase?
Did my debt decrease?
Did I invest according to my plan?
Did an unexpected expense change my budget?
Which spending category needs attention?
What worked well this month?
What should I change next month?
Keep the review simple. You are looking for patterns, not trying to create a complicated financial report.
Use a One-Page Personal Finance Dashboard
If you want to make your system even easier, keep your most important numbers in one place.
Metric
What to Track
Monthly income
Money coming in
Essential expenses
Money required for basic living
Debt
Total outstanding balance
Emergency fund
Current emergency savings
Financial goals
Progress toward important targets
Investments
Long-term portfolio value and contributions
Net worth
Assets minus liabilities
You do not need to check investment values every day. The purpose of a dashboard is to understand your overall direction.
Measure Progress With Net Worth, Not Just Income
A higher salary is useful, but income alone does not tell you whether your financial situation is improving.
Consider two people who both earn ₹50,000 per month.
One has ₹5 lakh in savings and investments with manageable debt. The other has large debt and almost no savings.
Their incomes are identical, but their financial positions are very different.
This is why tracking net worth can be useful.
Net worth = Total assets − Total liabilities
Assets can include savings, investments, and other things of financial value. Liabilities are amounts you owe.
Your net worth does not need to increase every single month. Markets fluctuate and life creates unexpected expenses. What matters is the long-term direction and whether your financial decisions are improving your position over time.
Make Your Financial System Flexible
A good financial system should not collapse because one month goes badly.
Maybe your income is lower than expected. Maybe your phone breaks. Maybe you have an urgent family expense. Maybe your work situation changes.
Your plan should have enough flexibility to handle real life.
For example, during a difficult month you may temporarily reduce optional spending or investing contributions while protecting essential expenses and required debt payments.
When your situation improves, you can return to your normal plan.
Flexibility is not failure. It is part of a realistic financial system.
Protect the Progress You Have Built
As your finances improve, protecting that progress becomes increasingly important.
That can mean maintaining an emergency fund, avoiding unnecessary high-cost debt, using appropriate insurance where relevant, keeping important financial documents organised, and being careful about scams or unrealistic investment promises.
Investor.gov, the U.S. Securities and Exchange Commission’s investor education website, also provides resources on avoiding investment fraud and making informed investment decisions.
The specific protections you need will depend on your country and personal circumstances, so treat this as a general principle rather than a one-size-fits-all checklist.
Build a Financial Routine You Can Maintain
You do not need to think about money constantly.
A simple routine might look like this:
Every payday: Check income, move planned savings, and cover important obligations.
Every week: Review spending and upcoming expenses.
Every month: Review savings, debt, goals, and cash flow.
Every few months: Review your financial goals and make adjustments.
Once a year: Take a broader look at your income, expenses, investments, insurance, debt, and long-term goals.
This routine turns personal finance from something you constantly worry about into something you manage systematically.
What to Do When You Make a Financial Mistake
You will probably make some.
You may overspend one month. You may buy something you later regret. You may choose an investment that does not work out as expected. You may miss a savings target.
The important thing is not to turn one mistake into a permanent habit.
Instead, ask:
What happened?
Why did it happen?
Was there a weakness in my system?
What can I change so it is less likely to happen again?
For example, if you repeatedly overspend because you use your main account for both bills and entertainment, the solution may not be “I need more discipline.” A better solution might be to separate spending money from money reserved for important obligations.
Good financial systems reduce the amount of willpower you need.
Put All Seven Rules Together
Now the seven rules can work as one system:
Spend less than you earn so you create financial breathing room.
Build an emergency fund so unexpected expenses do not immediately destroy your budget.
Pay off high-interest debt so expensive interest does not keep consuming your income.
Save and invest for the future so your money can support long-term goals.
Set clear financial goals so you know what your money is working toward.
Increase your income and protect your progress so your financial capacity can grow.
Create a simple financial system and review it regularly so all the other rules continue working together.
Notice that these rules are connected.
Spending less creates room. That room helps you build an emergency fund. A stronger emergency fund reduces the need for expensive debt. Lower debt gives you more money for goals and investing. Increasing your income can accelerate the entire process. Regular reviews keep the system from falling apart when life changes.
Your Complete Personal Finance Routine
If you are a beginner and all of this feels like a lot, do not try to change everything tomorrow.
Start with the basics:
Know your monthly income.
Know where your money is going.
Spend less than you earn whenever possible.
Build an emergency buffer.
Control expensive debt.
Set specific financial goals.
Learn before investing.
Work on increasing your earning power.
Review your money regularly.
Then improve one part at a time.
Your financial life does not need to become perfect. It needs to become more organised, more intentional, and more resilient over time.
Final Checklist: Are You Following the 7 Rules?
☐ I spend less than I earn or have a clear plan to fix the gap.
☐ I am building an emergency fund.
☐ I know what debts I owe and which ones are expensive.
☐ I save and invest according to my goals and risk.
☐ My important financial goals have amounts and deadlines.
☐ I am working on increasing my earning potential.
☐ I review my finances regularly.
☐ I adjust my plan when my circumstances change.
☐ I focus on progress instead of trying to become financially perfect.
Final Takeaway
The seven rules of personal finance are not seven separate tricks for becoming rich. They are a framework for making better decisions with the money you have today while building a stronger financial future.
You do not need a high salary to start. You do not need to understand every investment product. And you do not need to change your entire life overnight.
Start with one improvement. Then build the next one on top of it.
Earn → Spend intentionally → Save → Protect → Reduce expensive debt → Invest appropriately → Increase your income → Review → Repeat.
That is how personal finance becomes a system rather than a collection of random money tips.
The 7 rules of personal finance are to spend less than you earn, build an emergency fund, manage expensive debt, save and invest for the future, set clear financial goals, increase your income, and create a simple financial system that you review regularly. Together, these rules help you manage your money and build long-term financial stability.
What is the most important rule of personal finance for beginners?
For beginners, one of the most important rules is to spend less than you earn. This creates financial breathing room that can be used to build an emergency fund, reduce expensive debt, save for important goals, and invest appropriately for the future.
How can I start managing my money if I have a low income?
If you have a low income, start by understanding exactly how much you earn and where your money goes. Focus on essential expenses, avoid unnecessary debt, build a small emergency buffer, and set realistic savings goals. At the same time, work on developing skills or finding opportunities that can gradually increase your income.
How can I build good financial habits and become financially stable?
Build good financial habits by creating a simple system instead of relying only on willpower. Track your spending, save regularly, set specific financial goals, manage debt, invest according to your goals and risk, and review your finances regularly. Consistent small improvements can gradually strengthen your financial position.
conclusion
Personal finance does not have to be complicated. The 7 rules of personal finance give you a simple framework to take control of your money: spend less than you earn, build an emergency fund, manage expensive debt, save and invest for the future, set clear financial goals, increase your income, and review your financial system regularly.You do not need a high income or a perfect financial plan to start. Begin with the problem that matters most right now and improve one part of your finances at a time.The goal is not to become financially perfect overnight. It is to build better money habits, protect yourself from financial setbacks, and gradually create more freedom and stability.Start small, stay consistent, and let your financial system improve as your income, goals, and life change.
Hi, I’m Asif Khan, the voice behind paisakmao.de. For the past two years, I’ve been blogging about financial education, income skills, and mindset development for students and young minds. My mission is to empower every youth with financial literacy and practical money-making skills at an early age. Through paisakmao.de, I share actionable guides for students to start earning early, money wisdom that schools don’t teach, and mindset lessons from successful people and modern psychology. Whether you’re a teenager looking to earn your first income or a student exploring side hustles, you’re in the right place. Financial freedom begins with the right mindset and the right knowledge. Let’s grow, earn, and evolve together — welcome to the movement!
Managing money can feel confusing when you are just starting. You may earn money but still wonder where it goes, struggle to save consistently, or feel unsure about budgeting, debt, emergency funds, and investing.
The good news is that personal finance does not have to be complicated. You do not need a high income, advanced financial knowledge, or a perfect plan to begin. You only need to understand your current situation, make a few practical decisions, and build better money habits over time.
This Personal Finance for Beginners guide will help you understand the essential steps needed to take control of your money. You will learn how to track your income and expenses, create a realistic budget, build savings, prepare for emergencies, manage debt, and start investing according to your financial goals.
In this guide, we will break everything down into 10 practical steps. Each step includes clear explanations, realistic examples, and simple actions you can apply in your daily life. Whether you are a student, a beginner, a salaried employee, or someone trying to improve your financial situation, this guide will help you build a stronger financial foundation and create a clear plan for your money in 2026.
Step 1: Understand Your Current Financial Situation
Before creating a budget, building an emergency fund, paying off debt, or investing, you need to understand where you currently stand with your money. Many people know their monthly salary, but they do not know exactly where that money goes. They may feel that they are always short of money, even when their income seems reasonable.
For personal finance beginners, understanding your current financial situation is the foundation of good money management. You do not need advanced financial knowledge, expensive software, or complicated calculations. A notebook, a spreadsheet, your bank statements, and your UPI transaction history are enough to begin.
Your goal is not to judge yourself or feel guilty about past spending. The goal is to understand your financial reality. Once you know how much you earn, spend, save, and owe, you can create a financial plan that fits your actual life instead of following advice that may not work for your situation.
Start by reviewing these five areas:
Your monthly income
Your regular and flexible expenses
Your savings and emergency money
Your loans and other debts
Your monthly cash flow
SEBI explains that documenting income and expenses can help people understand their financial position, control spending, manage debt, save money, and work toward financial goals. You can read its official guide on financial goals and budgeting for additional financial education.
1. Calculate Your Actual Monthly Income
The first step is to calculate the money you actually receive during a normal month. Include your salary, wages, freelance income, business income, commissions, part-time earnings, rental income, or other regular sources.
If you have a fixed job, use your take-home income, not only the salary written in your employment agreement. Take-home income is the amount that actually reaches your bank account after deductions.
For example, if your monthly salary is ₹30,000 but ₹2,000 is deducted before payment, your usable monthly income is ₹28,000. Your budget should be based on ₹28,000 because that is the amount available for expenses, savings, and financial goals.
Income Source
Monthly Amount
Salary
₹25,000
Part-time work
₹3,000
Freelance work
₹2,000
Total Monthly Income
₹30,000
If your income changes every month, do not create your financial plan using your highest-income month. Review your income from the previous three to six months and calculate a realistic average. You can also use your lowest normal monthly income as a safer starting point for essential expenses.
If your earnings are irregular, read our detailed guide on how to budget with an irregular income. It explains how to calculate a minimum income level, prioritize essential expenses, and manage months when earnings are lower.
2. Track Your Monthly Expenses Before Creating a Budget
After calculating your income, review where your money is going. Do not depend only on memory because small expenses are easy to forget. A ₹100 snack, a ₹200 online purchase, or several small UPI payments may not seem important individually, but together they can affect your monthly savings.
Review your bank statements, UPI history, cash spending, and recurring payments. Record what you actually spent—not what you think you should have spent. An honest record gives you a useful starting point for improving your financial habits.
A practical way to organize expenses is to divide them into three groups.
Essential Expenses
Rent or housing
Groceries and basic food
Electricity, phone, and internet bills
Transport
Healthcare and medicines
Education expenses
Financial Commitments
Loan EMIs
Credit-card payments
Insurance premiums
Other required payments
Flexible Expenses
Eating out
Entertainment
Online shopping
Subscriptions
Impulse purchases
Optional lifestyle spending
You do not have to remove every flexible expense. The purpose of expense tracking is to understand your choices and identify spending that does not provide enough value. A good personal budget should be realistic and sustainable, not so restrictive that you abandon it after a few weeks.
SEBI’s official guide on managing income and expenses also recommends listing income sources, categorizing expenses, tracking spending, and allocating money toward savings and investments.
If you receive a regular salary, our Day 1 to Day 30 salary management plan can help you organize your income after payday and divide money between bills, savings, goals, and personal spending.
3. Calculate Your Monthly Cash Flow
Your monthly cash flow shows whether you are earning more than you spend. It is one of the simplest ways to understand your current financial health.
Monthly Cash Flow = Total Monthly Income − Total Monthly Expenses
Financial Item
Amount
Total monthly income
₹30,000
Essential expenses
₹17,000
Loan payments
₹4,000
Flexible expenses
₹5,000
Money Remaining
₹4,000
In this example, ₹4,000 remains after all monthly expenses. This amount could be used for savings, an emergency fund, additional debt repayment, investing, or another financial goal.
If your result is negative, it means your expenses are higher than your income. This is not a reason to panic. It is a signal that your current money system needs adjustment. You may need to reduce avoidable expenses, review recurring payments, increase income, or change the order of your financial priorities.
Do not try to fix everything at once. First, identify the largest reason for the negative cash flow. A single change—such as reducing an unnecessary recurring expense—may be more useful than making many small changes that are difficult to maintain.
4. Review Your Savings and Emergency Fund
Next, calculate how much money you have saved and how much is available for unexpected expenses. Include money in your savings account, a separate emergency fund, or another easily accessible account.
Ask yourself:
How much money can I access quickly if an emergency occurs?
Could I pay for an urgent medical bill or necessary repair?
How many months of essential expenses could my savings cover?
Is my emergency money separate from my everyday spending money?
For example, if your essential monthly expenses are ₹15,000 and you have ₹30,000 in accessible savings, your savings could cover approximately two months of essential expenses.
An emergency fund is generally meant for unexpected costs, such as urgent repairs, medical expenses, or a temporary loss of income. The amount you need depends on your income stability, responsibilities, expenses, and personal situation. The Consumer Financial Protection Bureau’s emergency-fund guide explains why emergency savings can reduce the need to depend on loans or credit when an unexpected expense occurs.
If you are starting from zero, you do not need to save a large amount immediately. You could begin with ₹500 or ₹1,000 per month and increase the amount when your income allows. Small, consistent savings can still create a useful financial cushion over time.
For practical ideas to create more room in your budget, read our guide on how to save money fast in 30 days. It includes realistic strategies for reducing unnecessary spending without making your daily life unnecessarily difficult.
5. List Your Debts and Monthly Payments
If you have a personal loan, education loan, credit-card balance, borrowed money, or another financial obligation, write down the details clearly. Avoiding debt information may temporarily feel easier, but it makes financial planning more difficult.
For each debt, record:
Total amount remaining
Interest rate, if known
Required monthly payment
Payment due date
Remaining repayment period
Debt
Amount Remaining
Monthly Payment
Personal loan
₹50,000
₹3,000
Credit-card balance
₹10,000
₹1,000
Once you can see all your debts in one place, you can compare the balances, interest rates, and payment requirements. Some people prefer paying the smallest debt first to build motivation, while others focus on higher-interest debt to reduce interest costs. The right approach depends on your financial situation and ability to make payments consistently.
Before taking a new loan, understand the total repayment responsibility, interest cost, fees, and repayment period. Borrowing can create long-term pressure if the monthly payment does not fit your income. For additional investor education, SEBI provides guidance on prioritizing needs, wants, and financial priorities.
6. Review Your Financial Habits and Spending Patterns
Your financial numbers show what is happening, but your habits often explain why it is happening. Two people with similar incomes may have very different financial results because their spending, saving, and decision-making habits are different.
Ask yourself:
Do I check my account balance before spending?
Do I save at the beginning of the month or only save what is left?
Do I make unplanned purchases because of discounts or social pressure?
Do I know how much I spend on subscriptions?
Do I review my finances regularly?
Do I compare prices before making a large purchase?
Good financial habits are usually built through small actions repeated over time. You do not need to change everything in one day. For example, reviewing your expenses every Sunday may help you notice problems before they become larger.
Students and young adults can also read our guide on financial habits every college student should develop. Many of these habits can help beginners build a stronger relationship with money before taking bigger financial decisions.
7. Use Financial Tools Carefully
Budgeting apps, expense trackers, banking tools, and AI-powered finance tools can help you organize expenses, monitor spending, set reminders, and understand financial information. However, a tool cannot automatically make the right financial decision for you. It should support your judgment, not replace it.
Before connecting an app to your financial accounts, review its privacy policy, permissions, security practices, and data-sharing rules. Avoid entering sensitive banking information into tools that you do not trust.
To explore useful options, read our guide on the best AI tools to manage personal finances. Choose a tool based on your actual needs instead of downloading many apps that you may never use.
A Simple Real-Life Example
Rahul earns ₹30,000 per month. He believes that he should be able to save ₹8,000, but his bank balance is almost empty before every payday.
After reviewing one month of transactions, Rahul discovers that ₹2,000 goes toward food delivery, ₹1,200 goes toward subscriptions he rarely uses, and ₹1,500 goes toward unplanned online purchases. None of these expenses seemed very large on their own, but together they were reducing his ability to save.
Rahul does not remove every enjoyable expense. Instead, he cancels unused subscriptions, sets a monthly limit for food delivery, and waits 24 hours before making non-essential purchases. These changes improve his monthly cash flow without making his budget too restrictive.
The lesson is simple: you cannot improve a financial problem until you understand what is causing it.
Common Mistake: Trying to Fix Everything at Once
A common mistake among personal finance beginners is trying to cut every expense, repay all debt, save a large amount, and start investing at the same time. This can create an unrealistic plan that is difficult to follow.
Instead, understand your current position first. Then choose one or two improvements that can make the biggest difference. For example, you could cancel one unused subscription, save ₹1,000 automatically, or pay an additional ₹500 toward a high-interest debt.
Review your bank statements, UPI history, and cash spending.
Track your expenses for at least 30 days.
Separate essential expenses from flexible spending.
Calculate your monthly cash flow.
Write down your savings and available emergency money.
List every debt and monthly payment.
Choose one financial habit to improve this month.
Quick Takeaway
Understanding your income, expenses, savings, debt, financial habits, and monthly cash flow gives you a strong foundation for managing money. You do not need to solve every financial problem today. First, understand your starting point. Once your numbers are clear, you can create realistic goals and build a financial plan that fits your actual situation.
Now that you understand your current financial position, the next step is to create a realistic budget that helps you control spending, protect your priorities, and make steady progress toward your financial goals.
2. Build an Emergency Fund to Protect Your Financial Future
Life does not always follow your monthly budget. A sudden medical bill, phone repair, job loss, family emergency, or unexpected travel expense can create financial pressure without warning. That is why building an emergency fund is one of the most important personal finance tips for beginners in 2026.
An emergency fund is money kept separately for genuine unexpected expenses. It is not money for shopping, entertainment, a planned vacation, or buying something just because it is on sale. Its main purpose is to give you financial breathing room when life becomes expensive unexpectedly.
According to the Consumer Financial Protection Bureau’s emergency fund guide, even a small amount of emergency savings can provide financial security and help people recover from unexpected expenses without immediately depending on credit or loans.
Why an Emergency Fund Matters in Personal Finance
Imagine that Rahul earns ₹25,000 per month. He spends almost all of his income and keeps no money aside. One day, his phone suddenly stops working, and the repair costs ₹6,000. Because Rahul has no emergency savings, he may need to borrow money, use a credit card, or delay another important payment.
Now imagine that Rahul had saved ₹500 every week. After several months, he would have built a useful financial cushion. The repair would still be inconvenient, but it would not automatically turn into debt.
This is the real value of an emergency fund. It may not make you rich, but it can stop a small financial problem from becoming a much larger one.
How Much Should You Keep in an Emergency Fund?
There is no single emergency-fund amount that is perfect for everyone. Your target should depend on your income, monthly essential expenses, job stability, family responsibilities, and how predictable your earnings are.
Financial Situation
Possible Emergency-Fund Goal
Student or beginner with limited income
Start with ₹5,000–₹10,000
Person with a stable monthly salary
Build 1–3 months of essential expenses
Freelancer or person with irregular income
Consider 3–6 months of essential expenses
Person supporting a family
Build a larger cushion based on responsibilities
For example, if your essential monthly expenses are ₹15,000, you could first aim for ₹15,000. After reaching that goal, you could gradually work toward ₹30,000 or more. You do not need to build the entire amount in one month.
If your income changes from month to month, your savings plan should also be flexible. You can learn a practical system for handling changing earnings in our guide on how to budget with an irregular income.
Start Small Instead of Waiting for the “Perfect Time”
Many people believe they must earn a high salary before they can start saving. In reality, waiting for the perfect income can delay the habit for years. A small and consistent contribution is often more useful than an ambitious plan that you stop after two weeks.
Save ₹20 or ₹50 whenever you receive money.
Set aside ₹100–₹500 every week if your budget allows.
Save a percentage of extra income, bonuses, or freelance payments.
Increase your contribution when your income grows.
For example, saving ₹50 per day could build approximately ₹1,500 in one month. Saving ₹500 per week could create around ₹26,000 in one year, before considering any interest. The amount may look small at first, but consistency creates momentum.
If saving feels difficult even when you earn a reasonable income, first identify where your money is quietly disappearing. Our article on why you can’t save money even with a good salary explains hidden spending patterns and practical ways to improve your savings.
Keep Your Emergency Money Separate
Keeping emergency money in the same account you use for daily spending can make it easier to spend accidentally. A separate savings account or another clearly labelled account can help create a mental boundary between everyday money and emergency money.
You could name the account “Emergency Fund” and avoid connecting it to routine shopping payments. The money should remain accessible when a genuine emergency happens, but it should not be so convenient that you spend it on ordinary wants.
Before choosing where to keep your emergency savings, consider three things:
Safety: The money should not be exposed to unnecessary risk.
Accessibility: You should be able to access it when a real emergency occurs.
Stability: The value should not fluctuate heavily when you may need the money soon.
Emergency money is different from long-term investment money. Investments may rise or fall in value, while an emergency fund is designed primarily for financial stability and quick access.
Use Your Emergency Fund Only for Real Emergencies
Before withdrawing money, ask yourself:
“Is this expense unexpected, necessary, and difficult to manage without using my emergency savings?”
A sudden medical expense, urgent home repair, essential vehicle repair, or temporary loss of income may qualify. A planned holiday, new gadget, festival shopping, or a discount offer usually does not.
After using the fund, begin rebuilding it gradually. You do not need to replace the entire amount immediately. Return to your normal saving routine and increase contributions when possible.
A Simple 30-Day Emergency-Fund Action Plan
Week
Action
Week 1
Calculate your essential monthly expenses.
Week 2
Open or choose a separate place for emergency savings.
Week 3
Save your first amount, even if it is only ₹100 or ₹500.
Week 4
Review your spending and choose a realistic monthly saving amount.
For a broader step-by-step money system, you can also read our guide on financial planning for beginners. It explains how budgeting, saving, debt management, and long-term goals can work together.
Key Takeaway
Building an emergency fund is not about saving a huge amount overnight. It is about creating a financial safety net one small contribution at a time. Start with a realistic target, keep the money separate, use it only for genuine emergencies, and rebuild it after you use it.
Among the most practical personal finance tips for beginners, this habit can reduce financial stress and help you avoid unnecessary debt when unexpected expenses appear.
Next: Once you have started building a financial safety net, the next step is to understand how to reduce expensive debt without damaging your monthly budget.
Step 3: Pay Off High-Interest Debt and Avoid Unnecessary Borrowing
Debt can help you pay for an important need, such as education, a home, or an emergency. However, debt can become difficult to manage when monthly payments take a large part of your income or when high interest causes the total amount to grow over time.
For personal finance beginners, learning how to manage debt is an important part of building financial stability. The goal is not always to become debt-free overnight. The goal is to understand what you owe, make payments on time, reduce expensive debt strategically, and avoid borrowing for expenses you may not be able to afford.
Before choosing a repayment strategy, create a clear list of every loan, credit-card balance, EMI, or other amount you owe. When all your debt is visible in one place, it becomes easier to decide what to pay first and how much you can realistically contribute each month.
Understand the True Cost of Your Debt
Many people focus only on the monthly EMI. However, the EMI does not always show the complete cost of borrowing. You should also understand the interest rate, repayment period, processing fees, late-payment charges, and total amount you may repay.
For example, two loans may have the same monthly payment but different interest rates or repayment periods. The loan with the higher interest rate may cost more over time, even if the monthly payment appears manageable.
Debt Type
Amount Remaining
Interest Rate
Minimum Monthly Payment
Credit-card balance
₹20,000
36% per year
₹2,000
Personal loan
₹50,000
16% per year
₹3,000
Education loan
₹1,50,000
9% per year
₹4,000
In this example, the credit-card balance has the highest interest rate. If all minimum payments are affordable and current, paying extra toward the highest-interest debt may reduce interest costs. However, your repayment plan should consider your complete financial situation.
Before borrowing, review the repayment responsibility carefully. SEBI’s official guide on thinking before you borrow money explains that borrowing creates financial responsibilities and should not be used for avoidable or unnecessary expenses.
Create a Complete Debt List
Write down every debt in one place. Do not rely only on memory because it is easy to forget due dates, fees, or small balances.
Your debt list should include:
The name of the lender
The total amount remaining
The interest rate
The minimum monthly payment
The payment due date
The remaining repayment period
Any late-payment fees or penalties
Once your list is complete, calculate the total amount you pay toward debt every month. Compare that number with your monthly take-home income and essential expenses.
If you have not created a clear monthly spending plan yet, review Step 2: Create a Realistic Budget before increasing your debt payments. A repayment plan should fit your budget so that you can continue paying consistently.
Choose a Debt-Repayment Method
Two popular debt-repayment methods are the debt avalanche and the debt snowball. Both can work, but they focus on different priorities.
Method 1: The Debt Avalanche
With the debt avalanche method, you continue making the required minimum payments on all debts. Any extra money is directed toward the debt with the highest interest rate.
After the highest-interest debt is paid off, you move the extra payment to the debt with the next-highest interest rate.
With the debt snowball method, you continue making the required payments on all debts and direct extra money toward the smallest balance first.
After paying off the smallest debt, you add that payment amount to the next-smallest debt. This creates a series of small wins that may help some people stay motivated.
The debt snowball may not always minimize total interest, but motivation can be valuable if it helps you continue the repayment plan.
Method
Priority
Possible Benefit
Debt avalanche
Highest interest rate first
May reduce total interest costs
Debt snowball
Smallest balance first
May create faster motivational wins
Choose the method that you can follow consistently. A mathematically efficient plan is less useful if it is too difficult to maintain.
Always Pay Required Amounts on Time
Even when you are focusing extra money on one debt, continue making the required payments on your other debts. Missing payments may result in late fees, additional interest, or other financial consequences.
Set reminders a few days before each due date. If your income arrives on a predictable schedule, you may also consider automatic payments, provided you keep enough money in your account.
RBI’s Financial Literacy Guide includes responsible borrowing and timely repayment as important financial education topics.
Do Not Borrow More While Paying Off Existing Debt
It is difficult to reduce debt if new borrowing continues to replace the amount you repay. Before taking another loan or using credit for a non-essential purchase, ask yourself:
Is this expense necessary?
Can I wait and save for it instead?
Can I afford the monthly payment after paying essential expenses?
What will the total borrowing cost be?
Will this new payment make my current debt harder to manage?
A new loan may be appropriate for some important needs, but it should not be treated as free money. Every borrowed amount has a repayment responsibility.
SEBI also advises investors not to borrow money for securities-market investments. You can review its official investment dos and don’ts before making investment decisions.
Use Extra Income Strategically
If you receive a bonus, freelance payment, tax refund, or other extra income, you do not have to use all of it for debt. However, allocating a planned portion toward high-interest debt may help you reduce the balance faster.
For example, imagine that you receive an extra ₹10,000:
Purpose
Amount
Emergency savings
₹3,000
Extra high-interest debt payment
₹5,000
Upcoming essential expense
₹2,000
This is only an example. If you have no emergency savings, keeping some money available may help you avoid borrowing again when an unexpected expense occurs.
Arman has three debts: a ₹5,000 credit-card balance, a ₹20,000 personal loan, and a ₹40,000 education loan. He pays the required amount on each debt but has an additional ₹2,000 available every month.
Using the debt avalanche method, Arman directs the extra ₹2,000 toward the debt with the highest interest rate while continuing the required payments on the other two debts. When the first debt is paid off, he adds its previous payment to the next priority.
Using the debt snowball method, he would pay the smallest balance first. Both approaches can create progress. The important part is that Arman has a clear plan and avoids adding unnecessary new debt.
Common Debt-Management Mistakes to Avoid
Looking only at the EMI and ignoring the interest rate
Taking a new loan to pay for avoidable expenses
Missing due dates because payments are not tracked
Paying extra toward one debt while missing required payments on another
Using new credit while trying to reduce existing debt
Ignoring fees, penalties, and the total repayment cost
Borrowing money to make high-risk investments
Step 3 Debt-Repayment Action Plan
List every debt, balance, interest rate, and due date.
Calculate your total required monthly debt payments.
Make a realistic budget before increasing repayments.
Choose the debt avalanche or debt snowball method.
Continue making required payments on all debts.
Direct extra money toward your chosen priority debt.
Avoid unnecessary new borrowing.
Review your progress once each month.
Quick Takeaway
Managing debt is not only about paying money faster. It is about understanding interest costs, making payments on time, choosing a realistic strategy, and avoiding unnecessary borrowing.
For personal finance beginners, a clear debt plan can reduce financial pressure and create more room for savings and future goals. Progress may be gradual, but consistent payments and better borrowing decisions can make a meaningful difference over time.
Now that you have started protecting yourself with savings and managing expensive debt, the next step is to automate your savings and build consistent financial habits.
Step 3: Pay Off High-Interest Debt and Avoid Unnecessary Borrowing
Debt can help you pay for an important need, such as education, a home, or an emergency. However, debt can become difficult to manage when monthly payments take a large part of your income or when high interest causes the total amount to grow over time.
For personal finance beginners, learning how to manage debt is an important part of building financial stability. The goal is not always to become debt-free overnight. The goal is to understand what you owe, make payments on time, reduce expensive debt strategically, and avoid borrowing for expenses you may not be able to afford.
Before choosing a repayment strategy, create a clear list of every loan, credit-card balance, EMI, or other amount you owe. When all your debt is visible in one place, it becomes easier to decide what to pay first and how much you can realistically contribute each month.
Understand the True Cost of Your Debt
Many people focus only on the monthly EMI. However, the EMI does not always show the complete cost of borrowing. You should also understand the interest rate, repayment period, processing fees, late-payment charges, and total amount you may repay.
For example, two loans may have the same monthly payment but different interest rates or repayment periods. The loan with the higher interest rate may cost more over time, even if the monthly payment appears manageable.
Debt Type
Amount Remaining
Interest Rate
Minimum Monthly Payment
Credit-card balance
₹20,000
36% per year
₹2,000
Personal loan
₹50,000
16% per year
₹3,000
Education loan
₹1,50,000
9% per year
₹4,000
In this example, the credit-card balance has the highest interest rate. If all minimum payments are affordable and current, paying extra toward the highest-interest debt may reduce interest costs. However, your repayment plan should consider your complete financial situation.
Before borrowing, review the repayment responsibility carefully. SEBI’s official guide on thinking before you borrow money explains that borrowing creates financial responsibilities and should not be used for avoidable or unnecessary expenses.
Create a Complete Debt List
Write down every debt in one place. Do not rely only on memory because it is easy to forget due dates, fees, or small balances.
Your debt list should include:
The name of the lender
The total amount remaining
The interest rate
The minimum monthly payment
The payment due date
The remaining repayment period
Any late-payment fees or penalties
Once your list is complete, calculate the total amount you pay toward debt every month. Compare that number with your monthly take-home income and essential expenses.
If you have not created a clear monthly spending plan yet, review Step 2: Create a Realistic Budget before increasing your debt payments. A repayment plan should fit your budget so that you can continue paying consistently.
Choose a Debt-Repayment Method
Two popular debt-repayment methods are the debt avalanche and the debt snowball. Both can work, but they focus on different priorities.
Method 1: The Debt Avalanche
With the debt avalanche method, you continue making the required minimum payments on all debts. Any extra money is directed toward the debt with the highest interest rate.
After the highest-interest debt is paid off, you move the extra payment to the debt with the next-highest interest rate.
With the debt snowball method, you continue making the required payments on all debts and direct extra money toward the smallest balance first.
After paying off the smallest debt, you add that payment amount to the next-smallest debt. This creates a series of small wins that may help some people stay motivated.
The debt snowball may not always minimize total interest, but motivation can be valuable if it helps you continue the repayment plan.
Method
Priority
Possible Benefit
Debt avalanche
Highest interest rate first
May reduce total interest costs
Debt snowball
Smallest balance first
May create faster motivational wins
Choose the method that you can follow consistently. A mathematically efficient plan is less useful if it is too difficult to maintain.
Always Pay Required Amounts on Time
Even when you are focusing extra money on one debt, continue making the required payments on your other debts. Missing payments may result in late fees, additional interest, or other financial consequences.
Set reminders a few days before each due date. If your income arrives on a predictable schedule, you may also consider automatic payments, provided you keep enough money in your account.
RBI’s Financial Literacy Guide includes responsible borrowing and timely repayment as important financial education topics.
Do Not Borrow More While Paying Off Existing Debt
It is difficult to reduce debt if new borrowing continues to replace the amount you repay. Before taking another loan or using credit for a non-essential purchase, ask yourself:
Is this expense necessary?
Can I wait and save for it instead?
Can I afford the monthly payment after paying essential expenses?
What will the total borrowing cost be?
Will this new payment make my current debt harder to manage?
A new loan may be appropriate for some important needs, but it should not be treated as free money. Every borrowed amount has a repayment responsibility.
SEBI also advises investors not to borrow money for securities-market investments. You can review its official investment dos and don’ts before making investment decisions.
Use Extra Income Strategically
If you receive a bonus, freelance payment, tax refund, or other extra income, you do not have to use all of it for debt. However, allocating a planned portion toward high-interest debt may help you reduce the balance faster.
For example, imagine that you receive an extra ₹10,000:
Purpose
Amount
Emergency savings
₹3,000
Extra high-interest debt payment
₹5,000
Upcoming essential expense
₹2,000
This is only an example. If you have no emergency savings, keeping some money available may help you avoid borrowing again when an unexpected expense occurs.
Arman has three debts: a ₹5,000 credit-card balance, a ₹20,000 personal loan, and a ₹40,000 education loan. He pays the required amount on each debt but has an additional ₹2,000 available every month.
Using the debt avalanche method, Arman directs the extra ₹2,000 toward the debt with the highest interest rate while continuing the required payments on the other two debts. When the first debt is paid off, he adds its previous payment to the next priority.
Using the debt snowball method, he would pay the smallest balance first. Both approaches can create progress. The important part is that Arman has a clear plan and avoids adding unnecessary new debt.
Common Debt-Management Mistakes to Avoid
Looking only at the EMI and ignoring the interest rate
Taking a new loan to pay for avoidable expenses
Missing due dates because payments are not tracked
Paying extra toward one debt while missing required payments on another
Using new credit while trying to reduce existing debt
Ignoring fees, penalties, and the total repayment cost
Borrowing money to make high-risk investments
Step 3 Debt-Repayment Action Plan
List every debt, balance, interest rate, and due date.
Calculate your total required monthly debt payments.
Make a realistic budget before increasing repayments.
Choose the debt avalanche or debt snowball method.
Continue making required payments on all debts.
Direct extra money toward your chosen priority debt.
Avoid unnecessary new borrowing.
Review your progress once each month.
Quick Takeaway
Managing debt is not only about paying money faster. It is about understanding interest costs, making payments on time, choosing a realistic strategy, and avoiding unnecessary borrowing.
For personal finance beginners, a clear debt plan can reduce financial pressure and create more room for savings and future goals. Progress may be gradual, but consistent payments and better borrowing decisions can make a meaningful difference over time.
Now that you have started protecting yourself with savings and managing expensive debt, the next step is to automate your savings and build consistent financial habits.
Step 4: Automate Your Savings and Investments for Consistent Growth
Creating a budget and building an emergency fund are important, but consistency is what turns good financial intentions into long-term progress. Many people plan to save money every month, yet they wait until the end of the month and discover that very little is left. Automating your money can help solve this problem.
For personal finance beginners, automation means setting up a planned transfer so that a portion of your income moves toward savings or investments automatically. Instead of depending only on memory, motivation, or willpower, you create a system that supports your financial goals every time you receive money.
Automation does not guarantee investment returns, and it does not replace financial planning. However, it can make saving more consistent and reduce the temptation to spend money that was intended for your future.
What Does Automating Your Finances Mean?
Financial automation means using your bank, investment platform, or payment system to complete selected money tasks automatically on a fixed date.
For example, if you receive your salary on the 5th of every month, you could arrange:
₹1,000 to move into your emergency savings account on the 6th
₹2,000 to be invested through a planned investment contribution on the 7th
Your regular EMI or bill payment to be scheduled before its due date
This approach follows a simple principle: save first and spend the remaining amount according to your budget. It is often easier than trying to save whatever remains after a month of spending.
Why Automation Can Improve Your Money Habits
People are busy, and financial tasks are easy to postpone. You may tell yourself that you will transfer money tomorrow, but an unexpected expense or an attractive purchase can change the plan.
Automation reduces the number of decisions you need to make each month. Once the system is set up correctly, your planned contribution can happen without requiring repeated effort.
Manual Saving
Automated Saving
You must remember to transfer money
The transfer follows a scheduled date
Saving may be delayed
Saving can happen soon after income arrives
Spending may happen before saving
Money is assigned to goals earlier
Progress may depend heavily on motivation
A system supports consistency
Automation is useful because it creates a repeatable process. However, you should still review your account balance and financial plan regularly. An automatic payment is helpful only when the amount and timing are appropriate for your income.
Start With a Small Automatic Savings Amount
You do not need to automate a large amount immediately. Start with an amount that fits your current budget and does not make it difficult to pay essential expenses.
For example, if your monthly income is ₹20,000, your first automated plan could look like this:
Financial Purpose
Monthly Amount
Transfer Date
Emergency fund
₹1,000
One day after income arrives
Long-term investment
₹2,000
Two days after income arrives
Future annual expenses
₹500
One day after income arrives
In this example, ₹3,500 is assigned to future goals. The remaining income can then be used for essential expenses, debt payments, and personal spending according to the budget.
If ₹3,500 is not affordable, start with ₹500 or ₹1,000. The purpose is to build a sustainable habit. You can increase the amount after reviewing your income and expenses.
Automate Savings Before Automating Investments
If you have no emergency savings and your financial situation is unstable, building a basic emergency fund may be more important than increasing investment contributions. Investment values can rise or fall, while emergency money is intended to remain available for unexpected essential expenses.
A practical order may be:
Pay essential bills and required debt payments.
Build a basic emergency fund.
Automate regular savings.
Begin long-term investing according to your goals and risk tolerance.
Increase contributions gradually as your financial position improves.
In India, many investors use a Systematic Investment Plan, commonly called a SIP, to invest a fixed amount at regular intervals in a mutual fund. A SIP is a method of investing regularly; it does not guarantee profits or protect against market losses.
According to the Association of Mutual Funds in India (AMFI), a SIP allows investors to invest a fixed amount periodically. Before investing, understand the fund’s objective, risk level, costs, and whether it matches your financial goals.
For example, someone may invest ₹2,000 per month through a SIP for a long-term goal. The investment amount remains fixed, but the value of the investment can move up or down depending on market performance.
If you are new to mutual funds, your article on best-performing FlexiCap funds can be linked here only if that is the exact working URL. Otherwise, search for the article inside WordPress and select the correct page before publishing.
Choose the Right Date for Automatic Transfers
The timing of automation matters. Setting a transfer date before your income arrives may cause a failed transaction or create pressure on your account balance.
A simple approach is to schedule savings one or two days after your salary, business income, or regular payment usually arrives.
For example:
Income arrives: 5th of the month
Emergency-fund transfer: 6th
Investment contribution: 7th
Bill and EMI payments: According to their due dates
Budget review: Last day of the month
If your income is irregular, avoid setting an automatic amount that could leave you short of money. You may prefer to transfer a percentage of each payment manually or automate a small base amount.
A Simple Automation Example
Meera earns ₹30,000 per month. She wants to save and invest but usually spends most of her money before the month ends.
She creates the following system:
Purpose
Amount
Emergency savings
₹2,000
Long-term investment
₹3,000
Future expenses
₹1,000
Every month, ₹6,000 is assigned automatically after she receives her income. She then manages the remaining ₹24,000 using her monthly budget.
After three months, Meera reviews the plan. Because her essential expenses are under control, she increases her savings contribution by ₹500. She does not make a large change all at once; she improves the system gradually.
Review Automated Payments Regularly
Automation should not become “set it and forget it.” Your income, expenses, goals, and financial responsibilities may change.
Review your automated transfers at least every three to six months and ask:
Is the savings amount still affordable?
Have my essential expenses increased?
Is my emergency fund progressing toward its target?
Does my investment still match my financial goal and risk tolerance?
Have any automatic payments become unnecessary?
Is there enough money in my account before each payment date?
The SEBI Investor Education portal provides educational information about investing and investor awareness. Before investing, understand the product instead of choosing it only because it is popular or has performed well recently.
Common Automation Mistakes to Avoid
Automating an amount that is too large for your budget
Scheduling transfers before income usually arrives
Ignoring account balances and payment failures
Investing emergency money in volatile assets
Increasing investment contributions while high-interest debt remains unmanaged
Choosing an investment without understanding its risks
Never reviewing old automatic payments or subscriptions
Step 4: 15-Minute Automation Action Plan
Review your monthly income and essential expenses.
Choose a realistic savings amount.
Select a separate account for emergency savings.
Schedule the transfer one or two days after income arrives.
Decide whether you are financially ready for long-term investing.
Set up investment contributions only after understanding the risks and product.
Turn on transaction alerts and check that payments are successful.
Review the entire system every three to six months.
Key Takeaway
Automating savings and investments can make financial progress more consistent because it turns a good intention into a repeatable system. Start with an affordable amount, protect your emergency savings, understand investment risks, and review your automatic payments regularly.
For personal finance beginners, the goal is not to automate the largest possible amount. The goal is to create a sustainable financial system that supports your needs today while helping you prepare for future goals.
Next: After creating a consistent savings system, the next step is to diversify your investments and manage risk instead of depending too heavily on a single asset or investment.
Step 5: Diversify Your Investments and Manage Risk Wisely
After building an emergency fund, managing expensive debt, and creating a regular saving habit, you may begin thinking about long-term investing. However, investing all your money in one company, one sector, one fund, or one type of asset can create unnecessary risk.
For personal finance beginners, diversification means spreading your investments instead of depending too heavily on a single investment. Diversification cannot guarantee profits or prevent all losses, but it may reduce the damage if one investment performs poorly.
A strong investment plan is not only about finding the investment with the highest recent return. It should also consider your financial goals, time horizon, risk tolerance, emergency savings, existing debt, and the purpose of the money you are investing.
What Does Investment Diversification Mean?
Diversification is often explained with the phrase, “Do not put all your eggs in one basket.” In personal finance, this means avoiding excessive dependence on one company, industry, asset class, or investment idea.
For example, imagine that Ravi invests his entire ₹1,00,000 in shares of only one company. If that company faces financial problems, the value of a large part of his investment may fall.
Now imagine that another investor spreads money across different investments based on their goals and risk capacity. If one investment performs poorly, the other investments may reduce the overall impact. This does not remove risk, but it can reduce concentration risk.
Highly Concentrated Portfolio
More Diversified Portfolio
Most money is invested in one company or asset
Money is spread across multiple investments
One poor investment may have a large impact
The effect of one investment may be reduced
Higher concentration risk
Risk may be spread across different areas
Returns depend heavily on one outcome
The portfolio is less dependent on one investment
The Investor.gov guide to diversification explains that diversification involves spreading investments among different assets to reduce the impact of a single investment on an overall portfolio.
Understand the Main Types of Investment Risk
Investment risk is not only the possibility that prices may fall. Different investments can involve different risks, and understanding them can help you make more informed decisions.
Market risk: Investment values may rise or fall because of economic conditions, interest rates, company performance, or market sentiment.
Concentration risk: Too much money is invested in one company, sector, asset, or investment theme.
Liquidity risk: You may not be able to access your money quickly without selling at an unfavorable price.
Inflation risk: Your money may lose purchasing power if its growth does not keep up with rising prices.
Credit risk: A borrower or issuer may fail to make expected payments.
Understanding these risks does not mean avoiding every investment. It means knowing what could happen before you commit your money.
Match Your Investments With Your Financial Goals
Before choosing an investment, decide what the money is for and when you may need it. Money needed next year may require a different approach from money intended for a goal that is ten or twenty years away.
Financial Goal
Possible Time Horizon
Important Consideration
Emergency expense
Any time
Safety and quick access may be more important than growth
Course fee or planned purchase
1–2 years
Avoid taking unnecessary market risk with money needed soon
Buying a home
5–10 years
Consider the target date and your ability to handle investment changes
Long-term financial independence
10+ years
Long-term growth, risk, and diversification may become more relevant
Emergency savings should remain separate from long-term investments because you may need emergency money quickly. If you have not built an emergency fund yet, return to Step 2: Build an Emergency Fund and create a basic financial safety net first.
For a broader money-management framework, you can also read our guide on Financial Planning for Beginners: 10 Simple Steps. It explains how budgeting, saving, debt management, financial goals, and investing can work together.
Understand Asset Allocation
Asset allocation means deciding how your investment money is divided among different investment categories. There is no single allocation that is suitable for everyone.
Your financial goals, income, responsibilities, time horizon, and ability to handle losses can affect the type of allocation that may be appropriate for you.
For educational purposes, a sample portfolio could look like this:
Investment Category
Example Allocation
Possible Purpose
Equity-oriented investments
50%
Long-term growth potential
Debt or fixed-income investments
30%
Potential stability and income
Cash or short-term savings
20%
Liquidity and near-term needs
This is only an example for understanding asset allocation. It is not a recommended portfolio. Your own allocation should be based on your financial goals, risk capacity, and time horizon.
Diversification Does Not Mean Buying Everything
Some beginners believe that buying many investments automatically creates diversification. However, owning a large number of products does not always reduce risk.
For example, buying shares of ten companies from the same industry may still create concentration risk. Similarly, investing in several funds that hold many of the same companies may create more overlap than you expect.
Before adding a new investment, ask:
What does this investment add to my portfolio?
Does it hold many of the same assets I already own?
Does it support one of my financial goals?
Do I understand its risks and costs?
Am I buying it because of a clear plan or only because it recently performed well?
The goal is not to own the largest number of investments. The goal is to avoid unnecessary concentration while keeping your financial plan understandable.
Understand Mutual Funds Before Investing
Mutual funds may provide exposure to multiple securities through a single investment product. However, different funds have different objectives, risks, costs, investment styles, and portfolio holdings.
Before investing, read the scheme information, understand the investment objective, review the risk level, and check whether the fund matches your financial goal.
The AMFI Investor Knowledge Centre provides educational information about mutual funds, investor awareness, and important investment concepts.
If you want to learn more about one mutual-fund category, read our detailed guide on Best Performing FlexiCap Funds. The article can help you understand what to examine beyond past returns, including investment strategy, risk, consistency, and long-term suitability.
A Practical Diversification Example
Suppose Sana has ₹1,20,000 available. Before investing, she checks whether she has enough emergency savings, whether she has expensive debt, and when she may need the money.
She realizes that she may need ₹20,000 within the next year and wants to keep ₹30,000 available for emergencies. Instead of investing the entire ₹1,20,000 in one company, she separates the money according to its purpose.
Financial Purpose
Example Amount
Emergency savings
₹30,000
Near-term planned expense
₹20,000
Long-term investment goal
₹70,000
This example shows that diversification is not only about dividing investments. It also includes separating emergency money, short-term goal money, and long-term investment money.
Review Your Investments Without Reacting Emotionally
Investment prices may change every day. Checking your portfolio constantly can increase stress and may encourage emotional decisions.
Instead, review your investments on a planned schedule, such as every six or twelve months, or when your financial goals change.
During a review, ask:
Does this investment still support my financial goal?
Has my time horizon changed?
Has my income or financial responsibility changed?
Has one investment become too large a part of my portfolio?
Do I understand what I own?
Are the risks and costs still acceptable?
A review does not always mean buying or selling. Sometimes the correct action is to continue following a suitable long-term plan.
Use Reliable Investment Information
Investment decisions should not be based only on social-media trends, advertisements, or promises of guaranteed returns. Check official information and understand the product before investing.
The SEBI Investor Education portal provides investor-awareness information and educational resources. It can help beginners understand important investment concepts and recognize the need for informed decision-making.
If you are using digital tools to organize your financial information, read our guide on 10 Best AI Tools to Manage Your Personal Finances in 2026. These tools may help with budgeting, expense tracking, planning, and research, but important financial information should always be verified.
Common Diversification Mistakes to Avoid
Investing all your money in one company or sector
Choosing investments only because of recent high returns
Copying another person’s portfolio without understanding it
Investing emergency money in volatile assets
Buying many funds without checking portfolio overlap
Ignoring investment costs and risk information
Making decisions because of short-term market fear or excitement
Assuming diversification guarantees profit or eliminates all losses
Step 5: Investment Diversification Action Plan
Write down your financial goals and target dates.
Keep emergency savings separate from long-term investments.
Review your current investments and identify concentration risk.
Check whether multiple investments hold similar assets.
Understand the purpose, risk, and cost of every investment.
Choose an allocation based on your goals and risk capacity.
Avoid investing only because of recent returns or online trends.
Review your portfolio periodically instead of reacting to daily price changes.
Key Takeaway
Diversification is a risk-management strategy, not a guarantee of profit. By spreading investments thoughtfully, matching them with your financial goals, and avoiding excessive dependence on one asset, you can build a more balanced financial plan.
For personal finance beginners, the most important rule is to understand what you own and why you own it. Keep emergency money separate, invest according to your time horizon, and avoid making decisions based only on recent performance.
Next: After building a diversified investment approach, the next step is to improve your financial knowledge and stay informed without becoming overwhelmed by financial news, trends, or social-media advice.
Step 6: Improve Your Financial Knowledge and Stay Informed
Managing money is not only about earning, budgeting, saving, or investing. Good financial decisions also depend on understanding how money works. Financial products, interest rates, investment options, technology, and economic conditions can change over time. That is why improving your financial knowledge can help you make more informed decisions and avoid costly mistakes.
For personal finance beginners, financial education does not mean becoming an accountant, economist, or investment expert. It means learning enough to understand your financial choices, compare options, recognize risks, ask useful questions, and avoid making decisions only because something is popular on social media.
You do not need to study finance for several hours every day. Even 20 to 30 minutes of focused learning each week can improve your understanding when you apply what you learn to your own income, expenses, savings, debt, investments, and financial goals.
Why Financial Knowledge Is Important
Many financial problems happen because people do not fully understand interest rates, loan terms, investment risks, fees, inflation, or the long-term effect of their decisions.
For example, imagine that two people want to invest ₹2,000 every month. The first person invests because a social-media creator says that a particular investment will provide very high returns. The second person spends time learning about risk, diversification, investment time horizons, fees, and how the investment actually works.
Neither person can predict future returns. However, the second person is more likely to understand the possible benefits and risks before investing.
Learn the Most Important Personal Finance Topics First
There is a huge amount of financial information online. Trying to learn everything at once can create confusion. A better approach is to begin with the topics that directly affect your financial life.
Financial Topic
What You Should Learn
Why It Matters
Budgeting
Income, expenses, spending limits, and monthly planning
Helps you understand where your money goes
Saving
Emergency funds, savings goals, and consistent saving habits
Helps create financial security
Debt
Interest rates, EMIs, repayment periods, and borrowing costs
Helps you manage debt responsibly
Investing
Risk, return, diversification, time horizon, and fees
Helps you make informed long-term decisions
Financial Goals
Target amounts, deadlines, and monthly contributions
Gives your money a clear purpose
Credit
Payment history and responsible borrowing
Can affect future borrowing opportunities
Start with the topic that is most important to your current situation. If you are struggling to save money, first learn about spending habits and budgeting. If you have expensive debt, understand interest costs and repayment strategies before focusing heavily on investing.
If you earn regularly but still struggle to save, read our detailed guide on why you can’t save money even with a good salary. It explains hidden spending patterns and practical ways to improve your saving habits.
Use Reliable Financial Sources Instead of Following Every Trend
Social media can help you discover financial ideas, but short videos and viral posts often leave out important details. A person may show high investment returns without explaining the risks, fees, losses, taxes, or time involved.
Before acting on financial information, check whether the source is reliable and whether the information applies to your situation.
Ask these questions:
Who published this information?
Is the source a government agency, financial regulator, recognized institution, or qualified professional?
Does the content explain risks as well as possible benefits?
Is the information current?
Is someone trying to sell a financial product?
Can the information be verified through another reliable source?
For beginner investment education, Investor.gov’s introduction to investing explains important topics such as financial goals, risk, diversification, long-term investing, and the difference between saving and investing.
Use Financial Technology to Learn and Manage Money
Technology can make financial learning easier. Budgeting apps, expense trackers, calculators, banking tools, and AI-powered financial tools can help you organize information and understand your financial habits.
However, a tool should support your decisions rather than replace your judgment. Before sharing financial information with an app or AI tool, check its privacy policy, security practices, and the type of information it collects.
To explore useful tools in more detail, read our guide on 10 Best AI Tools to Manage Your Personal Finances in 2026. The article explains how different tools may help with budgeting, expense tracking, financial planning, and money management.
Financial tools can help you organize information, but they may not understand your complete financial situation. Verify important information before making a major financial decision.
Understand an Investment Before You Put Money Into It
One of the most useful financial habits is refusing to invest in something you do not understand. A product may have a professional-looking website, a popular name, or strong past returns, but those factors do not automatically make it suitable for your goals.
Before investing, try to answer these questions in simple language:
What does this investment actually do?
How can it make or lose money?
What are its main risks?
How long may I need to keep my money invested?
Can I access the money quickly if necessary?
What fees or charges may apply?
Does this investment match my financial goal and risk tolerance?
The Investor.gov guide to investment options explains that different investments have different risks, potential returns, and characteristics. Understanding these factors can help investors make more informed decisions.
If you want to understand one mutual-fund category in greater detail, read our guide on Best Performing FlexiCap Funds. It explains important factors to evaluate beyond past returns, including investment strategy, risk, consistency, and long-term suitability.
Create a Simple Weekly Financial Learning Routine
You do not need a complicated study plan. A small routine is easier to follow and becomes more valuable when you apply the lessons to your own finances.
Day
Learning Activity
Suggested Time
Monday
Read one reliable article about budgeting or saving
10 minutes
Wednesday
Learn one financial term, such as inflation or interest
10 minutes
Friday
Study one investment concept or financial risk
15 minutes
Sunday
Apply one lesson to your own financial plan
15 minutes
The most important part is application. Reading about budgeting is useful, but reviewing your own spending is more practical. Learning about emergency funds is useful, but saving your first ₹100 or ₹500 turns knowledge into action.
Keep a Personal Finance Learning Notebook
Create a notebook, document, or digital note where you explain financial concepts in your own words. Avoid copying complicated definitions without understanding them.
Financial Concept
Simple Meaning
Personal Action
Emergency Fund
Money reserved for unexpected essential expenses
I will begin by saving ₹5,000
Interest Rate
The cost of borrowing or the return offered by some savings products
I will compare rates before borrowing
Diversification
Spreading investments to reduce dependence on one investment
I will avoid putting all my money into one company
Writing financial ideas in your own words can help you identify what you understand and what you need to learn further.
Learn From Your Own Financial Decisions
Your monthly financial activity is also a learning opportunity. At the end of each month, review your decisions and look for useful patterns.
Ask yourself:
Where did I spend more than expected?
Did I save the amount I planned?
Did I borrow money? If yes, why?
Which expense gave me real value?
Which expense could I reduce next month?
Did I make a financial decision without enough information?
For example, suppose you planned to spend ₹3,000 on food but spent ₹4,500. Instead of only saying that your budget failed, find the reason. Did prices increase? Did you order food more often? Did you forget to include an important expense?
The answer can help you create a more realistic financial plan next month.
A Practical Financial Learning Example
Arif wants to invest ₹3,000 every month. Before investing, he spends one week learning about risk, diversification, investment time horizons, and fees.
He discovers that he may need part of the money within one year. Instead of investing the complete ₹3,000 without a plan, he separates his short-term needs from his long-term goals.
Financial Purpose
Monthly Amount
Short-term savings goal
₹1,000
Emergency savings
₹1,000
Long-term investment goal
₹1,000
The amounts are only examples. The important lesson is that financial knowledge helped Arif create a plan based on his own needs instead of copying someone else’s investment decision.
Common Financial Learning Mistakes to Avoid
Believing every viral financial video
Following investment tips without checking the source
Focusing only on returns and ignoring risk
Learning advanced investing before understanding budgeting
Buying a financial product without reading important information
Assuming past performance guarantees future results
Copying another person’s financial plan without considering your own goals
Reading financial content without applying anything to your own situation
Step 6: Financial Learning Action Plan
Choose one personal finance topic to study this week.
Use an official or reliable educational source.
Learn the concept in simple language.
Write the main lesson in your own words.
Check how the concept applies to your income, expenses, savings, or goals.
Take one small action based on what you learned.
Review the result at the end of the month.
Continue learning without rushing into financial products.
Key Takeaway
Financial knowledge is not about memorizing complicated terms. It is about understanding how your money decisions affect your present and future.
For personal finance beginners, learning the basics of budgeting, saving, debt, investing, risk, and financial goals can improve decision-making over time. Use reliable sources, question unrealistic promises, apply what you learn, and continue improving your financial knowledge step by step.
Next: After improving your financial knowledge, the next step is to use financial technology and digital money tools wisely while protecting your personal and financial information.
Step 7: Use Financial Technology and Money Tools Wisely
Financial technology has made managing money faster and more convenient. Today, you can check your bank balance, track expenses, pay bills, create a budget, invest, and monitor financial goals using a smartphone. However, technology is only useful when it helps you make better decisions instead of encouraging unnecessary spending or creating security risks.
For personal finance beginners, financial tools can simplify money management by organizing financial information in one place. A budgeting app may show where your money goes, an expense tracker may help identify unnecessary spending, and an automated transfer can make saving more consistent.
However, no app can automatically create good financial habits. A tool can show that you spent too much, but you still need to decide what to change. Use technology as a support system—not as a replacement for financial knowledge and personal responsibility.
How Financial Technology Can Help You Manage Money
Different financial tools are designed for different purposes. You do not need to install every app. Choose tools that solve a specific problem in your financial life.
Financial Tool
How It Can Help
What to Check
Banking App
Check balances, review transactions, transfer money, and pay bills
Security settings and transaction alerts
Budgeting App
Plan monthly income and expenses
Privacy policy and data access
Expense Tracker
Identify spending patterns
Accuracy and account permissions
Goal Tracker
Monitor progress toward savings goals
Whether the goals are realistic
Investment Platform
View investments and research products
Fees, risks, and regulatory information
AI Financial Tool
Organize information and explain financial concepts
Accuracy, privacy, and limitations
The best financial tool is not always the one with the most features. It is the one you can understand, use consistently, and trust with your information.
Use Budgeting and Expense-Tracking Tools to Understand Your Spending
Many people know their monthly income but cannot clearly explain where all their money goes. Small expenses can become difficult to notice when they happen through digital payments.
An expense tracker can help you categorize spending, such as:
Rent or housing
Food and groceries
Transportation
Mobile and internet bills
Entertainment
Shopping
Loan or EMI payments
Savings and investments
For example, suppose your monthly income is ₹25,000. You believe that you spend only ₹2,000 on online shopping and food delivery. After tracking your expenses for one month, you discover that the actual amount is ₹4,500.
The tool did not create the problem. It simply made the spending pattern visible. You can now decide whether reducing that category would help you save more.
If you are earning regularly but still struggle to save, read our guide on why you can’t save money even with a good salary. It explains hidden spending habits and practical ways to improve your savings.
Use Automation to Make Saving More Consistent
Automation can reduce the need to make the same financial decision every month. For example, you may schedule an automatic transfer to a savings account shortly after receiving your income.
Suppose you earn ₹30,000 per month and want to save ₹3,000. Instead of waiting until the end of the month to see what remains, you may automatically move ₹3,000 into savings after your income arrives.
Without Automation
With Automation
Save whatever remains at the end of the month
Move a planned amount soon after receiving income
Saving may be affected by unnecessary spending
Savings become part of the monthly system
Requires a new decision every month
Reduces repeated manual effort
Automation should still be reviewed regularly. If your income changes or you have an unexpected expense, you may need to adjust the amount.
Use AI Tools as Financial Assistants, Not Financial Decision-Makers
AI tools can help explain financial terms, summarize information, create a basic budget template, organize expenses, compare general financial concepts, and generate questions for research.
For example, you can ask an AI tool:
“Help me create a monthly budget using an income of ₹25,000.”
“Explain the difference between saving and investing in simple language.”
“Create a checklist for comparing two financial products.”
“Help me identify possible unnecessary expenses from this spending list.”
However, AI-generated information can be incomplete, outdated, or incorrect. Do not treat an AI response as personalized financial advice. Verify important information using official sources before making major decisions.
Convenience should not come at the cost of security. Financial apps may contain sensitive information, including account details, transaction history, personal information, and spending patterns.
Before installing or connecting a financial app, check what information it requests and why it needs that access.
Follow these basic security practices:
Use a strong and unique password for important financial accounts.
Enable two-factor authentication when available.
Keep your phone and financial apps updated.
Do not share OTPs, passwords, PINs, or security codes.
Avoid entering financial information on suspicious websites.
Review app permissions before connecting bank accounts.
Check Privacy Before Connecting Your Financial Accounts
Some financial tools request permission to access account information or transaction data. Before approving access, read the privacy policy and understand what data the company collects, stores, shares, or uses.
Ask these questions:
What financial information will the app access?
Why does the app need this information?
Does the company explain how it protects user data?
Can you delete your data or close your account?
Does the company share information with third parties?
Can you use the tool without connecting your bank account?
Do not connect an account only because an app promises convenience. The benefit should be worth the information you are sharing.
Use Investment Apps Carefully
Investment apps can make buying and selling easier, but convenience may also encourage frequent decisions. Seeing prices change every minute can create fear or excitement and lead to emotional actions.
Before using an investment platform, understand:
What investment products are available?
What fees or charges may apply?
What risks are involved?
How quickly can you access your money?
Is the platform regulated where required?
Does the investment match your financial goal?
The SEBI Investor Education portal provides educational information to help investors understand financial markets, investment risks, and informed decision-making.
Before selecting a mutual fund or investment category, you can also read our guide on Best Performing FlexiCap Funds. Past performance alone should not be the only factor in an investment decision.
A Practical Example: Creating a Simple Digital Money System
Suppose Sameer earns ₹30,000 per month. He wants to improve his money management but does not want to use many different apps.
He creates a simple system:
Financial Activity
Tool or Method
Monthly Action
Track spending
Expense tracker
Review expenses every Sunday
Save money
Automatic bank transfer
Move ₹3,000 after receiving income
Pay bills
Banking app reminder
Check due dates before payment
Monitor goals
Simple spreadsheet
Update savings progress monthly
Learn about finance
Reliable educational websites
Study one topic each week
Sameer does not need ten financial apps. He uses a small number of tools with clear purposes and reviews them regularly.
Common Financial Technology Mistakes to Avoid
Installing many financial apps without using them consistently
Giving unnecessary permissions to an app
Sharing OTPs, PINs, passwords, or security codes
Trusting AI-generated financial information without verification
Making investment decisions because an app makes trading easy
Ignoring privacy policies and data-sharing practices
Using the same password for multiple financial accounts
Following notifications that encourage unnecessary spending
Connecting financial accounts to unknown or unverified apps
Step 7: Financial Technology Action Plan
Choose one financial problem you want technology to help solve.
Select one simple and reliable tool instead of downloading many apps.
Use an expense tracker for at least 30 days.
Turn on useful transaction and payment alerts.
Automate a realistic savings amount if your cash flow allows it.
Review app permissions and privacy settings.
Enable strong security and two-factor authentication.
Verify important financial information before acting on it.
Review your tools every three to six months.
Key Takeaway
Financial technology can make money management easier, but it cannot replace financial knowledge, discipline, or careful decision-making.
For personal finance beginners, the best approach is to use a small number of reliable tools for clear purposes—such as tracking expenses, automating savings, monitoring goals, and learning financial concepts. Protect your information, review permissions, and verify important financial details before taking action.
Next: After creating a simple financial system, the next step is to set clear financial goals and track your progress so that your income, savings, and investments have a defined purpose.
Step 8: Set Clear Financial Goals and Track Your Progress
Saving money without a clear purpose can feel difficult. When you do not know what you are saving or investing for, it becomes easier to spend the money on short-term wants. Financial goals give your money a direction and help you make decisions based on what matters most to you.
For personal finance beginners, setting financial goals does not mean creating an unrealistic plan to become wealthy quickly. It means deciding what you want your money to help you achieve, estimating how much you may need, choosing a realistic timeline, and taking small, consistent steps.
Your goals may include building an emergency fund, paying off debt, buying a phone, funding education, starting a business, purchasing a home, or preparing for retirement. The goal can be different for every person because income, responsibilities, priorities, and financial situations are different.
Why Financial Goals Are Important
A financial goal turns a general wish into a measurable plan.
For example, saying, “I want to save more money,” is a good intention, but it does not explain how much you want to save or when you want to achieve it.
A clearer goal would be:
“I want to save ₹30,000 for my emergency fund within 12 months by saving ₹2,500 every month.”
This goal has a target amount, a timeline, and a monthly action. You can measure your progress and adjust the plan if your income or expenses change.
Understand the Three Main Types of Financial Goals
Dividing your goals by time can help you decide how much money you need and when you may need it.
Goal Type
Typical Time Frame
Examples
Short-Term Goals
Less than 1–2 years
Emergency savings, a course fee, a phone, or paying a small debt
Medium-Term Goals
Approximately 2–5 years
Starting a business, buying a vehicle, or funding higher education
Long-Term Goals
More than 5 years
Buying a home, retirement, or long-term financial independence
The time frame is not fixed. A goal that is short-term for one person may take longer for another person. Your income, responsibilities, and available savings will affect the timeline.
Turn a Financial Wish Into a SMART Goal
A useful financial goal should be clear enough that you can measure and review it. You can use the SMART framework:
SMART Element
Meaning
Example
Specific
Clearly define the goal
Build an emergency fund
Measurable
Choose a target amount
Save ₹30,000
Achievable
Keep the plan realistic
Save ₹2,500 per month
Relevant
Connect the goal to your needs
Prepare for unexpected expenses
Time-Bound
Set a target date
Complete the goal in 12 months
A SMART goal may look like this:
“I will save ₹24,000 in 12 months by transferring ₹2,000 into my savings account every month.”
This is easier to follow than saying, “I will try to save more.”
Calculate How Much You Need to Save Each Month
Once you know your target amount and deadline, calculate the approximate monthly amount required.
Simple formula:
Monthly Savings Needed = Total Goal Amount ÷ Number of Months
Example:
Financial goal: ₹60,000
Time available: 20 months
₹60,000 ÷ 20 = ₹3,000 per month
In this example, you would need to save approximately ₹3,000 each month if your income and expenses remain stable.
However, do not create a savings target that forces you to miss essential expenses or rely on expensive borrowing. If ₹3,000 is not realistic, extend the timeline or reduce the target amount.
Prioritize Your Financial Goals
You may have several goals at the same time, but your income may not be enough to fund all of them equally. Prioritization helps you decide where your money should go first.
Priority Level
Example Goal
Reason
High Priority
Emergency fund or high-interest debt
May protect financial stability and reduce expensive costs
Medium Priority
Education, skill development, or a planned purchase
Important but may have a flexible timeline
Long-Term Priority
Retirement or long-term investing
May require consistent contributions over many years
For example, if you have high-interest debt and no emergency savings, it may be more practical to improve those areas before putting a large amount into a long-term investment.
Financial priorities can change. A new job, family responsibility, income reduction, or unexpected expense may require you to adjust your plan.
Create a Goal-Based Money Plan
Instead of keeping all your money in one general savings category, assign each amount a purpose. This can make your progress easier to understand.
Suppose Ayaan has ₹5,000 available each month after essential expenses:
Financial Goal
Monthly Amount
Purpose
Emergency fund
₹2,000
Prepare for unexpected essential expenses
Debt repayment
₹1,500
Reduce an existing financial obligation
Education or skill fund
₹1,000
Support future learning
Personal goal
₹500
Save for a planned purchase
This is only an example. Your own plan should depend on your income, essential expenses, debt, emergency needs, and priorities.
Track Your Financial Progress Regularly
Setting a goal is only the first step. Tracking helps you see whether your actions are moving you closer to the target.
You can track progress using:
A notebook
A spreadsheet
A budgeting app
A savings tracker
Your banking app
A simple monthly checklist
For example:
Month
Target Savings
Actual Savings
Total Progress
January
₹2,500
₹2,500
₹2,500
February
₹2,500
₹2,000
₹4,500
March
₹2,500
₹3,000
₹7,500
Progress does not need to be perfect every month. If you save less during one month because of an important expense, review the reason and adjust the next month instead of abandoning the goal.
Use Financial Tools to Track Goals More Easily
Digital tools can make goal tracking faster. A budgeting app, spreadsheet, expense tracker, or AI-powered financial tool may help you organize your income, expenses, savings targets, and progress.
However, technology should support your plan rather than create unnecessary complexity. You do not need ten different apps to track one financial goal.
To explore useful digital tools, read our detailed guide on 10 Best AI Tools to Manage Your Personal Finances in 2026. It explains how different tools may support budgeting, expense tracking, financial planning, and money management.
Review Goals Without Feeling Discouraged
Your financial plan should be flexible. If your income changes, an emergency occurs, or your expenses increase, you may need to change the amount or timeline.
For example, suppose your goal is to save ₹30,000 in one year, but you can save only ₹15,000 after six months. Instead of giving up, review your situation:
Can you reduce one unnecessary expense?
Can you increase your income?
Can you extend the deadline?
Can you reduce the target amount?
Was there an unexpected expense that affected your progress?
Adjusting a financial goal is not the same as failing. A realistic plan should be able to adapt to changes in your life.
If you are earning a reasonable income but still cannot save consistently, our guide on why you can’t save money even with a good salary may help you identify hidden spending patterns and improve your savings system.
Use Long-Term Goals to Guide Investment Decisions
Long-term financial goals can help you decide why you are investing and how much risk may be appropriate. Before choosing an investment, consider when you may need the money and whether you can handle changes in its value.
The Investor.gov investing basics explain that financial goals, time horizon, risk tolerance, and investment choices are connected.
If you are researching mutual funds, you can also read our guide on Best Performing FlexiCap Funds. Past returns should not be the only factor; the investment strategy, risk, costs, and suitability for your goal are also important.
A Practical Financial Goal Example
Suppose Sana wants to build a ₹50,000 emergency fund within 20 months.
She calculates:
₹50,000 ÷ 20 months = ₹2,500 per month
Her plan looks like this:
Action
Plan
Monthly savings target
₹2,500
Transfer date
Within two days of receiving income
Tracking method
Simple spreadsheet
Review schedule
Last Sunday of every month
Adjustment plan
Extend the timeline if income falls
After four months, Sana has saved ₹9,000 instead of the planned ₹10,000 because of an unexpected expense. She reviews her budget and decides to add ₹500 during the next two months. Her goal remains flexible and realistic.
Common Financial Goal Mistakes to Avoid
Setting a goal without choosing a target amount
Creating an unrealistic deadline
Trying to fund too many goals at the same time
Ignoring emergency savings
Saving without tracking progress
Using borrowed money to meet a savings target
Comparing your financial progress with other people
Giving up after one difficult month
Never reviewing or updating your goals
Step 8: Financial Goal Action Plan
Write down your three most important financial goals.
Choose a target amount for each goal.
Set a realistic deadline.
Calculate the approximate monthly amount required.
Rank your goals by priority.
Choose a simple tracking method.
Review your progress once every month.
Adjust the amount or timeline when your financial situation changes.
Celebrate progress without creating unnecessary spending.
Key Takeaway
Financial goals give your money a purpose. A clear target, realistic timeline, regular contribution, and simple tracking system can make a large financial goal feel more manageable.
For personal finance beginners, the best approach is to start with one important goal, take small and consistent actions, and review your progress regularly. Your financial plan does not need to be perfect—it needs to be realistic enough to continue.
Next: After setting clear financial goals, the next step is to build and protect a healthy credit profile by understanding responsible borrowing, timely payments, and credit-report monitoring.
What is personal finance for beginners?
Personal finance for beginners means learning how to manage income, expenses, savings, debt, insurance, and investments. The goal is to make informed money decisions, build financial security, and work toward short-term and long-term financial goals.
How should a beginner start managing money?
A beginner can start by tracking monthly income and expenses, creating a simple budget, saving a small amount regularly, building an emergency fund, and avoiding unnecessary debt. Start with a simple system that you can follow consistently.
How much money should a beginner save each month?
There is no single amount that works for everyone. Start with an amount that fits your income and essential expenses, even if it is small. Saving consistently is usually more sustainable than setting an unrealistic target and stopping after a few months.
Conclusion:
Personal finance does not require a high income, complicated calculations, or perfect money habits. It starts with understanding where your money comes from, where it goes, and what you want it to achieve.
By following these 10 steps, you can create a realistic budget, control unnecessary expenses, build an emergency fund, manage debt responsibly, set clear financial goals, and make better decisions about saving and investing. You do not need to complete everything at once. Start with one small action, such as tracking your expenses for a week or saving a fixed amount every month.
Your financial plan should also change as your income, responsibilities, and goals change. Review your progress regularly, learn from mistakes, and adjust your plan when necessary. A missed savings target or an unexpected expense does not mean your plan has failed—it simply shows that something may need to be improved.
For personal finance beginners, consistency is usually more valuable than trying to follow a perfect system. Small habits, repeated over time, can help you build greater financial confidence and move closer to long-term financial stability.
Start today: review your income and expenses, choose one financial goal, and take the first practical step toward managing your money better.
Personal Finance for Beginners: Quick Summary Personal finance for beginners starts with understanding your income, tracking expenses, and making a realistic plan for your money. You do not need a high income or a complicated system to begin. Small and consistent financial decisions can help you build better money habits over time. Understand your income, expenses, savings, and debts. Create a realistic monthly budget. Track spending and reduce unnecessary expenses. Build an emergency fund gradually. Manage debt responsibly and pay bills on time. Set clear short-term and long-term financial goals. Protect your finances with suitable insurance and basic security practices. Learn the basics before investing and understand the risks involved. Develop consistent financial habits instead of looking for quick results. Review your financial plan regularly and adjust it when your income, expenses, or goals change. The most important lesson is that financial progress does not usually happen through one big decision. It is built through small actions repeated consistently. Start with one practical step today, improve your system over time, and make decisions that support your financial goals.
Imagine you suddenly need ₹10,000 for a medical bill, urgent travel, a job gap, or an unexpected repair. If all your money is sitting in the same account you use for everyday spending, you may end up using money meant for other goals—or worse, borrowing to cover the expense. That’s where an emergency fund becomes … Read more
Planning for multiple financial goals can feel overwhelming. This simple guide shows you how to prioritize your goals, set realistic targets, calculate monthly savings, and stay on track for 2027. Saving for one goal is simple. But when you have several goals at the same time—such as an emergency fund, annual expenses, a new laptop, … Read more
Managing money can feel difficult when small purchases keep adding up throughout the month. The cash stuffing method offers a simple way to give each spending category a clear limit and make your budget easier to see and follow.Instead of keeping your entire spending budget in one place, you divide cash into separate categories such … Read more
introduction Getting a salary every month feels good, but managing that money wisely can be challenging, especially when you are just starting to manage your finances. Bills, daily expenses, savings, debt, and personal spending can quickly compete for the same income. Learning how to divide your salary for beginners can make this much easier. Instead … Read more
Managing money isn’t just about earning more—it’s about making smart financial decisions that help you build a secure future. Unfortunately, many people struggle with budgeting, saving, investing, and managing debt because they don’t have a clear financial plan. That’s why Financial Planning for Beginners is one of the most important skills anyone can learn, regardless of their income or financial background.
Whether you’re a student, a young professional, a freelancer, or simply looking to take control of your finances, financial planning provides a clear roadmap for managing your money with confidence. It helps you set realistic financial goals, create a practical budget, build an emergency fund, reduce financial stress, and make informed investment decisions that support long-term wealth.
In this complete guide, you’ll learn the 10 simple steps of Financial Planning for Beginners, along with practical strategies, real-world examples, and actionable tips that you can apply immediately. By the end of this article, you’ll have a step-by-step financial roadmap to make smarter money decisions, avoid common financial mistakes, and build a stronger financial future.
What Is Financial Planning?
Financial planning is the strategic process of managing your income, expenses, savings, investments, insurance, taxes, and future financial goals to achieve long-term financial security. Instead of making random money decisions, it provides a structured roadmap that helps you spend wisely, save consistently, invest intelligently, and prepare for life’s expected and unexpected financial challenges.
For beginners, financial planning is not about becoming rich overnight or making complicated investments. It starts with understanding your current financial situation, setting realistic goals, creating a budget, building an emergency fund, managing debt, and investing consistently. Whether you’re a student, a salaried employee, a freelancer, or a business owner, having a financial plan gives every dollar a purpose and helps you make smarter financial decisions.
Think of financial planning as a GPS for your financial journey. Just as you wouldn’t start a long road trip without knowing your destination, you shouldn’t make important money decisions without a clear financial plan. A proper plan keeps you focused on your goals while reducing financial stress and avoiding costly mistakes.
Why Is Financial Planning Important?
Financial planning helps you stay in control of your money instead of letting your money control you. It creates a balance between your current lifestyle and your future financial goals while protecting you from unexpected financial emergencies.
Helps you understand your complete financial situation.
Creates a realistic monthly budget.
Builds an emergency fund for unexpected expenses.
Reduces unnecessary debt and financial stress.
Improves your saving habits.
Helps you invest according to your goals.
Protects your family with proper insurance planning.
Builds long-term wealth through disciplined investing.
Prepares you for retirement and major life events.
Key Components of Financial Planning
A successful financial plan consists of several interconnected areas. Ignoring even one of them can affect your overall financial health.
1. Income Management
The first step is understanding your income sources and managing them efficiently. Knowing exactly how much money you earn each month allows you to create realistic financial goals and spending plans.
Managing debt wisely allows more of your income to be used for saving and investing instead of paying interest. Paying off high-interest debt should always be a priority.
5. Investment Planning
Investing helps your money grow over time and protects it against inflation. If you’re just getting started, our explains the basics in simple language.
6. Insurance and Risk Management
Insurance protects your financial future from unexpected events. Health, life, and disability insurance reduce financial risk and protect your long-term wealth.
7. Retirement Planning
Retirement planning ensures financial independence later in life. Starting early allows compound growth to work in your favor, making it easier to build long-term wealth.
Financial Planning vs Budgeting vs Investing
Financial Planning
Budgeting
Investing
Creates an overall financial roadmap.
Controls monthly income and expenses.
Grows your wealth over time.
Focuses on long-term financial goals.
Focuses on short-term cash flow.
Focuses on increasing asset value.
Includes budgeting, saving, insurance, debt, and investing.
Focuses mainly on spending and saving.
Focuses on stocks, mutual funds, ETFs, bonds, and other investments.
Real-Life Example
Imagine two friends earning the same salary. The first spends money without tracking expenses, saves only when money is left over, and invests randomly. The second creates a budget, builds an emergency fund, pays off high-interest debt, invests every month, and reviews financial goals regularly. After several years, the second person is far more likely to achieve financial stability and long-term wealth—not because they earned more, but because they followed a financial plan.
Common Myths About Financial Planning
Financial planning is only for wealthy people.
You need a high income before creating a financial plan.
Financial planning only means investing in the stock market.
Budgeting alone is enough to achieve financial success.
Financial planning is something you only do once.
In reality, financial planning is a continuous process that evolves as your income, expenses, responsibilities, and financial goals change over time.
Expert Tips for Beginners
Pay yourself first by saving before spending.
Review your budget every month.
Build an emergency fund before making risky investments.
Invest consistently instead of trying to time the market.
Review your financial plan at least once every six months.
Quick Checklist
✔ Know your monthly income.
✔ Track your expenses.
✔ Create a realistic budget.
✔ Build an emergency fund.
✔ Eliminate high-interest debt.
✔ Start investing consistently.
✔ Protect yourself with insurance.
✔ Review your financial plan regularly.
Key Takeaways
Financial planning is a complete strategy for managing money effectively.
It combines budgeting, saving, investing, insurance, debt management, and retirement planning.
Anyone can start financial planning regardless of income.
Small, consistent financial decisions often produce significant long-term results.
Reviewing and improving your financial plan regularly is essential for achieving financial success.
Now that you understand what financial planning is, let’s explore why financial planning is important and how it can transform your financial future.
Why Is Financial Planning Important?
Financial planning is more than just saving money—it is about creating a roadmap for your financial future. Without a proper plan, even people with high incomes can struggle to achieve financial freedom because they spend without clear priorities. A well-designed financial plan helps you manage your income wisely, prepare for emergencies, reduce debt, build wealth, and achieve long-term financial goals with confidence.
Whether you are a student, salaried employee, freelancer, or business owner, financial planning gives every dollar a purpose. Instead of wondering where your money disappeared each month, you gain complete control over your finances and make decisions that support your future.
If you’re finding it difficult to control your monthly expenses, read our How to Manage Your Salary guide to build a stronger financial foundation.
1. Gives You Complete Control Over Your Money
Financial planning allows you to understand exactly how much money you earn, spend, save, and invest. This awareness helps eliminate unnecessary expenses and improves your financial discipline.
Track monthly income and expenses.
Reduce impulse spending.
Create better money habits.
Increase monthly savings.
2. Helps You Achieve Financial Goals Faster
Whether your goal is buying a house, starting a business, traveling the world, or retiring early, financial planning breaks large goals into smaller, achievable milestones.
Examples of Financial Goals
Build a $1,000 emergency fund.
Save for higher education.
Buy your first home.
Become debt-free.
Create passive income.
Retire comfortably.
3. Protects You During Financial Emergencies
Unexpected events such as medical bills, job loss, or major repairs can disrupt your finances. A financial plan includes an emergency fund that helps you handle these situations without relying on high-interest debt.
Money is one of the biggest causes of stress. When you know your financial position and have a clear action plan, you feel more confident and make better financial decisions.
5. Helps You Build Long-Term Wealth
Saving alone is not enough. Financial planning combines budgeting, saving, investing, insurance, and tax planning to help your money grow over time through compound growth.
Financial planning gives your money a clear direction.
It helps you achieve goals while reducing financial stress.
Emergency savings and investing are equally important.
Consistent planning leads to long-term financial security.
According to the Consumer Financial Protection Bureau (CFPB), creating a financial plan and reviewing it regularly helps individuals make informed financial decisions and prepare for future financial needs.
Next, let’s understand the 10 simple steps you can follow to create your own financial plan from scratch.
Step 3: Build an Emergency Fund Before You Invest
One of the biggest financial mistakes beginners make is investing before creating an emergency fund. While investing helps grow your wealth, it cannot replace cash that is immediately available during unexpected situations.
An emergency fund acts as your financial safety net. It protects you from debt, high-interest loans, and financial stress when life takes an unexpected turn.
What Is an Emergency Fund?
An emergency fund is money set aside only for unexpected expenses such as:
Medical emergencies
Job loss
Car or bike repairs
Home maintenance
Family emergencies
Urgent travel expenses
Never use this money for shopping, vacations, or entertainment.
How Much Should You Save?
A good rule is to save enough to cover 3–6 months of essential living expenses.
For example:
Monthly expenses: $800
Emergency fund goal:
Minimum: $2,400
Ideal: $4,800
If you’re just starting, don’t wait until you can save the full amount.
Start with your first milestone:
$100
$250
$500
$1,000
Small wins create long-term financial discipline.
Where Should You Keep Your Emergency Fund?
Keep your emergency money somewhere safe and easily accessible.
Good options include:
High-yield savings account
Cash management account
Money market account
Avoid keeping emergency funds in stocks or other volatile investments because their value can fall when you need the money most.
Common Mistakes Beginners Make
Investing without any emergency savings
Using credit cards for emergencies
Spending emergency money on non-essential purchases
Keeping all savings in risky investments
Never replenishing the emergency fund after using it
Quick Action Plan
✔ Calculate your monthly essential expenses.
✔ Set a realistic emergency savings goal.
✔ Automate a fixed amount every month.
✔ Use the fund only for real emergencies.
✔ Rebuild the fund immediately after withdrawing money.
Pro Tip: Build your emergency fund first. Once you have a strong financial safety net, you can invest with greater confidence and avoid selling investments during difficult times.
A budget is the foundation of every successful financial plan. No matter how much you earn, if you don’t know where your money goes each month, building wealth becomes extremely difficult. A realistic monthly budget gives every dollar a purpose, helping you spend intentionally instead of emotionally.
Many people think budgeting is about restricting their lifestyle, but that’s a common misconception. In reality, a budget gives you more financial freedom because it allows you to spend confidently while ensuring your essential expenses, savings, and investments remain on track.
If you’ve ever wondered where your salary disappears before the end of the month, it’s time to create a budget that works for your lifestyle—not against it.
Need help managing your monthly income? Read our How to Manage Your Salary guide for practical strategies.
Why Budgeting Is Important
A monthly budget acts as a financial blueprint. Instead of reacting to expenses, you plan them in advance and stay in control of your money.
Track every dollar you earn.
Reduce unnecessary spending.
Increase monthly savings.
Avoid overspending.
Achieve financial goals faster.
Reduce money-related stress.
How to Create a Budget in 5 Simple Steps
1. Calculate Your Monthly Income
Start by adding all reliable sources of income, including salary, freelance work, side hustles, rental income, or business earnings.
2. List Every Monthly Expense
Separate your expenses into fixed and variable categories.
Housing
Utilities
Transportation
Groceries
Insurance
Entertainment
Shopping
Subscriptions
3. Follow the 50/30/20 Budget Rule
Category
Percentage
Purpose
Needs
50%
Housing, food, bills, transportation
Wants
30%
Entertainment, shopping, dining out
Savings & Investing
20%
Emergency fund, investments, retirement
The 50/30/20 rule is a helpful starting point, but you can adjust the percentages based on your income, financial goals, and living expenses.
4. Track Your Spending Every Week
Review your expenses weekly instead of waiting until the end of the month. This helps you identify unnecessary spending before it becomes a habit.
5. Adjust and Improve Every Month
A budget isn’t permanent. As your income, expenses, and financial goals change, your budget should evolve too.
Real-Life Example
Imagine David earns $3,000 every month. Before budgeting, he often ran out of money before payday. After following a monthly budget, he reduced unnecessary subscriptions and impulse purchases, increased his monthly savings, and started investing consistently. Within a year, he had built a healthy emergency fund and significantly improved his financial confidence.
Common Budgeting Mistakes
Not tracking daily expenses.
Ignoring small purchases.
Creating an unrealistic budget.
Forgetting irregular yearly expenses.
Never reviewing the budget.
Expert Tips
Automate your savings first.
Review your budget every Sunday.
Keep entertainment spending within limits.
Increase savings whenever your income grows.
Use budgeting apps or spreadsheets to monitor expenses.
According to the Consumer Financial Protection Bureau (CFPB), maintaining a monthly budget is one of the most effective ways to improve financial well-being and achieve long-term financial goals.
Key Takeaways
A budget gives every dollar a purpose.
Track your spending consistently.
Review and improve your budget every month.
Small budgeting habits create long-term financial success.
Next Step: Now that you’ve created a realistic budget, it’s time to build a strong emergency fund that protects your financial future.
Manage and Eliminate Debt Wisely
Managing debt is one of the most important parts of financial planning for beginners. Many people focus only on earning more money, but building wealth becomes difficult if a large part of your income goes toward loan payments, credit card bills, or other debts. A smart financial plan helps you reduce debt strategically so you can save, invest, and achieve your financial goals faster.
Why Debt Management Matters
Not all debt is bad. A home loan or education loan can help build your future, but high-interest debt such as credit card balances and personal loans can slow your financial growth. Paying these off early gives you more financial freedom and reduces stress.
Types of Debt You Should Know
Good Debt
Education loans
Home loans
Business loans used for growth
Bad Debt
High-interest credit cards
Personal loans for unnecessary expenses
Buy Now Pay Later (BNPL) purchases without a repayment plan
How to Eliminate Debt Faster
1. List Every Debt
Write down each loan with its total balance, interest rate, and minimum monthly payment. This helps you see the complete picture.
2. Pay High-Interest Debt First
Use the Debt Avalanche Method by paying extra toward the loan with the highest interest rate while making minimum payments on the others. This saves the most money over time.
3. Avoid Taking New Debt
Reduce unnecessary spending and avoid borrowing for non-essential purchases until your existing debt is under control.
4. Make Extra Payments Whenever Possible
Use bonuses, tax refunds, freelance income, or any extra earnings to reduce your loan principal faster.
Real-Life Example
Imagine you have a credit card balance with a high interest rate and a small education loan. By paying extra toward the credit card first while continuing minimum payments on the education loan, you reduce interest costs and become debt-free sooner.
Common Debt Management Mistakes
Paying only the minimum amount every month
Ignoring high-interest debt
Borrowing to repay another loan
Using credit cards for everyday expenses without a repayment plan
Not tracking loan balances regularly
Expert Tips
Keep your monthly debt payments below 35% of your income whenever possible.
Set up automatic payments to avoid late fees.
Review your debt every month and celebrate small milestones to stay motivated.
Key Takeaways
Eliminate high-interest debt first.
Avoid unnecessary borrowing.
Make extra payments whenever you can.
A strong debt management strategy creates more room for saving and investing.
Related Guide: Read our complete guide on How to Manage Your Salary to improve your monthly cash flow.
Saving money protects your finances, but investing helps your money grow over time. If you want to build long-term wealth, beat inflation, and achieve major financial goals, investing should become an essential part of your financial planning. The earlier you start, the more time your money has to benefit from compound growth.
Why Investing Is Important
Many beginners keep all their money in a savings account. While savings are important for emergencies, they usually don’t generate enough returns to build significant wealth. Investing allows your money to work for you instead of sitting idle.
Where Should Beginners Invest?
1. Mutual Funds
Mutual funds are one of the easiest investment options for beginners. You can start with a small monthly SIP and let professional fund managers handle your investments.
2. Index Funds
Index funds track the overall market and usually have lower fees. They are ideal for beginners who want long-term growth with minimal effort.
3. Stocks
Buying individual company shares can offer higher returns, but it also involves higher risk. Beginners should learn the basics before investing directly in stocks.
4. Fixed-Income Investments
Fixed deposits and government-backed savings schemes provide stable returns and are suitable for short-term or low-risk financial goals.
Investment Mistakes Beginners Should Avoid
Investing without clear financial goals.
Trying to become rich overnight.
Following social media tips without research.
Investing money needed for emergencies.
Selling investments during short-term market declines.
Real-Life Example
Suppose you invest a fixed amount every month through a SIP instead of waiting for the “perfect time.” Over several years, consistent investing and compound growth can build significantly more wealth than keeping the same money in a regular savings account.
Expert Tips
Start investing as early as possible.
Invest regularly instead of timing the market.
Diversify your investments across different assets.
Review your portfolio once or twice a year.
Stay invested for the long term.
Key Takeaways
Investing is essential for long-term wealth creation.
Protect Your Financial Future with the Right Insurance
A complete financial planning for beginners guide is not only about saving and investing. It is also about protecting everything you have built. A single medical emergency, accident, or unexpected event can destroy years of savings if you are not properly insured. That’s why insurance is an essential part of every financial planning process.
Why Is Insurance Important in Financial Planning?
Insurance protects your income, savings, investments, and family from unexpected financial risks. Instead of paying huge expenses from your own pocket, insurance helps reduce the financial burden and keeps your long-term financial goals on track.
Types of Insurance Every Beginner Should Consider
1. Health Insurance for Financial Security
Health insurance is one of the first policies every beginner should have. Medical costs continue to rise every year, and a good health insurance plan protects your savings from unexpected hospital bills.
2. Life Insurance for Family Protection
If your family depends on your income, life insurance provides financial support to your loved ones if something unexpected happens to you. A term life insurance plan is often the most affordable option for beginners.
3. Vehicle Insurance to Avoid Financial Losses
If you own a bike or car, vehicle insurance protects you from repair costs, accidents, and legal liabilities. It is also mandatory in many countries.
4. Property and Home Insurance
Home insurance protects your house and valuable belongings from fire, theft, natural disasters, and other unexpected events.
How Much Insurance Do You Need?
The right insurance coverage depends on your income, financial responsibilities, existing savings, debts, and family needs. Review your insurance requirements regularly as your financial situation changes.
Common Insurance Mistakes Beginners Make
Buying insurance only to save tax.
Delaying health insurance until later in life.
Choosing the cheapest policy without comparing coverage.
Ignoring policy exclusions and claim conditions.
Never reviewing insurance after major life changes.
Expert Tips for Choosing the Right Insurance
Buy insurance before investing aggressively.
Compare multiple insurance providers before purchasing.
Read the policy terms carefully.
Review your coverage every year.
Keep all insurance documents organized and updated.
Key Takeaways
Insurance protects your financial future from unexpected risks.
Health insurance should usually be your first priority.
Life insurance is important if your family depends on your income.
Review your insurance coverage regularly as your financial goals change.
Creating a financial plan is only the beginning. To achieve long-term success, you must review and improve your plan regularly. Your income, expenses, financial goals, investments, and responsibilities will change over time, so your financial plan should evolve as well.
Many beginners create a budget or investment plan once and never look at it again. This is one of the biggest mistakes in financial planning for beginners. Regular reviews help you identify problems early, adjust your strategy, and stay on track toward your financial goals.
Why Is Reviewing Your Financial Plan Important?
A financial plan is not a one-time document—it is a living strategy. Reviewing it regularly helps you adapt to life’s changes and make smarter financial decisions.
Benefits of reviewing your financial plan include:
Stay focused on your financial goals.
Adjust your budget as your income changes.
Track your savings and investment progress.
Identify unnecessary expenses.
Improve your long-term financial security.
Reduce financial mistakes before they become costly.
What Should You Review Every Month?
1. Review Your Monthly Budget
Compare your planned budget with your actual spending. Look for areas where you consistently overspend and make adjustments for the next month.
2. Review Your Savings Progress
Check whether you’re consistently contributing to your emergency fund, retirement savings, and other financial goals.
3. Review Your Investments
Monitor your portfolio’s performance without reacting to short-term market movements. Focus on whether your investments still match your goals and risk tolerance.
4. Review Your Debt
Track your outstanding balances, interest rates, and repayment progress. If possible, increase your monthly payments to become debt-free faster.
5. Review Your Financial Goals
As your career, family, or lifestyle changes, update your short-term and long-term financial goals to reflect your current priorities.
Annual Financial Planning Checklist
At least once a year, ask yourself:
Have I increased my savings rate?
Is my emergency fund still adequate?
Do I have the right insurance coverage?
Am I investing enough for retirement?
Have I reduced unnecessary debt?
Do my financial goals still reflect my priorities?
Common Financial Planning Mistakes
Never reviewing your budget.
Ignoring lifestyle inflation after salary increases.
Making emotional investment decisions.
Forgetting to update financial goals.
Delaying important financial decisions.
Expert Tips
Schedule a monthly “Money Review Day.”
Review your net worth every six months.
Increase your investments whenever your income grows.
Rebalance your investment portfolio once a year.
Keep learning about personal finance to improve your financial decisions.
Key Takeaways
Financial planning is an ongoing process, not a one-time task.
Small monthly improvements lead to significant long-term results.
Regular reviews help you stay aligned with your financial goals.
Continuous learning and disciplined habits are the foundation of financial success.
External Resource: The Consumer Financial Protection Bureau (CFPB) recommends reviewing your financial goals, spending, savings, and debt regularly to maintain long-term financial well-being.
Step 10: Take Action and Stay Consistent with Your Financial Plan
Creating a financial plan is an important achievement, but taking consistent action is what turns your plan into real financial success. Many people spend weeks learning about budgeting, investing, and saving, yet never implement what they learn. Knowledge alone doesn’t build wealth—consistent action does.
The most successful people in personal finance aren’t always those with the highest incomes. They’re the ones who follow good financial habits month after month, year after year. Small, consistent improvements often produce far better results than occasional large efforts.
Why Consistency Is the Key to Financial Success
Financial planning isn’t about making one perfect decision. It’s about making hundreds of small, smart decisions over time.
When you stay consistent, you can:
Build wealth steadily.
Develop strong financial habits.
Reduce financial stress.
Reach your financial goals faster.
Stay motivated during market ups and downs.
Build Daily and Monthly Financial Habits
Daily Financial Habits
Avoid impulse purchases.
Track your daily spending.
Spend intentionally instead of emotionally.
Weekly Financial Habits
Review your expenses.
Check your budget progress.
Identify unnecessary spending.
Monthly Financial Habits
Save before spending.
Invest consistently.
Pay bills on time.
Review your financial goals.
Update your budget if needed.
Continue Learning About Personal Finance
Financial planning is a lifelong journey. As markets, technology, and your personal circumstances change, continue improving your financial knowledge.
Consider learning about:
Investing
Tax planning
Insurance
Retirement planning
Passive income
Wealth management
The more you learn, the better financial decisions you’ll make.
Common Mistakes That Prevent Long-Term Success
Giving up after one bad month.
Frequently changing financial strategies.
Trying to get rich quickly.
Ignoring long-term goals.
Not reviewing financial progress regularly.
Expert Tips
Focus on progress, not perfection.
Automate your savings and investments.
Increase your investment amount whenever your income grows.
Celebrate small financial milestones.
Stay patient—wealth takes time to build.
Your 30-Day Financial Planning Challenge
Complete these actions over the next month:
✅ Create a monthly budget.
✅ Track every expense.
✅ Build or increase your emergency fund.
✅ Invest your first monthly contribution.
✅ Review your financial goals.
✅ Read one personal finance book or article each week.
Key Takeaways
Financial planning is a lifelong process.
Consistency beats perfection.
Small financial habits create long-term wealth.
Keep learning and improving your financial knowledge.
Take action today instead of waiting for the perfect time.
Financial planning for beginners doesn’t have to be complicated. By following the simple steps in this guide—understanding your current financial situation, setting SMART goals, tracking your income and expenses, creating a realistic budget, managing debt, investing for the future, protecting yourself with insurance, planning for retirement, and reviewing your progress regularly—you can build a strong financial foundation.
Remember, financial success is not about earning the highest income. It’s about making smart financial decisions consistently over time. Even small actions, such as saving a little more each month or investing regularly, can create significant results through discipline and the power of compound growth.
The best time to start your financial planning journey is today. Stay committed to your goals, continue learning, and review your financial plan regularly. With patience and consistency, you’ll be well on your way to achieving long-term financial security and financial freedom.
What Is Financial Planning for Beginners? Financial planning for beginners is the process of managing your income, expenses, savings, investments, insurance, and financial goals to build long-term financial security. It helps you create a budget, save consistently, reduce debt, invest wisely, and make better financial decisions for the future.
Why Is Financial Planning Important Financial planning is important because it helps you take control of your money, prepare for unexpected expenses, achieve your financial goals, and build long-term wealth. A solid financial plan also reduces financial stress and gives you confidence in your financial future.
How Do I Start Financial Planning with a Low Income You can start financial planning with a low income by tracking your expenses, creating a realistic budget, building an emergency fund, paying off high-interest debt, and investing small amounts consistently. Good financial habits matter more than a high income.
What Are the Five Steps of Financial Planning The five basic steps of financial planning are assessing your current financial situation, setting clear financial goals, creating a budget, saving and investing regularly, and reviewing your financial plan periodically. Following these steps helps you achieve long-term financial success.
How Often Should You Review Your Financial Plan You should review your financial plan every three to six months or whenever a major life event occurs, such as changing jobs, getting married, buying a home, or starting a family. Regular reviews help keep your budget, savings, investments, and financial goals on track.
Detailed Summary Financial planning for beginners is the foundation of long-term financial success. It is not just about creating a budget or saving money—it’s a complete process that helps you manage your income, control expenses, reduce debt, invest wisely, protect your finances, and achieve your short-term and long-term financial goals. In this guide, you first learned what financial planning is and why it is essential for building financial security. You then discovered how to assess your current financial situation by evaluating your income, expenses, savings, debts, and overall financial health. Understanding your current position is the first step toward making smarter financial decisions. Next, you explored how to set SMART financial goals that are specific, measurable, achievable, relevant, and time-bound. Clear goals give your money a purpose and help you stay focused on what matters most. You also learned the importance of tracking your income and expenses, creating a realistic monthly budget, and managing debt effectively. These habits help you improve cash flow, reduce unnecessary spending, and create more opportunities to save and invest. The guide also explained why investing is essential for long-term wealth creation, how insurance protects your financial future from unexpected risks, and why starting retirement planning early allows your investments to benefit from compound growth over time. Finally, you learned that financial planning is an ongoing process. Reviewing your financial plan regularly, adjusting it as your life changes, and staying consistent with good financial habits are the keys to achieving lasting financial success. Whether you’re starting with a small income or beginning your financial journey from scratch, following these practical steps can help you build a stronger financial future. Remember, successful financial planning is not about being perfect—it’s about making consistent, informed decisions that move you closer to financial freedom, one step at a time.
Hi, I’m Asif Khan, the voice behind paisakmao.de. For the past two years, I’ve been blogging about financial education, income skills, and mindset development for students and young minds. My mission is to empower every youth with financial literacy and practical money-making skills at an early age. Through paisakmao.de, I share actionable guides for students to start earning early, money wisdom that schools don’t teach, and mindset lessons from successful people and modern psychology. Whether you’re a teenager looking to earn your first income or a student exploring side hustles, you’re in the right place. Financial freedom begins with the right mindset and the right knowledge. Let’s grow, earn, and evolve together — welcome to the movement!
How to Budget with Managing money becomes difficult when your income is not the same every month. Unlike salaried employees who receive a fixed paycheck, people with irregular income often face uncertainty — one month can bring high earnings, while the next month may be much lower.
The biggest challenge is not only earning money; it is creating a system that works when your income changes.
Many people with irregular income make the mistake of spending more during good months and struggling during slow months. Without a proper budgeting system, even a good income can disappear quickly.
This is where irregular income budgeting becomes important.
Instead of creating a budget based on your highest earning month, you need a flexible system that helps you manage expenses, save money, and prepare for unpredictable income.
In this guide, you will learn a practical step-by-step method to create a budget for irregular income, including how to calculate your minimum monthly expenses, manage variable spending, build an income buffer, and create a stable financial plan.
Whether you are a freelancer, self-employed professional, business owner, content creator, or anyone with changing income, this guide will help you take control of your money.
Now let’s start with the first and most important step: calculating your Minimum Monthly Expenses (Survival Budget).
What You Will Learn in This Guide
In this complete guide to budgeting with irregular income, you will learn:
How to calculate your minimum monthly expenses.
How to create a Survival Budget that works during low-income months.
How to separate essential expenses from unnecessary spending.
How to manage variable income without financial stress.
How to build an income buffer for unpredictable months.
How to create a long-term money management system.
This guide focuses on practical strategies that you can apply immediately, not just general budgeting advice.
Whether your income changes every week, every month, or seasonally, these methods will help you create a flexible financial system.
Now let’s start with the first step: calculating your Minimum Monthly Expenses (Survival Budget).
Step 1: Calculate Your Minimum Monthly Expenses (Survival Budget)
When your income changes every month, the first step is not deciding how much you should spend — it is understanding the minimum amount of money you actually need to run your life.
This amount is called your Survival Budget.
Your Survival Budget is the foundation of an effective irregular income budgeting system. It tells you the minimum money required to cover your essential expenses before you spend on lifestyle choices, entertainment, or other non-essential things.
For freelancers, self-employed professionals, business owners, and anyone with variable income, this system creates financial stability because you stop depending on your best earning months.
Why Your Survival Budget Is Important
Many people with irregular income follow an unstable money pattern:
The problem is not always income. The problem is not knowing your minimum financial requirement.
A Survival Budget helps you understand:
The minimum income you need every month.
Which expenses must be protected first.
How much extra money you can save or invest.
How to prepare for months when income is lower.
For example, if your minimum monthly expenses are $1,800, then your first financial target is not buying luxury items or increasing your lifestyle — it is securing that $1,800 amount first.
These expenses usually remain the same every month:
Rent or mortgage
Insurance
Phone and internet bills
Loan payments
Essential Variable Expenses
These expenses change but are necessary:
Groceries
Transportation
Electricity
Healthcare
Household needs
Minimum Financial Payments
Include all payments you cannot skip:
Credit card minimum payments
Loan installments
Other required payments
How to Calculate Your Minimum Monthly Expenses
1. Review Your Last 3–6 Months Spending
The first step is understanding your real spending pattern.
Check:
Bank statements
Payment apps
Credit card history
Expense tracking records
Write down every expense, including small purchases.
Many people underestimate small expenses because they seem insignificant. However, repeated small spending can reduce your savings significantly over time.
2. Separate Needs From Wants
After collecting your expenses, divide them into two categories.
Essential Expenses (Needs)
These are expenses required for your basic lifestyle:
Housing
Food
Utilities
Transportation
Healthcare
Insurance
Non-Essential Expenses (Wants)
These expenses are optional:
Eating outside
Entertainment
Shopping
Premium subscriptions
Luxury purchases
Reducing unnecessary expenses does not mean removing all enjoyment. It means creating space for your important financial goals.
This means you need at least $1,700 before spending money on optional things.
Any income above this amount can be used for:
Emergency savings
Investments
Debt reduction
Future low-income months
Common Mistakes To Avoid
Avoid these mistakes while creating your Survival Budget:
Planning your lifestyle around your highest income month.
Ignoring small recurring expenses.
Spending extra income immediately.
Not tracking your monthly cash flow.
Mixing business and personal expenses.
A proper Survival Budget protects you from financial uncertainty and gives you more control over your money.
Action Plan: Create Your Survival Budget Today
Follow these steps:
✅ Review your last 3–6 months of expenses. ✅ Write down every monthly cost. ✅ Separate needs and wants. ✅ Add only essential expenses. ✅ Calculate your Survival Budget number. ✅ Use this number as the base of your irregular income budget.
Once you know your Survival Budget, the next step is to calculate your Baseline Income — the income level you should target to create a stable financial system even when your earnings change every month.
Step 2: Calculate Your Baseline Income
Once you know your Survival Budget, the next step is to calculate your Baseline Income. This is one of the most important parts of budgeting with irregular income because it gives you a realistic income target instead of relying on your best earning month.
Many people make the mistake of planning their budget around the highest amount they have ever earned. For example, if you earned $5,000 last month, it’s easy to assume you’ll earn the same again. But irregular income rarely works that way. Some months are excellent, while others are much slower.
Your Baseline Income is the amount you can reasonably expect to earn on a consistent basis. It becomes the foundation for your monthly budget, savings plan, and financial decisions. Instead of chasing unpredictable numbers, you build your budget around a realistic average that keeps your finances stable throughout the year.
Why Your Baseline Income Matters
A Baseline Income helps you answer one simple question:
“How much money can I safely plan to spend every month?”
Without knowing this number, it becomes easy to overspend during good months and struggle during slow months.
Start by gathering your income from the last 6–12 months.
This may include:
Client payments
Freelance income
Business revenue
Commission earnings
Side hustle income
Part-time work
The longer the time period you review, the more accurate your Baseline Income will be.
2. Calculate Your Average Monthly Income
Add all your income from the past 6–12 months and divide it by the number of months.
Formula:
Baseline Income = Total Income ÷ Number of Months
Example:
Month
Income
January
$3,500
February
$2,400
March
$4,100
April
$2,800
May
$3,200
June
$3,000
Total Income = $19,000
Baseline Income = $19,000 ÷ 6 = $3,166
Instead of budgeting as if you’ll earn $4,100 every month, you should build your budget around $3,166, because it reflects your average earning pattern.
Don’t Budget Using Your Best Month
One of the biggest financial mistakes is treating your highest-income month as your normal income.
A better strategy is:
Budget using your Baseline Income.
Save extra income during high-earning months.
Use those savings to support low-income months.
This simple system creates consistency, even when your income is unpredictable.
Before moving to the next step, complete these tasks:
✅ Review your last 6–12 months of income.
✅ Add every income source.
✅ Calculate your average monthly income.
✅ Use this number as your Baseline Income.
✅ Ignore unusually high-income months when creating your budget.
Next Step: Now that you know your Baseline Income, the next step is to prioritize your expenses using a flexible budgeting system that works even when your income changes every month.
Step 3: Prioritize Essential Expenses First
Now that you know your Survival Budget and Baseline Income, it’s time to decide where your money should go first.
One of the biggest reasons people with irregular income struggle financially is not because they earn too little—but because they spend money in the wrong order.
Many people pay for shopping, entertainment, subscriptions, or lifestyle upgrades as soon as they receive income. Later, when rent, groceries, or utility bills are due, they find themselves short of cash.
A better approach is to prioritize your expenses based on importance, not urgency.
This simple habit ensures that even during a low-income month, your essential needs are always covered before you spend money on anything optional.
Why Prioritizing Expenses Is So Important
When your income changes every month, you cannot afford to treat every expense equally.
Some expenses keep your life running, while others simply make life more enjoyable.
If you pay for optional expenses before covering your basic needs, you’ll constantly feel financial pressure.
By prioritizing your expenses, you can:
Always pay your essential bills first.
Reduce financial stress during slow months.
Avoid relying on credit cards or loans.
Build better money habits.
Create a stable financial system even with unpredictable income.
Next Step: Now that your expenses are organized by priority, the next step is to build an Income Buffer that protects you during slow-income months and gives you greater financial confidence.
Step 4: Build an Income Buffer for Low-Income Months
By now, you’ve calculated your Survival Budget, estimated your Baseline Income, and learned how to prioritize essential expenses. The next step is creating an Income Buffer—a financial cushion that helps you stay stable during months when your income is lower than expected.
For people with irregular income, earning less in some months is completely normal. The real problem begins when there is no money set aside to cover essential expenses. That’s where an Income Buffer becomes one of the most powerful tools in your budgeting system.
Instead of worrying about whether next month’s income will be enough, you can use the money you’ve saved during high-income months to cover the gap. This creates peace of mind and helps you avoid borrowing money or using credit cards for everyday expenses.
Why an Income Buffer Is Important
An Income Buffer protects your monthly budget from unexpected income fluctuations.
Whether you’re a freelancer, self-employed professional, content creator, consultant, or seasonal worker, your income can change for many reasons—fewer clients, seasonal demand, delayed payments, or economic changes.
Without an Income Buffer, even a small drop in income can affect your ability to pay rent, buy groceries, or cover utility bills.
With an Income Buffer, your financial life becomes much more predictable because you already have money reserved for slower months.
According to the Consumer Financial Protection Bureau (CFPB), setting aside money for unexpected situations helps reduce financial stress and improves long-term financial stability.
How to Build an Income Buffer
1. Set a Clear Savings Target
Start with a realistic goal.
If you’re just beginning, aim to save enough money to cover one month of your Survival Budget.
Once you reach that goal, gradually increase it to cover:
One month of essential expenses.
Three months of essential expenses.
Six months of essential expenses for greater financial security.
Don’t try to save everything at once. Building an Income Buffer is a gradual process.
2. Save Extra Income During High-Earning Months
One of the biggest advantages of irregular income is that some months can be much better than others.
Instead of increasing your lifestyle during those months, save a portion of the extra income.
For example:
Survival Budget: $2,000
Monthly Income: $3,500
Instead of spending the extra $1,500, move part of it into your Income Buffer.
Over time, these small contributions create a strong financial cushion.
3. Keep Your Income Buffer Separate
Avoid keeping your Income Buffer in the same account you use for daily spending.
A separate high-yield savings account or dedicated savings account makes it less tempting to spend the money on non-essential purchases.
The FDIC Money Smart Program also encourages building healthy saving habits and keeping emergency savings separate from everyday spending.
4. Rebuild Your Buffer After Using It
An Income Buffer is meant to be used when income falls—not for shopping, vacations, or impulse purchases.
If you use part of your buffer during a slow month, make rebuilding it your priority during the next high-income month.
This keeps your financial safety net ready for future income fluctuations.
Real-Life Example
Imagine David is a freelance photographer.
His average monthly income is around $3,200, but some months he earns only $1,800.
His Survival Budget is $2,000.
During a busy wedding season, David saves an extra $600 every month into his Income Buffer.
A few months later, when business slows down, he uses the buffer to cover the difference instead of borrowing money or missing bill payments.
Because he planned ahead, his lifestyle remains stable even when his income changes.
Common Mistakes to Avoid
Avoid these mistakes when building your Income Buffer:
Spending all extra income during good months.
Keeping your buffer in your daily spending account.
Using the buffer for luxury purchases.
Stopping contributions after reaching your first savings goal.
Waiting for a financial emergency before starting to save.
Action Plan
Before moving to the next step, complete these tasks:
✅ Calculate your first Income Buffer target.
✅ Open a separate savings account if possible.
✅ Save a portion of every high-income month.
✅ Use the buffer only when your income falls below your normal level.
✅ Rebuild your buffer immediately after using it.
For more practical guidance on building emergency savings and financial resilience, you can also explore: MyMoney.gov – Emergency Funds.
Next Step: Once you have an Income Buffer in place, the next step is to create a Zero-Based Budget so every dollar you earn has a clear purpose and nothing is wasted.
Step 5: Use the Zero-Based Budgeting Method
Now that you have a Survival Budget, a realistic Baseline Income, prioritized your expenses, and built an Income Buffer, it’s time to give every dollar a specific purpose.
This is where the Zero-Based Budgeting Method becomes one of the most effective budgeting strategies for people with irregular income.
Despite its name, Zero-Based Budgeting does not mean your bank account should reach zero. It simply means every dollar you earn is assigned a job before you spend it.
Instead of wondering where your money went at the end of the month, you decide in advance where every dollar will go. This gives you complete control over your finances and reduces unnecessary spending.
Why Zero-Based Budgeting Works for Irregular Income
When your income changes every month, spending money without a plan can quickly create financial problems.
Zero-Based Budgeting helps you:
Give every dollar a clear purpose.
Avoid impulse spending.
Control lifestyle inflation.
Save consistently during high-income months.
Stay organized even when your income fluctuates.
Unlike traditional budgeting, this method is flexible. Each month, you create a new budget based on the income you actually expect to receive instead of using the same budget every month.
It means every dollar has already been assigned to a category before you begin spending.
For example:
Monthly Baseline Income: $3,200
Housing: $900
Groceries: $350
Utilities: $180
Transportation: $170
Insurance: $120
Debt Payments: $200
Emergency Savings: $300
Investments: $400
Personal Spending: $280
Miscellaneous: $300
Money Remaining = $0
Every dollar now has a purpose.
How to Apply Zero-Based Budgeting
1. Start With Your Baseline Income
Never create your budget using your highest earning month.
Instead, use the Baseline Income you calculated in Step 2.
This makes your budget realistic and easier to follow.
2. Fund Essential Expenses First
Your first responsibility is covering your Survival Budget.
Always fund:
Housing
Food
Utilities
Transportation
Insurance
Minimum debt payments
Only after these expenses are covered should you move to savings, investing, and lifestyle spending.
3. Give Every Remaining Dollar a Job
Extra income should never remain “unplanned.”
Assign every remaining dollar to one of these categories:
Income Buffer
Emergency Fund
Investments
Debt repayment
Business growth
Personal goals
A clear plan prevents unnecessary spending and keeps your financial priorities on track.
Real-Life Example
Sarah is a freelance graphic designer.
Her Baseline Income is $2,800 per month.
Instead of spending money as clients pay her, she creates a Zero-Based Budget before the month begins.
She first funds her essential expenses, then adds money to her Income Buffer, contributes to her investments, and finally sets aside a small amount for entertainment.
When unexpected expenses arise, she already knows where her money is allocated, so she avoids using credit cards unnecessarily.
Common Mistakes to Avoid
Avoid these common mistakes:
Creating a budget after spending your money.
Forgetting to budget for savings.
Leaving extra income without a purpose.
Budgeting based on your highest-income month.
Not reviewing your budget when your income changes.
Next Step: Now that every dollar has a purpose, the next step is learning how to manage separate bank accounts for spending, savings, and taxes, making your irregular income even easier to control.
Step 6: Create Separate Accounts for Spending, Savings, and Taxes
One of the smartest habits of people who successfully manage irregular income is keeping their money organized. Instead of using one bank account for everything, they divide their money into separate accounts with a specific purpose.
When all of your income stays in one account, it’s easy to lose track of how much money is actually available to spend. You may accidentally use money meant for taxes, emergency savings, or future bills.
Creating separate accounts gives every part of your money a clear destination. This simple system reduces financial mistakes, improves cash flow, and makes budgeting much easier.
Why Separate Bank Accounts Matter
People with fixed salaries usually know exactly when and how much money they will receive. However, freelancers, self-employed professionals, creators, consultants, and small business owners often receive payments at different times and in different amounts.
Without a clear system, all your income mixes together, making it difficult to know:
How much you can safely spend.
How much should be saved.
How much belongs to future taxes.
How much is available for investing.
Separating your money creates financial discipline and reduces the temptation to spend savings on everyday purchases.
According to the Consumer Financial Protection Bureau (CFPB), organizing your finances and planning ahead can make budgeting easier and help you stay on track with your financial goals.
The 4-Account Money Management System
You don’t need dozens of accounts. For most people with irregular income, four accounts are enough.
1. Spending Account
This is your everyday account.
Use it only for:
Rent
Groceries
Utilities
Transportation
Healthcare
Daily living expenses
Transfer only your planned monthly spending amount into this account.
Once the money is used, avoid moving extra money from your savings unless it’s absolutely necessary.
2. Emergency Savings Account
This account is for unexpected situations, not everyday spending.
Examples include:
Medical emergencies
Emergency home repairs
Temporary income loss
Unexpected travel
Keep this money separate so you’re less likely to spend it impulsively.
3. Tax Account
If you’re self-employed, a freelancer, or a business owner, taxes should never be treated as spending money.
Every time you receive a payment, move a percentage into a dedicated tax account.
This simple habit prevents financial stress when tax payments become due.
Next Step: Once your money is organized into separate accounts, the next step is learning how to save more during high-income months so you can stay financially secure when income slows down.
Step 7: Save Extra Income During High-Earning Months
One of the biggest advantages of having an irregular income is that some months can bring significantly higher earnings than others. However, this advantage can quickly become a financial problem if you spend the extra money instead of preparing for future slow months.
Many freelancers, business owners, creators, and self-employed professionals celebrate a high-income month by upgrading their lifestyle. They buy expensive gadgets, eat out more often, or increase their monthly spending. When the next month brings lower income, they struggle to pay even their essential bills.
A smarter strategy is to treat every high-income month as an opportunity to strengthen your financial future—not your lifestyle.
Why Saving Extra Income Is So Important
Irregular income is unpredictable by nature. You cannot always control when clients pay you, how much business you’ll receive, or whether demand will slow down.
What you can control is what you do with the extra money you earn during good months.
Saving part of your extra income helps you:
Prepare for low-income months.
Reduce financial stress.
Avoid unnecessary debt.
Build long-term financial security.
Reach your financial goals faster.
According to the Consumer Financial Protection Bureau (CFPB), consistently setting aside money improves financial resilience and helps people handle unexpected financial challenges.
Follow the “Save First, Spend Later” Rule
Many people save whatever money is left at the end of the month.
Successful money management works the opposite way.
As soon as you receive a larger-than-normal payment:
Cover your essential expenses.
Add money to your Income Buffer.
Increase your emergency savings.
Invest toward your long-term goals.
Spend only the remaining amount.
This approach ensures that your future is funded before your lifestyle.
How Much Should You Save?
There isn’t one percentage that works for everyone, but having a target makes saving easier.
For example:
Save 20–30% of extra income if you’re still building an Income Buffer.
Save 30–50% if your emergency savings are not yet complete.
Invest a portion after your essential savings goals are covered.
The exact percentage depends on your financial situation, but consistency matters more than perfection.
Real-Life Example
Imagine Alex owns a small online business.
His average monthly income is $3,000, but during a holiday season he earns $5,500.
Instead of increasing his spending, Alex follows a simple plan:
Pays all essential expenses.
Adds money to his Income Buffer.
Increases his emergency savings.
Invests part of the remaining income.
Keeps a small amount for personal enjoyment.
A few months later, when sales slow down, he continues paying his bills without financial stress because he planned ahead.
Common Mistakes to Avoid
Avoid these common mistakes during high-income months:
Assuming every month will be equally profitable.
Increasing your lifestyle too quickly.
Spending bonuses immediately.
Ignoring future slow seasons.
Saving only when it’s convenient.
Small, consistent decisions during good months often determine your financial stability during difficult months.
Action Plan
Complete these steps whenever you earn more than usual:
✅ Cover your Survival Budget first.
✅ Add money to your Income Buffer.
✅ Increase your emergency savings.
✅ Invest toward your long-term goals.
✅ Spend only what remains after your priorities are funded.
For additional guidance on building healthy saving habits, you can also explore: MyMoney.gov – Save Money.
Next Step: Now that you’ve learned how to use high-income months wisely, the next step is to track your income and expenses regularly so you can identify spending patterns and improve your budget over time.
Step 8: Track Your Income and Expenses Every Week
Creating a budget is only the beginning. The real difference comes from tracking your income and expenses consistently.
For people with irregular income, waiting until the end of the month to review finances is often too late. By then, you may have already overspent or missed opportunities to save.
A simple weekly money review helps you stay in control of your cash flow, spot spending problems early, and make better financial decisions before small mistakes become expensive ones.
Instead of asking, “Where did all my money go?”, you’ll know exactly where every dollar was earned and spent.
Why Weekly Tracking Is Better Than Monthly Tracking
When your income changes every month, your financial situation can change quickly.
You might receive several client payments in one week and nothing in the next. If you only check your finances once a month, it’s easy to lose control of your spending.
A weekly review helps you:
Monitor your cash flow.
Stay within your budget.
Identify unnecessary expenses.
Track progress toward your savings goals.
Adjust your budget before problems grow.
According to the Consumer Financial Protection Bureau (CFPB), regularly reviewing your income and expenses helps you make informed financial decisions and stay on track with your budget.
What Should You Track Every Week?
You don’t need complicated software. A simple spreadsheet, budgeting app, or notebook is enough.
Focus on these four areas:
1. Income Received
Record every payment you receive, including:
Freelance payments
Business income
Salary
Side hustle earnings
Commissions
Passive income
Tracking income helps you compare your actual earnings with your expected Baseline Income.
2. Essential Expenses
Review all necessary spending, such as:
Rent
Groceries
Utilities
Transportation
Insurance
Healthcare
This ensures your Survival Budget stays under control.
3. Non-Essential Spending
Track optional expenses like:
Dining out
Shopping
Entertainment
Subscriptions
Online purchases
Small purchases may seem harmless individually, but together they can significantly reduce your savings.
4. Savings and Investments
Every week, ask yourself:
Did I add money to my Income Buffer?
Did I contribute to my emergency savings?
Did I invest toward my long-term goals?
Tracking progress keeps your financial goals visible and motivates you to stay consistent.
Create a Simple Weekly Money Review
Choose one day each week—such as Sunday evening—and spend 15 to 20 minutes reviewing your finances.
Ask yourself these questions:
How much money did I earn this week?
Where did I spend the most?
Were all my expenses necessary?
Did I follow my budget?
What should I improve next week?
A short review every week is much easier than trying to fix an entire month’s financial mistakes.
Real-Life Example
Sophia is a freelance writer whose income changes every month.
Before tracking her finances weekly, she often forgot about small subscriptions and online purchases.
After creating a 20-minute weekly review, she discovered she was spending over $150 every month on services she rarely used.
By canceling unnecessary subscriptions, she redirected that money into her Income Buffer and emergency savings.
Common Mistakes to Avoid
Avoid these common mistakes:
Reviewing finances only at the end of the month.
Ignoring small daily expenses.
Forgetting to record cash payments.
Tracking expenses but never reviewing them.
Giving up after missing one week.
Remember, consistency is more valuable than perfection.
Action Plan
Complete these steps every week:
✅ Record every source of income.
✅ Review essential and non-essential expenses.
✅ Compare your spending with your budget.
✅ Update your savings and investment progress.
✅ Make one small improvement for the following week.
Next Step: After tracking your finances consistently, the final step is to review and adjust your budget every month so it continues to work as your income and financial goals change.
Step 9: Review and Adjust Your Budget Every Month
A budget is not something you create once and forget. It should evolve as your income, expenses, and financial goals change. This is especially important if you have an irregular income, where no two months are exactly the same.
A monthly budget review helps you identify what worked, what didn’t, and what needs to change. Instead of repeating the same financial mistakes, you improve your budgeting system every month.
Think of your budget as a living financial plan—not a fixed document.
Why You Should Review Your Budget Every Month
Even if you followed your budget perfectly this month, your financial situation may be different next month.
For example:
You may earn more or less than expected.
Your rent or utility bills may increase.
You may have unexpected medical expenses.
You may reach a savings goal and set a new one.
Reviewing your budget regularly allows you to adapt instead of reacting.
According to the Consumer Financial Protection Bureau (CFPB), reviewing your spending plan regularly helps you make better financial decisions and stay aligned with your goals.
How to Review Your Budget
1. Compare Your Planned Budget With Actual Spending
Start by comparing what you planned to spend with what you actually spent.
Ask yourself:
Which categories stayed within budget?
Which categories exceeded the budget?
Why did those differences happen?
The goal is not perfection—it is learning from your spending habits.
2. Review Your Income
Compare your actual monthly income with your Baseline Income.
If you earned more than expected:
Increase your Income Buffer.
Save or invest the extra money.
If you earned less than expected:
Reduce non-essential spending.
Use your Income Buffer if necessary.
Avoid unnecessary debt.
3. Update Your Financial Goals
Your goals will change over time.
For example, after completing your emergency fund, you may decide to focus on:
Investing.
Paying off debt.
Saving for a home.
Growing your business.
Learning new skills.
Your budget should always support your current priorities.
Questions to Ask Every Month
At the end of each month, answer these questions honestly:
Did I follow my budget?
Which expenses were unnecessary?
Did I save enough?
Did I invest consistently?
What financial habit should I improve next month?
These simple questions help you improve your budgeting system month after month.
Real-Life Example
Michael is a self-employed photographer.
At the end of every month, he spends 30 minutes reviewing his finances.
One month, he notices that transportation costs are much higher than expected because of extra client visits.
Instead of ignoring the problem, he increases that category in next month’s budget while reducing entertainment expenses.
This small adjustment keeps his overall budget balanced without affecting his savings goals.
Common Mistakes to Avoid
Avoid these common mistakes:
Never reviewing your budget.
Ignoring overspending.
Making unrealistic budget changes.
Forgetting to adjust for income changes.
Giving up after one difficult month.
Remember, a budget should improve over time. Small monthly adjustments often produce better long-term results than making major changes once a year.
Action Plan
At the end of every month:
✅ Compare planned spending with actual spending.
✅ Review your monthly income.
✅ Identify unnecessary expenses.
✅ Update your savings and investment goals.
✅ Adjust next month’s budget based on what you learned.
Next Step: After building a budgeting system that adapts to changing income, the final step is to focus on long-term financial stability through emergency savings, investing, and continuous financial planning.
Step 10: Build Long-Term Financial Stability
Creating a budget for irregular income is not just about paying this month’s bills—it’s about building a financial system that continues to support you for years to come. Once you’ve learned how to calculate your Survival Budget, estimate your Baseline Income, prioritize expenses, build an Income Buffer, and track your spending, the final step is turning these habits into long-term financial stability.
Financial stability doesn’t mean earning a huge income. It means having enough control over your money that unexpected events don’t completely disrupt your life. Whether you earn $2,000 or $10,000 a month, consistent financial habits will always matter more than occasional high-income months.
Why Long-Term Financial Planning Matters
People with irregular income often focus only on the next payment. While this is understandable, constantly thinking short-term makes it difficult to build wealth.
A long-term financial plan helps you:
Stay financially secure during income fluctuations.
Reduce money-related stress.
Build wealth gradually.
Achieve important life goals.
Become financially independent over time.
According to the Investor.gov, investing consistently over time is one of the most effective ways to build long-term wealth.
Build Your Long-Term Financial System
Instead of relying only on budgeting, combine budgeting with saving, investing, and goal planning.
1. Maintain Your Emergency Fund
Your emergency fund is your first line of financial protection.
Aim to keep enough money to cover at least three to six months of essential living expenses.
Use this money only for genuine emergencies, such as:
Medical expenses
Temporary income loss
Major home or vehicle repairs
Unexpected family emergencies
Continue rebuilding the fund whenever you need to use it.
2. Invest Consistently
Once your emergency savings are in place, start investing regularly.
You don’t need to invest a large amount.
The most important habit is consistency.
Depending on your financial goals, you may choose investments such as:
Index funds
Mutual funds
Retirement accounts
Other diversified long-term investments
If you’re new to investing, begin with research and invest according to your risk tolerance and financial objectives.
3. Continue Learning About Personal Finance
Financial success is a continuous learning process.
Make time to improve your knowledge about:
Budgeting
Saving
Investing
Taxes
Debt management
Retirement planning
The more you understand money, the better financial decisions you’ll make throughout your life.
4. Review Your Financial Goals Every Year
Your priorities will change over time.
Once a year, review your goals and ask yourself:
Have my financial priorities changed?
Am I saving enough?
Am I investing consistently?
Do I need to increase my Income Buffer?
What is my next financial milestone?
Regular reviews help ensure your money continues working toward your future goals.
Real-Life Example
Emma is a self-employed photographer whose income changes throughout the year.
A few years ago, she lived from one payment to the next.
Today, she follows a complete financial system.
She maintains an emergency fund, invests a portion of every profitable month, reviews her budget monthly, and adjusts her financial goals every year.
Although her income is still irregular, her financial life is far more stable because her habits—not her income—create consistency.
Common Mistakes to Avoid
Avoid these long-term financial mistakes:
Stopping your budget after reaching one savings goal.
Ignoring investing.
Depending entirely on one source of income.
Never reviewing your financial goals.
Assuming high income automatically leads to wealth.
Financial stability is built through consistent decisions, not occasional success.
Action Plan
Complete these long-term financial habits:
✅ Maintain an emergency fund covering 3–6 months of essential expenses.
✅ Invest consistently, even if you start with a small amount.
✅ Continue improving your financial knowledge.
✅ Review your financial goals every year.
✅ Keep updating your budgeting system as your income and lifestyle change.
For trusted financial education and long-term investing guidance, you can explore: Investor.gov and MyMoney.gov.
Final Thoughts
Budgeting with irregular income may seem challenging at first, but it becomes much easier when you follow a proven system. By calculating your Survival Budget, estimating your Baseline Income, prioritizing essential expenses, building an Income Buffer, using Zero-Based Budgeting, organizing your accounts, saving during high-income months, tracking your finances, and reviewing your budget regularly, you can take control of your money with confidence.
Remember, financial success isn’t determined by earning the same income every month—it’s determined by how consistently you manage the income you have. Start with one step today, stay disciplined, and improve your system over time. Small actions repeated consistently can lead to lasting financial freedom.
What is the best budgeting method for irregular income
What is the best budgeting method for irregular income? The best budgeting method for irregular income is to combine a Survival Budget, Baseline Income, Income Buffer, and Zero-Based Budgeting. This system helps you cover essential expenses first, save during high-income months, and stay financially stable even when your income changes. FAQ 2 How much emergency savings should I have if my income is irregular? A good goal is to save at least three to six months of essential living expenses. If you're just starting, aim to build one month of expenses first and gradually increase your emergency fund over time. FAQ 3 Should I budget based on my highest-income month? No. Budgeting based on your highest-income month can lead to overspending during slower months. Instead, calculate your Baseline Income using your average earnings from the last 6–12 months and build your budget around that amount. FAQ 4 How often should I review my budget if I have irregular income? Review your budget every week to track income and expenses, and complete a full budget review at the end of each month. Regular reviews help you adjust your spending, improve savings, and stay on track with your financial goals. Key Takeaway 1 Know your Survival Budget before making any spending decisions. Key Takeaway 2 Save extra income during high-earning months instead of increasing your lifestyle. Key Takeaway 3 Track your income and expenses consistently because what gets measured gets managed. Key Takeaway 4 Review and improve your budget every month to keep it aligned with your changing income and financial goals.
Conclusion
Budgeting with irregular income may seem difficult at first, but it becomes much easier when you follow a proven system instead of relying on guesswork. The goal isn’t to predict exactly how much you’ll earn every month—it’s to build a financial plan that works whether your income is high or low.
By calculating your Survival Budget, estimating your Baseline Income, prioritizing essential expenses, building an Income Buffer, using Zero-Based Budgeting, organizing separate accounts, saving more during high-income months, tracking your finances weekly, and reviewing your budget regularly, you can create a stable financial system that grows with you.
Remember, financial success doesn’t depend on having a fixed salary. It depends on making consistent, smart decisions with the money you earn. Even small improvements, repeated every month, can lead to greater financial security, less stress, and long-term wealth.
Start with the first step today. You don’t need a perfect budget—you just need a system that you can follow consistently. Over time, those small habits will help you take full control of your finances, no matter how unpredictable your income may be.
Article Summary If your income changes every month, creating a traditional budget may not work. Instead, you need a flexible budgeting system designed specifically for irregular income. In this guide, you learned how to calculate your Survival Budget, estimate your Baseline Income, prioritize essential expenses, build an Income Buffer, use the Zero-Based Budgeting Method, organize separate bank accounts, save more during high-income months, track your finances every week, review your budget every month, and build long-term financial stability. By following these 10 practical steps, you can reduce financial stress, avoid overspending, prepare for low-income months, and make smarter financial decisions. The key is not earning the same amount every month—it’s creating a money management system that adapts to changing income while helping you save, invest, and achieve your long-term financial goals. Whether you’re a freelancer, self-employed professional, small business owner, content creator, or anyone with variable income, this budgeting method can help you stay in control of your money and build lasting financial confidence.
Hi, I’m Asif Khan, the voice behind paisakmao.de. For the past two years, I’ve been blogging about financial education, income skills, and mindset development for students and young minds. My mission is to empower every youth with financial literacy and practical money-making skills at an early age. Through paisakmao.de, I share actionable guides for students to start earning early, money wisdom that schools don’t teach, and mindset lessons from successful people and modern psychology. Whether you’re a teenager looking to earn your first income or a student exploring side hustles, you’re in the right place. Financial freedom begins with the right mindset and the right knowledge. Let’s grow, earn, and evolve together — welcome to the movement!
Have you ever reached the end of the month and wondered, “Where did all my money go?” You’re not alone. Millions of people earn a decent income but still struggle to save because of impulse spending, poor budgeting, hidden expenses, and the lack of a clear financial plan.
The good news is that you don’t need a higher salary to start saving. With the right strategy, it’s possible to save money fast in 30 days by making small, practical changes to your daily habits. Whether you’re trying to build an emergency fund, pay off debt, or simply take control of your finances, the next 30 days can completely change the way you manage money.
In this step-by-step guide, you’ll learn 15 proven strategies that actually work—from creating a realistic budget and cutting unnecessary expenses to building smarter spending habits and staying motivated throughout the month. These are practical techniques that beginners can start using today, without making extreme sacrifices.
If you’re serious about improving your financial life, don’t wait for the “perfect time.” Start your 30-day money-saving journey today, because every day you delay is another day of missed savings and lost financial opportunities.
Is It Really Possible to Save Money Fast in 30 Days?
Yes—but only if you follow a realistic plan instead of chasing unrealistic money-saving hacks. Many people believe they need a higher salary before they can start saving, but that’s one of the biggest financial myths. In reality, the first 30 days are not about becoming rich overnight. They’re about changing your spending habits, creating a simple budget, and building a system that helps you save consistently.
If you’re wondering how to save money fast in 30 days, the answer isn’t cutting out everything you enjoy. It’s about identifying unnecessary expenses, making smarter financial decisions, and taking small actions that add up over time. Even saving a small amount every week can create momentum and make long-term saving much easier.
Instead of looking for shortcuts, focus on building habits that you can continue long after these 30 days are over. That’s exactly what this guide is designed to help you do.
Why Most People Fail to Save Money
Most people don’t fail because they earn too little—they fail because they don’t have a clear financial system. Without tracking expenses or planning ahead, it’s easy for money to disappear on small daily purchases, subscriptions, impulse shopping, or lifestyle upgrades that seem harmless at first.
Another common mistake is waiting for the “perfect time” to start saving. Unfortunately, that perfect time rarely comes. The sooner you begin, the sooner you’ll gain control over your finances.
What You Can Realistically Achieve in 30 Days
This guide doesn’t promise overnight wealth or unrealistic results. Instead, it focuses on practical improvements that almost anyone can achieve with consistency.
By following these 15 proven strategies, you can:
Build a simple and realistic monthly budget.
Reduce unnecessary spending without feeling deprived.
Save your first meaningful amount of money.
Develop healthier money habits that last beyond 30 days.
Take the first step toward long-term financial freedom.
Remember, the goal isn’t just to save money fast in 30 days—it’s to build a financial system that continues working for you month after month
1. Track Every Expense Before You Cut Costs
If you’re searching for how to save money fast in 30 days, you’re probably hoping to find one simple trick that will instantly increase your savings.
Maybe you’ve already tried cutting back on coffee, deleting shopping apps, canceling streaming subscriptions, or promising yourself that this month you’ll finally stick to a budget.
But despite all your efforts, your savings account still doesn’t grow.
If that sounds familiar, don’t worry—you’re not alone.
Millions of people struggle to save money every month, not because they earn too little, but because they don’t fully understand where their money actually goes.
That’s why the first strategy in this guide isn’t about investing.
It isn’t about earning more money.
It isn’t even about creating a budget.
The first step is much simpler—but far more powerful.
Track every expense before you cut costs.
Because you can’t improve what you don’t measure.
If you don’t know where your money is going today, you’ll never know where you should start saving tomorrow.
Many people think they know their spending habits.
The reality is very different.
Small daily purchases—like a cup of coffee before work, ordering food after a busy day, buying something during an online sale, paying for subscriptions you rarely use, or grabbing snacks while traveling—don’t feel expensive in the moment.
However, when these purchases happen repeatedly, they quietly consume hundreds of dollars every month.
By the time payday arrives again, many people ask themselves the same question:
“I earned my salary… so where did all my money disappear?”
If you’ve ever asked yourself that question, this strategy will completely change the way you manage money.
A Real-Life Story: How One Simple Habit Changed Everything
Meet Alex.
Alex is 27 years old and works a full-time office job.
He earns approximately $2,800 every month.
He’s not irresponsible with money.
He pays his rent on time.
He doesn’t buy expensive luxury items.
He rarely travels.
Yet somehow…
Every month ends exactly the same way.
Very little money remains in his bank account.
Alex becomes frustrated.
He blames inflation.
He blames his salary.
He even starts searching for a second job.
One weekend, instead of looking for ways to earn more money, Alex decides to perform a simple experiment.
For the next seven days, he’ll record every single expense—no matter how small.
Every coffee.
Every snack.
Every ride-share.
Every online purchase.
Every subscription payment.
Nothing is ignored.
At the end of the week, the results shock him.
Expense
Weekly Spending
Coffee
$28
Food Delivery
$46
Snacks
$22
Online Shopping
$41
Ride Sharing
$23
Total Weekly Spending: $160
That’s nearly $640 every month.
The surprising part wasn’t the amount.
It was the fact that Alex couldn’t even remember making most of those purchases.
After identifying these hidden money leaks, he reduced only a few unnecessary expenses.
Three months later, he had already saved more than $900—without getting a raise, working overtime, or sacrificing everything he enjoyed.
His income didn’t change.
His awareness did.
That’s the real power of tracking every expense.
If you’re new to budgeting, learning the fundamentals from Investopedia’s budgeting guide can also help you understand why awareness always comes before budgeting.
Key Lesson: Before you cut expenses, you need to identify them. Every dollar you track today gives you more control over your money tomorrow.
What Expenses Should You Track?
One of the biggest mistakes people make is believing that only large purchases matter.
That’s simply not true.
A $500 purchase is easy to notice.
But ten $5 purchases often go completely unnoticed.
Ironically, those small daily expenses usually have a much bigger impact on your monthly savings than one occasional large expense.
If your goal is to save money fast in 30 days, you need to develop the habit of tracking every single expense—not just the expensive ones.
Think of yourself as a financial detective.
Your job isn’t to judge your spending.
Your job is to discover where your money is quietly disappearing.
Categorize Every Expense
To make your spending easier to understand, divide every expense into simple categories.
1. Essential Expenses (Needs)
These are the costs required for your daily life.
Rent or Home Loan
Electricity Bill
Water Bill
Internet
Mobile Recharge
Groceries
Transportation
Fuel
Healthcare
Insurance
Education
These expenses usually can’t be avoided.
Instead of eliminating them, focus on reducing unnecessary costs within these categories whenever possible.
2. Lifestyle Expenses (Wants)
These aren’t always necessary, but they improve your lifestyle.
Examples include:
Coffee
Restaurants
Food Delivery
Entertainment
Shopping
Streaming Services
Gaming
Weekend Trips
There’s nothing wrong with spending money on things you enjoy.
The problem starts when these purchases become automatic habits instead of intentional choices.
3. Hidden Money Leaks
This is where most people lose money without realizing it.
Hidden expenses often include:
ATM Charges
Bank Fees
Delivery Charges
Late Payment Fees
Forgotten Subscriptions
Premium Mobile Apps
In-App Purchases
Convenience Fees
These expenses rarely look expensive individually.
However, together they can quietly cost hundreds of dollars every year.
If you’ve ever wondered why your savings aren’t growing despite earning a decent salary, hidden money leaks are often the answer.
The good news is that tracking expenses doesn’t require complicated software.
You don’t need to be a financial expert.
You simply need consistency.
Step 1 — Record Every Purchase Immediately
The biggest mistake is trusting your memory.
Instead, record every purchase the moment you spend money.
Whether it’s a cup of coffee, a grocery bill, or an online order, write it down immediately.
The more accurate your records are, the easier it becomes to identify unnecessary spending.
Step 2 — Choose a Tracking Method You’ll Actually Use
The best expense tracker isn’t the most advanced one.
It’s the one you’ll continue using every day.
You can choose:
Google Sheets
Microsoft Excel
A budgeting app
A notebook
Your phone’s Notes app
Don’t waste time searching for the “perfect” tool.
Consistency is far more important than features.
Step 3 — Review Your Spending Every Evening
Spend just five minutes reviewing everything you purchased during the day.
Ask yourself three simple questions:
Did I really need this?
Could I have spent less?
Would I buy this again tomorrow?
These questions gradually train your brain to become more mindful before spending money.
Over time, you’ll naturally start making smarter financial decisions without feeling restricted.
A Small Habit That Creates Big Results
Imagine reducing just $10 of unnecessary spending every day.
That doesn’t sound life-changing.
But over one month, you’ve already saved around $300.
Over one year, that’s approximately $3,650—without earning an extra dollar.
That’s the power of small financial habits.
According to the Consumer Financial Protection Bureau, understanding where your money goes is one of the most important first steps toward building better financial habits.
Many successful investors don’t become wealthy because they never spend money.
They become wealthy because they understand where every dollar goes before deciding where it should go next.
Key Takeaway: Before you try to earn more money, learn to manage the money you already have. Financial awareness is the first habit that separates successful savers from everyone else.
4. Automate Your Savings Before You Spend
Many people believe they’ll save whatever money is left at the end of the month.
Unfortunately, that day rarely comes.
Unexpected expenses appear.
Online shopping becomes tempting.
Friends invite you out.
A sale pops up on your phone.
By the end of the month, there’s little or nothing left to save.
That’s why one of the smartest ways to save money fast in 30 days is to reverse the process.
Instead of saving what’s left after spending…
Save first, then spend what’s left.
This simple strategy is called Pay Yourself First, and it’s one of the most effective habits used by financially successful people.
Why Saving First Works
Your brain naturally adapts to the money that’s available.
For example, if your salary is $2,000 and you immediately transfer $200 into your savings account, your mind quickly adjusts to living on the remaining $1,800.
After a few weeks, it starts feeling normal.
However, if you wait until the end of the month to save, chances are you’ll find reasons to spend that extra $200.
The problem isn’t your income.
The problem is that spending always expands to match the money available.
Automating your savings removes emotion and temptation from the process.
According to the Consumer Financial Protection Bureau, automatic savings can help people build consistent financial habits by reducing the need for daily decisions.
How to Automate Your Savings
Step 1 – Decide Your Savings Percentage
Start with an amount that’s realistic.
For example:
10% of your monthly salary
15% if your budget allows
Even 5% is better than saving nothing
The goal is consistency—not perfection.
Step 2 – Create a Separate Savings Account
Avoid keeping your savings in the same account you use for daily spending.
A separate account creates a mental barrier, making impulse spending less likely.
Step 3 – Schedule Automatic Transfers
Set up an automatic transfer for the same day your salary arrives.
This way, your savings happen before you have a chance to spend the money.
Once it’s automated, you don’t have to rely on motivation or memory every month.
Real-Life Example
Sarah earns $3,000 every month.
For years, she tried to save money manually but never stayed consistent.
She decided to automate 15% of her salary.
Every payday, $450 was transferred directly into her savings account.
At first, she worried she wouldn’t have enough money.
After two months, she barely noticed the difference.
Within one year, Sarah had saved more than $5,000 without changing her lifestyle dramatically.
The system—not willpower—made the difference.
💡 Pro Tip
Increase your automatic savings by just 1% every six months.
Because the increase is small, you’ll barely notice it, but over time it can significantly grow your savings.
⚠️ Common Mistake
Don’t automate so much that you struggle to pay essential bills.
If your savings target feels stressful, lower the percentage and focus on consistency.
Saving a smaller amount every month is far better than saving a large amount for only one month.
📌 Expert Insight
Behavioral finance research shows that removing the need to make repeated financial decisions reduces the chances of impulsive spending.
Automation turns saving into a habit instead of a monthly challenge.
Transfer the money you save directly into your savings account.
Key Takeaway
You don’t always need to earn more to improve your finances.
Sometimes, the fastest way to save money is simply paying less for the services you already use.
Small monthly reductions may seem insignificant today, but over the course of a year, they can become one of the biggest contributors to your savings.
Next Strategy: Learn how meal planning and smart grocery shopping can dramatically reduce your food expenses without sacrificing healthy eating.
7. Plan Your Meals and Grocery Shopping Before You Spend
If you’re trying to save money fast in 30 days, there’s one area that can dramatically affect your monthly budget without you even noticing—food spending.
Most people think groceries are expensive.
The truth is that poor planning is expensive.
Buying food without a plan.
Ordering takeout because you’re too tired to cook.
Throwing away expired vegetables.
Buying snacks you didn’t intend to purchase.
These small habits slowly drain your wallet month after month.
The good news?
You don’t need to stop eating your favorite meals.
You simply need a smarter plan.
Meal planning helps you spend less, waste less, and save more—all without sacrificing your lifestyle.
Why Meal Planning Is One of the Smartest Money-Saving Habits
Imagine walking into a supermarket without a shopping list.
Everything looks useful.
Everything feels like a good deal.
You pick up chips because they’re on sale.
You buy extra drinks “just in case.”
You grab chocolates near the checkout counter.
By the time you reach home, you’ve spent far more than you planned.
A few days later, half the vegetables spoil, leftovers go untouched, and some groceries expire before you even use them.
That’s not just food waste.
That’s money waste.
According to the MyPlate nutrition guide, planning meals before shopping helps families make healthier food choices while reducing unnecessary purchases and food waste.
How to Spend Less on Food Without Feeling Restricted
Step 1 – Plan Your Meals for the Next 7 Days
Before buying anything, decide exactly what you’ll eat throughout the week.
Plan breakfast.
Plan lunch.
Plan dinner.
Plan snacks.
When every meal has a purpose, every grocery purchase also has a purpose.
This simple habit reduces impulse buying and makes food delivery much less tempting.
Step 2 – Check Your Kitchen Before Shopping
Open your refrigerator.
Look inside your freezer.
Check your pantry.
You might already have rice, pasta, spices, vegetables, or canned food waiting to be used.
Buying duplicates wastes money and increases food waste.
Use what you already own before purchasing more.
Step 3 – Make a Shopping List and Follow It
Never rely on memory.
Write down only the ingredients you actually need.
When you enter the supermarket with a clear shopping list, you’re far less likely to buy unnecessary products.
Think of your shopping list as your financial roadmap.
Every item should have a reason to be there.
Real-Life Example
Sophia loved ordering food after work because cooking felt exhausting.
Between groceries, takeout, and coffee stops, she was spending nearly $650 every month on food.
One Sunday, she decided to plan all her meals for the upcoming week.
She created a shopping list, cooked a few meals in advance, and carried lunch to work three times that week.
By the end of the month, her food expenses dropped to $430.
She didn’t stop eating well.
She simply stopped making last-minute decisions.
The money she saved went directly into her emergency fund.
Small changes produced big results.
💡 Pro Tip
Follow the “Shop Your Kitchen First” rule.
Before buying anything new, challenge yourself to prepare at least two meals using ingredients you already have at home.
You’ll reduce food waste and save money at the same time.
⚠️ Common Mistake
Don’t buy large quantities just because they’re on sale.
If you don’t use the food before it expires, the discount becomes a loss.
A product isn’t a bargain unless you actually use it.
📌 Expert Insight
Research from the USDA Food and Nutrition Service shows that meal planning and reducing food waste are practical ways to improve household budgeting while supporting healthier eating habits.
If you’ve already started tracking your daily expenses, you’ll find it much easier to identify how much of your monthly budget goes toward groceries and food delivery.
Compare this week’s grocery spending with last week’s.
Transfer the money you saved into your savings account.
Key Takeaway
Saving money on food isn’t about eating less.
It’s about planning better, shopping smarter, and wasting less.
When every grocery purchase has a purpose, your food budget becomes easier to manage, your kitchen becomes more organized, and your savings grow without making you feel deprived.
Next Strategy: Learn how to use cashback offers, reward programs, and credit card benefits wisely to save money without falling into the trap of unnecessary spending.
8. Try a 30-Day No-Spend Challenge to Reset Your Spending Habits
If you’ve been wondering how to save money fast in 30 days, there’s one powerful strategy that doesn’t require a higher salary, a second job, or extreme budgeting.
Instead, it requires one simple decision:
Stop buying things you don’t truly need—for just 30 days.
This is called a 30-Day No-Spend Challenge, and it’s one of the fastest ways to break bad spending habits while giving your finances a fresh start.
The goal isn’t to stop spending money completely.
That’s impossible.
You’ll still pay rent, buy groceries, pay your electricity bill, and cover transportation costs.
The real goal is to eliminate non-essential spending so you can clearly see how much money usually disappears because of habits rather than necessity.
By the end of the challenge, most people don’t just save more money—they completely change the way they think about spending.
Why the No-Spend Challenge Works
Every purchase starts with a decision.
Unfortunately, many of those decisions happen automatically.
You’re bored.
You open Amazon.
You’re stressed.
You order food.
You see a flash sale.
You convince yourself you’re saving money by spending money.
This cycle repeats over and over until payday arrives and your savings account is still empty.
The 30-Day No-Spend Challenge interrupts this pattern.
Instead of asking,
“Can I afford this?”
you begin asking,
“Do I actually need this?”
That single question changes everything.
According to the Consumer Financial Protection Bureau (CFPB), becoming more intentional about spending is one of the most effective ways to build healthier financial habits.
What You Can Spend Money On
During the challenge, spending is allowed only on essential needs.
✅ Rent or Mortgage
✅ Groceries
✅ Electricity and Water Bills
✅ Transportation
✅ Healthcare
✅ Education
✅ Emergency Expenses
Everything else should wait.
That includes:
❌ Online Shopping
❌ Fashion Purchases
❌ Entertainment Purchases
❌ Expensive Coffee
❌ Food Delivery
❌ Impulse Buying
❌ Unnecessary Gadgets
Remember…
You’re not saying “Never.”
You’re simply saying “Not today.”
Real-Life Example
Michael loved online shopping.
Almost every evening he bought something small.
Sometimes it was a phone accessory.
Sometimes new shoes.
Sometimes gadgets he never actually used.
Individually, none of these purchases felt expensive.
But after accepting a 30-Day No-Spend Challenge, he noticed something surprising.
Most of the items he wanted on Day 1 didn’t matter anymore by Day 10.
By the end of the month, he had saved nearly $520 without feeling deprived.
More importantly, he realized that many of his purchases were emotional—not necessary.
That lesson changed his financial habits permanently.
💡 Pro Tip
Whenever you feel tempted to buy something, write it down on a 30-Day Wish List instead of purchasing it immediately.
If you still genuinely want it after the challenge ends—and it fits your budget—you can buy it without regret.
Most people discover they no longer want nearly half the items on their list.
⚠️ Common Mistake
Don’t make the challenge so strict that you quit after a few days.
The goal isn’t perfection.
The goal is awareness.
If you accidentally buy something unnecessary, don’t give up.
Learn from the mistake and continue the challenge.
Progress always beats perfection.
📌 Expert Insight
Behavioral finance research shows that delaying gratification helps reduce impulsive spending and strengthens long-term financial discipline.
If you’re already tracking your expenses, this challenge becomes much easier because you’ll immediately notice where your biggest money leaks occur.
Transfer those savings into your emergency fund or savings account.
Review your progress at the end of each week.
Key Takeaway
A 30-Day No-Spend Challenge isn’t about making life boring.
It’s about proving to yourself that you control your money—not your impulses.
After just one month, you’ll spend more intentionally, save more consistently, and develop financial habits that continue long after the challenge ends.
Next Strategy: Learn how to build an emergency fund even if you’re living paycheck to paycheck.
9. Build an Emergency Fund—Even If You Can Only Save a Little
Imagine this.
Your phone suddenly stops working.
Your bike needs repairs.
You face an unexpected medical bill.
Or your car breaks down on the way to work.
None of these situations are part of your monthly budget.
Yet they happen to almost everyone.
When people don’t have an emergency fund, they often rely on credit cards, personal loans, or borrow money from friends and family.
Instead of solving one financial problem, they create another.
That’s why building an emergency fund is one of the smartest strategies if you want to save money fast in 30 days and protect your financial future.
An emergency fund isn’t just money sitting in a bank account.
It’s peace of mind.
It’s knowing that one unexpected expense won’t destroy your entire budget.
The best part?
You don’t need thousands of dollars to get started.
Even saving a small amount consistently can make a huge difference over time.
Why an Emergency Fund Is More Important Than You Think
Many people believe they should start investing before building emergency savings.
While investing is important, emergencies don’t wait for the stock market to perform well.
Without emergency savings, people often withdraw investments at the wrong time or take high-interest loans.
That’s why financial experts recommend building a cash safety cushion first.
According to the Consumer Financial Protection Bureau (CFPB), having emergency savings helps households recover from unexpected financial setbacks without relying on expensive debt.
Think of your emergency fund as a financial airbag.
You hope you’ll never need it.
But when an emergency happens, you’ll be grateful it’s there.
How to Build an Emergency Fund
Step 1 – Set a Small Starting Goal
Don’t aim for $10,000 immediately.
That number feels overwhelming.
Instead, focus on your first milestone.
For example:
First $100
Then $500
Then one month’s living expenses
Small victories create motivation.
Step 2 – Save Automatically
Treat your emergency fund like a monthly bill.
Transfer money into it as soon as your salary arrives.
Even $20 or $50 every month builds momentum.
Consistency matters far more than the amount.
Step 3 – Keep It Separate
Don’t keep your emergency savings in the same account you use for daily spending.
A separate savings account reduces temptation and protects your money from impulse purchases.
The harder it is to spend, the more likely you’ll keep saving.
Real-Life Example
Ryan worked as a delivery driver.
His income wasn’t very high, so he believed saving money was impossible.
Instead of giving up, he started saving just $25 every week.
After ten months, he had built an emergency fund of over $1,000.
One day, his motorcycle needed urgent repairs.
Instead of borrowing money or using a credit card, Ryan paid the repair bill from his emergency fund.
He continued working without falling into debt.
That small habit protected both his finances and his peace of mind.
💡 Pro Tip
Keep your emergency fund in a high-yield savings account or another secure savings account that earns interest while keeping your money easily accessible for genuine emergencies.
Avoid investing emergency savings in assets that can lose value in the short term.
⚠️ Common Mistake
Don’t use your emergency fund for vacations, shopping, or festival sales.
An emergency fund is only for unexpected and essential expenses such as medical emergencies, urgent home repairs, or temporary income loss.
If you spend it on non-emergencies, you’ll have nothing when a real emergency happens.
📌 Expert Insight
Financial planners generally recommend building an emergency fund before aggressively investing or paying for lifestyle upgrades because unexpected expenses are inevitable.
If you’re already following the earlier strategies in this guide—tracking expenses, reducing monthly bills, and avoiding impulse purchases—you’ll find it much easier to save money consistently.
An emergency fund isn’t about expecting the worst.
It’s about being prepared for life’s unexpected moments.
Even if you can only save a small amount each week, consistency will eventually create a financial safety net that protects you from debt, reduces stress, and keeps your long-term savings goals on track.
Next Strategy: Learn how increasing your income with simple side hustles can accelerate your savings without relying only on cutting expenses.
10. Increase Your Income with a Simple Side Hustle Instead of Only Cutting Expenses
Cutting expenses is one of the fastest ways to save money.
But there’s a limit.
You can only reduce your spending so much before it starts affecting your lifestyle.
Your income, however, has much more room to grow.
That’s why one of the smartest ways to save money fast in 30 days is to focus on earning a little extra money alongside your regular income.
You don’t need to quit your job.
You don’t need a business degree.
And you certainly don’t need thousands of dollars to get started.
Even earning an extra $100–$300 per month can dramatically improve your savings, help you build an emergency fund faster, or pay off debt without feeling financially stressed.
The goal isn’t to work every waking hour.
The goal is to create an additional income stream that supports your financial goals.
Why Increasing Your Income Is Better Than Extreme Budgeting
Imagine two people.
The first person cuts every possible expense.
No coffee.
No entertainment.
No dining out.
No hobbies.
They manage to save $150 every month.
The second person keeps a balanced lifestyle but earns an extra $300 each month through freelancing, tutoring, selling digital products, or weekend work.
Who reaches their savings goal faster?
The second person.
That’s because increasing your income creates new financial opportunities instead of constantly restricting your lifestyle.
How to Start a Side Hustle Without Feeling Overwhelmed
Step 1 – Identify a Skill You Already Have
You don’t need to learn something completely new.
Start with skills you already possess.
Examples include:
Writing
Graphic Design
Video Editing
Teaching
Photography
Coding
Social Media Management
Translation
Data Entry
Almost every skill can become a source of income.
Step 2 – Start Small
Don’t wait until everything is perfect.
Offer one service.
Get your first client.
Learn from feedback.
Improve gradually.
The biggest mistake beginners make is spending months planning instead of taking action.
Small progress every week creates long-term success.
Step 3 – Save Every Dollar You Earn
Here’s where most people go wrong.
They earn extra money…
Then immediately spend it.
Instead, make a rule:
Every dollar earned from your side hustle goes directly into savings or investments.
This separates your extra income from your everyday spending.
Real-Life Example
James worked a full-time office job and believed saving money was impossible because his salary barely covered his monthly expenses.
Instead of looking for another full-time job, he started freelancing on weekends as a graphic designer.
During his first month, he earned only $180.
Rather than spending that money, he transferred every dollar into his savings account.
Within eight months, he had saved more than $1,500 from side income alone.
His salary stayed exactly the same.
Only his income sources changed.
💡 Pro Tip
Choose a side hustle that matches your existing skills.
You’ll start earning much faster than trying to learn an entirely new profession from scratch.
⚠️ Common Mistake
Don’t chase every new “Get Rich Quick” opportunity you see online.
If something promises huge profits with little effort, treat it with caution.
Building extra income usually takes time, consistency, and patience.
📌 Expert Insight
Many financially successful people don’t rely on just one source of income.
They gradually build multiple income streams, allowing them to save more, invest more, and recover more easily from unexpected financial setbacks.
If you’re already saving money by tracking expenses and reducing unnecessary bills, adding even a small side income can accelerate your progress significantly.
For practical career and earning advice, explore the CareerOneStop Career Resources, sponsored by the U.S. Department of Labor.
✅ Quick Action Plan
List three skills you already have.
Choose one side hustle that matches those skills.
Set a goal to earn your first extra $100.
Save every dollar you earn from that side hustle.
Review your progress after 30 days and increase your income goal gradually.
Key Takeaway
Saving money isn’t only about spending less.
Sometimes, the fastest way to reach your financial goals is to earn a little more while continuing your smart saving habits.
When you combine disciplined spending with an additional source of income, you’ll build savings faster, reduce financial stress, and create more opportunities for your future.
Next Strategy: Learn how setting clear savings goals can keep you motivated and make it easier to stay consistent throughout your 30-day money-saving journey.
11. Set a Clear Savings Goal to Stay Motivated Every Day
Have you ever promised yourself,
“From next month, I’ll start saving money.”
But after a few weeks, that motivation disappeared?
If your answer is yes, you’re not alone.
One of the biggest reasons people fail to save money fast in 30 days isn’t because they don’t earn enough money.
It’s because they don’t have a clear reason to save.
Saving money without a goal is like driving without a destination.
You’ll keep moving, but you won’t know whether you’re making progress.
A specific savings goal gives every dollar a purpose.
Instead of thinking,
“I’m saving money because I should.”
You start thinking,
“I’m saving money because I want to buy my first home, build an emergency fund, travel, become debt-free, or achieve financial freedom.”
That small shift completely changes your mindset.
Why Clear Financial Goals Make Saving Easier
Our brains naturally stay motivated when we can see progress.
Imagine trying to climb a mountain without knowing where the top is.
You’d probably give up halfway.
Now imagine seeing clear milestones every few hundred meters.
How to Set a Savings Goal That You’ll Actually Achieve
Step 1 – Choose One Primary Goal
Don’t try to save for ten different things at once.
Focus on one goal first.
For example:
Build an Emergency Fund
Buy a New Laptop
Save for Higher Education
Buy Your First Car
Start Investing
Pay Off Debt
Build a House Down Payment
One clear goal creates better focus than several competing goals.
Step 2 – Give Your Goal a Deadline
Goals without deadlines usually remain wishes.
Instead of saying,
“I’ll save someday.”
Say,
“I’ll save $2,000 within the next eight months.”
A deadline creates urgency and helps you measure progress.
Step 3 – Break the Goal into Small Milestones
Large numbers often feel overwhelming.
Break them into smaller targets.
Example:
Goal = $1,200
Monthly Target = $100
Weekly Target = $25
Daily Target = Around $3.30
Small milestones make big goals feel achievable and keep you motivated throughout the journey.
Real-Life Example
Ava wanted to buy her first laptop for freelance work.
The laptop cost $1,200, but her salary barely covered her monthly expenses.
Instead of giving up, she created a clear savings goal.
She decided to save $100 every month by reducing unnecessary spending, cooking more meals at home, and setting aside part of her side-hustle income.
She tracked her progress every weekend.
Each month, watching her savings grow motivated her to continue.
Within one year, Ava bought her laptop without taking a loan or using a credit card.
The goal gave her direction.
The habit made it possible.
💡 Pro Tip
Keep your savings goal somewhere you’ll see it every day.
Write it on a sticky note, make it your phone wallpaper, or use a savings tracker.
A constant visual reminder helps you stay focused when you’re tempted to spend money impulsively.
⚠️ Common Mistake
Don’t set unrealistic goals.
Trying to save half of your salary overnight often leads to frustration.
Choose a goal that’s challenging but realistic.
It’s better to reach a smaller goal consistently than to abandon a larger one after a few weeks.
📌 Expert Insight
Behavioral finance research shows that people are far more likely to stick with financial habits when they have a specific, measurable goal instead of a vague intention.
If you’ve already started tracking your expenses and completed the earlier strategies in this guide, setting a clear savings goal becomes much easier because you already know how much money you can realistically save each month.
People don’t stay motivated because they’re disciplined.
They stay motivated because they have a clear purpose.
When every dollar moves you one step closer to a meaningful goal, saving money becomes easier, more rewarding, and far more sustainable.
Next Strategy: Discover how reviewing your progress every week helps you stay consistent and reach your savings goals faster.
12. Review Your Finances Every Week to Stay on Track
Saving money isn’t something you do once and forget about.
It’s a habit that needs regular attention.
Many people start the month feeling motivated.
They create a budget.
Track their expenses.
Promise themselves they’ll spend less.
But after a week or two, life gets busy.
Small purchases go unnoticed.
Impulse spending slowly returns.
By the end of the month, they wonder why they failed to reach their savings goal.
The problem isn’t a lack of motivation.
The problem is a lack of regular financial reviews.
Just as businesses review their finances every week, you should also schedule a weekly money check-in.
It takes only 15–20 minutes, but it can save you hundreds of dollars every month.
Why Weekly Reviews Are So Powerful
Imagine driving from one city to another without ever looking at the road signs or your GPS.
You might still reach your destination—but you’ll probably take wrong turns, waste fuel, and lose time.
Managing money works the same way.
If you never review your finances, you won’t notice problems until it’s too late.
A weekly review helps you catch mistakes early.
Maybe you spent more on dining out than expected.
Maybe you forgot to cancel a subscription.
Maybe you achieved your weekly savings target ahead of schedule.
Reviewing your finances every week allows you to make small adjustments before those mistakes become expensive habits.
According to the Consumer.gov Money Management Guide, regularly reviewing your income, expenses, and savings is one of the best ways to build long-term financial stability.
How to Do a Weekly Money Review
Step 1 – Check Your Income and Expenses
Open your banking app, expense tracker, or spreadsheet.
Compare how much money came in versus how much went out.
Look for anything unusual.
Did you spend more than expected?
Did you receive extra income?
The goal isn’t to judge yourself.
It’s to understand your financial habits.
Step 2 – Compare Your Spending with Your Budget
Now compare your actual spending with the budget you planned.
Ask yourself:
Did I stay within my grocery budget?
Did I avoid unnecessary online shopping?
Did I save what I planned this week?
Which category needs improvement next week?
This simple comparison helps you stay accountable.
Step 3 – Celebrate Small Wins and Fix Small Mistakes
Don’t focus only on what went wrong.
Celebrate every small success.
Maybe you avoided impulse buying.
Maybe you cooked meals at home all week.
Maybe you reached your weekly savings target.
Recognizing progress keeps you motivated to continue.
If you made mistakes, don’t feel guilty.
Instead, create a simple plan to avoid repeating them next week.
Real-Life Example
Chris wanted to save $3,000 within a year.
Instead of checking his finances only at the end of each month, he reviewed them every Sunday evening.
During one review, he noticed he had spent much more than expected on food delivery.
The following week, he planned his meals in advance and cut those expenses nearly in half.
That one adjustment helped him stay on track without making drastic lifestyle changes.
By the end of the year, Chris successfully reached his savings goal because he corrected small problems before they became big ones.
💡 Pro Tip
Choose the same day and time every week for your money review.
For example, every Sunday at 7:00 PM.
When it becomes part of your weekly routine, you’ll be much more likely to stay consistent.
⚠️ Common Mistake
Don’t wait until the end of the month to review your finances.
By then, the money is already spent.
Weekly reviews give you enough time to correct mistakes while they’re still small and manageable.
📌 Expert Insight
Successful investors, business owners, and financially disciplined individuals don’t leave their money to chance.
They regularly measure their financial progress and make small improvements over time.
If you’ve already completed the earlier strategies in this guide, a weekly financial review ties everything together by helping you stay accountable and consistent.
It’s about making small improvements consistently.
A weekly financial review helps you stay aware of your spending, correct mistakes before they grow, and remain focused on your long-term financial goals.
Next Strategy: Learn how to avoid common money mistakes that silently destroy your savings and keep you from achieving financial freedom.
13. Avoid Lifestyle Inflation as Your Income Grows
Getting a salary raise should improve your financial future.
Unfortunately, for many people, it only increases their monthly expenses.
They earn more…
Then immediately upgrade their phone.
Move into a more expensive apartment.
Buy a newer car.
Eat out more often.
Purchase premium subscriptions.
Within a few months, their higher income disappears just as quickly as before.
This financial trap is called lifestyle inflation, and it’s one of the biggest reasons people struggle to build wealth—even with a good salary.
If your goal is to save money fast in 30 days and continue growing your savings for years to come, learning how to control lifestyle inflation is essential.
Remember:
Making more money doesn’t automatically make you wealthier.
Keeping more of what you earn does.
What Is Lifestyle Inflation?
Lifestyle inflation happens when your spending increases every time your income increases.
Instead of saving or investing your extra income, you slowly upgrade your lifestyle.
At first, these upgrades feel harmless.
A better smartphone.
A nicer watch.
More expensive restaurants.
Premium memberships.
Luxury vacations.
None of these purchases seem like a major problem individually.
But together, they quietly consume every salary increase you receive.
As a result, you continue living paycheck to paycheck—even though you’re earning more than ever before.
Whenever your income increases, decide in advance where the extra money will go.
For example:
Save 50%
Invest 30%
Enjoy 20%
This approach allows you to improve your lifestyle without sacrificing your future.
Step 2 – Increase Your Savings Rate
Instead of increasing only your spending, increase your savings too.
If you previously saved 10% of your salary, try saving 15% after your next raise.
Your future self will thank you.
Step 3 – Ask Yourself One Important Question
Before buying something more expensive, ask yourself:
“Am I buying this because I truly need it, or simply because I earn more now?”
That simple question prevents countless unnecessary purchases.
Real-Life Example
Kevin received a salary increase of $500 per month.
Most of his friends encouraged him to buy a newer car.
Instead, Kevin decided to keep driving his current car for another two years.
He automatically transferred $350 of his salary increase into his savings and investment accounts.
The remaining $150 was used to improve his lifestyle.
After two years, Kevin had built thousands of dollars in savings while still enjoying his higher income.
His friends, however, had larger car payments and very little savings.
The difference wasn’t income.
It was financial discipline.
💡 Pro Tip
Whenever you receive a salary raise, bonus, or tax refund, wait 30 days before making any major purchase.
Giving yourself time helps you make logical decisions instead of emotional ones.
⚠️ Common Mistake
Don’t compare your lifestyle to other people’s social media posts.
Many expensive-looking lifestyles are financed with debt—not wealth.
Build your financial future based on your own goals, not someone else’s appearance.
📌 Expert Insight
Many millionaires continue living below their means even after their income grows substantially.
They understand that wealth isn’t measured by what you spend—it’s measured by what you keep and invest.
If you’re already following the earlier strategies in this guide, avoiding lifestyle inflation becomes much easier because you’ll already have better control over your spending habits.
For more investor education, visit the Investor.gov website maintained by the U.S. Securities and Exchange Commission.
✅ Quick Action Plan
Decide how you’ll use your next salary increase before you receive it.
Increase your savings rate whenever your income grows.
Wait 30 days before making expensive purchases.
Avoid comparing your lifestyle with others.
Review your financial goals every month.
Key Takeaway
A higher income creates an opportunity to build wealth—but only if you resist the temptation to increase your spending at the same pace.
The people who achieve financial freedom aren’t always the ones who earn the most.
They’re the ones who consistently save, invest, and live below their means.
Next Strategy: Discover how small daily habits can compound into life-changing savings over time.
14. Build Small Daily Money Habits That Compound Over Time
When people think about saving money, they often look for one big solution.
A higher salary.
A better investment.
A huge discount.
A second job.
While these can certainly help, they usually aren’t what separates people who build wealth from those who constantly struggle with money.
The real difference is found in small daily habits.
Tiny financial decisions may seem insignificant today, but when repeated consistently, they create remarkable results over months and years.
Think about brushing your teeth.
Doing it once won’t make much difference.
But doing it every day protects your teeth for years.
Saving money works exactly the same way.
A small habit repeated consistently is far more powerful than one big financial decision made once.
If you truly want to save money fast in 30 days, start by improving your daily habits—not by searching for shortcuts.
Why Small Habits Create Big Financial Results
Most people underestimate the power of consistency.
Saving $5 today doesn’t feel life-changing.
Neither does avoiding one unnecessary online purchase.
But imagine repeating that decision every day for an entire year.
Those small choices gradually become thousands of dollars.
The reason is simple.
Financial success isn’t built in a single weekend.
It’s built through hundreds of smart decisions made over time.
According to the Consumer Financial Protection Bureau (CFPB), creating consistent financial habits is one of the most effective ways to improve long-term financial well-being.
Small Daily Habits That Save Money
1. Check Your Bank Balance Every Morning
This simple habit keeps your spending under control.
When you know exactly how much money you have, you’re less likely to make impulsive purchases.
Financial awareness leads to better financial decisions.
2. Ask One Question Before Every Purchase
Before spending money, pause for five seconds and ask yourself:
“Will this purchase improve my life next month, or am I buying it only because I want it today?”
That one question prevents countless unnecessary purchases.
3. Save Every Small Amount
Found $10 in your wallet?
Received cashback?
Earned a small bonus?
Instead of spending it immediately, transfer it directly into your savings account.
Small amounts eventually become meaningful savings.
4. Spend Five Minutes Learning About Money
Read one article.
Watch an educational video.
Listen to a personal finance podcast.
Improving your financial knowledge helps you make smarter decisions throughout your life.
Knowledge compounds just like money.
Real-Life Example
Olivia didn’t receive a promotion.
She didn’t start a side business.
She simply changed five small daily habits.
She stopped buying coffee every morning.
Checked her bank account daily.
Prepared lunch at home.
Transferred every cashback reward into savings.
Reviewed her expenses every Sunday.
None of these habits seemed extraordinary.
Yet after one year, she had saved over $3,000 without feeling like she had sacrificed her lifestyle.
Her success wasn’t created by one big decision.
It was built through hundreds of small ones.
💡 Pro Tip
Don’t try to build ten new financial habits at once.
Choose one habit every week.
Once it becomes automatic, add another.
Small improvements are easier to maintain than dramatic lifestyle changes.
⚠️ Common Mistake
Many people believe small savings don’t matter.
They think,
“It’s only $5.”
But that mindset repeated hundreds of times each year quietly destroys long-term wealth.
Never underestimate the value of small financial decisions.
📌 Expert Insight
Behavioral finance experts often explain that lasting financial success depends more on consistent habits than short bursts of motivation.
If you’ve followed the previous strategies in this guide—tracking expenses, avoiding impulse buying, building an emergency fund, and reviewing your finances weekly—you’ve already started creating habits that can benefit you for years to come.
You can also explore practical financial education from the MoneyHelper service for more guidance on budgeting, saving, and managing everyday finances.
✅ Quick Action Plan
Check your bank balance every morning.
Pause before every non-essential purchase.
Save unexpected income instead of spending it.
Learn one new money lesson every day.
Focus on building one financial habit each week.
Review your progress every Sunday.
Key Takeaway
Wealth isn’t created by one perfect decision.
It’s created by small, consistent habits repeated over time.
When smart money habits become part of your daily routine, saving money stops feeling difficult and starts becoming automatic.
Next Strategy: Learn the final habit that ties everything together and helps you continue saving money long after your 30-day challenge is over.
15. Turn Saving Money into a Lifelong Habit—Not Just a 30-Day Challenge
Congratulations.
If you’ve followed the strategies in this guide, you’ve already taken a huge step toward improving your financial life.
You’ve learned how to:
Track every expense.
Create a realistic budget.
Cut unnecessary spending.
Avoid impulse purchases.
Reduce monthly bills.
Plan your grocery shopping.
Complete a No-Spend Challenge.
Build an emergency fund.
Increase your income.
Set meaningful savings goals.
Review your finances weekly.
Avoid lifestyle inflation.
Build strong daily money habits.
But here’s the truth that many people overlook.
Saving money for 30 days is relatively easy.
Saving money consistently for years is what creates real financial freedom.
The biggest difference between people who constantly struggle with money and those who build lasting wealth isn’t intelligence.
It isn’t luck.
It isn’t even income.
It’s consistency.
Financial success isn’t built by making one perfect decision.
It’s built by making hundreds of smart decisions over months and years.
That’s why this final strategy isn’t about learning another budgeting trick.
It’s about creating a lifestyle where saving money becomes automatic.
Why Long-Term Consistency Matters More Than Short-Term Motivation
Motivation comes and goes.
Some days you’ll feel excited to save money.
Other days you’ll want to spend everything you’ve earned.
If your financial success depends only on motivation, you’ll eventually lose momentum.
Successful savers rely on systems, not emotions.
Think about exercising.
Going to the gym once doesn’t make you healthy.
Eating one healthy meal doesn’t transform your body.
The same principle applies to money.
Saving a large amount once is helpful.
Saving consistently every month changes your life.
According to the Consumer Financial Protection Bureau (CFPB), people who create consistent financial habits are more likely to achieve long-term financial stability than those who rely on occasional motivation.
How to Make Saving Money Automatic
Step 1 – Create a Monthly Money Routine
Choose one day every month to manage your finances.
During that session:
Review your income.
Check your expenses.
Update your savings.
Review your financial goals.
Plan next month’s budget.
Treat this appointment as seriously as any important meeting.
Step 2 – Increase Your Savings Every Year
Whenever your salary increases, increase your savings too.
Even raising your savings rate by just 2–5% each year can make a remarkable difference over time.
Don’t let every salary increase disappear into lifestyle inflation.
Step 3 – Keep Learning About Personal Finance
Financial education never stops.
The more you learn, the better decisions you’ll make.
Read trusted finance books.
Follow reliable financial websites.
Stay updated on budgeting, saving, investing, and debt management.
Knowledge is one of the few investments that continues paying dividends throughout your life.
Real-Life Example
David started with a simple goal:
Save $100 every month.
It didn’t seem like much.
His friends invested in expensive gadgets and luxury items.
David continued following his savings routine.
Each year, as his income grew, he increased his monthly savings.
Five years later, he had built an emergency fund, started investing, and saved enough for a down payment on his first home.
His success wasn’t the result of one brilliant financial decision.
It came from consistently following simple habits year after year.
💡 Pro Tip
Create a simple personal rule:
“Every time I earn more, I save more.”
This one habit helps your savings grow automatically as your income increases.
⚠️ Common Mistake
Don’t stop tracking your finances after reaching your first savings goal.
Many people save their first $1,000, celebrate, and slowly return to old spending habits.
Financial success isn’t reaching one milestone.
It’s continuing the journey.
📌 Expert Insight
Financial experts consistently emphasize that wealth is built through disciplined habits rather than occasional big wins.
The strategies you’ve learned in this guide work best when they’re combined into a long-term system rather than used individually.
For more evidence-based personal finance guidance, visit the Consumer.gov financial education resources.
✅ Final Action Plan
Continue tracking every expense.
Review your finances every week.
Increase your savings whenever your income grows.
Keep building healthy money habits.
Continue learning about personal finance.
Stay patient and trust the process.
Key Takeaway
The fastest way to save money fast in 30 days is to take action today.
The smartest way to build wealth is to continue those habits long after the 30 days are over.
Money management isn’t about being perfect.
It’s about making better financial decisions, one day at a time.
Over the years, those small decisions compound into something far more valuable than money alone:
Financial confidence, financial security, and the freedom to live life on your own terms.
1. Is it really possible to save money fast in 30 days
### 1. Is it really possible to save money fast in 30 days?Yes. While you may not become financially independent in just one month, you can make significant progress by tracking your expenses, creating a realistic budget, reducing unnecessary spending, avoiding impulse purchases, and following a consistent savings plan. Even small daily improvements can lead to noticeable savings within 30 days.
How much money should I try to save in 30 days
### 2. How much money should I try to save in 30 days?The amount depends on your income and monthly expenses. A practical goal is to save **10–20% of your monthly income**. If that’s not possible, start with a smaller target and increase it gradually. The most important thing is building a consistent saving habit rather than chasing an unrealistic number.
What is the fastest way to save money if I have a low income?
3. What is the fastest way to save money if I have a low income? If you have a low income, focus on the strategies that have the biggest impact. Track every expense, eliminate unnecessary subscriptions, plan your meals, avoid impulse purchases, and try to earn extra income through a side hustle. Even saving a small amount consistently can make a big difference over time.
4 What should I do after completing the 30-day
4 What should I do after completing the 30-day money-saving challenge? Don’t stop after the first month. Continue tracking your spending, reviewing your budget every week, increasing your savings as your income grows, and setting new financial goals. The real objective isn’t just to save money for 30 days—it’s to develop lifelong financial habits that help you build lasting wealth.
What should I do after completing the 30-day money-saving challenge
### 5. What should I do after completing the 30-day money-saving challenge?Don’t stop after the first month. Continue tracking your spending, reviewing your budget every week, increasing your savings as your income grows, and setting new financial goals. The real objective isn’t just to save money for 30 days—it’s to develop lifelong financial habits that help you build lasting wealth.
Conclusion: Start Saving Money Today—Your Future Self Will Thank You
Learning how to save money fast in 30 days isn’t about finding one secret trick or following an extremely strict budget.
It’s about making small, smart financial decisions consistently.
Throughout this guide, you’ve learned 15 proven strategies that can help you take control of your money—from tracking every expense and creating a realistic budget to avoiding impulse purchases, building an emergency fund, increasing your income, and developing lifelong money habits.
You don’t need to implement all 15 strategies perfectly on your first day.
Instead, start with one or two strategies today.
Build momentum.
Then add another habit next week.
Remember, financial success isn’t determined by how much you earn—it’s determined by how well you manage what you earn.
Every dollar you save today is a step toward a stronger financial future.
Whether your goal is to build an emergency fund, become debt-free, invest for the future, buy your dream home, or simply stop living paycheck to paycheck, the journey begins with one decision:
Start today.
Don’t wait for next month.
Don’t wait for a higher salary.
Don’t wait for the “perfect time.”
The best time to take control of your finances is right now.
If you found this guide helpful, consider bookmarking it and revisiting these strategies whenever you need a financial reset. Consistently applying these habits can help you build long-term wealth and achieve lasting financial freedom.
Your 30-day challenge starts today. The sooner you begin, the sooner you’ll see results.
## Article Summary
Saving money doesn’t require a high income—it requires smart financial habits and consistent action. In this guide, you learned **15 proven strategies** to help you **save money fast in 30 days**, including tracking every expense, creating a realistic budget, avoiding impulse purchases, reducing monthly bills, planning grocery shopping, building an emergency fund, increasing your income, setting clear savings goals, and developing long-term money habits.
The key takeaway is simple: **small financial decisions made consistently create big results over time.** You don’t have to apply every strategy at once. Start with one or two habits today, stay consistent, and gradually build a financial system that supports your goals.
Whether you’re saving for an emergency fund, paying off debt, buying your first home, or simply trying to stop living paycheck to paycheck, these practical strategies can help you take control of your money and build a more secure financial future.
**Remember:** Financial freedom isn’t achieved overnight. It’s built one smart decision at a time.
Hi, I’m Asif Khan, the voice behind paisakmao.de. For the past two years, I’ve been blogging about financial education, income skills, and mindset development for students and young minds. My mission is to empower every youth with financial literacy and practical money-making skills at an early age. Through paisakmao.de, I share actionable guides for students to start earning early, money wisdom that schools don’t teach, and mindset lessons from successful people and modern psychology. Whether you’re a teenager looking to earn your first income or a student exploring side hustles, you’re in the right place. Financial freedom begins with the right mindset and the right knowledge. Let’s grow, earn, and evolve together — welcome to the movement!