Learning the essential principles of RuPay credit card for students is critical for anyone looking to build healthy money habits, avoid debt traps, and make smart financial decisions in India.
⚡Updated: November 2026RBI & NPCI RuPay Protocol Verified
Learning the essential principles of RuPay credit card for students is critical for anyone looking to build healthy money habits, avoid debt traps, and make smart financial decisions in India.
Furthermore, over 4 years of active personal finance research in Indian markets. Furthermore, focused on transparent, math-backed guides to help students and young professionals build wealth and manage money smartly.
Learning the essential principles of RuPay credit card for students is critical for anyone looking to build healthy money habits, avoid debt traps, and make smart financial decisions in India.
Learning the essential principles of RuPay credit card for students is critical for anyone looking to build healthy money habits, avoid debt traps, and make smart financial decisions in India.
Essential Overview: Guide to RuPay credit card for students
Essential Overview: Guide to RuPay credit card for students
Learning the essential principles of RuPay credit card for students is critical for anyone looking to build healthy money habits, avoid debt traps, and make smart financial decisions in India.
Learning the essential principles of RuPay credit card for students is critical for anyone looking to build healthy money habits, avoid debt traps, and make smart financial decisions in India.
Additionally, finding the best RuPay credit card for students in India allows college students to build a 750+ CIBIL score early without income proof or annual fees.
Written & Researched by Asif Khan
Written & Researched by Asif Khan
Founder & Lead Financial Editor PaisaKmao.de
Additionally, over 4 years of active personal finance research in Indian markets. Furthermore, focused on transparent, math-backed guides to help students and young professionals build wealth and manage money smartly.
To begin with, learning about RuPay credit card for students is essential for anyone looking to build healthy money habits.
Disclaimer: This guide is for educational financial literacy only. Specifically, we are not SEBI-registered advisors or commercial banks. Furthermore, approvals and limits are granted at the issuing bank’s discretion via Aadhaar KYC. Therefore, never borrow beyond your repayment capacity.
Quick Overview: Best RuPay Credit Cards for Students (2026): Complete Guide to RuPay credit card for students
⚡Quick 30-Second Student RuPay Card Summary
Fast Skim
First: Zero Salary Slip
100% Legal Approval
First, getting a secured student card requires no salary slips or ITR through the secured FD route.
Second: Scan & Pay on UPI
PhonePe GPay Paytm
Second, it links directly into UPI to pay street vendors, canteens & books with zero plastic.
Third: Double Benefit
Earn ~7% Interest on FD
Third, your security deposit compounds interest while unlocking a 90% instant credit line.
Finally: Career Advantage
750+ CIBIL Before Degree
Actionable Insights and Smart Advice for RuPay credit card for students
Finally, you build an exceptional credit score before applying for jobs or study loans.
Previously, finding the best RuPay credit card for students in India used to be nearly impossible. In fact, most commercial banks demand salary slips or ITR proof that full-time college students simply do not possess.
However, thanks to new banking directives by the Reserve Bank of India (RBI) and the National Payments Corporation of India (NPCI), securing a RuPay credit card for students is now fast, 100% legal, and completely paperwork-free through the secured Fixed Deposit (FD) route. In addition, you can link this card directly into PhonePe and Google Pay to scan and pay at college canteens and local merchants.
Actionable Advice and Practical Tips for RuPay credit card for students
1. What is a Secured RuPay Credit Card for Students and How Does It Work?
Direct Definition: A RuPay credit card for students is a secured credit instrument issued against a small refundable Fixed Deposit (₹2,000 to ₹10,000). Consequently, the bank grants an instant 80% to 90% credit limit without requesting any salary slip, ITR, or past credit score.
🔒
1. Consequently, your Cash Stays Safe
Because the FD acts as collateral, your deposit remains 100% secure in your own bank account.
📈
2. In addition, earns ~7% FD Returns
Furthermore, your money doesn’t sit idle; it earns 6.5% to 7.5% compounding annual interest.
📱
3. Specifically, instant Virtual Card
As a result, your card details are generated immediately in the mobile banking app with zero physical waiting.
🎯
4. 100% Bureau Reporting
Consequently, every on-time statement payment reports to CIBIL, establishing a solid score early.
2. Why RuPay on UPI Beats Traditional Visa & Mastercard for Students: Complete Guide to RuPay credit card for students
Additionally, historically, traditional Visa or Mastercard credit cards only work when swiped on expensive electronic card machines. In contrast, choosing a RuPay card allows you to scan any standard merchant QR code at tea stalls, canteens, and stationery stores.
Feature
Regular Visa / Mastercard
RuPay Credit Card for Students
Everyday Merchant Acceptance
Limited to stores with POS machines
Specifically, over 30 Million+ QR codes across India
UPI App Linking
Cannot link to PhonePe / Google Pay
In addition, it links in 60 seconds with UPI PIN
Small Spends (₹20 – ₹100)
Merchants decline swipes under ₹100
Moreover, scan & pay even ₹15 for college snacks
Physical Card Burden
Must carry physical plastic everywhere
As a result, it is 100% phone-based with zero plastic needed
⚠️ Important Rule: A RuPay credit card for students supports Person-to-Merchant (P2M) payments at verified store QR codes. Therefore, you cannot send money directly to personal bank accounts or friend phone numbers (P2P). Thus, this protocol prevents cash recycling abuse.
3. Top 4 RuPay Credit Cards for Students in India (Reviewed): Complete Guide to RuPay credit card for students
To help you pick the right card, we evaluated the leading options based on minimum deposit requirements, fee structures, and UPI reliability. Accordingly, here is our detailed review of the four best options available today.
🏆 TOP RECOMMENDATION SCHEDULED BANK BACKED
Lifetime Free (₹0 Fee)
Specifically, backed by Kotak Mahindra Bank, this is our premier pick for a student credit card looking for an authentic zero-maintenance digital account foundation.
In addition, it is issued in partnership with SBM Bank India. For instance, if you operate on a tighter pocket money budget, this is the most accessible secured credit card in the country.
First, Minimum Deposit: Starting at just ₹2,000 to ₹5,000
Second, Credit Limit: 90% of your deposit value
Third, UPI Linking: Works seamlessly on Google Pay & PhonePe
Finally, Annual Fee: ₹0 forever with zero hidden renewals
📊 LIVE CIBIL TRACKING DASHBOARD
Lifetime Free
3. In fact, paisa+ SBM RuPay Credit Card
Furthermore, this option is developed by Paisabazaar and SBM Bank India. Additionally, this card gives you a built-in credit bureau tracking dashboard updated monthly.
First, Minimum Deposit: ₹5,000 collateral deposit
Second, Rewards Rate: Flat points on merchant UPI QR scans
Third, Bureau Dashboard: Free monthly CIBIL/Experian check
Finally, Digital Approval: 100% digital within 10 minutes
Furthermore, for example, alternatively, these modern fintech platforms are partnered with Axis Bank and Utkarsh SFB. In fact, these deliver 0.5% to 1.5% cashback on everyday merchant QR scans.
Third, Digital Format: Furthermore, it is an instant 100% digital virtual card
Finally, Ideal For: Particularly ideal for tech-savvy students wanting quick daily cashback
4. How to Link a RuPay Credit Card for Students to UPI (PhonePe & Google Pay)
Overall, linking your new RuPay credit card for students to UPI is remarkably straightforward. Because the process is entirely digital, you can complete the setup in under two minutes without waiting for a physical plastic card.
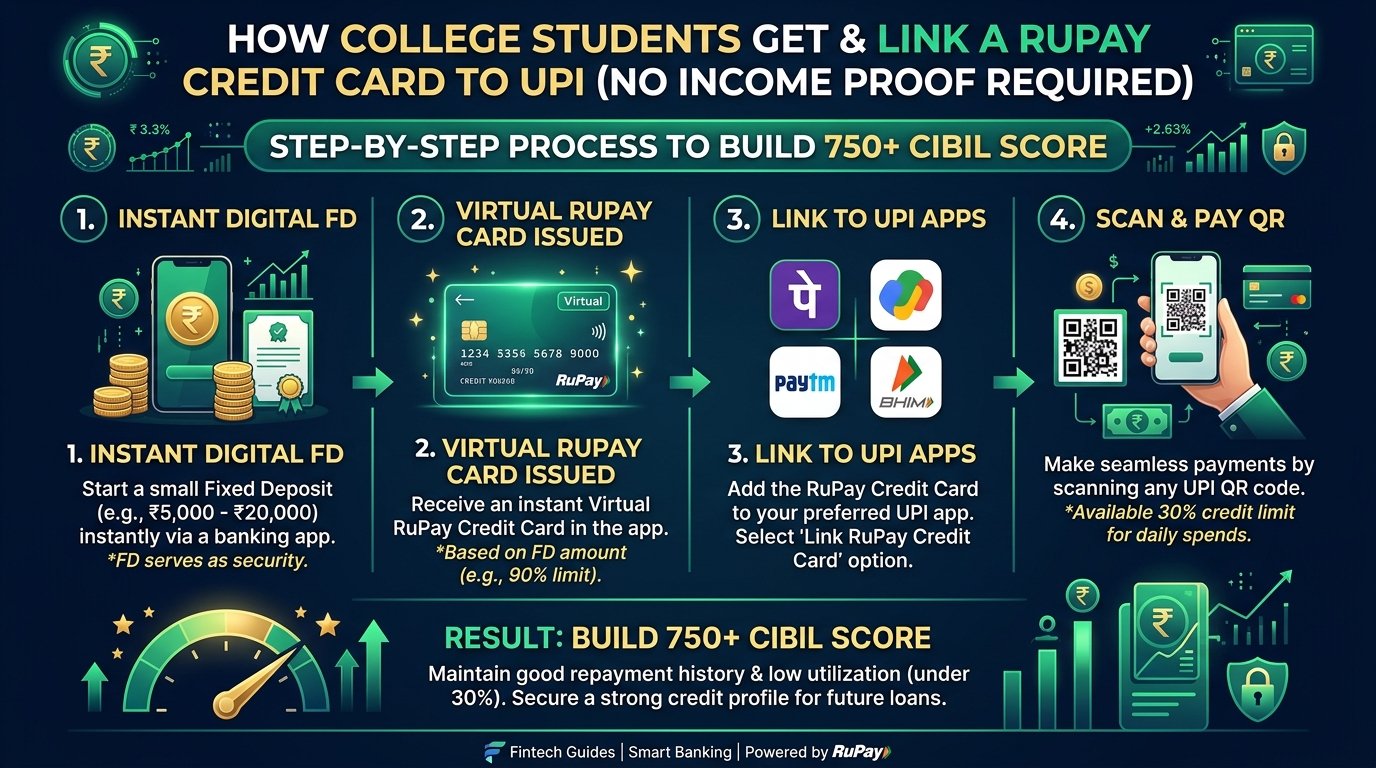
For example, Figure 1 illustrates the complete 4-step infographic roadmap showing how to get and link a virtual student RuPay card to UPI apps.
1Get Card Credentials
First, open your banking app → Credit Card → View your 16-digit card number, expiry date & CVV.
2Tap “Link RuPay on UPI”
Next, open PhonePe or Google Pay → Profile → Bank Accounts → Select Link RuPay Credit Card.
3Select Your Bank
Then, pick Kotak Mahindra or SBM. Subsequently, the app auto-detects your card using your registered mobile number.
4Set 6-Digit UPI PIN
Finally, enter the last 6 digits + expiry, confirm SMS OTP, and set your PIN. Afterwards, scan any merchant QR to pay!
5. The ₹5,000 ₹5,000 Student Math: Build 765+ CIBIL Score
Specifically, ultimately, using a secured credit card is about building an invaluable financial asset: your CIBIL credit score. In fact, a 750+ score makes future car loans, apartment leases, and premium cards instant and cheap.
📊 The Exact ₹5,000 Formula to a 765+ Score:
₹5,000
First, Initial Fixed Deposit
Naturally, it earns ~₹340/yr safe interest
₹4,500
Second, Credit Limit (90%)
Consequently, it protects against overspending
₹1,350
Third, 30% Monthly Cap
Specifically, this is the golden utilization threshold
765+
Finally, Prime Score in 6 Months
Ultimately, you reach a Prime Tier CIBIL rating
Consequently, for more actionable personal finance strategies, explore our detailed guides:
6. 3 Critical Student Traps & Hidden Charges to Avoid
Additionally, for example, even though a secured student credit card is very safe, reckless credit usage can still harm your finances. Therefore, ensure you follow these three protective rules:
❌ Trap 1: ATM Cash Withdrawals
First, never withdraw cash at ATMs using your credit card. Specifically, it triggers ₹300-₹500 cash advance fees plus 42% interest from minute one with zero grace period.
❌ Trap 2: “Minimum Amount Due”
Second, paying only 5% minimum due charges up to 42% compounding interest plus 18% GST on the remaining 95%. Instead, always pay 100% “Total Amount Due”.
❌ Trap 3: Spending Above 30% Limit
Third, spending ₹4,000 on a ₹4,500 limit gives a 90% utilization ratio. As a result, bureaus flag this as credit-hungry behavior, lowering your score. Hence, keep spends under ₹1,350/mo.
First, can a college student get a RuPay credit card without income proof in India?
However, yes. Indeed, students aged 18+ can get a secured student RuPay card backed by a small Fixed Deposit (₹2,000 to ₹10,000) with zero salary slips, zero ITR, and zero prior credit history.
Second, which bank offers the lowest FD requirement for a student RuPay card?
Specifically, the SBM ZET card starts with an FD as low as ₹2,000 to ₹5,000. In comparison, for an authentic full-service scheduled bank, Kotak 811 #DreamDifferent offers robust features starting at ₹10,000.
Third, can I send money to my friends using a RuPay credit card on UPI?
Consequently, clearly, under NPCI rules, RuPay credit cards on UPI only support Person-to-Merchant (P2M) payments at merchant QR codes. Therefore, direct transfers to personal mobile numbers or personal bank accounts are restricted.
Fourth, what happens to my Fixed Deposit while I use the credit card?
In fact, naturally, your fixed deposit remains completely untouched, earning 6.5% to 7.5% annual compounding interest. As long as you pay monthly bills on time, your deposit continues to grow safely.
Fifth, does paying via UPI credit card build a real CIBIL score?
In addition, yes. Indeed, banks report all repayment activity from your student credit card to CIBIL, Experian, and CRIF High Mark every 30 days. In fact, paying statements in full builds a 750+ CIBIL score within 6 to 9 months.
Final Thoughts: Start Your Credit Journey the Smart Way
In conclusion, you do not need to wait for a corporate job offer to build your financial reputation. Specifically, by opening an authentic zero-maintenance digital account like Kotak 811 and activating a secured RuPay credit card on UPI, you enjoy scan-and-pay convenience everywhere and graduate college with a 760+ credit score.
Therefore, are you ready to start your zero-balance digital banking journey?
In addition, open a paperless Kotak 811 account with ₹0 maintenance fees, set up your student fixed deposit, and unlock your virtual RuPay card for instant UPI payments today.
In addition, Affiliate Disclosure: This article contains an affiliate partner link. Specifically, if you open a digital account through this link, we may earn a referral commission at zero additional cost to you.
Actionable Insights and Smart Advice for RuPay credit card for students
Overall, I’m Asif Khan, founder and lead editor behind paisakmao.de. For the past two years, I’ve dedicated my work to financial education, income skills, and ethical money management tailored specifically for college students and ambitious young minds across India. Specifically, through deep research and real banking tests, I help youth build financial independence and avoid debt traps before entering the corporate workforce. Overall, learn more about my personal investing principles and editorial ethics on our About Us page.
Asif Khan
Can a college student get a RuPay credit card without income proof in India?
Furthermore, yes, students aged 18 and above can get a secured student RuPay credit card backed by a small Fixed Deposit (₹2,000 to ₹10,000) with zero salary slips, zero ITR, and zero prior credit history.
Actionable Insights and Smart Advice for RuPay credit card for students
Which bank offers the lowest FD requirement for a student RuPay card?
Specifically, the SBM ZET card starts with a minimum FD requirement of just ₹2,000 to ₹5,000. Meanwhile, Kotak 811 #DreamDifferent offers full-service banking features starting at a ₹10,000 deposit.
Can I send money to my friends using a RuPay credit card on UPI?
Additionally, for example, no. Specifically, according to NPCI guidelines, RuPay credit cards on UPI only support Person-to-Merchant (P2M) payments at verified store QR codes. For example, direct transfers to personal mobile numbers or bank accounts (P2P) are restricted.
What happens to my Fixed Deposit while I use the credit card?
Consequently, your Fixed Deposit remains 100% safe and untouched while continuously earning 6.5% to 7.5% annual compounding interest. As long as you pay your monthly bills on time, your deposit grows securely.
Learning the essential principles of Smallcase vs Mutual Fund is critical for anyone looking to build healthy money habits, avoid debt traps, and make smart financial decisions in India.
Learning the essential principles of Smallcase vs Mutual Fund is critical for anyone looking to build healthy money habits, avoid debt traps, and make smart financial decisions in India.
Learning the essential principles of Smallcase vs Mutual Fund is critical for anyone looking to build healthy money habits, avoid debt traps, and make smart financial decisions in India.
Learning the essential principles of Smallcase vs Mutual Fund is critical for anyone looking to build healthy money habits, avoid debt traps, and make smart financial decisions in India.
Essential Overview: Guide to Smallcase vs Mutual Fund
Learning about Smallcase vs Mutual Fund is essential for anyone looking to build healthy money habits. If you are stepping into the Indian stock market in 2026 with your first savings or stipend, you have almost certainly encountered the ongoing debate: Should you start with Direct Mutual Funds, or build curated stock baskets via Smallcase?
On one side, traditional mutual fund campaigns urge that “Mutual Funds Sahi Hai”. On the other, modern fintech influencers argue that “Smallcase is the 2.0 version of mutual funds because you own real shares in your Demat account without paying ongoing fund management cuts.”
Essential Overview: Guide to Smallcase vs Mutual Fund
Essential Overview: Guide to Smallcase vs Mutual Fund
Additionally, having actively invested in both instruments across bull and bear cycles over the past few years, I can tell you that the truth is far more nuanced than 30-second reels suggest. Furthermore, smallcase is an incredible product for certain investors, but for complete beginners with small starting capital, it introduces operational and tax frictions that very few creators talk about.
⚡ Quick Verdict for 2026 (TL;DR): For Beginners with Capital < ₹50,000:Direct Mutual Funds (especially a low-cost Nifty 50 Index Fund) are indisputably the better choice. You get ₹100/month automated SIPs, zero manual rebalancing hassle, and zero capital gains taxes when fund managers churn internal stocks. For Intermediate Investors with Capital > ₹1,00,000:Smallcase is a great tool for direct shareholder rights, transparency, and concentrated thematic bets (like EV, Defense, or Renewable Energy), provided you are willing to manage manual quarterly rebalance orders, DP charges, and short-term capital gains tax.
Actionable Advice and Practical Tips for Smallcase vs Mutual Fund
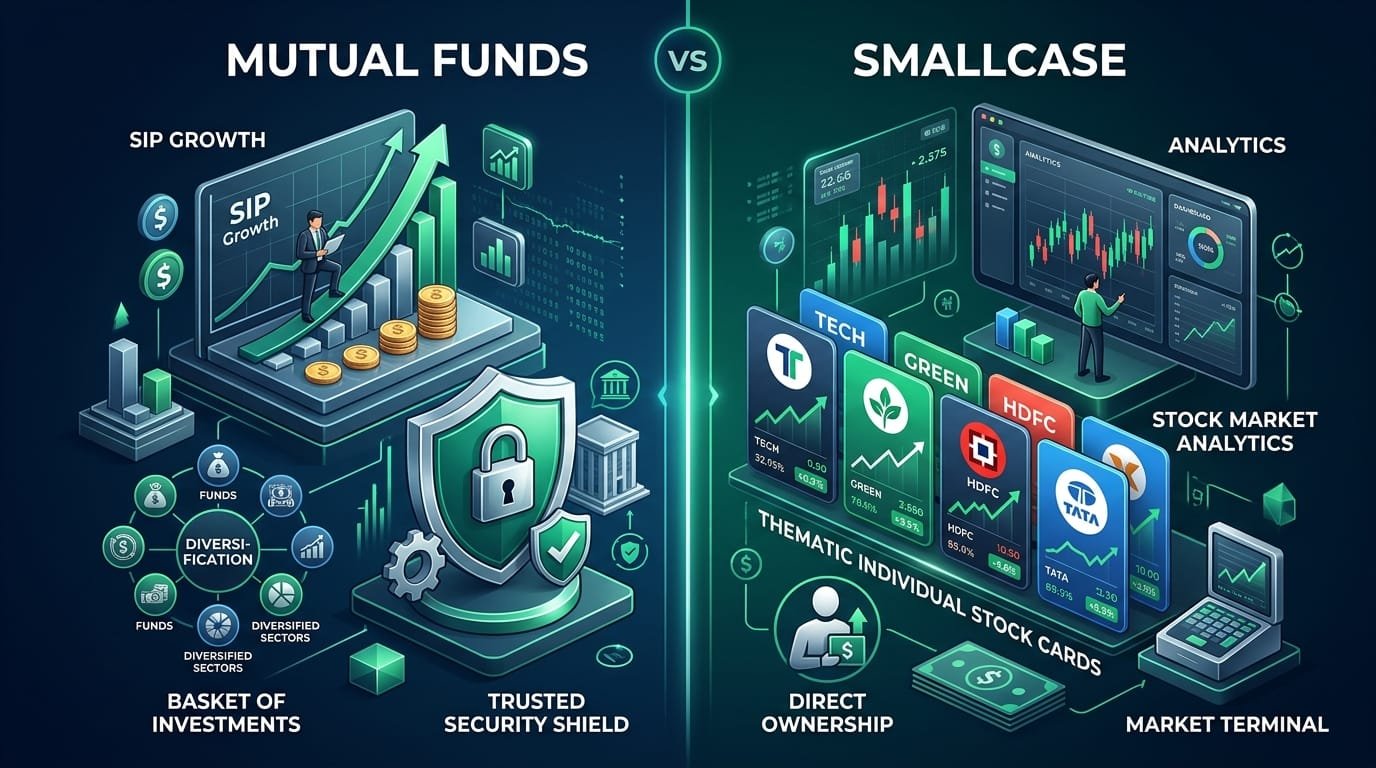
Smallcase vs Mutual Fund: Understanding the structural differences between pooled units and thematic Demat baskets.
⚡ Smallcase vs MF: Quick 30-Second Summary for Beginners
: Complete Guide to Smallcase vs Mutual Fund
If you are deciding between Smallcase vs MF (Mutual Funds) for your monthly savings or stipend in 2026, here is the direct, unfiltered verdict:
🟢 Mutual Funds (MF)
Best For: 90% of beginners, college students, and salaried professionals starting with ₹500 to ₹5,000 monthly SIP.
Automated Compounding: Rebalancing is handled automatically by SEBI-registered fund managers with zero effort.
Zero Tax Friction: No capital gains tax triggers when the fund manager buys or sells stocks internally.
Zero Hidden Fees: No DP charges, no per-trade brokerage on monthly SIP installments.
🔵 Smallcase (Direct Equities)
Best For: Active investors with ₹20,000+ capital who want direct Demat ownership and thematic exposure (e.g., Defence, EV, Green Energy).
Direct Demat Ownership: You own the actual shares in your Zerodha or Groww account.
Direct Dividends: Company dividends are credited directly into your linked bank account.
Friction Points: Every rebalance requires manual confirmation, triggers ₹15.93 DP charge per stock sold, and incurs short-term capital gains tax.
💡 Final Bottom Line: For pure wealth building with minimal hassle, choose Mutual Fund (MF) Direct-Growth. If you are passionate about direct stock ownership and have higher capital, explore Smallcase.
My Real Portfolio Experiment: What Actually Happened to ₹30,000: Complete Guide to Smallcase vs Mutual Fund
Furthermore, for example, back in late 2023, I decided to test both platforms with identical real capital rather than relying on backtested models. I put ₹30,000 into a widely recommended Smallcase (All Weather Investing) and ₹30,000 into a Direct Nifty 50 Index Mutual Fund.
Specifically, twelve months later, both portfolios showed roughly 14% to 15% pre-tax paper gains. But when I audited my actual bank deposits and tax console on Zerodha Kite, the net returns told a completely different story:
The Smallcase Friction: Over the year, the Smallcase manager issued 4 quarterly rebalancing updates. Consequently, across those rebalances, 7 stocks were sold and replaced. In addition, every single stock exit triggered a ₹15.93 CDSL DP charge, plus exchange turnover fees and STT. Specifically, even worse, selling profitable stocks within 12 months triggered a 20% Short-Term Capital Gains (STCG) tax under India’s updated tax regime. Therefore, across ₹30,000, those micro-deductions dragged down my net return by nearly 1.8%.
The Mutual Fund Compounding Advantage: The index fund manager rebalanced the underlying Nifty 50 basket internally as company weightings shifted. Yet, not a single rupee of brokerage, DP charge, or capital gains tax was deducted from my account. In fact, under Section 10(23D) of the Income Tax Act, mutual fund internal portfolio turnover is 100% tax-exempt.
The Takeaway: On smaller portfolios, transaction friction and quarterly taxes quietly devour compounding benefits before your money has time to snowball.
The Structural Architecture: How Each Model Works: Complete Guide to Smallcase vs Mutual Fund
Before comparing returns, it is essential to understand the legal and operational plumbing of both instruments.
FREE INTERACTIVE TOOL
Compare Platform Charges & Demat DP Fees
Consequently, calculate your net trading fees, brokerage, STT, and depository participant charges before executing stock baskets.
1. Furthermore, mutual Funds: The Pooled Trust Architecture: Complete Guide to Smallcase vs Mutual Fund
A mutual fund is a SEBI-regulated Trust. Moreover, millions of investors pool their capital together into a common pot managed by an Asset Management Company (AMC) like SBI, HDFC, or Nippon. A professional fund management team deploys that money across 40 to 80 individual stocks or bonds according to a defined investment mandate.
However, you do not own individual stock certificates; you receive Units (Net Asset Value – NAV) representing your proportional stake in the entire pool.
Because the pool is fractional, you can invest as little as ₹100 or ₹500 per month.
First, first, first, first, you do not even need a Demat account. You can hold mutual funds in traditional Statement of Account (SoA) format directly through AMC websites, MFCentral, or CAMS.
2. Overall, smallcase: The Demat Stock Basket Architecture: Complete Guide to Smallcase vs Mutual Fund
Furthermore, for example, smallcase is not an asset management company or a mutual fund. It is a fintech aggregation platform that connects retail investors to SEBI-registered Research Analysts (RAs) and Registered Investment Advisors (RIAs).
When you purchase a Smallcase, the platform executes a batch of market orders directly through your linked broker (such as Zerodha, Groww, Angel One, or Upstox).
You own individual shares directly in your Demat account. If the basket includes Tata Motors, Infosys, and HDFC Bank, those exact shares sit in your CDSL/NSDL holding statement.
Next, next, next, next, in fact, dividends bypass any fund manager and are credited directly to your bank account.
Because Indian law does not permit fractional equity shares, you must purchase at least 1 whole share of every company in the basket. This pushes the minimum entry ticket for most Smallcases to ₹2,500 – ₹10,000+.
Smallcase vs Mutual Fund: Head-to-Head Comparison Matrix
However, here is an objective comparison of the key parameters that directly impact your wallet:
Key Parameter
Direct Mutual Funds
Smallcase Baskets
Senior Blogger Verdict
Minimum Ticket Size
₹100 to ₹500 monthly
₹2,500 to ₹15,000+ per basket
Mutual Funds Win for pocket money budgets.
Asset Ownership
Units of the Fund (NAV)
Direct shares in your Demat account
Smallcase Wins for transparency & voting rights.
SIP Automation
100% automated via Bank e-Mandate/UPI
Requires manual login & order execution each month
Highly tailored themes (Defense, EV, Green Energy)
Smallcase Wins for focused trend investing.
Beginner Suitability
⭐ 10/10 (Passive, stress-free compounding)
⭐ 6/10 (Requires portfolio management & capital)
Mutual Funds Win for first-time investors.
The Hidden Cost Reality: Rebalancing, DP Charges, and Taxes: Complete Guide to Smallcase vs Mutual Fund
Consequently, many first-time investors see a Smallcase with a “Free to Invest” badge and assume it costs nothing. This is where real-world operational friction catches beginners off guard.
Automated recurring SIP setups on discount brokers eliminate the operational friction of manual rebalancing.
In fact, consider what happens during a standard quarterly rebalance:
Actionable Advice and Practical Tips for Smallcase vs Mutual Fund
Manual Execution Hassle: Under SEBI safety rules, no third-party app can buy or sell shares from your Demat account automatically. When a research analyst adjusts the basket, you receive an alert. You must log in during active market hours (9:15 AM to 3:30 PM), review the order, and authorize it. If you are in a college lecture or busy at work and miss the notification, your portfolio drifts off-target.
DP Charges on Every Exit: Every time a stock is sold from your Demat account, your depository (CDSL/NSDL) charges a flat fee (typically ₹15.93 + GST on discount brokers like Zerodha). If a rebalance replaces 5 stocks, you immediately pay ~₹80–₹95 in DP fees, regardless of whether your position in that stock was ₹500 or ₹50,000. On a ₹15,000 portfolio, losing ₹95 per quarter equals a 2.5% annualized fee drag!
The Short-Term Capital Gains (STCG) Drag: In Budget 2024, equity STCG tax was increased to 20%. When your Smallcase manager trims winning stocks within 12 months of purchase, that gain is immediately subject to STCG tax. In contrast, when an index mutual fund manager rebalances holdings, the compounding continues uninterrupted without triggering an immediate tax event.
In addition, want to see the compounding difference when fee friction is kept near zero? Consequently, check out our interactive calculator:
Real-World Math: ₹5,000 Monthly SIP Over 3 Years (The Hard Numbers): Complete Guide to Smallcase vs Mutual Fund
To see how these micro-charges accumulate over time, let us compare an investor putting ₹5,000 every month for 3 years (Total Capital Invested: ₹1,80,000) at an assumed 14% gross market return in both options:
Cost & Return Factor
Direct Index Mutual Fund
Smallcase Basket (4 Rebalances/Yr)
Net Investor Advantage
Total Capital Invested
₹1,80,000 (36 months × ₹5,000)
₹1,80,000 (36 months × ₹5,000)
Equal capital baseline
Brokerage & Turnover Fees
₹0 (Direct AMC / Free platform)
~₹2,160 (Buy/Sell order fees)
Mutual Fund saves ₹2,160
Depository (DP) Charges
₹0 (No Demat exit fees)
~₹1,530 (12 rebalances × 8 stock exits)
Mutual Fund saves ₹1,530
Quarterly STCG Tax Drag (20%)
₹0 (Exempt under Sec 10(23D))
~₹6,850 (Tax paid on rebalance gains)
Mutual Fund saves ₹6,850
Ongoing Platform / Advisory Fees
Expense ratio deducted in NAV (~₹900)
Free basket (₹0) to Paid (~₹6,000+)
Mutual Fund simpler deduction
Estimated In-Hand Final Corpus
~₹2,24,600
~₹2,13,800
Mutual Fund delivers ₹10,800+ extra cash!
On a modest ₹5,000 monthly SIP, the Smallcase investor loses over ₹10,800 purely to friction and quarterly tax leakage. This is why for small monthly budgets, low-cost Direct Mutual Funds consistently produce superior net in-hand wealth.
Dividend Taxation: The Silent Compounding Leak
Another major difference that most beginners overlook is how company dividend payouts are treated by the Income Tax Department:
In a Smallcase: Every dividend paid by companies in your basket is credited directly to your bank account. As a result, under Section 56(2)(i) of the Income Tax Act, dividends are added to your total income and taxed at your personal slab rate (with 10% TDS deducted if payouts exceed ₹5,000). Because that cash lands in your savings account, it is often spent on everyday expenses rather than reinvested.
In a Direct Mutual Fund (Growth Option): When underlying companies declare dividends, the fund manager instantly reinvests 100% of that capital back into more shares within the fund pool. Zero tax is deducted annually, and your compounding snowball remains entirely uninterrupted.
The 2026 Decision Framework: Which Should You Choose?
To make your decision straightforward, use this simple checklist:
Choose Direct Mutual Funds If:
Then, your monthly investable surplus is between ₹500 and ₹5,000.
Moreover, you want a strictly automated, “hands-off” process that runs on auto-pilot via UPI AutoPay or bank mandate.
Additionally, you do not want to spend hours tracking quarterly rebalance emails or calculating STCG taxes during income tax filing.
Furthermore, notably, your primary financial goal is building long-term wealth over 5, 10, or 20 years through the broad growth of the Indian economy.
Choose Smallcase If:
Finally, you have an existing investable capital of at least ₹75,000 to ₹1,00,000.
Specifically, you want direct shareholder voting rights, shareholder perks, and direct dividend deposits.
Then, first, for example, you want targeted exposure to high-conviction emerging themes (such as green hydrogen, infrastructure, or defense manufacturing) that traditional mutual funds cannot hold in concentrated proportions.
The Ideal Roadmap for Indian Beginners in 2026
Moreover, you do not have to pick one instrument and stick with it forever. The smartest strategy used by seasoned retail investors is a phased progression:
Phase 1 (The Core Foundation): Start by putting 100% of your investment capital into a low-cost Nifty 50 Index Fund (Direct Plan) with an expense ratio below 0.20%. This builds investment discipline and gets you accustomed to natural market volatility without worrying about stock selection.
Build a 3–6 Month Cash Buffer: Before taking higher equity risks, ensure you have an emergency fund parked in a high-interest savings account or liquid fund. You can calculate your exact buffer using our Emergency Fund Calculator.
Year 3 Onwards (Add Satellite Smallcases): Once your core mutual fund portfolio crosses ₹1 Lakh and you develop an understanding of market sectors, begin allocating 15% to 20% of your fresh monthly savings into a high-quality, low-churn Smallcase.
The 2-Minute Pre-Investment Checklist (Before You Hit Buy)
Before launching an investment on Zerodha Kite, Groww, or Angel One, run through this quick editorial checklist:
Beginner Preparedness Checklist: Liquidity First: Do you have at least 3 months of basic living expenses safe in a savings account or liquid fund? (Use our Emergency Fund Calculator). Time Horizon Check: Is your money committed for at least 3 to 5 years? (Equity volatility hurts short-term withdrawals). Direct Plan Verification: If picking mutual funds, ensure the fund name specifically includes “Direct – Growth” (not Regular) to avoid distributor commission cuts. Capital Suitability: If starting Smallcase, is your starting balance above ₹50,000 to absorb DP charges and rebalancing taxes comfortably? Top Mutual Funds Shortlist: If starting mutual funds, check out our curated guide on the Best 5 Mutual Funds for College Students in India (2026) for zero-commission picks.
Frequently Asked Questions (FAQ)
What is the main difference between Smallcase vs MF?
However, the fundamental difference between Smallcase vs MF lies in legal ownership, taxation, and convenience. In a Mutual Fund (MF), you own pooled units managed by a SEBI-registered AMC; internal rebalancing incurs zero capital gains tax or DP charges. In a Smallcase, you own the individual company shares in your Zerodha or Groww Demat; you receive direct corporate dividends, but each portfolio rebalancing incurs depository (DP) charges and taxable capital gains.
Mutual Fund vs Smallcase: Which gives higher returns?
Therefore, notably, neither product inherently gives higher returns since both invest in the same underlying Indian equities. However, over a 5 to 10 year horizon, low-cost Direct Mutual Funds often deliver higher net returns for retail investors because they avoid manager subscription fees (often ₹2,000–₹10,000/yr), eliminate DP charges on every rebalance, and allow uninterrupted compounding without premature tax deductions.
Can Always invest ₹500 per month in Smallcase like a mutual fund SIP?
In fact, for most baskets, no. Because Smallcase buys whole equity shares on the NSE/BSE, your minimum investment must cover at least one share of every stock in the basket. For example, if a 10-stock basket requires at least one share of each company, the minimum entry ticket often ranges from ₹2,500 to ₹8,000+. Additionally, mutual funds allow true fractional unit accumulation starting at ₹100.
Does Smallcase deliver higher returns than Mutual Funds?
Additionally, not necessarily. During aggressive bull markets, focused thematic Smallcases (such as defense or capital goods) may surge. However, they also experience steeper drawdowns during corrections. In addition, once rebalancing taxes (20% STCG), DP charges (₹15.93 per stock exit), and management fees are deducted, net returns often closely match a diversified equity index or flexi-cap mutual fund.
Actionable Insights and Smart Advice for Smallcase vs Mutual Fund
Do I need a Demat account to invest in Mutual Funds?
Particularly, no. You can invest in Direct Mutual Funds through AMC portals, MFCentral, CAMS, or apps using just your PAN and bank account (Statement of Account format). A Demat account is mandatory for Smallcase because you buy individual listed stocks on the NSE/BSE.
Does Smallcase rebalance automatically in the background?
Practical Steps & Actionable Tips for Smallcase vs Mutual Fund
Moreover, for example, no. Specifically, under SEBI regulations, automated third-party trading on personal retail Demat accounts is strictly prohibited. When a manager publishes a portfolio update, you must manually log in and click Apply Changes to execute the buy and sell orders.
Which option is better for a complete beginner with under ₹50,000 in 2026?
Overall, direct Mutual Funds, specifically a low-cost Nifty 50 Index Fund. It eliminates all manual rebalancing friction, prevents quarterly capital gains tax drag under Section 10(23D), and enables automated monthly compounding starting from just ₹100 or ₹500.
Can I switch directly from Smallcase to Mutual Funds without selling my shares?
Consequently, no. You cannot directly transfer or convert Smallcase equities into mutual fund units. To switch, you must sell your Smallcase shares in your Demat account, pay applicable DP fees and Short-Term/Long-Term Capital Gains taxes on profitable exits, transfer the proceeds to your bank account, and then start fresh mutual fund investments.
Can a Smallcase portfolio go to zero?
While an entire diversified basket going to zero is rare, a Smallcase holding 10 to 12 stocks carries substantial single-stock bankruptcy and downside risk if a constituent company crashes or faces fraud. In contrast, mutual funds hold 40 to 80 stocks with SEBI regulatory limits capping any single stock to a maximum of 10% of total assets, making total capital loss virtually impossible.
Editorial Standards & Author Profile
Asif Khan
Founder & Principal Researcher at PaisaKmao.de
Specifically, notably, asif has over 3–4 years of hands-on experience in personal finance, mutual funds, and retail stock investments in Indian markets. For example, starting as a student navigating pocket money budgeting, penny stock mistakes, and DP charges, he built a disciplined portfolio and founded PaisaKmao to provide transparent, math-backed guidance.
All insights are independently verified through live portfolio testing, fee reconciliation statements, and SEBI regulatory circulars.
Written & Researched by Asif Khan
Written & Researched by Asif Khan
Founder & Lead Financial Editor PaisaKmao.de
Additionally, over 4 years of active personal finance research in Indian markets. Specifically, focused on transparent, math-backed guides to help students and young professionals build wealth and manage money smartly.
⚖️ Regulatory & Compliance Disclaimer: In accordance with statutory guidelines from regulatory authorities like the Reserve Bank of India (RBI), The financial analysis published on PaisaKmao.de is strictly for financial literacy and educational purposes. Neither the author nor PaisaKmao.de is a SEBI-registered Research Analyst (RA) or Registered Investment Advisor (RIA). In addition, equity investments, mutual funds, and thematic baskets are subject to market risks. However, read all scheme and offer documents carefully and consult an independent SEBI-registered financial planner before committing capital.
Learning the essential principles of best mutual funds for college students is critical for anyone looking to build healthy money habits, avoid debt traps, and make smart financial decisions in India.
⚡Last Updated: November 2026SEBI-Regulated Mutual Funds Guide for Students
Learning the essential principles of best mutual funds for college students is critical for anyone looking to build healthy money habits, avoid debt traps, and make smart financial decisions in India.
Learning the essential principles of best mutual funds for college students is critical for anyone looking to build healthy money habits, avoid debt traps, and make smart financial decisions in India.
Learning the essential principles of best mutual funds for college students is critical for anyone looking to build healthy money habits, avoid debt traps, and make smart financial decisions in India.
Essential Overview: Guide to best mutual funds for college students
Learning about best mutual funds for college students is essential for anyone looking to build healthy money habits. Furthermore, starting an investment journey during college can completely transform your long-term financial future. While most college students assume that investing in the stock market requires huge capital, financial degrees, or full-time corporate salaries, the Indian mutual fund ecosystem has evolved dramatically. Specifically, today, any student with an active smartphone and just ₹100 to ₹500 from their monthly pocket money can build a high-compounding investment portfolio.
Essential Overview: Guide to best mutual funds for college students
In this comprehensive guide, we will break down the top five beginner-friendly mutual funds for Indian college students in 2026. You will learn the exact expense ratios, portfolio holdings, how to complete paperless KYC without income proof, and how to automate your monthly SIP on Zerodha Coin, Groww, or Angel One.
Essential Overview: Guide to best mutual funds for college students
Disclaimer: In accordance with statutory guidelines from regulatory authorities like the Reserve Bank of India (RBI), The financial insights shared in this article are solely for educational, academic, and informational purposes. We are not SEBI-registered investment advisors. Furthermore, mutual fund investments are subject to market risks; past performance does not guarantee future returns. Consequently, always review the Scheme Information Document (SID) on official AMC portals before investing.
Practical Steps & Actionable Tips for best mutual funds for college students
Best Investment Plan for College Students in India (2026 Step-by-Step Blueprint): Complete Guide to best mutual funds for college students
When students search for the best investment plan for college students in India, they often get confused between fixed deposits, crypto schemes, gold, and stock trading. If you have ₹500 to ₹2,000 monthly pocket money or internship stipend, here is the proven 3-step investment blueprint designed specifically for Indian college students:
Essential Overview: Guide to best mutual funds for college students
🎯 The 50-30-20 Student Pocket Money Rule
If you receive ₹3,000 to ₹6,000 monthly pocket money or internship stipend:
30% (Personal Wants): Weekend movies, social outings, gadget accessories, OTT subscriptions.
20% (Student Investment Plan): Dedicated ₹500 to ₹1,200 monthly SIP into equity mutual funds.
📊 The 3-Pillar Investment Plan for Students
1. Consequently, core Wealth Engine (50%)
Nifty 50 or Sensex Index Fund: Invest ₹500/month. As a result, ultra-low expense ratio (0.10%-0.20%), zero fund manager risk, tracks India’s top 50 corporate leaders.
2. Additionally, high-Growth Alpha Booster (30%)
Flexi Cap or Multi-Asset Fund: Invest ₹300-₹500/month. In addition, gives diversified exposure across large, mid, and small-cap stocks, plus gold for inflation protection.
3. Specifically, emergency Buffer (20%)
High-Yield Savings / Liquid Fund: Keep ₹1,000 to ₹3,000 liquid for sudden expenses like phone repairs, semester books, or emergency travel.
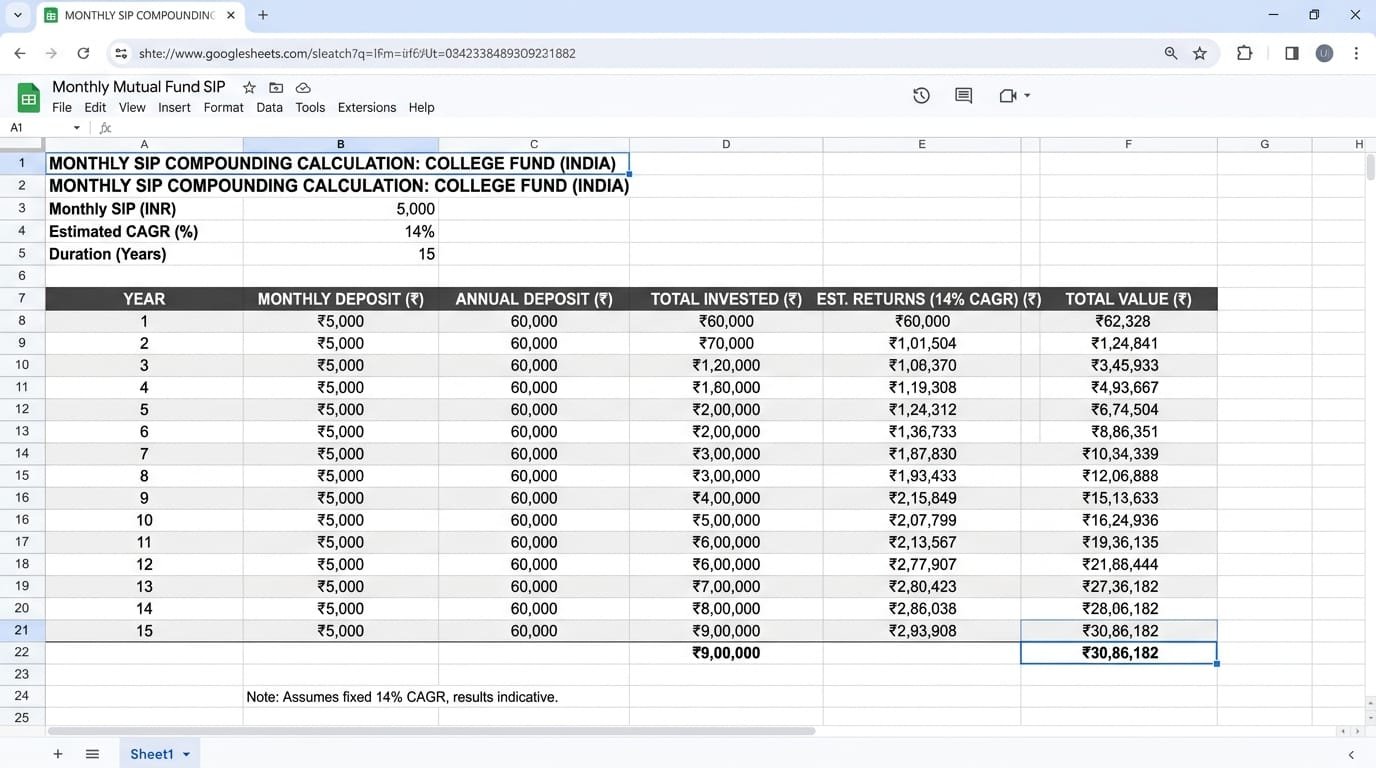
Why is this the best investment plan for college students in India? Because starting at age 19 or 20 gives you a 10-year compounding head start over your peers. For example, even a simple SIP of ₹1,000 per month at 13% CAGR grows to over ₹35.4 Lakhs by age 40, from just ₹2.4 Lakhs of total invested pocket money!
Why College Students Should Start a Mutual Fund SIP Early: Complete Guide to best mutual funds for college students
When you are 18 to 22 years old, your biggest financial superpower is not the amount of money in your wallet, but the time you have ahead of you. Specifically, compounding works like a rolling snowball: the longer your money stays invested in quality companies, the faster your returns begin to generate their own returns.
FREE INTERACTIVE TOOL
Calculate Your Monthly SIP Wealth Growth
Additionally, see how starting with just ₹500/month in college compounds into lakhs over 3, 5, or 10 years with our live SIP Calculator.
To see the real power of time, consider two college students investing ₹500 every month at an average historical return of 14% CAGR:
Student A (Starts at Age 18): Invests ₹500 every month from pocket money or freelance stipends. In addition, over 35 years until age 53, the total money deposited is just ₹2.10 Lakhs. At 14% CAGR, the final portfolio grows to over ₹35,40,000!
Student B (Waits until Age 25): Decides to wait for a full-time corporate job. By delaying by just 7 years, their portfolio reaches only ₹13,80,000.
A short 7-year delay costs Student B over ₹21 Lakhs in compounding gains. That is why starting early with whatever small amount you can save from canteen expenses is the single smartest money decision you can make in college.
Calculation Sheet: Month-by-month ₹500 SIP compounding calculation at 14% CAGR demonstrating how time beats capital.
💡 Also Comparing Mutual Funds vs Smallcase? Before selecting individual thematic stock baskets, read our comprehensive field study on Smallcase vs Mutual Fund: Which is Better for Beginners in 2026? to understand real rebalancing friction, DP exit charges, and 20% STCG tax differences.
Quick Comparison: Top 5 Mutual Funds for Students at a Glance: Complete Guide to best mutual funds for college students
Furthermore, for example, the table below provides a quick side-by-side comparison of the five premier student-friendly equity schemes based on their category, entry requirements, ongoing costs, and long-term risk profiles:
Fund Scheme
Category
Minimum SIP
Direct Expense Ratio
Risk Level
Ideal For
Parag Parikh Flexi Cap
Flexi Cap
₹1,000
~0.65%
Moderate to High
All-round wealth (5+ yrs)
Nippon India Small Cap
Small Cap
₹100
~0.70%
Very High
Aggressive growth (7+ yrs)
HDFC Index S&P BSE Sensex
Index (Passive)
₹100
~0.20%
Moderate
Safe beginner entry (3+ yrs)
Quant Multi Asset
Multi Asset
₹500
~0.75%
Moderate
Equity + Gold balance
ICICI Prudential Bluechip
Large Cap
₹100
~0.85%
Low to Moderate
Capital stability & low swings
Detailed Review of the 5 Best Mutual Funds for Students: Complete Guide to best mutual funds for college students
1. However, parag Parikh Flexi Cap Fund (Direct – Growth): Complete Guide to best mutual funds for college students
The Ultimate Foundation Fund: If you only want to invest in a single equity mutual fund throughout your entire college degree, Parag Parikh Flexi Cap is arguably the most disciplined option in India. Because it is a flexi-cap fund, the fund managers have complete freedom to invest across large-cap, mid-cap, and small-cap companies depending on where the best value lies.
Assets Under Management (AUM): ₹75,000+ Crores
Direct Expense Ratio: ~0.65% (Very competitive for an actively managed fund)
Benchmark: NIFTY 500 TRI
Top Indian Holdings: HDFC Bank, Bajaj Holdings, ITC, Power Grid, ICICI Bank
International Advantage: The fund holds global tech giants like Alphabet (Google) and Microsoft. This gives students automatic foreign currency diversification, protecting your portfolio if the Indian rupee depreciates against the US dollar.
Minimum SIP: ₹1,000 per month (Ideal if you earn stipends or receive consistent pocket money).
2. Therefore, nippon India Small Cap Fund (Direct – Growth): Complete Guide to best mutual funds for college students
Highest Growth Potential for Patient Students: Small-cap funds invest in emerging, fast-growing companies ranked 251st and below in Indian stock exchanges. In fact, nippon India Small Cap is one of the largest and most consistently managed small-cap schemes in India.
Assets Under Management (AUM): ₹55,000+ Crores
Direct Expense Ratio: ~0.70%
Benchmark: NIFTY Smallcap 250 TRI
Top Holdings: Tube Investments of India, Apar Industries, HDFC Bank, Voltamp Transformers
Why It Suits College Students: Because students have 10 to 15 years before retirement or major adult liabilities, you can easily ride out short-term market crashes. Particularly, historically, small caps offer the highest wealth multiplier over 7 to 10-year horizons.
Minimum SIP: Just ₹100 per month, making it accessible to any student with basic pocket money.
3. HDFC Index S&P BSE Sensex Fund (Direct – Growth): Complete Guide to best mutual funds for college students
The Safest, Lowest-Cost Passive Entry: An index fund does not rely on a human fund manager picking individual stocks. Instead, it mechanically mirrors India’s premier benchmark index—the S&P BSE Sensex—which tracks the country’s top 30 corporate giants like Reliance Industries, TCS, Infosys, and Larsen & Toubro.
Assets Under Management (AUM): ₹8,000+ Crores
Direct Expense Ratio:~0.20% (Ultra-low cost; almost zero fees deducted)
Tracking Error: Less than 0.05% (Extremely accurate index replication)
Zero Fund Manager Risk: You never have to worry about a manager making bad bets. As long as India’s overall economy and top industries expand, your investment grows steadily with it.
Minimum SIP:₹100 per month.
4. In fact, quant Multi Asset Fund (Direct – Growth): Complete Guide to best mutual funds for college students
All-Weather Protection During Market Dips: Most college beginners get panicked when the stock market drops 10% during exam season. A Multi Asset Allocation Fund solves this by automatically diversifying your money across three different asset classes: Equities (Stocks), Gold, and Debt (Bonds).
Why It Works: When the equity market experiences sharp corrections, gold prices frequently surge. This dynamic hedge cushions your portfolio, giving you peace of mind while still delivering equity-like returns over the long run.
Minimum SIP: ₹500 per month.
5. ICICI Prudential Bluechip Fund (Direct – Growth)
Steady Compounding with India’s Market Leaders: If your risk tolerance is low and you want maximum stability, ICICI Prudential Bluechip Fund is a premier large-cap scheme that invests primarily in India’s top 100 established market leaders.
Assets Under Management (AUM): ₹58,000+ Crores
Direct Expense Ratio: ~0.85%
Benchmark: NIFTY 100 TRI
Top Holdings: ICICI Bank, Reliance Industries, Infosys, Bharti Airtel, Larsen & Toubro, Maruti Suzuki
Defensive Character: Bluechip companies possess massive cash reserves and pricing power. During economic slowdowns, these funds experience far lower drawdowns than small-cap schemes.
Minimum SIP:₹100 per month.
How College Students Can Complete 100% Paperless Video-KYC (No Salary Slip Needed)
Specifically, one of the biggest hurdles that stops students from starting is the fear of paperwork: “I don’t have a corporate job, salary slip, or ITR. Overall, will investment apps reject me?”
Consequently, under official SEBI and AMFI guidelines, no income proof you need for mutual fund investments. Any Indian citizen who is 18 years or older can complete verification in under five minutes using three basic documents:
1. PAN Card: Required by law for all Indian capital market investments.
2. Notably, aadhaar Card: Must be linked to an active mobile number to receive an instant OTP via DigiLocker.
3. Moreover, student Savings Bank Account: Any active savings bank account in your own name (such as SBI, Kotak 811, HDFC, or Paytm Payments Bank) with UPI or net banking enabled.
When you sign up on an investment app, it connects to government records via DigiLocker. You verify your details, record a 5-second video selfie on your phone to confirm in-person verification (IPV), and your KYC is officially approved within 2 to 24 hours without stepping into a physical bank branch.
Direct Plan vs. Additionally, regular Plan: Why Students Must Never Choose Regular Plans
Furthermore, for example, every single mutual fund in India is offered in two distinct formats: Direct Plan and Regular Plan. Furthermore, understanding this distinction is crucial for protecting your wealth:
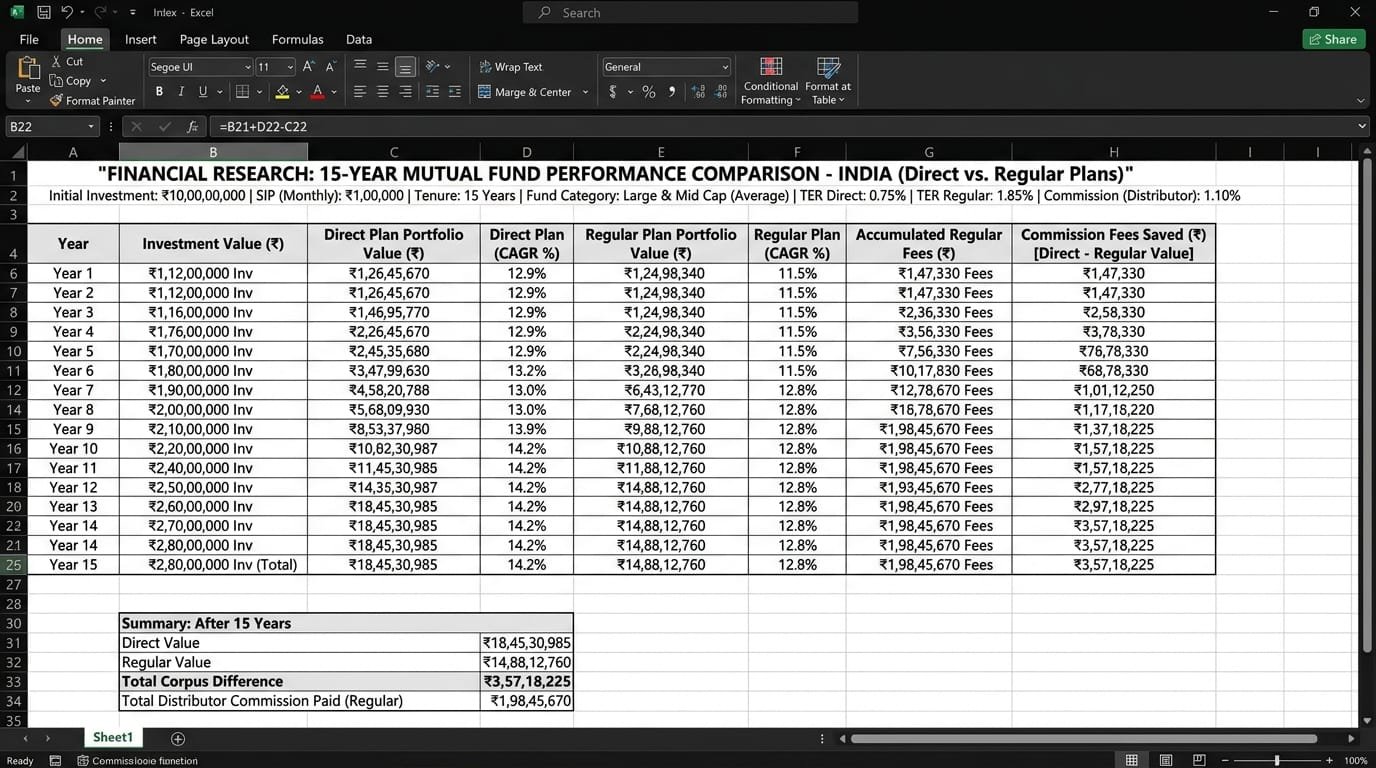
Regular Plans: Sold by traditional bank relationship managers, local agents, and commission brokers. The mutual fund company secretly deducts 1% to 1.5% from your portfolio every year to pay ongoing commissions to the broker.
Direct Plans: You invest directly through SEBI-registered discount platforms like Zerodha Coin or Groww. Overall, zero middleman commission is deducted, meaning 100% of your earnings stay in your account.
The Real Impact: On a 15-year SIP of ₹1,000 per month, that small 1.5% commission difference cuts your final wealth by over ₹2,40,000 in lost returns. For example, always make sure the word “Direct” is explicitly written in the fund title before confirming your purchase.
Research Data Sheet: How a 1.5% annual distributor commission in Regular Plans erodes over ₹1,04,000 from a 15-year student portfolio.
How to Set Up Your Monthly SIP on Groww, Zerodha Coin, and Angel One
However, automating your monthly SIP takes under three minutes on your smartphone. Consequently, here is how the top three platforms compare for college students:
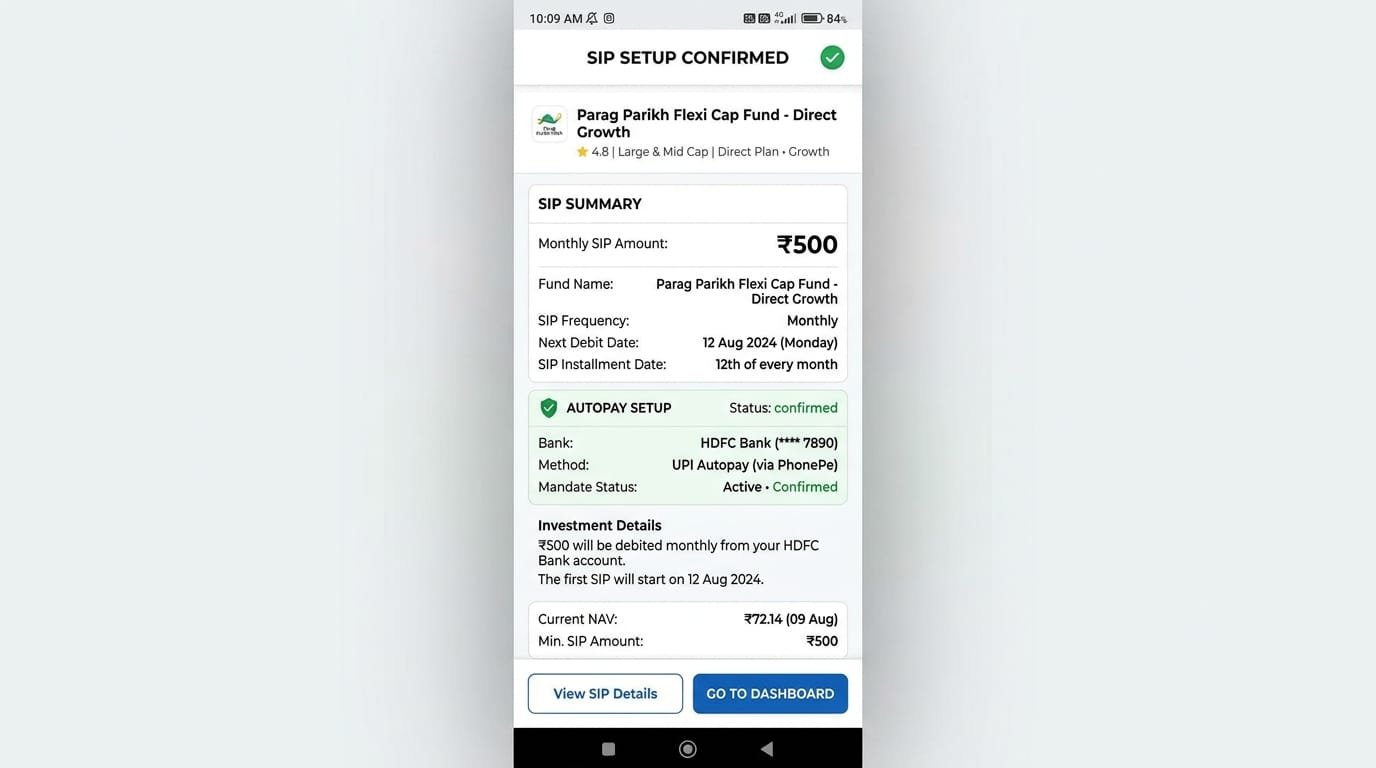
Mobile App Screen: Setting up a ₹100 or ₹500 automated monthly SIP with UPI Autopay on a verified Direct Growth plan.
Platform
Plans Available
Minimum SIP
Key Advantage for Students
Groww
100% Direct Plans
₹100
Cleanest interface for beginners, 1-click UPI Autopay setup
Zerodha Coin
100% Direct Plans
₹100
Zero distributor fees, Demat holding, and Step-Up SIP option
Angel One
100% Direct Plans
₹100
Advanced research tools, smart advisory, easy e-mandate
1. Consequently, setting Up SIP on Groww (Step-by-Step)
Download Groww & Complete DigiLocker Verification: Log in with your mobile number, verify Aadhaar OTP via DigiLocker, and enter your PAN details.
Search for Your Fund: Type the scheme name in the search bar (for example: Nippon India Small Cap Fund Direct Growth). However, always verify that it says Direct Plan.
Tap “Start SIP”: Select the Start SIP button at the bottom of the screen.
Enter Amount and Pick Date: Enter your monthly budget (₹100 or ₹500). Therefore, pick a date 2-3 days after your pocket money or allowance usually arrives.
Authorize UPI Autopay: Select Google Pay, PhonePe, or Paytm. As a result, enter your UPI PIN to approve the recurring mandate. Particularly, your automated monthly SIP is now live!
2. Moreover, setting Up SIP on Zerodha Coin (Step-by-Step)
Log into Coin: Open the Coin app or visit coin.zerodha.com using your Zerodha user ID.
Search for Direct Scheme: Search for your fund (such as HDFC Index S&P BSE Sensex Fund Direct Growth). Additionally, coin exclusively lists 100% Direct Plans with zero commission.
Click “SIP” & Choose Frequency: Tap SIP and set the frequency to Monthly. You can also turn on the Step-Up SIP feature to raise your monthly investment by 10% each year as your internship stipend grows.
Authorize Mandate: Link your student savings bank account using Net Banking or Debit Card to approve the recurring auto-debit.
3. In addition, notably, setting Up SIP on Angel One (Step-by-Step)
Go to Mutual Funds: Open the Angel One mobile app and tap on the Mutual Funds tab from the home dashboard.
Discover Scheme: Search for Parag Parikh Flexi Cap Direct Plan and check the NAV performance chart.
Confirm SIP: Tap Start SIP, choose your monthly date, enter your amount, and approve the auto-debit via UPI or Net Banking.
Mutual Fund Tax Rules for College Students (2026 Simplified)
Consequently, students often worry that investing in mutual funds will lead to tax notices. As a result, here is how Indian taxation legally applies to college students:
Zero Tax for Non-Earning Students: Under Indian tax laws, if your total annual income (including pocket money stipends and mutual fund profits) is below the basic tax exemption limit (₹3,00,000 per year under the New Tax Regime), you pay zero tax.
Long-Term Capital Gains (LTCG): For equity mutual funds held for more than 12 months, profits up to ₹1.25 Lakh every financial year are completely tax-exempt.
Short-Term Gains (STCG): If you redeem equity funds within 12 months, gains are taxed at 20%, but basic exemption thresholds continue to protect college students who do not have other taxable salaries.
How to Allocate Your Student Pocket Money for Monthly SIPs
To invest consistently without running out of money before the end of the month, follow the 50/30/20 Student Budgeting Framework:
50% for Essentials: Semester books, bus/metro transit, mobile recharges, hostel canteen meals.
30% for Fun & Social Life: Outings with friends, movies, weekend snacks.
20% for Automated SIP: Transfer ₹100, ₹500, or ₹1,000 directly into your mutual fund SIP on the day your allowance arrives before you have a chance to spend it.
Regulatory & Editorial Standards (AMFI & SEBI Disclosure): paisakmao.de is an independent financial education initiative founded by Asif Khan. We are not SEBI-registered investment advisers (RIA) or portfolio managers. Specifically, mutual fund investments are subject to market risks; please read all scheme-related documents (SID / KIM) carefully on official AMC portals before investing. Furthermore, past performance figures reflect historical data up to 2026 and do not guarantee future returns.
Frequently Asked Questions (FAQs)
What is the best investment plan for college students in India?
In fact, the best investment plan for college students in India is a combination of a Direct Nifty 50 Index Fund (like HDFC or UTI) and a Flexi Cap Fund (like Parag Parikh Flexi Cap). Specifically, allocating ₹500 to ₹1,000 monthly via SIP provides low risk, zero demat transaction charges, and compounding returns without requiring active stock market monitoring during exams.
How much pocket money should a college student invest each month?
In addition, as a general financial guideline, aim to invest 15% to 20% of your monthly pocket money or stipend. If you receive ₹3,000 per month, starting a ₹500 SIP is perfect. For example, most leading mutual funds in India allow monthly SIPs starting from as low as ₹100.
Can a college student invest in mutual funds without a job or income proof?
Moreover, yes, absolutely. SEBI and AMFI guidelines do not require salary slips or income tax returns (ITR) to invest in mutual funds. As long as you are 18+ years old with a valid PAN card, Aadhaar card, and a student bank account, you can complete paperless Video-KYC in under 5 minutes on apps like Groww or Zerodha Coin.
What is the minimum monthly SIP amount a student can start with?
However, you can start with as little as ₹100 per month. Consequently, popular student-friendly funds like Nippon India Small Cap Fund, HDFC Index S&P BSE Sensex Fund, and ICICI Prudential Bluechip Fund all allow ₹100 micro-SIPs, making investing accessible on any college budget.
What happens if I don’t have enough pocket money in my bank on SIP date?
Therefore, notably, the mutual fund company simply skips the installment for that month with zero penalties. To avoid bank auto-debit bounce fees, you can easily tap “Pause SIP” on your app 2-3 days before the scheduled date for 1 to 3 months without any charge.
Practical Steps & Actionable Tips for best mutual funds for college students
Is a Fixed Deposit (FD) better or a Mutual Fund SIP for students?
In fact, bank FDs offer guaranteed 6.5% to 7% returns, which barely beats inflation. In addition, equity mutual funds have historically delivered 14% to 18%+ CAGR over 5-7 year horizons. If you need money within a year for semester fees, use a Bank FD; for long-term wealth creation, a Mutual Fund SIP is far superior.
Which is the best and safest app for college students to invest in mutual funds?
Groww and Zerodha Coin are the top two choices. Both are SEBI-regulated, offer paperless DigiLocker KYC, charge zero account opening fees, and strictly sell Direct Plans with zero middleman commissions.
Actionable Advice and Practical Tips for best mutual funds for college students
Hi, I’m Asif Khan, the voice behind paisakmao.de. For the past two years, I’ve been blogging about financial education, income skills, and mindset development for students and young minds. My mission is to empower every youth with financial literacy and practical money-making skills at an early age. Therefore, through paisakmao.de, I share actionable guides for students to start earning early, money wisdom that schools don’t teach, and mindset lessons from successful people and modern psychology. Whether you’re a teenager looking to earn your first income or a student exploring side hustles, you’re in the right place. In fact, financial freedom begins with the right mindset and the right knowledge. Let’s grow, earn, and evolve together — welcome to the movement!
Editorial Standards & Author Profile
Asif Khan
Founder & Principal Researcher at PaisaKmao.de
Additionally, asif has over 3–4 years of hands-on experience in personal finance, mutual funds, and student pocket-money investing in Indian markets. In addition, starting as a college student with zero financial backing, he built a disciplined personal SIP portfolio and created PaisaKmao to provide transparent, math-backed guidance for young Indians.
All mutual fund insights are independently audited through AMFI fact sheets, TER sheets, and SEBI regulatory norms.
Written & Researched by Asif Khan
Written & Researched by Asif Khan
Founder & Lead Financial Editor PaisaKmao.de
Additionally, over 4 years of active personal finance research in Indian markets. Therefore, focused on transparent, math-backed guides to help students and young professionals build wealth and manage money smartly.
⚖️ Regulatory & Compliance Disclaimer: The financial analysis published on PaisaKmao.de is strictly for financial literacy and educational purposes. Moreover, neither the author nor PaisaKmao.de is a SEBI-registered Research Analyst (RA) or Registered Investment Advisor (RIA). Overall, equity mutual funds are subject to market risks. However, read all scheme related documents (SID/KIM) carefully before investing.
Learning the essential principles of Lifetime Free Credit Cards is critical for anyone looking to build healthy money habits, avoid debt traps, and make smart financial decisions in India.
⚡Last Updated: November 2026Student Credit Cards & CIBIL Building Tested
Learning the essential principles of Lifetime Free Credit Cards is critical for anyone looking to build healthy money habits, avoid debt traps, and make smart financial decisions in India.
Learning the essential principles of Lifetime Free Credit Cards is critical for anyone looking to build healthy money habits, avoid debt traps, and make smart financial decisions in India.
Learning the essential principles of lifetime free credit cards for students is critical for anyone looking to build healthy money habits, avoid debt traps, and make smart financial decisions in India.
Additionally, finding the best lifetime free credit cards for students in India allows college students to build a 750+ CIBIL score early without income proof or annual renewal fees.
📌
Key Takeaways: Lifetime Free Student Credit Cards
No Income Proof Needed: College students without salary slips can easily get approved via Fixed Deposit (FD) backing or verified college ID neo-banking cards.
100% Lifetime Free (LTF): Never pay joining or annual renewal fees as a student. Furthermore, only choose strictly lifetime free cards.
Credit Score Booster: Spend only up to 30% of your limit and pay credit card bills in full before the due date to graduate with a 750+ CIBIL score.
Student Perks: Earn instant cashback and reward points on UPI transactions, food delivery apps, and online learning courses.
Actionable Insights and Smart Advice for Lifetime Free Credit Cards
Learning about lifetime free credit cards for students is essential for anyone looking to build healthy money habits. Specifically, choosing the best 5 lifetime free credit cards for college students in India can completely transform how you manage your money, especially when you don’t have a salary slip or income proof. Furthermore, many students need instant credit options to purchase necessary gadgets, pay for online certification courses, or handle sudden educational expenses, but traditional banking rules often lead to immediate rejections. Consequently, fortunately, secured or FD-backed options provide a guaranteed route to bypass these strict requirements. In this comprehensive guide, we will break down the top student-friendly cards that charge zero annual fees, helping you secure instant buying power and build a rock-solid 750+ CIBIL score during your college years.
Written & Researched by Asif Khan
Written & Researched by Asif Khan
Founder & Lead Financial Editor PaisaKmao.de
Additionally, over 4 years of active personal finance research in Indian markets. Furthermore, focused on transparent, math-backed guides to help students and young professionals build wealth and manage money smartly.
Disclaimer: In accordance with statutory guidelines from regulatory authorities like the Reserve Bank of India (RBI), The information provided in this article is for educational and informational purposes only. We are not SEBI-registered financial advisors or banking experts. In addition, credit cards require high financial discipline and timely repayments. Specifically, late payments or defaulting on dues can severely damage your CIBIL score and attract heavy penalties. Therefore, please read all terms, conditions, and fee structures carefully on the official bank website before applying for any financial product.
Actionable Advice and Practical Tips for lifetime free credit cards for students
Practical Steps & Actionable Tips for lifetime free credit cards for students
How Can College Students Get a Credit Card Without Income Proof?: Complete Guide to lifetime free credit cards for students
Furthermore, for example, most traditional credit cards require you to submit salary slips or Income Tax Returns (ITR) to prove your monthly income. Since college students usually do not have a steady job or formal income documents, banks routinely reject their regular card applications.
However, you can easily bypass this barrier through a financial asset known as a secured credit card. Instead of looking at your monthly salary, banks issue these cards against a small Fixed Deposit (FD) that you open with them. You can read this detailed secured credit cards guide on Paisabazaar to understand the eligibility parameters deeply. The bank keeps this FD as collateral security and grants you a credit limit equivalent to 80% to 100% of your deposit amount.
Specifically, the biggest benefit of this method is that your money is never locked away uselessly. You continue to earn regular interest on your fixed deposit—often between 6.5% to 7.5% depending on the bank—while simultaneously enjoying the spending power of a credit card. It is a 100% guaranteed way for students to build a high credit history from scratch.
Quick Comparison: Best Student Credit Cards in India (2026): Complete Guide to lifetime free credit cards for students
Quick Pick: Agar aapko sabse kam FD (₹5,000) me metal card chahiye toh OneCard Lite lein. Moreover, agar aapko zero maintenance digital bank account ke sath instant card chahiye toh Kotak 811 #DreamDifferent sabse reliable hai.
Data verified for November 2026 Approvals subject to bank KYC verification
Before reading the detailed analysis, look at this quick comparison table. It highlights the baseline entry barriers, annual fees, and core purposes of the top student credit cards available in the market.
FREE INTERACTIVE TOOL
Plan Your College Expenses Before Using Credit
Consequently, never risk a credit card debt trap. Use our Student Budget Calculator to map your monthly pocket money, food, and essential spends.
Important Note: Before you apply for any card and swipe it, managing your cash flow is critical. Consequently, scroll down to the bottom of this article to download our free budgeting tracker tool to secure your payment cycles.
Detailed Review of the Best Lifetime Free Student Credit Cards: Complete Guide to lifetime free credit cards for students
Additionally, for example, choosing your first credit card can be confusing because each bank offers different benefits. To make your decision easier, here is a detailed, transparent review of the top lifetime free credit cards available for college students in India, along with their pros and cons.
1. IDFC FIRST WOW! As a result, credit Card: Complete Guide to lifetime free credit cards for students
However, the IDFC FIRST WOW! is an excellent secured card that requires zero documentation or income verification. You can check the complete application criteria on the official IDFC FIRST Bank WOW Credit Card page. This card is highly popular among students because it charges a 0% foreign markup fee, making it the cheapest option for making international transactions, such as buying foreign courses, paying for GRE/IELTS exams, or ordering global software subscriptions.
Pros: Earns regular FD interest up to 7.5% per annum; 100% cash withdrawal limit; absolutely zero joining and annual fees.
Cons: Requires a high minimum fixed deposit of ₹20,000 to get started.
2. SBM OneCard Lite
If you want a highly modern, digital-first credit card experience, the SBM OneCard Lite is a fantastic choice. Additionally, managed entirely via a smooth mobile application, it is issued against a very affordable deposit. You can read more about the digital features and reward slabs directly on the official OneCard platform. It offers 5X reward points on your top two spending categories every month, making it perfect for online shopping.
Pros: Very low minimum fixed deposit entry barrier of just ₹5,000; instant virtual card activation; sleek metal card options for higher deposit amounts.
Cons: Rewards point redemption has complex fractional slabs that take time to accumulate.
3. In addition, kotak 811 #DreamDifferent Credit Card
Consequently, the Kotak 811 #DreamDifferent Credit Card is tailored for students who already hold a Kotak 811 digital savings account. It requires a moderate fixed deposit and can be activated instantly directly through the Kotak mobile banking app. For full details on interest calculations, visit the official Kotak Mahindra Bank 811 Card portal. It gives you 2X reward points for every ₹100 spent online.
Pros: Quick in-app approval process; 100% interest-free cash withdrawal for up to 48 days; zero documentation required.
Cons: Reward points cannot be redeemed directly for cash statement credit; they must be used against specific vouchers.
★ Zero-Balance Digital Banking
100% Online 18+ Eligible
Kotak 811 Digital Savings Account
In fact, students seeking the Kotak #DreamDifferent card can start with the zero-balance 811 digital account, which activates directly with instant Video KYC.
₹0 Min Balance3-Min Video KYCFree Virtual Debit Card
Affiliate Disclosure: This article contains an affiliate link. If you open an account through this link, we may earn a commission at no additional cost to you.
How to Build a 750+ CIBIL Score in College Without Falling Into Debt Trap
In addition, getting your first credit card is easy, but managing it responsibly is the real test for a college student. If you swipe your card recklessly and fail to pay the bills on time, you will damage your CIBIL score before your career even begins. On the other hand, if you clear your total dues before the due date, you can easily build a solid 750+ credit history within 12 months.
Moreover, credit card debt traps usually happen when you do not follow a strict money management system. To prevent overspending on your new card, read our comprehensive guide on how to divide your salary for beginners with examples to learn how to allocate your funds correctly.
Additionally, using a credit card requires serious self-control. You must develop healthy spending boundaries early in life. To help you master this mindset, check out our expert blueprint on the 10 best financial habits every college student should develop. By combining the right habits with your new card, you will secure a powerful financial future.
Download Our Free College Student Budgeting and Credit Card Expense Tracker Tool
To make your financial journey completely stress-free, we have designed a customized, easy-to-use student budgeting and credit card expense tracker tool. This free spreadsheet helps you log your monthly pocket money, divide your expenses automatically, and monitor your credit card bill cycles so that you never miss a payment deadline.
To track your monthly budget and expenses easily, you can use a ready-made professional template. Specifically, click the official reference link below to save a free tracking sheet directly:
Additionally, if you want to quick-check your monthly financial math right now, you can try our interactive budget-calculator to plan your monthly income allocation in seconds.
However, please Note: If you do not have a fixed monthly stipend or work as a student freelancer, tracking your expenses can be slightly tricky. If that is your current situation, make sure to read our highly detailed blueprint on how to budget with an irregular income step-by-step guide to sync your fluctuating money flows with these calculators perfectly.
Can a college student get a credit card without an income proof or salary slip?
Therefore, notably, yes, college students can absolutely get a credit card without any income proof by choosing a secured credit card. Instead of validating your monthly salary, banks issue these cards against a small Fixed Deposit (FD) that acts as collateral security.
What is the minimum FD amount required for a student credit card?
Practical Steps & Actionable Tips for lifetime free credit cards for students
In fact, the minimum deposit required varies depending on the bank you choose. For instance, you can get started with as little as ₹5,000 for an SBM OneCard Lite, while cards like the IDFC FIRST WOW! require a minimum fixed deposit of ₹20,000 to trigger activation.
Does using a student credit card really improve your CIBIL score?
Additionally, yes, as long as you pay your credit card bills on time and in full every single month. By clearing your dues before the payment deadline, the bank reports your positive repayment behavior to credit bureaus, helping you build a solid credit history.
What happens if a student fails to pay their credit card bill?
Particularly, failing to clear your credit card dues will severely damage your credit history and drop your score instantly. To understand how utilization patterns affect your overall credit standing, you can read the official CIBIL score management guide on TransUnion CIBIL. Additionally, banks will levy heavy annual interest penalties ranging from 36% to 42% on your outstanding balance.
Conclusion: Which Student Credit Card Should You Choose?
Moreover, for example, building a solid financial foundation while studying is one of the smartest moves a college student can make. By picking a lifetime free secured credit card, you eliminate the need for any formal income proof or salary slips while unlocking a guaranteed path to a high CIBIL score.
If your primary goal is to pay for international exams, foreign subscriptions, or online global courses without losing money on conversion fees, the IDFC FIRST WOW! For example, credit Card is your best option due to its zero forex markup feature. However, if you are looking for an affordable entry point with minimal deposit requirements and a sleek design, starting with the SBM OneCard Lite at just ₹5,000 is highly recommended.
Zero Balance Digital Account
Ready to Open Your Free Kotak 811 Account?
Link an independent digital savings account to your new student card for effortless UPI and bill payments.
Affiliate Disclosure: This article contains an affiliate link. If you open an account through this link, we may earn a commission at no additional cost to you.
Practical Steps & Actionable Tips for lifetime free credit cards for students
Overall, no matter which card you select, ensure you clear your monthly statements on time, keep your credit utilization low, and utilize our free tracking spreadsheet to manage your student budget safely.
Hi, Always am Asif Khan, founder and lead research editor at PaisaKmao.de. Over the past 3 to 4 years of active personal finance research and real-money investing in Indian markets, Ensure you have navigated the practical realities of building an investment portfolio from scratch—from starting with small student pocket money, learning from early market mistakes (penny stocks, dividend tax surprises, and hidden DP charges), to establishing disciplined SIPs in low-cost index funds and managing risk. My mission with PaisaKmao.de is to provide 100% transparent, math-backed financial guides and practical calculators so young investors can build long-term wealth without falling into common traps.
Before converting any credit card purchase into “Smart EMI” or “Instant Cash”, make sure you understand how banks disguise 18% loans as 10% flat rates.
Learning the essential principles of cash stuffing method is critical for anyone looking to build healthy money habits, avoid debt traps, and make smart financial decisions in India.
Learning the essential principles of cash stuffing method is critical for anyone looking to build healthy money habits, avoid debt traps, and make smart financial decisions in India.
Learning the essential principles of cash stuffing method is critical for anyone looking to build healthy money habits, avoid debt traps, and make smart financial decisions in India.
Learning the essential principles of cash stuffing method is critical for anyone looking to build healthy money habits, avoid debt traps, and make smart financial decisions in India.
Additionally, managing money can feel difficult when small purchases keep adding up throughout the month. The cash stuffing method offers a simple way to give each spending category a clear limit and make your budget easier to see and follow.Instead of keeping your entire spending budget in one place, you divide cash into separate categories such as groceries, transportation, eating out, or personal spending. When an envelope gets low, you know exactly how much is left for that category.In this guide, you’ll learn how cash stuffing works, how to set up your first envelopes, how much to allocate to each category, and how to adapt the method for different budgets and payment habits.
Additionally, table of Contents
Practical Steps & Actionable Tips for cash stuffing method
Additionally, for verified statutory guidelines and official regulatory protections, refer directly to the Reserve Bank of India (RBI).
What Is the Cash Stuffing Method for Beginners?
Furthermore, for example, the cash stuffing method for beginners is a simple way to organize your spending by separating money into different categories. Instead of keeping all your spending money together, you decide how much you want to use for groceries, transportation, eating out, entertainment, or other everyday expenses.
Specifically, the basic idea is simple: give your money a purpose before you spend it.
Essential Overview: Guide to cash stuffing method
Consequently, for example, if you have $500 available for flexible spending, you might divide it between several categories instead of treating the entire $500 as available for anything. In India, the same idea could be applied to ₹40,000 of monthly income or spending money. The actual amounts depend on your income, bills, and personal circumstances.
How Does Cash Stuffing Work: Complete Guide to cash stuffing method
Furthermore, for example, traditional cash stuffing uses physical envelopes. Additionally, each envelope represents a spending category, and you place the amount you’ve budgeted for that category inside it.
A simple setup might include:
Groceries
Transportation
Eating out
Entertainment
Personal spending
Miscellaneous
When you spend money, you take it from the relevant category. If your grocery envelope has $150 left, for example, you know that $150 is what remains for groceries under that budget.
However, the system is closely related to the cash envelope system and traditional envelope budgeting. The Consumer Financial Protection Bureau (CFPB) has also discussed the envelope approach as a way of separating money for different spending categories.
Why Do People Use Cash Stuffing?: Complete Guide to cash stuffing method
Consequently, the main attraction is visibility.
When your spending money is separated into categories, it can be easier to notice how much you have left before making another purchase.
In fact, that doesn’t mean cash stuffing will automatically stop overspending. It simply gives you a clear spending boundary to work with.
In addition, for someone who regularly wonders, “Where did my money go this month?”, seeing separate amounts for different categories can make budgeting feel more concrete.
Does Cash Stuffing Mean Using Only Physical Cash?: Complete Guide to cash stuffing method
Moreover, not necessarily.
However, physical envelopes are the traditional version, but the underlying idea can also work with digital budgeting.
Therefore, notably, someone in the US might use cash envelopes for groceries and entertainment while keeping rent and online bills in a bank account.
A UK reader might use digital “pots” for some categories.
In India, where UPI and digital payments are widely used, someone may prefer a hybrid approach—keeping some categories in cash while tracking other spending digitally.
In fact, the important principle is separating money by purpose, not carrying every expense in your wallet.
Cash Stuffing at a Glance: Complete Guide to cash stuffing method
Element
What it means
Income
Money available for your budget
Categories
Different types of spending
Envelopes
Separate places for each category
Spending limit
Amount assigned to a category
Tracking
Recording what you spend
Review
Checking what worked and what needs adjusting
Additionally, this is only the basic idea. The next step is understanding how to actually set up a cash stuffing budget, choose the right categories, and decide how much money should go into each one.
How Much Money Should You Put in Each Cash Stuffing Envelope?: Complete Guide to cash stuffing method
Particularly, once you know your income and regular expenses, the next step is deciding how much money to put into each envelope.
FREE INTERACTIVE TOOL
Digital 50/30/20 Budget Breakdown
Moreover, for example, convert your cash envelope categories into structured Needs, Wants, and Savings targets with our instant calculator.
Overall, there is no single amount that works for everyone. In addition, your cash stuffing budget should reflect your income, essential expenses, family situation, location, and normal spending habits.
A good starting point is to look at what you actually spend rather than copying someone else’s envelope amounts.
Start With Your Real Spending: Complete Guide to cash stuffing method
Before setting your limits, look at your recent bank statements, receipts, or budgeting records.
Consequently, you might notice that groceries regularly cost more than you expected, while entertainment spending is much smaller.
Specifically, notably, that information is useful.
However, try to identify the categories where your spending is both variable and controllable.
Additionally, for example, as a result, common examples include:
Consequently, groceries
First, first, first, first, eating out
However, transportation
Next, next, next, next, entertainment
Then, in fact, clothing
Additionally, personal spending
Moreover, household purchases
Furthermore, miscellaneous expenses
If you don’t know your spending patterns yet, track them for a few weeks before creating strict limits.
In fact, this makes the cash envelope system more realistic and easier to maintain.
Separate Fixed Bills From Flexible Spending: Complete Guide to cash stuffing method
Additionally, cash stuffing doesn’t require you to put every expense into a physical envelope.
Moreover, some expenses are already predictable or automatically paid from your bank account.
Furthermore, for example:
Finally, notably, rent or mortgage
Specifically, insurance
Additionally, loan payments
Then, first, subscriptions
Additionally, next, for example, internet and phone bills
Then, other recurring payments
Specifically, notably, cash envelopes are usually more useful for spending that can change from week to week.
Consequently, for example, the goal is not to make your finances complicated. It’s to create a clear boundary around the spending you can control.
A Simple Cash Stuffing Example: Complete Guide to cash stuffing method
Additionally, imagine someone in the US takes home $2,500 a month.
Consequently, after accounting for essential bills, savings, and other financial commitments, they have $600 available for selected flexible expenses.
In addition, for example, they might start with:
Category
Example Amount
Groceries
$300
Transportation
$100
Eating out
$75
Personal spending
$75
Miscellaneous
$50
Total
$600
However, these numbers are only an example. Specifically, they are not recommended spending limits.
A person in the UK might work with £500, while someone in India might have ₹10,000 available for similar variable categories.
Consequently, the currency and cost of living change, but the basic idea remains the same: divide the money according to your own spending needs.
Don’t Set Unrealistic Envelope Limits: Complete Guide to cash stuffing method
Therefore, one common beginner mistake is trying to make the budget look perfect on paper.
However, suppose you normally spend around $350 on groceries but decide to put only $200 into your grocery envelope because you want to save more.
If you run out of money halfway through the month, the problem may not be the cash stuffing method. For example, your original limit may simply have been unrealistic.
A better approach is to start with your actual spending and make gradual adjustments
What If Your Income Changes?: Complete Guide to cash stuffing method
In fact, the cash stuffing method for beginners can also be adapted for irregular income.
If you receive money weekly, work freelance, or have changing monthly income, you don’t necessarily need to decide your entire month’s envelope amounts at once.
Instead, you can allocate money when you actually receive it.
In addition, notably, this helps prevent a common mistake: filling your envelopes first and discovering later that you don’t have enough money for an important bill.
Start Small: Complete Guide to cash stuffing method
Additionally, you don’t need ten or twenty envelopes on your first attempt.
However, as a result, start with three to five categories that are genuinely useful for your spending habits.
Additionally, for example, for example:
Consequently, groceries
Additionally, transportation
However, eating out
Furthermore, personal spending
Finally, in fact, miscellaneous
Furthermore, after a month, review what happened.
If one envelope consistently has money left over, you can reconsider its limit.
If another runs out too quickly, look at your actual spending before simply adding more money.
Consequently, your first cash stuffing budget doesn’t need to be perfect. It needs to be realistic enough to help you understand and control your spending.
What Categories Should You Use for Cash Stuffing?: Complete Guide to cash stuffing method
Specifically, you don’t need a separate envelope for every expense. Specifically, start with the spending categories where you are most likely to overspend.
Best Cash Stuffing Categories for Beginners
However, common categories include:
Groceries — food and household shopping
Transportation — fuel, bus, train, or local travel
Eating Out — restaurants, snacks, and coffee
Personal Spending — small personal purchases
Entertainment — movies, games, and hobbies
Gifts — birthdays, festivals, and special occasions
Category
Example
Groceries
$250 / £200 / ₹8,000
Transportation
$100 / £80 / ₹3,000
Eating Out
$75 / £60 / ₹2,500
Personal
$75 / £60 / ₹2,500
Therefore, for example, these amounts are only examples. In addition, your actual budget should depend on your income and regular spending.
Don’t Put Every Expense in an Envelope
In fact, fixed expenses such as rent, mortgage payments, electricity bills, and subscriptions usually don’t need physical cash envelopes. You can continue paying them digitally or through your bank account.
Consequently, for irregular expenses like gifts, clothing, or annual costs, a sinking fund can be useful. MoneyHelper explains sinking funds as a way to prepare for expenses that don’t happen every month.
If you are unsure how much you can actually afford for each category, first use the Budget Calculator.
Start small: 3–5 useful categories are usually easier to manage than 15–20 envelopes. However, once the system becomes a habit, you can add more categories if needed.
How to Start Cash Stuffing: A Step-by-Step Setup
Moreover, starting the cash stuffing method is easier when you follow a simple routine instead of trying to change all your spending habits at once. The basic idea is to decide your limits, separate the money into categories, and track what you spend.
1. Therefore, choose Your Budget Period
In addition, first, decide how often you want to organize your envelopes.
However, notably, you can use a:
Weekly system if you prefer tighter spending control
Biweekly system if you get paid every two weeks
Monthly system if you receive a monthly salary
Therefore, your choice should match your income schedule and spending pattern.
Additionally, choose a few categories that you actually use.
In fact, for example:
Specifically, groceries
Moreover, transportation
Furthermore, first, eating out
Finally, next, notably, personal spending
Then, entertainment
Particularly, for example, write the category name clearly on each envelope. Particularly, starting with 3–5 categories can make the system easier to maintain.
3. In fact, decide How Much Goes Into Each Envelope
Moreover, use the spending limits from your budget rather than guessing.
Consequently, for example, a monthly flexible-spending budget might look like this:
Category
Example Amount
Groceries
$250
Transportation
$100
Eating out
$75
Personal
$75
Overall, these amounts are only examples. Overall, your actual limits should depend on your income, essential expenses, and normal spending.
However, you can first use our Budget Calculator to organize your numbers.
4. Notably, track Every Purchase
In fact, notably, this is one of the most important parts of cash stuffing.
In fact, suppose your grocery envelope contains $250. You spend $35 at the supermarket, so your remaining amount is $215.
Particularly, as a result, writing down each purchase helps you know exactly how much is available instead of relying on memory.
Moreover, moneyHelper also recommends keeping track of income and spending when creating a workable budget. You can learn more from its budgeting guidance.
5. Moreover, review and Adjust
At the end of your budget period, check what happened.
Additionally, ask yourself:
Additionally, which envelope ran out first?
Additionally, which category had money left?
Furthermore, for example, were any limits unrealistic?
Finally, should money be moved between categories next time?
Furthermore, notably, don’t treat going over one category as failure. It can simply show that your original estimate needs adjusting.
Specifically, for readers in India, the RBI financial education material also provides guidance on budgeting and managing personal finances.
If your income is very tight and covering basic expenses is already difficult, see our paycheck-to-paycheck budgeting guide for a more focused approach.
Additionally, the goal is not to follow a perfect envelope system. The goal is to create a spending system that you can realistically follow every pay period.
What Happens When a Cash Stuffing Envelope Runs Out?
Moreover, for example, one of the biggest questions beginners have is: What should you do when an envelope reaches $0 before the end of the month?
Consequently, for example, it doesn’t automatically mean your budget has failed. It may simply mean that your spending limit needs to be reviewed.
Check Before Moving Money
In addition, first, ask whether the expense is actually necessary.
Consequently, for example, if your entertainment envelope is empty, you may decide to wait until the next budget period. But if your grocery budget is short because food prices were higher than expected, the situation may be different.
A simple rule is:
Needs first, wants second.
Situation
What You Can Do
Non-essential spending
Wait until the next period
Essential expense
Consider moving money from a lower-priority category
Unexpected expense
Use an appropriate emergency/savings fund
Budget repeatedly runs short
Recalculate your category limits
Can You Move Money Between Envelopes?
However, yes. Additionally, your budget doesn’t have to be completely rigid.
However, suppose your Eating Out envelope has $40 left, while your Groceries envelope needs another $25. If groceries are the priority, you could move $25 from Eating Out to Groceries.
Therefore, the important part is to record the transfer so you know where your money went.
What If This Happens Every Month?
If the same envelope runs out repeatedly, don’t simply keep adding money to it.
In fact, look at your actual spending and adjust the budget.
In fact, for example, if you regularly spend $300 on groceries but your budget allows only $250, your original limit may not reflect your real situation.
Moreover, our salary division guide can help you review how your income is being allocated across different priorities.
What About Leftover Money?
If an envelope still has money at the end of the period, you have several options:
Consequently, carry it into the next period
Specifically, move it toward a planned expense
However, add it to savings
Specifically, first, keep a small buffer for future spending
Particularly, for irregular expenses, a sinking-fund approach can make budgeting easier. MoneyHelper’s sinking-fund guidance explains how setting money aside over time can help prepare for expenses that don’t happen every month.
Moreover, notably, the goal of cash stuffing isn’t to punish yourself for spending. It’s to make your spending choices visible and intentional. If you’re already struggling to cover essential expenses, our paycheck-to-paycheck budgeting guide covers a more focused approach for tight budgets.
Cash Stuffing vs. Furthermore, digital Budgeting: Which Is Better?
Overall, cash stuffing works by making your spending limits visible through separate cash envelopes. Overall, digital budgeting uses bank accounts, budgeting apps, spreadsheets, or digital savings pots to organize the same idea electronically.
Additionally, neither method is automatically better. The right choice depends on how you normally spend and how often you use cash.
Feature
Cash Stuffing
Digital Budgeting
Spending visibility
Very high
High
Physical cash needed
Yes
No
Card/UPI payments
Limited unless hybrid
Easy
Tracking
Manual
Often automatic
Best for
Controlling flexible spending
Digital-first spending
When Cash Stuffing Can Work Well
Overall, notably, physical cash can make a spending limit feel more concrete. For example, once the envelope is nearly empty, you can immediately see that you’re approaching your limit.
Furthermore, notably, as a result, for example, this can be particularly useful for categories such as groceries, eating out, entertainment, or personal spending.
When Digital Budgeting Makes More Sense
Additionally, cash isn’t practical for every expense. Consequently, rent, subscriptions, online shopping, bills, and many everyday transactions are normally paid digitally.
Consequently, that’s why a hybrid cash stuffing system can be useful. You might use cash for flexible spending while keeping fixed bills and other payments in your bank account.
Furthermore, for readers in the UK, MoneyHelper’s jam jar approach shows how separating money into different pots can also be done digitally.
In India, where digital payments are widely used, you can combine cash envelopes with separate bank-account or savings categories rather than forcing every expense into physical cash.
Which Should Beginners Choose?
However, start with the method you are most likely to follow consistently.
If you often overspend on small purchases, physical envelopes may give you stronger spending awareness. If you rarely use cash, a digital or hybrid approach may be more practical.
In fact, the goal isn’t to use cash simply because it’s called “cash stuffing.” The goal is to give every spending category a clear limit and make your money easier to manage.
Common Cash Stuffing Mistakes Beginners Should Avoid
Specifically, as a result, for example, cash stuffing looks simple, but a few common mistakes can make the system difficult to maintain. The good news is that most of them are easy to fix.
1. Consequently, creating Too Many Envelopes
Moreover, you don’t need an envelope for every small expense.
Consequently, starting with 15–20 categories can make your budget feel like another chore. However, begin with 3–5 important spending categories and add more only when necessary.
2. Therefore, setting Unrealistic Limits
A budget shouldn’t be based on what you wish you spent. It should reflect your actual situation.
If you normally spend $300 on groceries but set a $150 limit without a realistic plan to reduce costs, the envelope may run out quickly.
In addition, notably, review your real spending before changing your limits. Our Budget Calculator can help you organize your numbers.
3. As a result, trying to Use Cash for Everything
However, not every expense needs a physical envelope.
Additionally, rent, subscriptions, online payments, and many bills can remain digital. A hybrid budgeting system can be more practical than forcing every payment into cash.
4. Particularly, forgetting to Track Spending
Therefore, cash can disappear quickly when you make several small purchases.
In fact, for example, write down each transaction or keep a simple note on your phone. This makes it easier to understand where your money is actually going.
5. Moreover, taking Money From Other Envelopes Without Recording It
Particularly, moving money between categories is sometimes reasonable. But repeatedly doing it without tracking the changes can hide the real problem.
If you keep taking money from groceries to cover entertainment, for example, your category limits may need to be reviewed.
6. Additionally, ignoring Irregular Expenses
Consequently, some expenses don’t appear every month but still need planning.
Moreover, gifts, annual subscriptions, clothing, repairs, and seasonal expenses you can handle through a sinking fund rather than pretending they don’t exist.
In fact, for broader money-management principles, you can also explore our 7 Rules of Personal Finance guide.
The Simple Rule to Remember
Don’t try to make your cash stuffing system perfect. Specifically, make it sustainable.
Additionally, notably, start with a few categories, use realistic limits, track your spending, and adjust the system when your circumstances change. That’s what turns cash stuffing from a budgeting experiment into a habit you can actually maintain.
Is cash stuffing good for beginners?
Moreover, yes. Furthermore, cash stuffing can be beginner-friendly because it gives each spending category a clear limit and makes it easier to see how much money is available.
How much money should I put in cash stuffing envelopes?
Furthermore, as a result, use an amount that fits your actual budget. Specifically, after essential expenses, divide your flexible spending money between categories such as groceries, transportation, personal spending, and entertainment.
What happens if I run out of money in an envelope?
Additionally, notably, check whether the expense is essential. If it is, you can move money from a lower-priority category and record the transfer. For non-essential spending, waiting until the next budget period may be the better option.
Can I do cash stuffing without using physical cash?
Furthermore, yes. You can use a digital or hybrid system with bank accounts, savings pots, spreadsheets, or budgeting apps. The principle remains the same: separate your money into spending categories with clear limits
Conclusion
Additionally, the cash stuffing method can be a simple way to make everyday spending easier to understand and control. Instead of treating your entire budget as one amount, you give different spending categories clear limits.
Specifically, you don’t need to start with a complicated system. For example, choose a few categories, set realistic amounts, track your spending, and adjust your envelopes when your real spending doesn’t match your original plan.
Specifically, for example, for example, and remember, cash stuffing doesn’t have to mean using physical cash for everything. A digital or hybrid approach can work too, especially for bills and online payments.
Actionable Advice and Practical Tips for cash stuffing method
Consequently, the best budgeting system is the one you can understand, follow, and maintain consistently. Consequently, start small, learn from each budget period, and improve your system over time.
Hi, Always am Asif Khan, founder and lead research editor at PaisaKmao.de. In addition, over the past 3 to 4 years of active personal finance research and real-money investing in Indian markets, Ensure you have navigated the practical realities of building an investment portfolio from scratch—from starting with small student pocket money, learning from early market mistakes (penny stocks, dividend tax surprises, and hidden DP charges), to establishing disciplined SIPs in low-cost index funds and managing risk. My mission with PaisaKmao.de is to provide 100% transparent, math-backed financial guides and practical calculators so young investors can build long-term wealth without falling into common traps.
Written & Researched by Asif Khan
Written & Researched by Asif Khan
Founder & Lead Financial Editor PaisaKmao.de
Additionally, over 4 years of active personal finance research in Indian markets. Focused on transparent, math-backed guides to help students and young professionals build wealth and manage money smartly.
Learning the essential principles of financial habits for college students is critical for anyone looking to build healthy money habits, avoid debt traps, and make smart financial decisions in India.
⚡Last Updated: November 2026College Financial Literacy Edition
Learning the essential principles of financial habits for college students is critical for anyone looking to build healthy money habits, avoid debt traps, and make smart financial decisions in India.
Learning the essential principles of financial habits for college students is critical for anyone looking to build healthy money habits, avoid debt traps, and make smart financial decisions in India.
Learning the essential principles of financial habits for college students is critical for anyone looking to build healthy money habits, avoid debt traps, and make smart financial decisions in India.
Additionally, mastering sound financial habits for college students sets the foundation for lifelong wealth, smart investing, and complete debt freedom.
📌
Key Takeaways: Essential Financial Habits for Students
Start With ₹500/Month: Building the habit of saving consistently matters far more than the initial amount during your college years.
Track Daily Outflows: Log everyday small expenses (canteen, tea, outings) using simple budgeting tools to prevent end-of-month cash emergencies.
Beware of Debt Traps: Strictly stay away from predatory instant loan apps, unregulated credit schemes, and unnecessary Buy Now Pay Later (BNPL) loans.
Build an Emergency Buffer: Keep at least 1–2 months of living allowance in a digital zero-balance savings account for unexpected academic or travel needs.
Learning about financial habits for college students is essential for anyone looking to build healthy money habits. INTRODUCTION
Additionally, starting college is exciting, but it also brings new financial responsibilities. For many students, this is the first time they have complete control over their money. Whether you receive a monthly allowance from your family, earn ₹10,000–₹20,000 ($100–$300) from a part-time job, or manage a scholarship, every financial decision you make today shapes your future.
Furthermore, for example, table of Contents
Practical Steps & Actionable Tips for financial habits for college students
Specifically, for verified statutory guidelines and official consumer protections, refer to the Reserve Bank of India (RBI).
1.Why Financial Habits Matter in College: Complete Guide to financial habits for college students
Consequently, college is more than a place to earn a degree—it’s where your financial future quietly begins. For many students, this is the first time they manage their own money, make independent financial decisions, and learn the real difference between needs and wants. Whether your monthly income comes from a scholarship, a part-time job, freelancing, or family support, the habits you develop today will shape your financial life long after graduation.
Additionally, for example, the 10 Best Financial Habits Every College Student Should Develop aren’t simply money-saving tips. Furthermore, they are lifelong principles that help you build discipline, reduce financial stress, avoid unnecessary debt, and create a strong foundation for financial independence. Moreover, according to the Consumer Financial Protection Bureau (CFPB), students who learn budgeting and responsible money management early are more likely to achieve long-term financial stability.
The Long-Term Impact of Small Money Decisions: Complete Guide to financial habits for college students
However, many students believe that financial success depends on earning more money. In reality, it depends on making better decisions with the money you already have.
Consequently, imagine spending just ₹200 ($2.40) every day on coffee, food delivery, online shopping, or impulse purchases. It doesn’t feel expensive because it’s only one small transaction. However, over one year, that habit costs nearly ₹73,000 ($880+)—enough to buy a quality laptop, build an emergency fund, pay for professional certifications, or even start investing.
In fact, now imagine doing the exact opposite.
Instead of spending that ₹200 every day, you save or invest it consistently. Overall, without increasing your income, you’ve already created a financial system that works for you rather than against you.
In addition, this is why experts often say that wealth isn’t built by one big decision—it is built by thousands of small decisions repeated consistently.
A Simple Real-Life Example
Moreover, consider two college students who each receive ₹15,000 ($180) every month.
However, the first student spends money whenever they feel like it. Consequently, they never check where their money goes and often run out of cash before the month ends.
Therefore, notably, the second student receives the same amount but saves 20% (₹3,000 / $36) before spending anything else. As a result, they follow a simple budget, review their expenses every weekend, and avoid unnecessary purchases.
In fact, after one year, both students earned exactly the same amount of money.
Additionally, the only difference is that one developed financial stress, while the other developed financial freedom.
Why Building Financial Habits Early Gives You a Competitive Advantage: Complete Guide to financial habits for college students
Particularly, good financial habits work like compound interest—the earlier you build them, the greater the rewards become over time.
Moreover, for example, research from the OECD Financial Education shows that people with stronger financial literacy are more likely to save regularly, avoid unnecessary debt, and make informed financial decisions throughout their lives.
Overall, you don’t need a six-figure salary to start building wealth.
Consequently, you need the discipline to make one smart financial decision today, then repeat it tomorrow, next week, next month, and next year.
Key Takeaway
Furthermore, notably, your salary may determine how much money enters your bank account.
However, your financial habits determine how much of that money stays there.
Start building the right habits in college, and your future self will thank you for every smart financial decision you make today.
2. Additionally, create a Monthly Budget That Actually Works: Complete Guide to financial habits for college students
A budget isn’t about restricting your life—it’s about giving every rupee and dollar a purpose. One of the biggest financial mistakes college students make is spending first and wondering where their money went at the end of the month. A simple monthly budget helps you stay in control, reduce financial stress, and make smarter decisions without sacrificing the things you enjoy.
FREE INTERACTIVE TOOL
Start Habit #1: Track Your Student Budget Today
Specifically, as a result, take 2 minutes to calculate your exact monthly pocket money, hostel spends, and discretionary savings.
Whether your monthly income is ₹10,000 ($120) or ₹25,000 ($300), budgeting ensures that your essential expenses, savings, and personal spending remain balanced. In addition, according to the Consumer Financial Protection Bureau (CFPB), creating and following a budget is one of the most effective ways to improve financial health and avoid unnecessary debt.
Why Every College Student Needs a Budget: Complete Guide to financial habits for college students
In fact, without a budget, it’s easy to underestimate small daily expenses. A few online orders, food deliveries, subscriptions, and impulse purchases may not seem expensive individually, but together they can consume a large portion of your monthly income.
A well-planned budget helps you:
First, first, first, first, know exactly where your money goes.
However, avoid overspending before the month ends.
Next, next, next, next, save consistently for future goals.
Then, in fact, prepare for unexpected expenses.
Additionally, spend with confidence instead of guilt.
A Simple Student Budget Example
Category
Recommended Allocation
Example (₹15,000 / $180)
Essential Expenses
50%
₹7,500 ($90)
Savings
20%
₹3,000 ($36)
Learning & Skill Development
20%
₹3,000 ($36)
Entertainment & Personal Spending
10%
₹1,500 ($18)
Additionally, this isn’t a fixed rule. Specifically, adjust the percentages based on your income and responsibilities, but always make saving a priority before spending.
Budgeting Isn’t About Spending Less—It’s About Spending Smarter: Complete Guide to financial habits for college students
Moreover, many students think budgeting means giving up everything they enjoy. In reality, budgeting gives you permission to spend on what truly matters while avoiding wasteful expenses that don’t improve your life.
Furthermore, research from the OECD Financial Education shows that people who regularly plan and monitor their finances are more likely to achieve long-term financial security than those who spend without a plan.
A budget doesn’t limit your freedom—it protects your future by making every rupee and dollar work with purpose.
3. For example, save Money Before You Spend: Complete Guide to financial habits for college students
Specifically, notably, one of the biggest differences between students who achieve financial stability and those who constantly struggle isn’t how much they earn—it’s when they choose to save. Specifically, most people spend first and save whatever is left at the end of the month. In addition, unfortunately, for many college students, nothing is left to save.
★ Zero-Balance Digital Banking
100% Online 18+ Eligible
Kotak 811 Digital Savings Account
Additionally, for example, for example, practice “Paying Yourself First” by routing your college savings directly into a separate zero-maintenance digital bank account.
₹0 Min Balance3-Min Video KYCFree Virtual Debit Card
Affiliate Disclosure: This article contains an affiliate link. If you open an account through this link, we may earn a commission at no additional cost to you.
Additionally, financially successful people follow a different approach known as “Pay Yourself First.” Instead of treating savings as an afterthought, they make it their first financial priority. However, even if you can only save ₹100–₹300 ($1–$4) a day, that habit can grow into thousands of rupees or hundreds of dollars over time.
According to the Consumer Financial Protection Bureau (CFPB), automatically saving a portion of your income before spending can improve financial security and help you prepare for unexpected expenses.
What Does “Pay Yourself First” Really Mean?: Complete Guide to financial habits for college students
Consequently, the moment your monthly allowance, scholarship, freelance payment, or salary arrives, move a fixed percentage directly into your savings account before paying for anything else.
In addition, for example, this simple habit changes your mindset from:
“I’ll save whatever is left.”
to
“I’ll spend only what’s left after saving.”
However, that small shift can completely transform your financial future.
How Much Should a College Student Save?
Monthly Income
Minimum Savings (10%)
Ideal Savings (20%)
₹10,000 ($120)
₹1,000 ($12)
₹2,000 ($24)
₹15,000 ($180)
₹1,500 ($18)
₹3,000 ($36)
₹20,000 ($240)
₹2,000 ($24)
₹4,000 ($48)
₹25,000 ($300)
₹2,500 ($30)
₹5,000 ($60)
Consequently, don’t worry if you can’t save 20% immediately. The most important goal is to build the habit of saving consistently, even if you start with a smaller amount.
Why Saving First Is More Powerful Than Saving Later: Complete Guide to financial habits for college students
Therefore, imagine two students who each receive ₹15,000 ($180) every month.
Student A spends freely throughout the month and tries to save whatever remains. Therefore, most months, nothing is left.
Student B immediately transfers ₹3,000 ($36) into a savings account on the day the money arrives. In fact, they learn to live comfortably on the remaining ₹12,000 ($144).
However, after one year, Student B has saved ₹36,000 ($430+) without increasing their income. Particularly, more importantly, they’ve built a habit that can continue for decades.
In fact, research from the OECD Financial Education shows that consistent saving habits are strongly linked to better financial resilience, lower debt, and greater long-term financial confidence.
You don’t become wealthy because you save what’s left after spending. You build wealth by spending what’s left after saving.
4. In fact, track Every Expense Without Making It Complicated
In fact, many college students believe they don’t spend much money. However, the real problem isn’t always how much they spend—it’s not knowing where their money goes. Overall, small daily expenses like coffee, food delivery, online subscriptions, and impulse purchases can quietly drain your budget without you noticing.
Particularly, tracking your expenses isn’t about recording every rupee forever. It’s about understanding your spending habits so you can make smarter financial decisions. Notably, according to the Consumer Financial Protection Bureau (CFPB), regularly monitoring your spending is one of the simplest ways to improve budgeting and avoid unnecessary financial stress.
A Simple Expense Tracking Method
Category
Example
🍽️ Food & Drinks
₹3,500 ($42)
🚕 Transportation
₹1,200 ($14)
📚 Education
₹2,000 ($24)
🎬 Entertainment
₹1,000 ($12)
💰 Savings
₹3,000 ($36)
📱 Other Expenses
₹1,300 ($16)
Moreover, you don’t need expensive apps to do this. A simple notes app, spreadsheet, or budgeting app is enough to record your daily spending for just 30 days. By the end of the month, you’ll clearly see where your money is going and which expenses can be reduced.
Pro Tip
At the end of every week, spend 10 minutes reviewing your expenses. This small habit helps you identify unnecessary spending before it becomes a long-term financial problem.
You can’t improve what you don’t measure. Moreover, tracking your expenses is the first step toward taking control of your money.
5. Additionally, build an Emergency Fund Before You Need It
Moreover, life is unpredictable. A medical emergency, laptop repair, unexpected travel, or a sudden loss of income can happen when you least expect it. Furthermore, without savings, many college students rely on credit cards or borrow money from friends and family, creating unnecessary financial stress.
Overall, notably, an emergency fund is money set aside specifically for unexpected expenses—not for shopping, vacations, or entertainment. Overall, according to the Consumer Financial Protection Bureau (CFPB), having emergency savings can help people avoid debt and recover from financial setbacks more quickly.
How Much Should a College Student Save?
Monthly Expenses
Recommended Emergency Fund
₹8,000 ($95)
₹16,000–₹24,000 ($190–$285)
₹12,000 ($145)
₹24,000–₹36,000 ($285–$430)
₹15,000 ($180)
₹30,000–₹45,000 ($360–$540)
₹20,000 ($240)
₹40,000–₹60,000 ($480–$720)
Consequently, notably, don’t worry if you can’t build this amount immediately. For example, start by saving a small portion every month. Consequently, even ₹500–₹1,000 ($6–$12) saved consistently can grow into a reliable financial safety net over time.
Where Should You Keep Your Emergency Fund?
Additionally, keep this money in a separate savings account where it’s easy to access during emergencies but not so convenient that you’re tempted to spend it on everyday purchases.
An emergency fund doesn’t make you richer overnight—it gives you peace of mind when life doesn’t go according to plan.
6. Consequently, avoid Impulse Buying and Think Before You Spend
In addition, as a result, impulse buying is one of the biggest reasons college students struggle to save money. However, flash sales, limited-time offers, social media ads, and one-click online shopping make it easy to spend money on things you never planned to buy. While a single purchase may seem harmless, repeated impulse spending can quietly damage your monthly budget.
Additionally, for example, building the habit of thinking before spending helps you stay in control of your money instead of letting emotions control your decisions. Therefore, according to the Consumer Financial Protection Bureau (CFPB), creating a spending plan and avoiding emotional purchases are important steps toward better financial health.
The 24-Hour Rule
Before buying any non-essential item, wait 24 hours.
Furthermore, ask yourself these simple questions:
Do I really need this, or do I just want it?
Will I still use it after one month?
Does this purchase fit my monthly budget?
Can this money be used for something more valuable?
Consequently, most impulse purchases lose their appeal after a day, helping you save money without feeling deprived.
Smart Spending Checklist
Before You Buy
Ask Yourself
Need or Want?
Is this essential?
Budget Check
Can I afford it without affecting my savings?
Future Value
Will this improve my life or skills?
24-Hour Rule
Can this purchase wait until tomorrow?
Every purchase is a financial decision. As a result, spend with purpose today, and your future self will thank you tomorrow.
7. Particularly, start Investing Early—Even with a Small Amount
Specifically, many college students believe they need thousands of rupees or dollars before they can start investing. In reality, the most valuable advantage an investor has isn’t a large amount of money—it’s time. Moreover, starting early allows your investments more time to grow through the power of compounding.
However, you don’t have to begin with a large portfolio. Additionally, even investing ₹500–₹1,000 ($6–$12) every month can help you develop the habit of investing while learning how financial markets work. The goal during college isn’t to become rich overnight—it’s to become a disciplined long-term investor.
However, for example, once these foundations are in place, you can gradually begin your investing journey.
Investment Habit
Why It Matters
Invest Every Month
Builds discipline and consistency
Think Long-Term
Reduces emotional decisions
Keep Learning
Helps you make smarter investment choices
Avoid “Get Rich Quick” Schemes
Protects your money from unnecessary risks
A Long-Term Mindset Wins
In fact, successful investing isn’t about predicting tomorrow’s market. It’s about staying patient, investing consistently, and allowing time to work in your favor.
The best time to start investing was yesterday. The second-best time is today. As a result, small investments made consistently can grow into significant wealth over the long term.
8. Specifically, avoid High-Interest Debt and Borrow Responsibly
Consequently, debt isn’t always bad, but high-interest debt can quickly become a financial burden—especially for college students with limited income. Furthermore, many students borrow money for non-essential purchases, use credit cards carelessly, or take personal loans without understanding how interest works. These small decisions can create long-term financial stress.
Learning to borrow responsibly is one of the best financial habits every college student should develop. If you need to borrow money, make sure it’s for an important purpose such as education, an emergency, or something that genuinely improves your future—not for impulse shopping or luxury purchases.
According to the Consumer Financial Protection Bureau (CFPB), understanding interest rates, repayment terms, and borrowing limits can help consumers avoid unnecessary debt and protect their financial well-being.
Good Debt vs. Bad Debt
Type of Debt
Smart or Risky?
Example
📚 Education Loan
Good (when planned wisely)
College tuition or skill development
🏥 Emergency Medical Loan
Good
Unexpected medical expenses
📱 Buying the Latest Phone on Credit
❌ Risky
Non-essential purchase
🛍️ Shopping with Borrowed Money
❌ Risky
Clothes, gadgets, luxury items
Borrow Only When Necessary
Before taking any loan or using a credit card, ask yourself:
Do I really need this money?
Can I comfortably repay it on time?
Will this borrowing improve my future or just satisfy a temporary desire?
If the answer is no, it’s usually better to wait, save, and pay with your own money.
Debt can be a useful financial tool when used wisely—but when used carelessly, it can delay your financial freedom for years.
9. Set Clear Financial Goals and Review Your Progress
Moreover, without a clear goal, it’s easy to spend money without thinking about the future. Specifically, financial goals give your money a purpose and help you stay motivated, even when it’s tempting to make unnecessary purchases. Whether your goal is building an emergency fund, buying a laptop, starting to invest, or graduating without debt, having a written plan makes it much easier to stay on track.
In addition, the best financial habits every college student should develop include setting both short-term and long-term goals. For example, according to the Consumer Financial Protection Bureau (CFPB), people who write down their financial goals and regularly review their progress are more likely to achieve them than those who simply keep goals in their mind.
Set SMART Financial Goals
However, notably, your financial goals should be Specific, Measurable, Achievable, Relevant, and Time-bound (SMART).
Goal
Target
Time Frame
💰 Build an Emergency Fund
₹30,000 ($360)
12 Months
💻 Buy a Laptop
₹60,000 ($720)
18 Months
📈 Start Investing
₹1,000/month
This Month
📚 Skill Development
Complete 2 Online Courses
6 Months
Review Your Goals Every Month
At the end of each month, ask yourself:
Finally, did I stay within my budget?
Specifically, did I save the amount I planned?
Then, first, am I getting closer to my financial goal?
Additionally, next, what financial mistake can Always avoid next month?
Therefore, even if your progress is slow, consistency matters more than perfection.
A goal without a plan is only a wish. Consequently, give every rupee and every dollar a purpose, and your financial future will become much clearer.
10. In addition, review Your Finances Every Month and Keep Improving
Additionally, building good financial habits isn’t a one-time task—it’s an ongoing process. Even the best budget won’t help if you never review it. That’s why one of the best financial habits every college student should develop is setting aside a few minutes every month to evaluate their financial progress.
A monthly financial review helps you understand what’s working, identify unnecessary expenses, improve your savings, and make better decisions for the next month. Therefore, according to the Consumer Financial Protection Bureau (CFPB), regularly reviewing your budget, savings, and financial goals can improve money management and reduce financial stress over time.
Zero Balance Digital Account
Ready to Open Your Free Kotak 811 Account?
Build your financial foundation with a 100% paperless student-friendly zero balance account.
Affiliate Disclosure: This article contains an affiliate link. If you open an account through this link, we may earn a commission at no additional cost to you.
Your 15-Minute Monthly Money Review
At the end of each month, answer these questions honestly:
Review Question
Your Goal
💰 Did I stay within my monthly budget?
Yes
📊 Did I save at least 10–20% of my income?
Yes
🛒 What was my biggest unnecessary expense?
Identify & reduce it
🎯 Am I closer to my financial goals?
Measure your progress
📚 What financial lesson did I learn this month?
Improve next month
In fact, you don’t need complicated spreadsheets or expensive apps. A notebook, spreadsheet, or budgeting app is enough to review your finances in just 15 minutes every month.
Small Improvements Lead to Big Results
If you improve your financial habits by just 1% every month, you’ll make significantly better financial decisions over the course of a year. In fact, review your progress, celebrate small wins, learn from mistakes, and keep moving forward.
Financial success isn’t about being perfect every month—it’s about becoming a little smarter with your money every single month.
### Can college students become financially independent while studying?
Particularly, for example, yes. In addition, financial independence doesn’t happen overnight, but college students can begin building it by following a budget, saving consistently, developing valuable skills, earning through part-time work or freelancing, and avoiding unnecessary debt. The earlier you start, the stronger your financial future becomes.
What is the 50/30/20 budgeting rule for college students?
Moreover, the 50/30/20 budgeting rule recommends using **50%** of your income for essential needs, **30%** for personal wants, and **20%** for savings or investments. It’s a simple budgeting framework that helps college students manage money more effectively and build healthy financial habits.
How much emergency savings should a college student have?
Practical Steps & Actionable Tips for financial habits for college students
A good starting goal is to save enough to cover **one to three months of essential expenses**. If that’s not possible, begin with a smaller target such as **₹10,000–₹20,000 ($120–$240)** and increase your emergency fund gradually through consistent monthly savings.
### Which financial skill should every college student learn first?
Consequently, budgeting is the most important financial skill for college students. Moreover, once you understand how to manage your income and expenses, it becomes much easier to save money, avoid debt, invest wisely, and achieve your long-term financial goals.
Actionable Insights and Smart Advice for financial habits for college students
## ConclusionDeveloping strong financial habits during college is one of the smartest investments you can make for your future. By creating a budget, saving consistently, tracking expenses, avoiding unnecessary debt, and setting clear financial goals, you’ll build a solid foundation for long-term financial success.Remember, financial freedom doesn’t depend on how much you earn—it depends on how wisely you manage your money. Overall, start with one habit, stay consistent, and improve a little every month. However, over time, these small actions can lead to greater financial confidence, stability, and lasting wealth.**The best financial habits you build today can shape a more secure and successful tomorrow.**
Additionally, over 4 years of active personal finance research in Indian markets. Therefore, focused on transparent, math-backed guides to help students and young professionals build wealth and manage money smartly.