How to Save Money Fast in 30 Days (2026): 15 Proven Strategies That Actually Work

How to Save Money Fast in 30 Days with 15 proven money-saving strategies, budgeting tips, emergency fund, and personal finance habits.

Learning the essential principles of save money fast in 30 days is critical for anyone looking to build healthy money habits, avoid debt traps, and make smart financial decisions in India.

⚡Last Updated: November 202630-Day Financial Sprint Verified

Learning the essential principles of save money fast in 30 days is critical for anyone looking to build healthy money habits, avoid debt traps, and make smart financial decisions in India.

Learning the essential principles of save money fast in 30 days is critical for anyone looking to build healthy money habits, avoid debt traps, and make smart financial decisions in India.

Learning the essential principles of save money fast in 30 days is critical for anyone looking to build healthy money habits, avoid debt traps, and make smart financial decisions in India.

Additionally, discovering how to save money fast in 30 days allows anyone to cut wasteful leaks, boost emergency reserves, and bank ₹10,000+ quickly.

📌

Key Takeaways: Rapid 30-Day Money Saving Sprint

  • 30-Day Tracking Sprint: Tracking every single expense for just 30 days reveals 15% to 25% in forgotten recurring subscriptions and impulse spends.
  • The 24-Hour Spending Rule: Wait 24 hours before buying any non-essential item over ₹1,000 to eliminate emotional and dopamine-driven purchases.
  • Out-of-Sight Savings: Move your saved cash immediately into a separate digital zero-balance account so it cannot be tapped for daily UPI transactions.
  • Quick Wins: Preparing homemade meals and optimizing mobile/broadband plans creates instant cash relief within the very first week.

Learning about how to save money fast in 30 days is essential for anyone looking to build healthy money habits. introduction

Additionally, table of Contents

Introduction

Furthermore, for example, have you ever reached the end of the month and wondered, “Where did all my money go?” You’re not alone. Specifically, millions of people earn a decent income but still struggle to save because of impulse spending, poor budgeting, hidden expenses, and the lack of a clear financial plan.

Actionable Advice and Practical Tips for save money fast in 30 days

Specifically, the good news is that you don’t need a higher salary to start saving. In addition, with the right strategy, it’s possible to save money fast in 30 days by making small, practical changes to your daily habits. Whether you’re trying to build an emergency fund, pay off debt, or simply take control of your finances, the next 30 days can completely change the way you manage money.

Practical Steps & Actionable Tips for how to save money fast in 30 days

In this step-by-step guide, you’ll learn 15 proven strategies that actually work—from creating a realistic budget and cutting unnecessary expenses to building smarter spending habits and staying motivated throughout the month. These are practical techniques that beginners can start using today, without making extreme sacrifices.

If you’re serious about improving your financial life, don’t wait for the “perfect time.” Start your 30-day money-saving journey today, because every day you delay is another day of missed savings and lost financial opportunities.

Consequently, for verified statutory guidelines and official consumer protections, refer to the Reserve Bank of India (RBI).

Is It Really Possible to Save Money Fast in 30 Days?: Complete Guide to how to save money fast in 30 days

Additionally, for example, yes—but only if you follow a realistic plan instead of chasing unrealistic money-saving hacks. However, many people believe they need a higher salary before they can start saving, but that’s one of the biggest financial myths. In reality, the first 30 days are not about becoming rich overnight. Therefore, they’re about changing your spending habits, creating a simple budget, and building a system that helps you save consistently.

If you’re wondering how to save money fast in 30 days, the answer isn’t cutting out everything you enjoy. It’s about identifying unnecessary expenses, making smarter financial decisions, and taking small actions that add up over time. In fact, even saving a small amount every week can create momentum and make long-term saving much easier.

Instead of looking for shortcuts, focus on building habits that you can continue long after these 30 days are over. That’s exactly what this guide helps you to help you do.

Why Most People Fail to Save Money: Complete Guide to how to save money fast in 30 days

However, most people don’t fail because they earn too little—they fail because they don’t have a clear financial system. Particularly, without tracking expenses or planning ahead, it’s easy for money to disappear on small daily purchases, subscriptions, impulse shopping, or lifestyle upgrades that seem harmless at first.

Another common mistake is waiting for the “perfect time” to start saving. In fact, unfortunately, that perfect time rarely comes. The sooner you begin, the sooner you’ll gain control over your finances.

What You Can Realistically Achieve in 30 Days: Complete Guide to how to save money fast in 30 days

Consequently, this guide doesn’t promise overnight wealth or unrealistic results. Instead, it focuses on practical improvements that almost anyone can achieve with consistency.

By following these 15 proven strategies, you can:

  • Additionally, build a simple and realistic monthly budget.
  • First, first, first, first, reduce unnecessary spending without feeling deprived.
  • Next, next, next, next, for example, save your first meaningful amount of money.
  • Then, develop healthier money habits that last beyond 30 days.
  • Consequently, take the first step toward long-term financial freedom.

In fact, remember, the goal isn’t just to save money fast in 30 days—it’s to build a financial system that continues working for you month after month

1. Overall, track Every Expense Before You Cut Costs: Complete Guide to how to save money fast in 30 days

If you’re searching for how to save money fast in 30 days, you’re probably hoping to find one simple trick that will instantly increase your savings.

FREE INTERACTIVE TOOL

Set a 30-Day Sprint Target

In addition, calculate how much you need to save daily to reach your 30-day savings milestone without unnecessary friction.

Moreover, maybe you’ve already tried cutting back on coffee, deleting shopping apps, canceling streaming subscriptions, or promising yourself that this month you’ll finally stick to a budget.

But despite all your efforts, your savings account still doesn’t grow.

If that sounds familiar, don’t worry—you’re not alone.

However, millions of people struggle to save money every month, not because they earn too little, but because they don’t fully understand where their money actually goes.

Therefore, notably, that’s why the first strategy in this guide isn’t about investing.

In fact, it isn’t about earning more money.

Additionally, it isn’t even about creating a budget.

Particularly, the first step is much simpler—but far more powerful.

Track every expense before you cut costs.

Actionable Advice and Practical Tips for save money fast in 30 days

Because you can’t improve what you don’t measure.

If you don’t know where your money is going today, you’ll never know where you should start saving tomorrow.

Moreover, for example, many people think they know their spending habits.

Overall, the reality is very different.

Consequently, small daily purchases—like a cup of coffee before work, ordering food after a busy day, buying something during an online sale, paying for subscriptions you rarely use, or grabbing snacks while traveling—don’t feel expensive in the moment.

However, when these purchases happen repeatedly, they quietly consume hundreds of dollars every month.

By the time payday arrives again, many people ask themselves the same question:

“I earned my salary… so where did all my money disappear?”

If you’ve ever asked yourself that question, this strategy will completely change the way you manage money.

Why Can’t I Save Money? Notably, hidden Reasons You’re Still Broke Even with a Good Salary


Why Tracking Every Expense Is the Foundation of Saving Money: Complete Guide to how to save money fast in 30 days

Furthermore, notably, imagine trying to fill a bucket with water.

However, you keep pouring more and more water into it.

But no matter how much water you add, the bucket never becomes full.

Specifically, as a result, after looking closely, you notice several tiny holes at the bottom.

In fact, the problem wasn’t that you weren’t pouring enough water.

Additionally, the problem was that the water was leaking before it had a chance to collect.

Moreover, your money works exactly the same way.

Furthermore, many people believe they need a higher salary before they can start saving money.

While earning more certainly helps, income isn’t always the biggest problem.

Specifically, notably, the real problem is often unnoticed spending.

Actionable Insights and Smart Advice for save money fast in 30 days

Additionally, for example, for example, without tracking your expenses, you’re making financial decisions based on assumptions instead of facts.

Additionally, expense tracking gives you something that every financially successful person has:

Financial awareness.

Consequently, once you’re aware of where your money goes, you’ll start noticing patterns that were completely invisible before.

In addition, for example, you may discover you’re paying for subscriptions you forgot about.

However, you may realize that ordering food three or four times a week costs far more than cooking at home.

Consequently, or perhaps you’ll notice that small impulse purchases are slowly destroying your monthly savings.

Therefore, this awareness becomes the foundation for every financial decision you’ll make in the future.

However, the Consumer Financial Protection Bureau’s budgeting resources also emphasize understanding your spending before building a realistic budget.


A Real-Life Story: How One Simple Habit Changed Everything: Complete Guide to how to save money fast in 30 days

In fact, meet Alex.

In fact, alex is 27 years old and works a full-time office job.

Particularly, he earns approximately $2,800 every month.

Moreover, he’s not irresponsible with money.

Moreover, he pays his rent on time.

Overall, notably, he doesn’t buy expensive luxury items.

Consequently, notably, he rarely travels.

Additionally, yet somehow…

In addition, as a result, every month ends exactly the same way.

Additionally, for example, very little money remains in his bank account.

Furthermore, alex becomes frustrated.

Consequently, he blames inflation.

Specifically, he blames his salary.

However, he even starts searching for a second job.

However, for example, one weekend, instead of looking for ways to earn more money, Alex decides to perform a simple experiment.

In fact, for the next seven days, he’ll record every single expense—no matter how small.

Consequently, every coffee.

Moreover, every snack.

Actionable Advice and Practical Tips for save money fast in 30 days

In addition, every ride-share.

However, notably, every online purchase.

Therefore, every subscription payment.

Additionally, nothing is ignored.

At the end of the week, the results shock him.

ExpenseWeekly Spending
Coffee$28
Food Delivery$46
Snacks$22
Online Shopping$41
Ride Sharing$23

Total Weekly Spending: $160

In fact, that’s nearly $640 every month.

Particularly, for example, the surprising part wasn’t the amount.

Moreover, it was the fact that Alex couldn’t even remember making most of those purchases.

Consequently, after identifying these hidden money leaks, he reduced only a few unnecessary expenses.

Overall, three months later, he had already saved more than $900—without getting a raise, working overtime, or sacrificing everything he enjoyed.

However, his income didn’t change.

Therefore, notably, his awareness did.

In fact, that’s the real power of tracking every expense.

If you’re new to budgeting, learning the fundamentals from Investopedia’s budgeting guide can also help you understand why awareness always comes before budgeting.

Key Lesson: Before you cut expenses, you need to identify them. Moreover, every dollar you track today gives you more control over your money tomorrow.


What Expenses Should You Track?: Complete Guide to how to save money fast in 30 days

In fact, as a result, one of the biggest mistakes people make is believing that only large purchases matter.

Moreover, that’s simply not true.

A $500 purchase is easy to notice.

But ten $5 purchases often go completely unnoticed.

Additionally, ironically, those small daily expenses usually have a much bigger impact on your monthly savings than one occasional large expense.

If your goal is to save money fast in 30 days, you need to develop the habit of tracking every single expense—not just the expensive ones.

Furthermore, notably, think of yourself as a financial detective.

Specifically, your job isn’t to judge your spending.

Additionally, your job is to discover where your money is quietly disappearing.


Categorize Every Expense: Complete Guide to how to save money fast in 30 days

To make your spending easier to understand, divide every expense into simple categories.

1. Additionally, essential Expenses (Needs)

Particularly, for example, these are the costs required for your daily life.

  • Additionally, rent or Home Loan
  • However, electricity Bill
  • Furthermore, water Bill
  • Finally, in fact, internet
  • Specifically, mobile Recharge
  • Moreover, groceries
  • Then, first, transportation
  • Additionally, next, notably, fuel
  • Then, healthcare
  • Additionally, insurance
  • Additionally, education

Consequently, for example, these expenses usually can’t be avoided.

Instead of eliminating them, focus on reducing unnecessary costs within these categories whenever possible.


2. Furthermore, lifestyle Expenses (Wants)

In addition, these aren’t always necessary, but they improve your lifestyle.

Consequently, examples include:

  • Furthermore, for example, coffee
  • Finally, restaurants
  • Consequently, food Delivery
  • Specifically, entertainment
  • However, shopping
  • Furthermore, first, streaming Services
  • Finally, next, in fact, gaming
  • Then, weekend Trips

However, there’s nothing wrong with spending money on things you enjoy.

However, the problem starts when these purchases become automatic habits instead of intentional choices.


3. Overall, hidden Money Leaks

Therefore, this is where most people lose money without realizing it.

In fact, hidden expenses often include:

  • ATM Charges
  • Moreover, bank Fees
  • Additionally, delivery Charges
  • Furthermore, notably, late Payment Fees
  • Finally, forgotten Subscriptions
  • Additionally, premium Mobile Apps
  • Specifically, in-App Purchases
  • Specifically, first, convenience Fees

In fact, these expenses rarely look expensive individually.

However, together they can quietly cost hundreds of dollars every year.

If you’ve ever wondered why your savings aren’t growing despite earning a decent salary, hidden money leaks are often the answer.

Learn how hidden money leaks silently destroy your savings.


Step-by-Step: How to Track Every Expense: Complete Guide to how to save money fast in 30 days

Moreover, the good news is that tracking expenses doesn’t require complicated software.

Particularly, you don’t need to be a financial expert.

Moreover, notably, you simply need consistency.

Step 1 — Record Every Purchase Immediately

Overall, the biggest mistake is trusting your memory.

Instead, record every purchase the moment you spend money.

Whether it’s a cup of coffee, a grocery bill, or an online order, write it down immediately.

Additionally, the more accurate your records are, the easier it becomes to identify unnecessary spending.


Step 2 — Choose a Tracking Method You’ll Actually Use

Moreover, notably, the best expense tracker isn’t the most advanced one.

Overall, as a result, for example, it’s the one you’ll continue using every day.

Additionally, you can choose:

  • Then, first, next, for example, google Sheets
  • Then, microsoft Excel
  • A budgeting app
  • A notebook
  • Consequently, your phone’s Notes app

Consequently, don’t waste time searching for the “perfect” tool.

Furthermore, consistency is far more important than features.


Step 3 — Review Your Spending Every Evening

However, spend just five minutes reviewing everything you purchased during the day.

Specifically, ask yourself three simple questions:

  • Additionally, did I really need this?
  • However, could Always have spent less?
  • Furthermore, would I buy this again tomorrow?

In fact, these questions gradually train your brain to become more mindful before spending money.

Furthermore, notably, for example, over time, you’ll naturally start making smarter financial decisions without feeling restricted.


A Small Habit That Creates Big Results: Complete Guide to how to save money fast in 30 days

Moreover, imagine reducing just $10 of unnecessary spending every day.

Consequently, that doesn’t sound life-changing.

But over one month, you’ve already saved around $300.

In addition, notably, over one year, that’s approximately $3,650—without earning an extra dollar.

However, that’s the power of small financial habits.

According to the Consumer Financial Protection Bureau, understanding where your money goes is one of the most important first steps toward building better financial habits.

Additionally, many successful investors don’t become wealthy because they never spend money.

Therefore, they become wealthy because they understand where every dollar goes before deciding where it should go next.

Key Takeaway: Before you try to earn more money, learn to manage the money you already have. For example, financial awareness is the first habit that separates successful savers from everyone else.

4. Consequently, automate Your Savings Before You Spend: Complete Guide to how to save money fast in 30 days

In fact, for example, many people believe they’ll save whatever money is left at the end of the month.
save money fast in 30 days: : : : Kotak 811 Zero Balance Savings Account - Instant Video KYC
★ Zero-Balance Digital Banking 100% Online 18+ Eligible

Kotak 811 Digital Savings Account

Particularly, supercharge your 30-day savings challenge by automating your transfers into an insulated, zero-maintenance digital account.

₹0 Min Balance 3-Min Video KYC Free Virtual Debit Card

Affiliate Disclosure: This article contains an affiliate link. If you open an account through this link, we may earn a commission at no additional cost to you.

Consequently, unfortunately, that day rarely comes.

Moreover, unexpected expenses appear.

However, online shopping becomes tempting.

Overall, friends invite you out.

A sale pops up on your phone.

By the end of the month, there’s little or nothing left to save.

In fact, that’s why one of the smartest ways to save money fast in 30 days is to reverse the process.

Instead of saving what’s left after spending…

Save first, then spend what’s left.

Specifically, as a result, notably, this simple strategy is called Pay Yourself First, and it’s one of the most effective habits used by financially successful people.


Why Saving First Works: Complete Guide to how to save money fast in 30 days

Moreover, your brain naturally adapts to the money that’s available.

Additionally, as a result, for example, if your salary is $2,000 and you immediately transfer $200 into your savings account, your mind quickly adjusts to living on the remaining $1,800.

Additionally, notably, after a few weeks, it starts feeling normal.

However, if you wait until the end of the month to save, chances are you’ll find reasons to spend that extra $200.

Furthermore, the problem isn’t your income.

Additionally, the problem is that spending always expands to match the money available.

Specifically, automating your savings removes emotion and temptation from the process.

According to the Consumer Financial Protection Bureau, automatic savings can help people build consistent financial habits by reducing the need for daily decisions.


How to Automate Your Savings: Complete Guide to how to save money fast in 30 days

Step 1 – Decide Your Savings Percentage

Furthermore, for example, for example, start with an amount that’s realistic.

Consequently, for example:

  • 10% of your monthly salary
  • 15% if your budget allows
  • Finally, in fact, even 5% is better than saving nothing

Consequently, the goal is consistency—not perfection.

Step 2 – Create a Separate Savings Account

In addition, avoid keeping your savings in the same account you use for daily spending.

A separate account creates a mental barrier, making impulse spending less likely.

Step 3 – Schedule Automatic Transfers

However, set up an automatic transfer for the same day your salary arrives.

However, this way, your savings happen before you have a chance to spend the money.

In fact, once it’s automated, you don’t have to rely on motivation or memory every month.


Real-Life Example: Complete Guide to how to save money fast in 30 days

Therefore, sarah earns $3,000 every month.

Moreover, for years, she tried to save money manually but never stayed consistent.

In fact, she decided to automate 15% of her salary.

Particularly, notably, every payday, $450 was transferred directly into her savings account.

At first, she worried she wouldn’t have enough money.

Moreover, after two months, she barely noticed the difference.

Additionally, within one year, Sarah had saved more than $5,000 without changing her lifestyle dramatically.

Overall, the system—not willpower—made the difference.


💡 Pro Tip: Complete Guide to how to save money fast in 30 days

Specifically, notably, for example, increase your automatic savings by just 1% every six months.

Because the increase is small, you’ll barely notice it, but over time it can significantly grow your savings.


⚠️ Common Mistake: Complete Guide to how to save money fast in 30 days

Additionally, for example, for example, as a result, don’t automate so much that you struggle to pay essential bills.

If your savings target feels stressful, lower the percentage and focus on consistency.

Consequently, saving a smaller amount every month is far better than saving a large amount for only one month.


📌 Expert Insight: Complete Guide to how to save money fast in 30 days

Additionally, behavioral finance research shows that removing the need to make repeated financial decisions reduces the chances of impulsive spending.

However, automation turns saving into a habit instead of a monthly challenge.

If you’re still struggling to control spending, read Why Can’t I Save Money? Consequently, hidden Reasons You’re Still Broke Even with a Good Salary to identify the habits that silently drain your income.


Quick Action Plan: Complete Guide to how to save money fast in 30 days

  • Specifically, decide your monthly savings percentage.
  • Moreover, open a dedicated savings account if you don’t already have one.
  • Additionally, next, first, schedule an automatic transfer on your payday.
  • Then, next, notably, review your progress after 30 days.
  • Then, increase your savings rate gradually as your income grows.

Key Takeaway: Complete Guide to how to save money fast in 30 days

Furthermore, you don’t build wealth by saving what’s left after spending.

In fact, you build wealth by saving first and spending the rest.

When your savings become automatic, financial discipline becomes much easier because your system does the work for you—not your willpower.

Next Strategy: Learn how to eliminate unnecessary subscriptions and recurring expenses that quietly drain your monthly budget.

5. However, stop Impulse Buying with the 24-Hour Rule: Complete Guide to how to save money fast in 30 days

Specifically, have you ever opened an online shopping app just to “look around” and ended up buying something you never planned to purchase?

Moreover, you’re not alone.

Consequently, for example, impulse buying is one of the biggest reasons people fail to save money fast in 30 days.

Consequently, notably, the problem isn’t always expensive purchases.

In addition, it’s the small, emotional purchases that happen without planning.

A flash sale.

A “Limited Time Offer.”

A “Buy One Get One Free” deal.

A social media advertisement.

Additionally, or a friend recommending a product.

However, these situations trigger emotions instead of logic, causing us to spend money on things we don’t actually need.

Therefore, for example, that’s why one of the simplest—and most effective—money-saving habits is following the 24-Hour Rule.

Instead of buying immediately…

In fact, wait 24 hours.

Consequently, this small pause gives your brain enough time to separate want from need.


Why the 24-Hour Rule Works: Complete Guide to how to save money fast in 30 days

Particularly, most impulse purchases are emotional, not logical.

When you see a product, your brain imagines how happy owning it will make you feel.

However, this feeling is temporary.

Moreover, after waiting one day, the excitement usually fades.

In fact, once your emotions settle down, you begin asking better questions.

  • Additionally, do I really need this?
  • Additionally, will I still use it next month?
  • Furthermore, for example, is there a cheaper alternative?
  • Finally, can I borrow it instead?
  • Consequently, what happens if I don’t buy it today?

In many cases, you’ll realize you never needed the product in the first place.

According to Consumer Financial Protection Bureau (CFPB), creating intentional spending habits is one of the most effective ways to improve long-term financial health.


How to Use the 24-Hour Rule: Complete Guide to how to save money fast in 30 days

Step 1 – Never Buy Immediately

Whenever you find something you want to purchase, don’t click “Buy Now.”

Instead, save the product to your wishlist or shopping cart.

Overall, walking away for just one day helps remove emotional pressure.


Step 2 – Ask Yourself Five Questions

Before purchasing, answer these honestly.

  • Specifically, do I really need this?
  • However, can I afford it without touching my savings?
  • Additionally, first, will I still use it six months from now?
  • Furthermore, next, in fact, is this solving a real problem?
  • Then, would I rather invest or save this money?

If most answers are No, don’t buy it.


Step 3 – Compare Prices

Moreover, many people purchase the first product they see.

Instead, compare prices on different websites.

In addition, notably, you may find the same item at a significantly lower price or discover that you don’t need it at all.

Learning smart shopping habits can save hundreds of dollars every year.


Real-Life Example: Complete Guide to how to save money fast in 30 days

However, as a result, notably, david wanted to buy a new smartwatch after seeing an advertisement online.

Additionally, the discount looked amazing.

Additionally, normally, he would have purchased it immediately.

Instead, he followed the 24-Hour Rule.

Furthermore, the next day, he realized his current watch was working perfectly.

Specifically, for example, the excitement had disappeared.

Rather than spending $280 on something unnecessary, he transferred that money into his emergency fund.

A few months later, that same money helped him pay an unexpected medical bill.

Therefore, for example, one small decision protected his finances.


💡 Pro Tip: Complete Guide to how to save money fast in 30 days

Whenever you feel tempted to buy something, add it to a 30-Day Wishlist instead of your shopping cart.

If you still genuinely want the item after several weeks—and it fits your budget—you can buy it without guilt.

Consequently, most items never make it off the wishlist.


⚠️ Common Mistake: Complete Guide to how to save money fast in 30 days

Consequently, don’t confuse needs with wants.

However, replacing broken shoes for work is a need.

In addition, buying another pair simply because they’re on sale is a want.

In fact, sales don’t save money.

However, buying only what you truly need does.


📌 Expert Insight: Complete Guide to how to save money fast in 30 days

Moreover, behavioral economists have found that delaying purchasing decisions reduces emotional spending and improves financial discipline.

Therefore, giving yourself time creates space for logical thinking instead of emotional reactions.

If you’re still wondering where your salary disappears every month, read Why Can’t I Save Money? Therefore, hidden Reasons You’re Still Broke Even with a Good Salary to identify the hidden habits that quietly drain your income.


Quick Action Plan: Complete Guide to how to save money fast in 30 days

  • Moreover, enable a 24-hour waiting period before every non-essential purchase.
  • Additionally, create a wishlist instead of buying immediately.
  • Furthermore, notably, compare prices before making any purchase.
  • Finally, ask yourself the five questions above.
  • Additionally, move the money you didn’t spend into your savings account.

Key Takeaway: Complete Guide to how to save money fast in 30 days

In fact, notably, impulse buying steals money one emotional decision at a time.

Particularly, the 24-Hour Rule helps you slow down, think clearly, and spend intentionally.

Additionally, the goal isn’t to stop enjoying life.

Moreover, the goal is to make sure every purchase supports your financial goals instead of delaying them.

Next Strategy: Learn how to reduce your monthly bills and recurring expenses without lowering your quality of life.

6. As a result, reduce Your Monthly Bills Without Sacrificing Your Lifestyle: Complete Guide to how to save money fast in 30 days

When people decide to save money, they often believe they have to stop enjoying life.

Overall, for example, no more restaurants.

In fact, notably, no more entertainment.

Consequently, no more shopping.

While extreme budgeting might work for a few weeks, it’s rarely sustainable.

Particularly, as a result, the good news is that you don’t always have to cut the things you love.

However, sometimes, you simply need to pay less for the things you’re already using.

Additionally, reducing your monthly bills is one of the easiest ways to save money fast in 30 days because these savings repeat every single month.

In fact, imagine saving just $100 every month.

Furthermore, that’s $1,200 a year without working extra hours or changing jobs.

Moreover, small monthly savings create long-term financial freedom.


Why Lowering Monthly Bills Matters: Complete Guide to how to save money fast in 30 days

Specifically, most recurring bills increase slowly over time.

Moreover, for example, notably, internet plans become more expensive.

Consequently, streaming services raise their prices.

Additionally, insurance premiums go up.

In addition, mobile plans include features you never use.

Because these increases happen gradually, many people never notice them.

Instead of asking,

“How can I earn more money?”

However, for example, start by asking,

“Am I paying more than I need to?”

According to the Consumer Financial Protection Bureau (CFPB), regularly reviewing recurring expenses is one of the simplest ways to improve your monthly cash flow.


How to Reduce Your Monthly Bills: Complete Guide to how to save money fast in 30 days

Step 1 – Review Every Recurring Payment

Therefore, open your bank statement or credit card history.

Consequently, write down every recurring payment, including:

  • Specifically, internet
  • Finally, first, for example, mobile Recharge
  • Specifically, next, streaming Services
  • Consequently, gym Membership
  • Then, insurance
  • However, cloud Storage
  • Additionally, software Subscriptions
  • Furthermore, in fact, music Apps

In fact, many people are surprised to discover subscriptions they completely forgot about.


Step 2 – Cancel What You Don’t Use

However, ask yourself one simple question:

“Have I used this service in the last 30 days?”

If the answer is no, cancel it.

Particularly, you’re not losing money by canceling.

In fact, you’re stopping unnecessary money from leaving your account every month.


Step 3 – Negotiate Better Prices

Moreover, many companies offer discounts to existing customers—but only if you ask.

Moreover, call your internet provider.

Overall, contact your insurance company.

Overall, notably, notably, compare mobile plans.

Consequently, notably, as a result, even a small monthly discount adds up over time.

A five-minute phone call could save hundreds of dollars each year.


Real-Life Example: Complete Guide to how to save money fast in 30 days

Additionally, maria was trying to save money but felt she couldn’t cut any more expenses.

Instead of giving up, she reviewed her monthly bills.

Additionally, she discovered she was paying for:

  • Finally, two streaming services she rarely watched.
  • A premium mobile plan she didn’t need.
  • A gym membership she hadn’t used for four months.

Furthermore, for example, after canceling unnecessary subscriptions and switching to a cheaper internet plan, she reduced her monthly bills by $145.

Specifically, that’s nearly $1,740 every year—without reducing her quality of life.

Consequently, the money she saved was redirected into her emergency fund and long-term investments.


💡 Pro Tip: Complete Guide to how to save money fast in 30 days

In addition, as a result, for example, schedule a “Monthly Bill Review Day” on your calendar.

However, spend just 15 minutes reviewing every recurring payment.

Consequently, this simple habit helps you catch unnecessary expenses before they become expensive long-term habits.


⚠️ Common Mistake: Complete Guide to how to save money fast in 30 days

In fact, don’t cancel services you genuinely use every day just to save a few dollars.

In addition, focus on removing waste—not value.

Moreover, saving money should improve your financial life, not make your daily life miserable.


📌 Expert Insight: Complete Guide to how to save money fast in 30 days

However, financial experts often recommend optimizing recurring expenses before trying extreme budgeting.

Therefore, notably, reducing fixed monthly costs creates permanent savings that continue month after month.

If you’re still wondering why your savings aren’t growing, read Why Can’t I Save Money? Particularly, hidden Reasons You’re Still Broke Even with a Good Salary to uncover hidden spending habits that quietly drain your finances.

In fact, for additional budgeting advice, you can also explore NerdWallet’s budgeting guide.


Quick Action Plan: Complete Guide to how to save money fast in 30 days

  • Moreover, list every recurring monthly bill.
  • Specifically, cancel subscriptions you don’t use.
  • Furthermore, first, first, notably, compare prices with competitors.
  • Finally, next, next, negotiate lower rates with service providers.
  • Additionally, transfer the money you save directly into your savings account.

Key Takeaway: Complete Guide to how to save money fast in 30 days

Additionally, you don’t always need to earn more to improve your finances.

Particularly, sometimes, the fastest way to save money is simply paying less for the services you already use.

Moreover, for example, small monthly reductions may seem insignificant today, but over the course of a year, they can become one of the biggest contributors to your savings.

Next Strategy: Learn how meal planning and smart grocery shopping can dramatically reduce your food expenses without sacrificing healthy eating.

7. Moreover, plan Your Meals and Grocery Shopping Before You Spend: Complete Guide to how to save money fast in 30 days

If you’re trying to save money fast in 30 days, there’s one area that can dramatically affect your monthly budget without you even noticing—food spending.

Overall, most people think groceries are expensive.

Consequently, the truth is that poor planning is expensive.

Additionally, notably, buying food without a plan.

However, ordering takeout because you’re too tired to cook.

Furthermore, as a result, throwing away expired vegetables.

In fact, buying snacks you didn’t intend to purchase.

Additionally, these small habits slowly drain your wallet month after month.

Moreover, the good news?

Furthermore, you don’t need to stop eating your favorite meals.

Specifically, notably, you simply need a smarter plan.

Specifically, for example, meal planning helps you spend less, waste less, and save more—all without sacrificing your lifestyle.


Why Meal Planning Is One of the Smartest Money-Saving Habits: Complete Guide to how to save money fast in 30 days

Additionally, imagine walking into a supermarket without a shopping list.

Consequently, everything looks useful.

In addition, for example, everything feels like a good deal.

However, you pick up chips because they’re on sale.

Consequently, you buy extra drinks “just in case.”

Therefore, you grab chocolates near the checkout counter.

By the time you reach home, you’ve spent far more than you planned.

A few days later, half the vegetables spoil, leftovers go untouched, and some groceries expire before you even use them.

However, that’s not just food waste.

In fact, that’s money waste.

According to the MyPlate nutrition guide, planning meals before shopping helps families make healthier food choices while reducing unnecessary purchases and food waste.


How to Spend Less on Food Without Feeling Restricted: Complete Guide to how to save money fast in 30 days

Step 1 – Plan Your Meals for the Next 7 Days

Before buying anything, decide exactly what you’ll eat throughout the week.

In fact, plan breakfast.

Particularly, plan lunch.

Moreover, plan dinner.

Moreover, plan snacks.

When every meal has a purpose, every grocery purchase also has a purpose.

Overall, notably, this simple habit reduces impulse buying and makes food delivery much less tempting.


Step 2 – Check Your Kitchen Before Shopping

However, for example, notably, open your refrigerator.

Additionally, look inside your freezer.

Consequently, as a result, check your pantry.

Additionally, for example, you might already have rice, pasta, spices, vegetables, or canned food waiting to be used.

Furthermore, buying duplicates wastes money and increases food waste.

Consequently, use what you already own before purchasing more.


Step 3 – Make a Shopping List and Follow It

Specifically, never rely on memory.

However, write down only the ingredients you actually need.

When you enter the supermarket with a clear shopping list, you’re far less likely to buy unnecessary products.

In addition, for example, think of your shopping list as your financial roadmap.

In fact, every item should have a reason to be there.


Real-Life Example: Complete Guide to how to save money fast in 30 days

Consequently, sophia loved ordering food after work because cooking felt exhausting.

Moreover, between groceries, takeout, and coffee stops, she was spending nearly $650 every month on food.

In addition, one Sunday, she decided to plan all her meals for the upcoming week.

However, notably, she created a shopping list, cooked a few meals in advance, and carried lunch to work three times that week.

By the end of the month, her food expenses dropped to $430.

Therefore, she didn’t stop eating well.

Additionally, she simply stopped making last-minute decisions.

In fact, the money she saved went directly into her emergency fund.

Particularly, for example, small changes produced big results.


💡 Pro Tip: Complete Guide to how to save money fast in 30 days

Moreover, follow the “Shop Your Kitchen First” rule.

Before buying anything new, challenge yourself to prepare at least two meals using ingredients you already have at home.

Consequently, you’ll reduce food waste and save money at the same time.


⚠️ Common Mistake

Overall, don’t buy large quantities just because they’re on sale.

If you don’t use the food before it expires, the discount becomes a loss.

A product isn’t a bargain unless you actually use it.


📌 Expert Insight

However, research from the USDA Food and Nutrition Service shows that meal planning and reducing food waste are practical ways to improve household budgeting while supporting healthier eating habits.

If you’ve already started tracking your daily expenses, you’ll find it much easier to identify how much of your monthly budget goes toward groceries and food delivery.

However, notably, you can also read Why Can’t I Save Money? Additionally, hidden Reasons You’re Still Broke Even with a Good Salary to discover the hidden spending habits that silently reduce your savings.


Quick Action Plan

  • Then, plan your meals for the next seven days.
  • Additionally, for example, check your kitchen before shopping.
  • Furthermore, create a grocery list and stick to it.
  • Consequently, avoid shopping when you’re hungry.
  • Finally, compare this week’s grocery spending with last week’s.
  • However, transfer the money you saved into your savings account.

Key Takeaway

In fact, saving money on food isn’t about eating less.

Therefore, as a result, it’s about planning better, shopping smarter, and wasting less.

When every grocery purchase has a purpose, your food budget becomes easier to manage, your kitchen becomes more organized, and your savings grow without making you feel deprived.

Next Strategy: Learn how to use cashback offers, reward programs, and credit card benefits wisely to save money without falling into the trap of unnecessary spending.

8. Try a 30-Day No-Spend Challenge to Reset Your Spending Habits

If you’ve been wondering how to save money fast in 30 days, there’s one powerful strategy that doesn’t require a higher salary, a second job, or extreme budgeting.

Instead, it requires one simple decision:

Stop buying things you don’t truly need—for just 30 days.

Moreover, this is called a 30-Day No-Spend Challenge, and it’s one of the fastest ways to break bad spending habits while giving your finances a fresh start.

Additionally, the goal isn’t to stop spending money completely.

Furthermore, notably, that’s impossible.

Specifically, you’ll still pay rent, buy groceries, pay your electricity bill, and cover transportation costs.

Additionally, the real goal is to eliminate non-essential spending so you can clearly see how much money usually disappears because of habits rather than necessity.

By the end of the challenge, most people don’t just save more money—they completely change the way they think about spending.


Why the No-Spend Challenge Works

In fact, for example, every purchase starts with a decision.

Consequently, for example, unfortunately, many of those decisions happen automatically.

In addition, you’re bored.

Consequently, you open Amazon.

However, you’re stressed.

However, you order food.

Therefore, you see a flash sale.

In fact, you convince yourself you’re saving money by spending money.

In fact, this cycle repeats over and over until payday arrives and your savings account is still empty.

Moreover, the 30-Day No-Spend Challenge interrupts this pattern.

Instead of asking,

“Can I afford this?”

you begin asking,

“Do I actually need this?”

Particularly, that single question changes everything.

According to the Consumer Financial Protection Bureau (CFPB), becoming more intentional about spending is one of the most effective ways to build healthier financial habits.


What You Can Spend Money On

During the challenge, spending is allowed only on essential needs.

Particularly, rent or Mortgage

Moreover, groceries

Overall, electricity and Water Bills

Therefore, notably, transportation

In fact, as a result, healthcare

Additionally, education

Furthermore, emergency Expenses

Moreover, notably, everything else should wait.

Overall, that includes:

❌ Online Shopping

❌ Fashion Purchases

❌ Entertainment Purchases

❌ Expensive Coffee

❌ Food Delivery

❌ Impulse Buying

❌ Unnecessary Gadgets

Additionally, remember…

Specifically, notably, you’re not saying “Never.”

Particularly, for example, as a result, for example, you’re simply saying “Not today.”

Real-Life Example

Additionally, michael loved online shopping.

Consequently, almost every evening he bought something small.

Furthermore, sometimes it was a phone accessory.

However, sometimes new shoes.

Specifically, sometimes gadgets he never actually used.

In fact, individually, none of these purchases felt expensive.

But after accepting a 30-Day No-Spend Challenge, he noticed something surprising.

Consequently, for example, most of the items he wanted on Day 1 didn’t matter anymore by Day 10.

By the end of the month, he had saved nearly $520 without feeling deprived.

Moreover, more importantly, he realized that many of his purchases were emotional—not necessary.

Consequently, that lesson changed his financial habits permanently.


💡 Pro Tip

Whenever you feel tempted to buy something, write it down on a 30-Day Wish List instead of purchasing it immediately.

If you still genuinely want it after the challenge ends—and it fits your budget—you can buy it without regret.

In addition, notably, most people discover they no longer want nearly half the items on their list.


⚠️ Common Mistake

However, don’t make the challenge so strict that you quit after a few days.

Additionally, the goal isn’t perfection.

Therefore, the goal is awareness.

If you accidentally buy something unnecessary, don’t give up.

In fact, for example, learn from the mistake and continue the challenge.

Particularly, progress always beats perfection.


📌 Expert Insight

Consequently, behavioral finance research shows that delaying gratification helps reduce impulsive spending and strengthens long-term financial discipline.

If you’re already tracking your expenses, this challenge becomes much easier because you’ll immediately notice where your biggest money leaks occur.

Moreover, you can also read Why Can’t I Save Money? In addition, notably, hidden Reasons You’re Still Broke Even with a Good Salary to identify spending habits that silently reduce your savings.

However, for more practical consumer advice, visit the Consumer.gov Money Management resources.


30-Day Action Plan

  • Specifically, define your spending rules before Day 1.
  • Then, first, in fact, list essential expenses.
  • Additionally, next, avoid all unnecessary purchases for 30 days.
  • Moreover, record every dollar you didn’t spend.
  • Then, transfer those savings into your emergency fund or savings account.
  • Additionally, notably, review your progress at the end of each week.

Key Takeaway

A 30-Day No-Spend Challenge isn’t about making life boring.

Overall, it’s about proving to yourself that you control your money—not your impulses.

In fact, after just one month, you’ll spend more intentionally, save more consistently, and develop financial habits that continue long after the challenge ends.

Next Strategy: Learn how to build an emergency fund even if you’re living paycheck to paycheck.

9. As a result, build an Emergency Fund—Even If You Can Only Save a Little

In addition, notably, imagine this.

Moreover, your phone suddenly stops working.

However, as a result, your bike needs repairs.

Additionally, notably, you face an unexpected medical bill.

Furthermore, or your car breaks down on the way to work.

Additionally, none of these situations are part of your monthly budget.

Specifically, yet they happen to almost everyone.

When people don’t have an emergency fund, they often rely on credit cards, personal loans, or borrow money from friends and family.

Instead of solving one financial problem, they create another.

Therefore, for example, for example, that’s why building an emergency fund is one of the smartest strategies if you want to save money fast in 30 days and protect your financial future.

Consequently, an emergency fund isn’t just money sitting in a bank account.

Consequently, it’s peace of mind.

In addition, it’s knowing that one unexpected expense won’t destroy your entire budget.

However, the best part?

However, you don’t need thousands of dollars to get started.

In fact, even saving a small amount consistently can make a huge difference over time.


Why an Emergency Fund Is More Important Than You Think

Therefore, many people believe they should start investing before building emergency savings.

While investing is important, emergencies don’t wait for the stock market to perform well.

Moreover, without emergency savings, people often withdraw investments at the wrong time or take high-interest loans.

In fact, that’s why financial experts recommend building a cash safety cushion first.

According to the Consumer Financial Protection Bureau (CFPB), having emergency savings helps households recover from unexpected financial setbacks without relying on expensive debt.

Particularly, notably, think of your emergency fund as a financial airbag.

Moreover, you hope you’ll never need it.

But when an emergency happens, you’ll be grateful it’s there.


How to Build an Emergency Fund

Step 1 – Set a Small Starting Goal

Additionally, don’t aim for $10,000 immediately.

Overall, that number feels overwhelming.

Instead, focus on your first milestone.

In fact, notably, for example, for example:

  • Furthermore, first $100
  • Then $500
  • Then one month’s living expenses

Particularly, as a result, small victories create motivation.


Step 2 – Save Automatically

Consequently, treat your emergency fund like a monthly bill.

Additionally, transfer money into it as soon as your salary arrives.

However, even $20 or $50 every month builds momentum.

Furthermore, consistency matters far more than the amount.


Step 3 – Keep It Separate

In fact, don’t keep your emergency savings in the same account you use for daily spending.

A separate savings account reduces temptation and protects your money from impulse purchases.

Specifically, the harder it is to spend, the more likely you’ll keep saving.

Real-Life Example

Moreover, ryan worked as a delivery driver.

Moreover, for example, his income wasn’t very high, so he believed saving money was impossible.

Instead of giving up, he started saving just $25 every week.

Consequently, notably, after ten months, he had built an emergency fund of over $1,000.

In addition, one day, his motorcycle needed urgent repairs.

Instead of borrowing money or using a credit card, Ryan paid the repair bill from his emergency fund.

Additionally, he continued working without falling into debt.

However, that small habit protected both his finances and his peace of mind.


💡 Pro Tip

Therefore, for example, keep your emergency fund in a high-yield savings account or another secure savings account that earns interest while keeping your money easily accessible for genuine emergencies.

In fact, avoid investing emergency savings in assets that can lose value in the short term.


⚠️ Common Mistake

Consequently, don’t use your emergency fund for vacations, shopping, or festival sales.

Particularly, an emergency fund is only for unexpected and essential expenses such as medical emergencies, urgent home repairs, or temporary income loss.

If you spend it on non-emergencies, you’ll have nothing when a real emergency happens.


📌 Expert Insight

However, financial planners generally recommend building an emergency fund before aggressively investing or paying for lifestyle upgrades because unexpected expenses are inevitable.

If you’re already following the earlier strategies in this guide—tracking expenses, reducing monthly bills, and avoiding impulse purchases—you’ll find it much easier to save money consistently.

Moreover, you can also read Why Can’t I Save Money? Specifically, hidden Reasons You’re Still Broke Even with a Good Salary to identify hidden spending habits that may be preventing you from building emergency savings.

In fact, for additional guidance on emergency savings, visit the FDIC Money Smart financial education resources.


Quick Action Plan

  • Additionally, set your first emergency savings goal today.
  • Finally, open a separate savings account.
  • Specifically, for example, automate a weekly or monthly transfer.
  • Furthermore, first, use the fund only for genuine emergencies.
  • Consequently, rebuild the fund immediately after using it.

Key Takeaway

Overall, an emergency fund isn’t about expecting the worst.

Moreover, it’s about being prepared for life’s unexpected moments.

Overall, notably, even if you can only save a small amount each week, consistency will eventually create a financial safety net that protects you from debt, reduces stress, and keeps your long-term savings goals on track.

Next Strategy: Learn how increasing your income with simple side hustles can accelerate your savings without relying only on cutting expenses.

10. Furthermore, increase Your Income with a Simple Side Hustle Instead of Only Cutting Expenses

Moreover, notably, as a result, notably, cutting expenses is one of the fastest ways to save money.

But there’s a limit.

Additionally, you can only reduce your spending so much before it starts affecting your lifestyle.

Additionally, your income, however, has much more room to grow.

Furthermore, that’s why one of the smartest ways to save money fast in 30 days is to focus on earning a little extra money alongside your regular income.

Specifically, for example, you don’t need to quit your job.

Overall, as a result, for example, you don’t need a business degree.

Consequently, and you certainly don’t need thousands of dollars to get started.

Consequently, even earning an extra $100–$300 per month can dramatically improve your savings, help you build an emergency fund faster, or pay off debt without feeling financially stressed.

However, the goal isn’t to work every waking hour.

In addition, the goal is to create an additional income stream that supports your financial goals.


Why Increasing Your Income Is Better Than Extreme Budgeting

In fact, imagine two people.

However, the first person cuts every possible expense.

Moreover, no coffee.

Therefore, no entertainment.

In fact, notably, no dining out.

Particularly, no hobbies.

Additionally, they manage to save $150 every month.

Moreover, the second person keeps a balanced lifestyle but earns an extra $300 each month through freelancing, tutoring, selling digital products, or weekend work.

Overall, for example, who reaches their savings goal faster?

Additionally, notably, the second person.

Consequently, that’s because increasing your income creates new financial opportunities instead of constantly restricting your lifestyle.

According to the Consumer Financial Protection Bureau (CFPB), combining smart budgeting with higher income is often more sustainable than relying only on cutting expenses.


How to Start a Side Hustle Without Feeling Overwhelmed

Step 1 – Identify a Skill You Already Have

Furthermore, as a result, you don’t need to learn something completely new.

However, start with skills you already possess.

Additionally, examples include:

  • Finally, next, writing
  • However, graphic Design
  • Then, video Editing
  • Additionally, in fact, teaching
  • Furthermore, photography
  • Moreover, coding
  • Finally, social Media Management
  • Specifically, notably, translation
  • Specifically, first, data Entry

In fact, almost every skill can become a source of income.


Step 2 – Start Small

Furthermore, don’t wait until everything is perfect.

Moreover, offer one service.

Specifically, get your first client.

Specifically, for example, notably, learn from feedback.

Consequently, improve gradually.

Additionally, the biggest mistake beginners make is spending months planning instead of taking action.

In addition, small progress every week creates long-term success.


Step 3 – Save Every Dollar You Earn

However, for example, here’s where most people go wrong.

Therefore, they earn extra money…

Then immediately spend it.

Instead, make a rule:

Every dollar earned from your side hustle goes directly into savings or investments.

Consequently, this separates your extra income from your everyday spending.


Real-Life Example

In fact, james worked a full-time office job and believed saving money was impossible because his salary barely covered his monthly expenses.

Instead of looking for another full-time job, he started freelancing on weekends as a graphic designer.

During his first month, he earned only $180.

Rather than spending that money, he transferred every dollar into his savings account.

However, within eight months, he had saved more than $1,500 from side income alone.

Particularly, his salary stayed exactly the same.

In fact, only his income sources changed.


💡 Pro Tip

Moreover, choose a side hustle that matches your existing skills.

Moreover, you’ll start earning much faster than trying to learn an entirely new profession from scratch.


⚠️ Common Mistake

Overall, don’t chase every new “Get Rich Quick” opportunity you see online.

If something promises huge profits with little effort, treat it with caution.

Furthermore, notably, for example, notably, notably, building extra income usually takes time, consistency, and patience.


📌 Expert Insight

Consequently, as a result, many financially successful people don’t rely on just one source of income.

Additionally, they gradually build multiple income streams, allowing them to save more, invest more, and recover more easily from unexpected financial setbacks.

If you’re already saving money by tracking expenses and reducing unnecessary bills, adding even a small side income can accelerate your progress significantly.

Additionally, you may also like reading Why Can’t I Save Money? Specifically, hidden Reasons You’re Still Broke Even with a Good Salary to understand how spending habits and earning habits work together to build long-term wealth.

Furthermore, for example, for practical career and earning advice, explore the CareerOneStop Career Resources, sponsored by the U.S. For example, department of Labor.


Quick Action Plan

  • Additionally, list three skills you already have.
  • Specifically, first, next, choose one side hustle that matches those skills.
  • Then, for example, set a goal to earn your first extra $100.
  • Additionally, save every dollar you earn from that side hustle.
  • Consequently, review your progress after 30 days and increase your income goal gradually.

Key Takeaway

Specifically, saving money isn’t only about spending less.

Consequently, sometimes, the fastest way to reach your financial goals is to earn a little more while continuing your smart saving habits.

When you combine disciplined spending with an additional source of income, you’ll build savings faster, reduce financial stress, and create more opportunities for your future.

Next Strategy: Learn how setting clear savings goals can keep you motivated and make it easier to stay consistent throughout your 30-day money-saving journey.

11. Set a Clear Savings Goal to Stay Motivated Every Day

In addition, for example, have you ever promised yourself,

“From next month, I’ll start saving money.”

But after a few weeks, that motivation disappeared?

If your answer is yes, you’re not alone.

However, one of the biggest reasons people fail to save money fast in 30 days isn’t because they don’t earn enough money.

Consequently, it’s because they don’t have a clear reason to save.

In fact, saving money without a goal is like driving without a destination.

In addition, you’ll keep moving, but you won’t know whether you’re making progress.

A specific savings goal gives every dollar a purpose.

Instead of thinking,

“I’m saving money because I should.”

Moreover, you start thinking,

“I’m saving money because I want to buy my first home, build an emergency fund, travel, become debt-free, or achieve financial freedom.”

However, that small shift completely changes your mindset.


Why Clear Financial Goals Make Saving Easier

Therefore, notably, our brains naturally stay motivated when we can see progress.

In fact, imagine trying to climb a mountain without knowing where the top is.

Additionally, you’d probably give up halfway.

Particularly, now imagine seeing clear milestones every few hundred meters.

Suddenly, the journey feels achievable.

Moreover, for example, saving money works exactly the same way.

Instead of saying,

“I want to save more money.”

Overall, say,

“I want to save $1,000 in the next six months.”

Consequently, now your goal becomes measurable.

According to the Consumer Financial Protection Bureau (CFPB), setting realistic financial goals helps people stay focused and make better everyday spending decisions.


How to Set a Savings Goal That You’ll Actually Achieve

Step 1 – Choose One Primary Goal

However, notably, don’t try to save for ten different things at once.

However, focus on one goal first.

Therefore, as a result, for example:

  • Furthermore, build an Emergency Fund
  • However, buy a New Laptop
  • Finally, save for Higher Education
  • Specifically, in fact, buy Your First Car
  • Then, first, next, first, start Investing
  • Moreover, pay Off Debt
  • Then, next, build a House Down Payment

In fact, one clear goal creates better focus than several competing goals.


Step 2 – Give Your Goal a Deadline

Additionally, goals without deadlines usually remain wishes.

Instead of saying,

“I’ll save someday.”

Moreover, say,

“I’ll save $2,000 within the next eight months.”

A deadline creates urgency and helps you measure progress.


Step 3 – Break the Goal into Small Milestones

Furthermore, large numbers often feel overwhelming.

Specifically, notably, break them into smaller targets.

In fact, for example, example:

Additionally, goal = $1,200

Consequently, monthly Target = $100

In addition, for example, weekly Target = $25

However, daily Target = Around $3.30

Consequently, small milestones make big goals feel achievable and keep you motivated throughout the journey.


Real-Life Example

Therefore, ava wanted to buy her first laptop for freelance work.

However, the laptop cost $1,200, but her salary barely covered her monthly expenses.

Instead of giving up, she created a clear savings goal.

In fact, she decided to save $100 every month by reducing unnecessary spending, cooking more meals at home, and setting aside part of her side-hustle income.

In fact, she tracked her progress every weekend.

Particularly, each month, watching her savings grow motivated her to continue.

Moreover, within one year, Ava bought her laptop without taking a loan or using a credit card.

Moreover, the goal gave her direction.

Overall, notably, the habit made it possible.


💡 Pro Tip

Particularly, notably, keep your savings goal somewhere you’ll see it every day.

Additionally, write it on a sticky note, make it your phone wallpaper, or use a savings tracker.

A constant visual reminder helps you stay focused when you’re tempted to spend money impulsively.


⚠️ Common Mistake

Moreover, as a result, don’t set unrealistic goals.

Additionally, for example, trying to save half of your salary overnight often leads to frustration.

Furthermore, choose a goal that’s challenging but realistic.

Consequently, it’s better to reach a smaller goal consistently than to abandon a larger one after a few weeks.


📌 Expert Insight

Specifically, behavioral finance research shows that people are far more likely to stick with financial habits when they have a specific, measurable goal instead of a vague intention.

If you’ve already started tracking your expenses and completed the earlier strategies in this guide, setting a clear savings goal becomes much easier because you already know how much money you can realistically save each month.

However, you may also find it helpful to read Why Can’t I Save Money? Consequently, hidden Reasons You’re Still Broke Even with a Good Salary to identify habits that may be slowing your progress.

Overall, for example, for additional guidance on setting financial goals, visit the U.S. In addition, securities and Exchange Commission (Investor.gov).


Quick Action Plan

  • Then, notably, choose one savings goal.
  • Additionally, decide exactly how much money you need.
  • Additionally, set a realistic deadline.
  • Furthermore, break the goal into monthly and weekly targets.
  • Finally, for example, track your progress every week.
  • Specifically, celebrate each milestone without overspending.

Key Takeaway

In fact, people don’t stay motivated because they’re disciplined.

Consequently, they stay motivated because they have a clear purpose.

When every dollar moves you one step closer to a meaningful goal, saving money becomes easier, more rewarding, and far more sustainable.

Next Strategy: Discover how reviewing your progress every week helps you stay consistent and reach your savings goals faster.

12. Review Your Finances Every Week to Stay on Track

Moreover, saving money isn’t something you do once and forget about.

In addition, it’s a habit that needs regular attention.

However, notably, many people start the month feeling motivated.

Therefore, they create a budget.

Additionally, track their expenses.

In fact, promise themselves they’ll spend less.

But after a week or two, life gets busy.

Particularly, for example, small purchases go unnoticed.

Moreover, impulse spending slowly returns.

By the end of the month, they wonder why they failed to reach their savings goal.

Consequently, the problem isn’t a lack of motivation.

Overall, the problem is a lack of regular financial reviews.

However, just as businesses review their finances every week, you should also schedule a weekly money check-in.

Specifically, as a result, notably, notably, it takes only 15–20 minutes, but it can save you hundreds of dollars every month.


Why Weekly Reviews Are So Powerful

In fact, imagine driving from one city to another without ever looking at the road signs or your GPS.

Additionally, as a result, as a result, you might still reach your destination—but you’ll probably take wrong turns, waste fuel, and lose time.

Moreover, managing money works the same way.

If you never review your finances, you won’t notice problems until it’s too late.

A weekly review helps you catch mistakes early.

Additionally, maybe you spent more on dining out than expected.

Furthermore, notably, maybe you forgot to cancel a subscription.

Specifically, maybe you achieved your weekly savings target ahead of schedule.

Additionally, reviewing your finances every week allows you to make small adjustments before those mistakes become expensive habits.

According to the Consumer.gov Money Management Guide, regularly reviewing your income, expenses, and savings is one of the best ways to build long-term financial stability.


How to Do a Weekly Money Review

Step 1 – Check Your Income and Expenses

Additionally, for example, open your banking app, expense tracker, or spreadsheet.

Consequently, for example, compare how much money came in versus how much went out.

In addition, look for anything unusual.

Consequently, did you spend more than expected?

However, did you receive extra income?

However, the goal isn’t to judge yourself.

Therefore, it’s to understand your financial habits.


Step 2 – Compare Your Spending with Your Budget

In fact, now compare your actual spending with the budget you planned.

In fact, ask yourself:

  • Consequently, did I stay within my grocery budget?
  • Additionally, first, did Ensure you avoid unnecessary online shopping?
  • However, did I save what I planned this week?
  • Furthermore, next, which category needs improvement next week?

Moreover, this simple comparison helps you stay accountable.


Step 3 – Celebrate Small Wins and Fix Small Mistakes

Particularly, don’t focus only on what went wrong.

Moreover, notably, celebrate every small success.

Overall, maybe you avoided impulse buying.

Additionally, maybe you cooked meals at home all week.

Furthermore, notably, maybe you reached your weekly savings target.

Specifically, as a result, for example, recognizing progress keeps you motivated to continue.

If you made mistakes, don’t feel guilty.

Instead, create a simple plan to avoid repeating them next week.


Real-Life Example

Additionally, chris wanted to save $3,000 within a year.

Instead of checking his finances only at the end of each month, he reviewed them every Sunday evening.

During one review, he noticed he had spent much more than expected on food delivery.

Consequently, the following week, he planned his meals in advance and cut those expenses nearly in half.

Furthermore, that one adjustment helped him stay on track without making drastic lifestyle changes.

By the end of the year, Chris successfully reached his savings goal because he corrected small problems before they became big ones.


💡 Pro Tip

However, choose the same day and time every week for your money review.

Specifically, for example, every Sunday at 7:00 PM.

When it becomes part of your weekly routine, you’ll be much more likely to stay consistent.


⚠️ Common Mistake

In fact, don’t wait until the end of the month to review your finances.

By then, the money is already spent.

Furthermore, for example, for example, weekly reviews give you enough time to correct mistakes while they’re still small and manageable.


📌 Expert Insight

Moreover, successful investors, business owners, and financially disciplined individuals don’t leave their money to chance.

Consequently, they regularly measure their financial progress and make small improvements over time.

If you’ve already completed the earlier strategies in this guide, a weekly financial review ties everything together by helping you stay accountable and consistent.

In addition, notably, you may also find it helpful to revisit Why Can’t I Save Money? Therefore, hidden Reasons You’re Still Broke Even with a Good Salary to identify recurring habits that could still be slowing your financial progress.

However, for additional financial planning resources, visit the U.S. In fact, securities and Exchange Commission’s Investor.gov website.


Quick Action Plan

  • Then, in fact, schedule a 20-minute money review every week.
  • Additionally, compare your income, expenses, and savings.
  • Moreover, identify one spending habit to improve.
  • Furthermore, celebrate one financial win from the week.
  • Finally, notably, adjust your budget if necessary.
  • Specifically, repeat the process every week.

Key Takeaway

Additionally, saving money isn’t about being perfect.

Therefore, it’s about making small improvements consistently.

A weekly financial review helps you stay aware of your spending, correct mistakes before they grow, and remain focused on your long-term financial goals.

Next Strategy: Learn how to avoid common money mistakes that silently destroy your savings and keep you from achieving financial freedom.

13. In addition, avoid Lifestyle Inflation as Your Income Grows

In fact, for example, getting a salary raise should improve your financial future.

Particularly, unfortunately, for many people, it only increases their monthly expenses.

Consequently, they earn more…

Then immediately upgrade their phone.

Moreover, move into a more expensive apartment.

However, buy a newer car.

Overall, eat out more often.

In fact, purchase premium subscriptions.

Consequently, notably, within a few months, their higher income disappears just as quickly as before.

Moreover, this financial trap is called lifestyle inflation, and it’s one of the biggest reasons people struggle to build wealth—even with a good salary.

If your goal is to save money fast in 30 days and continue growing your savings for years to come, learning how to control lifestyle inflation is essential.

In addition, as a result, remember:

Making more money doesn’t automatically make you wealthier.

Additionally, notably, keeping more of what you earn does.


What Is Lifestyle Inflation?

Furthermore, lifestyle inflation happens when your spending increases every time your income increases.

Instead of saving or investing your extra income, you slowly upgrade your lifestyle.

At first, these upgrades feel harmless.

A better smartphone.

A nicer watch.

Additionally, more expensive restaurants.

Specifically, premium memberships.

However, for example, for example, luxury vacations.

Consequently, none of these purchases seem like a major problem individually.

But together, they quietly consume every salary increase you receive.

Consequently, as a result, you continue living paycheck to paycheck—even though you’re earning more than ever before.

According to the Consumer Financial Protection Bureau (CFPB), increasing savings alongside income is one of the most effective ways to build long-term financial security.


How to Avoid Lifestyle Inflation

Step 1 – Save Before You Upgrade

Whenever your income increases, decide in advance where the extra money will go.

In addition, for example:

  • Additionally, save 50%
  • Finally, first, invest 30%
  • Specifically, next, for example, enjoy 20%

However, this approach allows you to improve your lifestyle without sacrificing your future.


Step 2 – Increase Your Savings Rate

Instead of increasing only your spending, increase your savings too.

If you previously saved 10% of your salary, try saving 15% after your next raise.

However, your future self will thank you.


Step 3 – Ask Yourself One Important Question

Before buying something more expensive, ask yourself:

“Am I buying this because I truly need it, or simply because I earn more now?”

In fact, that simple question prevents countless unnecessary purchases.


Real-Life Example

Therefore, kevin received a salary increase of $500 per month.

Moreover, most of his friends encouraged him to buy a newer car.

Instead, Kevin decided to keep driving his current car for another two years.

In fact, he automatically transferred $350 of his salary increase into his savings and investment accounts.

Particularly, notably, the remaining $150 was used to improve his lifestyle.

Moreover, after two years, Kevin had built thousands of dollars in savings while still enjoying his higher income.

Additionally, his friends, however, had larger car payments and very little savings.

Overall, the difference wasn’t income.

Therefore, notably, for example, it was financial discipline.


💡 Pro Tip

Whenever you receive a salary raise, bonus, or tax refund, wait 30 days before making any major purchase.

In fact, as a result, giving yourself time helps you make logical decisions instead of emotional ones.


⚠️ Common Mistake

Consequently, don’t compare your lifestyle to other people’s social media posts.

Additionally, many expensive-looking lifestyles are financed with debt—not wealth.

However, build your financial future based on your own goals, not someone else’s appearance.


📌 Expert Insight

Furthermore, many millionaires continue living below their means even after their income grows substantially.

In fact, they understand that wealth isn’t measured by what you spend—it’s measured by what you keep and invest.

If you’re already following the earlier strategies in this guide, avoiding lifestyle inflation becomes much easier because you’ll already have better control over your spending habits.

Specifically, you may also benefit from reading Why Can’t I Save Money? Moreover, hidden Reasons You’re Still Broke Even with a Good Salary, where we explain the hidden habits that quietly reduce long-term wealth.

Moreover, for more investor education, visit the Investor.gov website maintained by the U.S. Overall, securities and Exchange Commission.


Quick Action Plan

  • Then, decide how you’ll use your next salary increase before you receive it.
  • Consequently, increase your savings rate whenever your income grows.
  • Additionally, wait 30 days before making expensive purchases.
  • However, avoid comparing your lifestyle with others.
  • Furthermore, review your financial goals every month.

Key Takeaway

A higher income creates an opportunity to build wealth—but only if you resist the temptation to increase your spending at the same pace.

Particularly, for example, the people who achieve financial freedom aren’t always the ones who earn the most.

Consequently, notably, they’re the ones who consistently save, invest, and live below their means.

Next Strategy: Discover how small daily habits can compound into life-changing savings over time.

14. However, build Small Daily Money Habits That Compound Over Time

When people think about saving money, they often look for one big solution.

A higher salary.

A better investment.

A huge discount.

A second job.

While these can certainly help, they usually aren’t what separates people who build wealth from those who constantly struggle with money.

In addition, the real difference is found in small daily habits.

Additionally, tiny financial decisions may seem insignificant today, but when repeated consistently, they create remarkable results over months and years.

However, think about brushing your teeth.

Therefore, for example, doing it once won’t make much difference.

But doing it every day protects your teeth for years.

In fact, saving money works exactly the same way.

A small habit repeated consistently is far more powerful than one big financial decision made once.

If you truly want to save money fast in 30 days, start by improving your daily habits—not by searching for shortcuts.


Why Small Habits Create Big Financial Results

Consequently, most people underestimate the power of consistency.

Particularly, saving $5 today doesn’t feel life-changing.

However, neither does avoiding one unnecessary online purchase.

But imagine repeating that decision every day for an entire year.

Moreover, those small choices gradually become thousands of dollars.

In fact, the reason is simple.

Overall, financial success isn’t built in a single weekend.

Moreover, it’s built through hundreds of smart decisions made over time.

According to the Consumer Financial Protection Bureau (CFPB), creating consistent financial habits is one of the most effective ways to improve long-term financial well-being.


Small Daily Habits That Save Money

1. As a result, check Your Bank Balance Every Morning

Moreover, notably, this simple habit keeps your spending under control.

When you know exactly how much money you have, you’re less likely to make impulsive purchases.

Overall, as a result, notably, financial awareness leads to better financial decisions.


2. Ask One Question Before Every Purchase

Before spending money, pause for five seconds and ask yourself:

“Will this purchase improve my life next month, or am I buying it only because I want it today?”

Additionally, that one question prevents countless unnecessary purchases.


3. Additionally, save Every Small Amount

Additionally, found $10 in your wallet?

Furthermore, received cashback?

Specifically, for example, earned a small bonus?

Instead of spending it immediately, transfer it directly into your savings account.

Specifically, notably, for example, small amounts eventually become meaningful savings.


4. Therefore, spend Five Minutes Learning About Money

Consequently, read one article.

Consequently, watch an educational video.

However, listen to a personal finance podcast.

In addition, improving your financial knowledge helps you make smarter decisions throughout your life.

In fact, knowledge compounds just like money.


Real-Life Example

However, olivia didn’t receive a promotion.

Moreover, she didn’t start a side business.

Therefore, she simply changed five small daily habits.

In fact, notably, she stopped buying coffee every morning.

Particularly, checked her bank account daily.

Additionally, prepared lunch at home.

Moreover, transferred every cashback reward into savings.

Overall, for example, reviewed her expenses every Sunday.

For example, for example, as a result, notably, none of these habits seemed extraordinary.

Consequently, yet after one year, she had saved over $3,000 without feeling like she had sacrificed her lifestyle.

Additionally, as a result, her success wasn’t created by one big decision.

However, it was built through hundreds of small ones.


💡 Pro Tip

Additionally, don’t try to build ten new financial habits at once.

In fact, choose one habit every week.

Furthermore, once it becomes automatic, add another.

Moreover, small improvements are easier to maintain than dramatic lifestyle changes.


⚠️ Common Mistake

Specifically, many people believe small savings don’t matter.

Furthermore, for example, notably, they think,

“It’s only $5.”

But that mindset repeated hundreds of times each year quietly destroys long-term wealth.

Consequently, never underestimate the value of small financial decisions.


📌 Expert Insight

Additionally, behavioral finance experts often explain that lasting financial success depends more on consistent habits than short bursts of motivation.

If you’ve followed the previous strategies in this guide—tracking expenses, avoiding impulse buying, building an emergency fund, and reviewing your finances weekly—you’ve already started creating habits that can benefit you for years to come.

In addition, for a deeper understanding of why many people struggle to keep their savings, revisit Why Can’t I Save Money? Specifically, hidden Reasons You’re Still Broke Even with a Good Salary.

However, for example, you can also explore practical financial education from the MoneyHelper service for more guidance on budgeting, saving, and managing everyday finances.


Quick Action Plan

  • Finally, in fact, check your bank balance every morning.
  • Specifically, pause before every non-essential purchase.
  • Moreover, save unexpected income instead of spending it.
  • Additionally, next, first, first, learn one new money lesson every day.
  • Then, next, next, notably, focus on building one financial habit each week.
  • Then, review your progress every Sunday.

Key Takeaway

Therefore, wealth isn’t created by one perfect decision.

Consequently, it’s created by small, consistent habits repeated over time.

When smart money habits become part of your daily routine, saving money stops feeling difficult and starts becoming automatic.

Next Strategy: Learn the final habit that ties everything together and helps you continue saving money long after your 30-day challenge is over.

15. For example, turn Saving Money into a Lifelong Habit—Not Just a 30-Day Challenge

In fact, congratulations.

If you’ve followed the strategies in this guide, you’ve already taken a huge step toward improving your financial life.

However, you’ve learned how to:

  • Additionally, track every expense.
  • Additionally, create a realistic budget.
  • Furthermore, for example, cut unnecessary spending.
  • Finally, avoid impulse purchases.
  • Consequently, reduce monthly bills.
  • Specifically, plan your grocery shopping.
  • However, complete a No-Spend Challenge.
  • Then, first, build an emergency fund.
  • Additionally, next, in fact, increase your income.
  • Then, set meaningful savings goals.
  • Moreover, review your finances weekly.
  • Additionally, avoid lifestyle inflation.
  • Furthermore, notably, build strong daily money habits.

But here’s the truth that many people overlook.

Saving money for 30 days is relatively easy.

Saving money consistently for years is what creates real financial freedom.

Particularly, the biggest difference between people who constantly struggle with money and those who build lasting wealth isn’t intelligence.

In fact, it isn’t luck.

Moreover, it isn’t even income.

Moreover, it’s consistency.

Overall, financial success isn’t built by making one perfect decision.

Specifically, notably, notably, it’s built by making hundreds of smart decisions over months and years.

Consequently, for example, as a result, that’s why this final strategy isn’t about learning another budgeting trick.

Additionally, it’s about creating a lifestyle where saving money becomes automatic.


Why Long-Term Consistency Matters More Than Short-Term Motivation

Additionally, motivation comes and goes.

Furthermore, for example, some days you’ll feel excited to save money.

Specifically, other days you’ll want to spend everything you’ve earned.

If your financial success depends only on motivation, you’ll eventually lose momentum.

Consequently, successful savers rely on systems, not emotions.

Consequently, for example, think about exercising.

However, going to the gym once doesn’t make you healthy.

Consequently, eating one healthy meal doesn’t transform your body.

In fact, the same principle applies to money.

In addition, saving a large amount once is helpful.

Moreover, saving consistently every month changes your life.

According to the Consumer Financial Protection Bureau (CFPB), people who create consistent financial habits are more likely to achieve long-term financial stability than those who rely on occasional motivation.


How to Make Saving Money Automatic

Step 1 – Create a Monthly Money Routine

However, choose one day every month to manage your finances.

During that session:

  • Finally, review your income.
  • Additionally, check your expenses.
  • Specifically, update your savings.
  • Furthermore, first, for example, review your financial goals.
  • Finally, next, plan next month’s budget.

Therefore, notably, treat this appointment as seriously as any important meeting.


Step 2 – Increase Your Savings Every Year

Whenever your salary increases, increase your savings too.

In fact, even raising your savings rate by just 2–5% each year can make a remarkable difference over time.

Additionally, don’t let every salary increase disappear into lifestyle inflation.


Step 3 – Keep Learning About Personal Finance

Particularly, financial education never stops.

Moreover, for example, the more you learn, the better decisions you’ll make.

Overall, read trusted finance books.

Consequently, follow reliable financial websites.

In addition, notably, stay updated on budgeting, saving, investing, and debt management.

However, knowledge is one of the few investments that continues paying dividends throughout your life.


Real-Life Example

However, as a result, david started with a simple goal:

In fact, save $100 every month.

Additionally, it didn’t seem like much.

Moreover, his friends invested in expensive gadgets and luxury items.

Furthermore, david continued following his savings routine.

Specifically, notably, each year, as his income grew, he increased his monthly savings.

Therefore, for example, five years later, he had built an emergency fund, started investing, and saved enough for a down payment on his first home.

Additionally, his success wasn’t the result of one brilliant financial decision.

Consequently, it came from consistently following simple habits year after year.


💡 Pro Tip

In addition, for example, create a simple personal rule:

“Every time I earn more, I save more.”

However, this one habit helps your savings grow automatically as your income increases.


⚠️ Common Mistake

Consequently, don’t stop tracking your finances after reaching your first savings goal.

Therefore, many people save their first $1,000, celebrate, and slowly return to old spending habits.

However, financial success isn’t reaching one milestone.

In fact, it’s continuing the journey.


📌 Expert Insight

In fact, financial experts consistently emphasize that wealth is built through disciplined habits rather than occasional big wins.

Particularly, the strategies you’ve learned in this guide work best when they’re combined into a long-term system rather than used individually.

If you ever notice your savings slowing down, revisit Why Can’t I Save Money? In fact, hidden Reasons You’re Still Broke Even with a Good Salary to identify hidden habits that may be affecting your progress.

Moreover, for more evidence-based personal finance guidance, visit the Consumer.gov financial education resources.


Final Action Plan

  • Consequently, continue tracking every expense.
  • Then, review your finances every week.
  • However, increase your savings whenever your income grows.
  • Additionally, keep building healthy money habits.
  • Furthermore, in fact, continue learning about personal finance.
  • Finally, stay patient and trust the process.

Key Takeaway

Moreover, the fastest way to save money fast in 30 days is to take action today.

Overall, notably, the smartest way to build wealth is to continue those habits long after the 30 days are over.

In fact, notably, money management isn’t about being perfect.

Additionally, it’s about making better financial decisions, one day at a time.

Particularly, as a result, over the years, those small decisions compound into something far more valuable than money alone:

Financial confidence, financial security, and the freedom to live life on your own terms.

1. Is it really possible to save money fast in 30 days

### 1. Is it really possible to save money fast in 30 days?Yes. While you may not become financially independent in just one month, you can make significant progress by tracking your expenses, creating a realistic budget, reducing unnecessary spending, avoiding impulse purchases, and following a consistent savings plan. In addition, even small daily improvements can lead to noticeable savings within 30 days.

How much money should I try to save in 30 days

### 2. How much money should I try to save in 30 days?The amount depends on your income and monthly expenses. A practical goal is to save **10–20% of your monthly income**. If that’s not possible, start with a smaller target and increase it gradually. The most important thing is building a consistent saving habit rather than chasing an unrealistic number.

Practical Steps & Actionable Tips for how to save money fast in 30 days

What is the fastest way to save money if Clearly have a low income?

3. What is the fastest way to save money if Consistently have a low income?
If you have a low income, focus on the strategies that have the biggest impact. However, track every expense, eliminate unnecessary subscriptions, plan your meals, avoid impulse purchases, and try to earn extra income through a side hustle. Particularly, even saving a small amount consistently can make a big difference over time.

4 What should I do after completing the 30-day

4 What should I do after completing the 30-day money-saving challenge?
Don’t stop after the first month. In fact, continue tracking your spending, reviewing your budget every week, increasing your savings as your income grows, and setting new financial goals. The real objective isn’t just to save money for 30 days—it’s to develop lifelong financial habits that help you build lasting wealth.

What should I do after completing the 30-day money-saving challenge

### 5. What should I do after completing the 30-day money-saving challenge?Don’t stop after the first month. Particularly, continue tracking your spending, reviewing your budget every week, increasing your savings as your income grows, and setting new financial goals. The real objective isn’t just to save money for 30 days—it’s to develop lifelong financial habits that help you build lasting wealth.

Conclusion: Start Saving Money Today—Your Future Self Will Thank You

Learning how to save money fast in 30 days isn’t about finding one secret trick or following an extremely strict budget.

Additionally, for example, it’s about making small, smart financial decisions consistently.

Zero Balance Digital Account
Ready to Open Your Free Kotak 811 Account?
Lock in your 30-day savings progress with instant, paperless zero-balance digital banking.
Check Account Details →

Affiliate Disclosure: This article contains an affiliate link. If you open an account through this link, we may earn a commission at no additional cost to you.

Furthermore, throughout this guide, you’ve learned 15 proven strategies that can help you take control of your money—from tracking every expense and creating a realistic budget to avoiding impulse purchases, building an emergency fund, increasing your income, and developing lifelong money habits.

Consequently, you don’t need to implement all 15 strategies perfectly on your first day.

Instead, start with one or two strategies today.

Specifically, build momentum.

Then add another habit next week.

However, remember, financial success isn’t determined by how much you earn—it’s determined by how well you manage what you earn.

Moreover, for example, every dollar you save today is a step toward a stronger financial future.

Whether your goal is to build an emergency fund, become debt-free, invest for the future, buy your dream home, or simply stop living paycheck to paycheck, the journey begins with one decision:

Start today.

Practical Steps & Actionable Tips for how to save money fast in 30 days

In fact, don’t wait for next month.

Consequently, don’t wait for a higher salary.

Moreover, don’t wait for the “perfect time.”

In addition, the best time to take control of your finances is right now.

If you found this guide helpful, consider bookmarking it and revisiting these strategies whenever you need a financial reset. In fact, consistently applying these habits can help you build long-term wealth and achieve lasting financial freedom.

Your 30-day challenge starts today. The sooner you begin, the sooner you’ll see results.

Actionable Advice and Practical Tips for save money fast in 30 days

## Article Summary

However, notably, saving money doesn’t require a high income—it requires smart financial habits and consistent action. In this guide, you learned **15 proven strategies** to help you **save money fast in 30 days**, including tracking every expense, creating a realistic budget, avoiding impulse purchases, reducing monthly bills, planning grocery shopping, building an emergency fund, increasing your income, setting clear savings goals, and developing long-term money habits.

Therefore, the key takeaway is simple: **small financial decisions made consistently create big results over time.** You don’t have to apply every strategy at once. Overall, start with one or two habits today, stay consistent, and gradually build a financial system that supports your goals.

Whether you’re saving for an emergency fund, paying off debt, buying your first home, or simply trying to stop living paycheck to paycheck, these practical strategies can help you take control of your money and build a more secure financial future.

**Remember:** Financial freedom isn’t achieved overnight. It’s built one smart decision at a time.

Written & Researched by Asif Khan

save money fast in 30 days: Asif Khan - Lead Research Editor
Written & Researched by Asif Khan
Founder & Lead Financial Editor PaisaKmao.de

Consequently, over 4 years of active personal finance research in Indian markets. Focused on transparent, math-backed guides to help students and young professionals build wealth and manage money smartly.
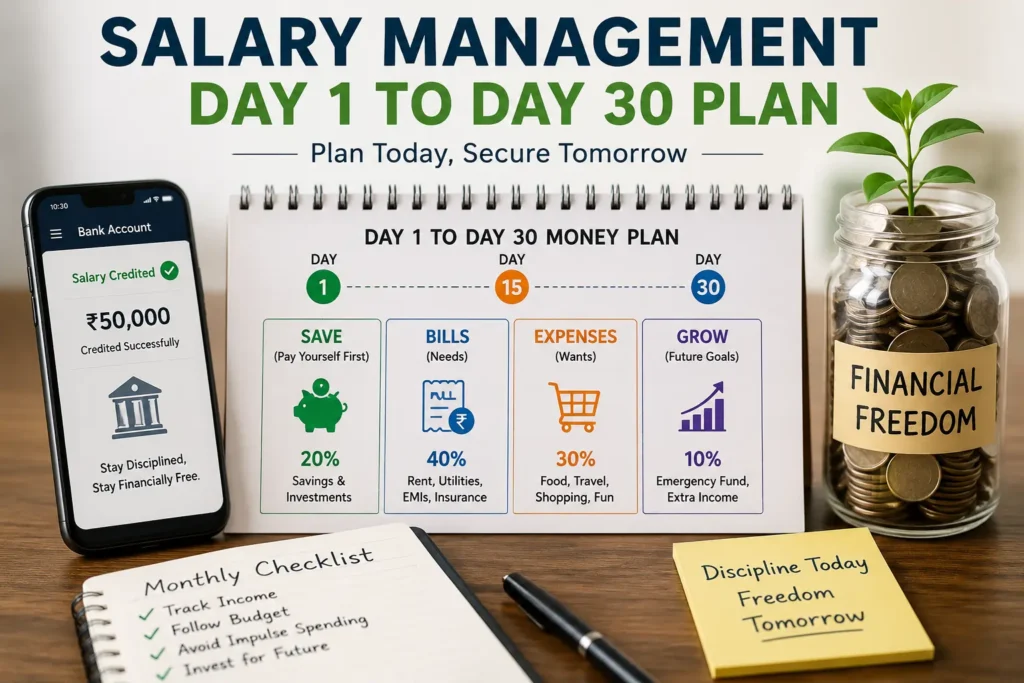
How to Manage Your Salary: A Complete Day 1 to Day 30 Money Plan (2026)

How to manage your salary with a complete 30-day money plan including budgeting, saving, investing, and expense tracking.

Learning the essential principles of how to manage your salary is critical for anyone looking to build healthy money habits, avoid debt traps, and make smart financial decisions in India.

Learning the essential principles of how to manage your salary is critical for anyone looking to build healthy money habits, avoid debt traps, and make smart financial decisions in India.

Learning the essential principles of how to manage your salary is critical for anyone looking to build healthy money habits, avoid debt traps, and make smart financial decisions in India.

Learning the essential principles of how to manage your salary is critical for anyone looking to build healthy money habits, avoid debt traps, and make smart financial decisions in India.

Essential Overview: Guide to how to manage your salary

Learning about how to manage your salary is essential for anyone looking to build healthy money habits. Furthermore, introduction

Additionally, managing your salary isn’t just about earning more—it’s about making smart financial decisions every single month. Specifically, many people believe a higher salary automatically leads to a better financial life, but that’s not always true. For example, imagine two friends, **Rahul** and **Aman**, who both earn **₹40,000 per month**. Furthermore, rahul spends first and saves whatever is left, often running out of money before payday. Consequently, aman, on the other hand, follows a simple salary management plan—he saves first, pays essential bills, sticks to a budget, and tracks his weekly expenses. In addition, after just one year, Aman has an emergency fund and growing investments, while Rahul is still living paycheck to paycheck.The difference isn’t their income—it’s **how they manage their salary**.In this complete guide, you’ll learn **how to manage your salary from Day 1 to Day 30** using practical, beginner-friendly strategies. Whether you earn **₹20,000, ₹50,000, or ₹1,00,000 per month**, you’ll discover how to budget wisely, save consistently, control unnecessary expenses, and build long-term financial stability without sacrificing your lifestyle.

Additionally, for verified statutory guidelines and official regulatory protections, refer directly to the Reserve Bank of India (RBI).

Essential Overview: Guide to how to manage your salary

Additionally, table of Contents

What to Do on Salary Day (Day 1): Complete Guide to how to manage your salary

Furthermore, for example, the day your salary is credited is the most important financial day of the month. Specifically, most people think salary day is the right time to celebrate, shop, or order things they’ve been waiting to buy. Therefore, unfortunately, this is also where many financial problems begin. If you don’t have a plan on the day your salary arrives, your money will slowly disappear on bills, impulse purchases, subscriptions, and unnecessary expenses. By the last week of the month, you may find yourself wondering, “Where did all my money go?”

Specifically, successful money management isn’t about earning a bigger salary—it’s about making the right decisions within the first 24 hours after getting paid. A simple salary management system can help you stay in control of your money throughout the month.

Step 1: Calculate Your Net Salary: Complete Guide to how to manage your salary

Before you plan your expenses, know exactly how much money has reached your bank account. In fact, your net salary is the amount you receive after deductions such as taxes, provident fund (PF), professional tax, insurance, or other employer deductions.

Consequently, for example, if your monthly salary package is ₹45,000 but only ₹41,800 is credited to your bank account, always create your budget using ₹41,800, not ₹45,000. Furthermore, planning based on your gross salary often leads to overspending because you’re budgeting with money you never actually receive.

Real-Life Example: Complete Guide to how to manage your salary

Furthermore, for example, imagine Rahul, a 26-year-old software engineer in Bengaluru. His monthly salary package is ₹50,000, but after deductions, ₹46,300 reaches his bank account. Moreover, every month, Rahul planned his expenses using ₹50,000. He booked weekend trips, ordered food online several times a week, and bought gadgets during online sales. By the last week of the month, he regularly used his credit card to cover basic expenses.

However, one day, Rahul decided to change just one habit—he started budgeting based on his actual credited salary, not his salary package. Overall, within a few months, he noticed fewer money shortages, reduced credit card usage, and started saving consistently. His income didn’t change—his financial planning did.

Why This Step Matters: Complete Guide to how to manage your salary

Consequently, knowing your exact take-home salary gives you a realistic starting point for every financial decision. It helps you:

  • Consequently, create an accurate monthly budget.
  • First, first, first, first, avoid spending money you don’t actually have.
  • However, plan your savings and investments confidently.
  • Next, next, next, next, reduce the chances of running out of money before payday.

Quick Action: As soon as your salary is credited, check your bank account, note your exact take-home salary, and use that amount as the foundation for your monthly money plan. This small habit can make every budgeting decision more accurate and help you manage your salary from Day 1 to Day 30 with confidence.

Step 1: Calculate Your Net Salary Before Planning Anything: Complete Guide to how to manage your salary

In fact, the first and most important step in how to manage your salary is knowing exactly how much money you actually receive every month. Consequently, many people make the mistake of planning their expenses based on their CTC (Cost to Company) or Gross Salary, but that’s one of the biggest reasons they struggle financially before the next payday.

FREE INTERACTIVE TOOL

Day 1 Action: Calculate Your Exact Salary Buckets

In addition, distribute your salary into automated buckets for rent, groceries, lifestyle, and wealth building in one click.

Moreover, your monthly budget should always be based on your Net Salary (Take-Home Salary)—the amount credited to your bank account after deductions such as Provident Fund (PF), Professional Tax, Income Tax (if applicable), and other statutory deductions. If you’re unsure how salary deductions work, the official Income Tax Department explains salary taxation, deductions, and related financial information in detail.

Golden Rule: Never create your monthly budget using your salary package. As a result, always budget using your Net Salary.

What Is Net Salary?: Complete Guide to how to manage your salary

Net Salary, also known as Take-Home Salary, is the actual amount you receive in your bank account after all mandatory deductions are made. This is the amount you should use while planning your monthly budget.

However, for example:

Salary ComponentAmount
Gross Salary₹45,000
Provident Fund (PF)₹1,800
Professional Tax & Other Deductions₹400
Net Salary₹42,800

Although your company pays you ₹45,000, you actually have only ₹42,800 available for spending, saving, and investing. That’s why every financial decision should begin with your Net Salary, not your salary package.

Why Do Most People Make This Mistake?: Complete Guide to how to manage your salary

Therefore, notably, many salaried employees become excited as soon as their salary is credited. Additionally, they immediately start planning shopping, dining out, online subscriptions, vacations, or expensive purchases without checking the exact amount available in their bank account.

In fact, this creates an unrealistic budget from the very first day of the month. As a result, many people rely on credit cards, loans, or borrowed money before their next salary arrives.

Additionally, the problem isn’t always a low income—the problem is planning your finances using the wrong number.

A Practical Real-Life Example: Complete Guide to how to manage your salary

Particularly, imagine two colleagues, Rahul and Aman, who both earn a salary package of ₹50,000 per month.

Moreover, for example, rahul assumes he has ₹50,000 available every month. He spends freely during the first two weeks on online shopping, restaurant meals, OTT subscriptions, and weekend trips. However, after deductions, only ₹46,500 is credited to his account. By the fourth week, he depends on his credit card to pay for groceries and fuel.

Overall, aman earns the same salary package. But every salary day, he first checks his bank account and notices that ₹46,500 has been credited. He prepares his entire monthly budget using only that amount. He saves first, pays rent and utility bills, and then decides how much he can safely spend on entertainment.

Consequently, after one year, Rahul is still living paycheck to paycheck, while Aman has built an emergency fund and started investing regularly.

Specifically, notably, the difference wasn’t their income—it was how they managed their salary.

Why This Step Is Important: Complete Guide to how to manage your salary

However, knowing your Take-Home Salary helps you make realistic financial decisions from the beginning of the month. It allows you to:

  • Then, in fact, create an accurate monthly budget.
  • Additionally, avoid overspending.
  • Moreover, save money consistently.
  • Furthermore, plan investments with confidence.
  • Finally, notably, reduce financial stress before payday.
  • Specifically, build long-term financial stability.

Additionally, for example, as a result, for additional financial awareness and responsible money management practices, you can also explore educational resources published by the Reserve Bank of India (RBI).

Quick Action Plan: Complete Guide to how to manage your salary

Before spending a single rupee on salary day:

  • Then, check your bank account and note your Net Salary.
  • Additionally, ignore your CTC or Gross Salary while budgeting.
  • Furthermore, create your monthly budget using only your Take-Home Salary.
  • Finally, write down your savings goal.
  • Specifically, move to the next step before making any unnecessary purchases.

Pro Tip: Spending just five minutes checking your Net Salary on payday can save you from weeks of financial stress and help you stay in control of your money throughout the month.Releted postWhy Can’t I Save Money? 5 Hidden Reasons You’re Still Broke Even With a Good Salary

Step 2: Pay Yourself First Before Paying Anyone Else: Complete Guide to how to manage your salary

In fact, after calculating your Net Salary, the next step is the foundation of smart salary management—Pay Yourself First.

Additionally, most people follow this order:

Salary → Bills → Shopping → Entertainment → Savings (if anything is left)

Moreover, unfortunately, by the end of the month, there’s usually nothing left to save.

Furthermore, financially successful people follow a completely different approach:

Salary → Savings → Investments → Bills → Expenses → Lifestyle

Specifically, notably, this simple habit ensures that your future is funded before your lifestyle.

According to the Reserve Bank of India (RBI), building healthy saving habits and managing personal finances wisely are essential for long-term financial stability.

Golden Rule: Save first. In addition, spend what’s left—not the other way around.

What Does “Pay Yourself First” Mean?: Complete Guide to how to manage your salary

Pay Yourself First means transferring a fixed portion of your salary into your savings or investment account immediately after your salary is credited—before paying for shopping, entertainment, or other non-essential expenses.

Consequently, for example, think of your savings as the first bill you must pay every month.

Instead of asking:

“How much can I save this month?”

Additionally, ask yourself:

“How much will I save before Always spend anything?”

Consequently, this small mindset shift can completely change your financial future.

A Practical Real-Life Example: Complete Guide to how to manage your salary

In addition, for example, let’s look at two friends.

Rahul earns ₹40,000 every month.

However, after receiving his salary, he pays bills, orders food online, buys clothes during sales, watches movies on weekends, and spends freely. At the end of the month, only ₹1,200 remains, and some months he saves nothing.

Consequently, now look at Aman, who earns the same salary.

Therefore, the moment his salary is credited, he automatically transfers ₹8,000 to a separate savings account. Specifically, after that, he pays his rent, utility bills, groceries, and other monthly expenses. Since his savings are already secured, he spends the remaining money without worrying.

However, after one year:

  • Additionally, rahul has almost no savings.
  • Then, first, first, aman has saved ₹96,000, even before earning any investment returns.

In fact, the difference wasn’t their salary.

In fact, the difference was one simple habit—Pay Yourself First.

How Much Should You Save First?: Complete Guide to how to manage your salary

Particularly, there’s no perfect percentage that works for everyone, but a simple starting point is:

Monthly SalaryRecommended Savings
₹20,000₹2,000–₹4,000 (10–20%)
₹40,000₹6,000–₹8,000 (15–20%)
₹60,000₹9,000–₹12,000 (15–20%)
₹1,00,000₹20,000+ (20% or more)

If your income is currently low, don’t worry.

Moreover, even saving ₹500 or ₹1,000 every month builds the habit that creates long-term wealth.

Automate Your Savings: Complete Guide to how to manage your salary

Moreover, one of the easiest ways to follow this rule is automation.

Overall, notably, as soon as your salary arrives:

  • Additionally, next, next, for example, automatically transfer money to your savings account.
  • Then, start a monthly SIP if you’re investing.
  • Consequently, keep emergency fund savings in a separate account.
  • Additionally, avoid keeping all your money in one spending account.

In addition, notably, automation removes emotions from money decisions.

Common Mistakes to Avoid: Complete Guide to how to manage your salary

Additionally, many people unknowingly delay their financial progress by making these mistakes:

  • However, saving only if money is left.
  • Furthermore, spending bonuses immediately.
  • Finally, in fact, increasing lifestyle after every salary hike.
  • Specifically, using savings for unnecessary shopping.
  • Moreover, depending on credit cards instead of building savings.

However, as a result, avoiding these mistakes can make a significant difference over time.

Quick Action Plan: Complete Guide to how to manage your salary

On your next salary day:

  • Then, decide how much you’ll save before spending.
  • Additionally, transfer that amount immediately.
  • Furthermore, keep savings in a separate account.
  • Finally, spend only from the remaining balance.
  • Specifically, repeat this habit every month without exception.

Pro Tip: Don’t wait until you earn a bigger salary to start saving. For example, build the habit today. As your income grows, your savings will grow automatically.

Additionally, for example, once you’ve paid yourself first, the next step is to pay all your essential bills and fixed expenses before spending money on anything else. This ensures your monthly budget stays on track from Day 1 to Day 30 Letest post.10 Best Financial Habits Every College Student Should Develop (2026)

Step 3: Pay Your Essential Bills and Fixed Expenses First: Complete Guide to how to manage your salary

Furthermore, once you’ve calculated your Net Salary and paid yourself first, the next priority is paying your essential bills and fixed monthly expenses. This simple habit keeps your finances organized, helps you avoid late payment charges, and reduces unnecessary financial stress throughout the month.

Consequently, many people spend money on shopping, dining out, or entertainment immediately after payday. A few days later, they realize rent is due, the electricity bill hasn’t been paid, or their EMI is approaching. This often forces them to use credit cards or borrow money just to cover essential expenses.

Golden Rule: Always pay your financial responsibilities before spending on your lifestyle.

What Are Essential Bills?: Complete Guide to how to manage your salary

Specifically, essential bills are expenses you must pay every month to maintain your daily life. These usually include:

  • Furthermore, first, first, house Rent
  • Finally, next, next, notably, home Loan or EMI
  • Then, electricity Bill
  • Additionally, water Bill
  • Additionally, internet & Mobile Recharge
  • Furthermore, for example, gas Bill
  • Finally, insurance Premium
  • Consequently, children’s School Fees (if applicable)
  • Specifically, transportation Costs

However, these expenses should always come before shopping, vacations, or other non-essential purchases.

A Practical Real-Life Example: Complete Guide to how to manage your salary

Therefore, for example, imagine Priya, who earns ₹35,000 every month.

On salary day, she buys a new smartwatch during an online sale, orders food throughout the week, and plans a weekend trip with friends. A few days later, she remembers her electricity bill and internet bill are due. Since most of her money has already been spent, she pays them using her credit card and ends up paying additional interest.

In fact, now consider Neha, who earns the same ₹35,000 salary.

Consequently, the first thing she does after receiving her salary is pay her rent, electricity bill, internet bill, insurance premium, and other fixed expenses. Specifically, whatever remains becomes her spending budget for the month.

At the end of the month, Neha has no overdue bills, no penalties, and much less financial stress than Priya.

Moreover, the difference isn’t income—it’s the order in which they use their salary.

Create a Fixed Expense List: Complete Guide to how to manage your salary

In addition, one of the easiest ways to stay organized is to prepare a list of your recurring monthly expenses.

Essential ExpenseExample Amount
Rent₹10,000
Electricity₹1,500
Internet₹800
Mobile Recharge₹400
EMI₹5,000
Insurance₹2,000

However, notably, once these expenses you pay, you’ll know exactly how much money is available for groceries, transportation, entertainment, and savings goals.

Why Paying Bills First Is Important: Complete Guide to how to manage your salary

Therefore, paying your fixed expenses immediately after salary day helps you:

  • ️ Avoid late payment penalties.
  • ️ Maintain a good credit history.
  • ️ Reduce financial stress.
  • ️ Prevent unnecessary credit card usage.
  • ️ Know exactly how much money is available for the rest of the month.

If you use credit cards or loans, it’s also important to understand responsible borrowing and repayment. The Reserve Bank of India (RBI) regularly publishes consumer awareness resources on safe banking practices and financial discipline.

Common Mistakes to Avoid: Complete Guide to how to manage your salary

Additionally, avoid these common salary management mistakes:

  • However, paying bills after unnecessary shopping.
  • Then, first, missing EMI due dates.
  • Additionally, next, in fact, ignoring insurance premiums.
  • Then, spending your emergency fund on lifestyle expenses.
  • Moreover, depending on credit cards for monthly bills.

In fact, even one missed payment can lead to late fees and unnecessary financial pressure.

Quick Action Plan: Complete Guide to how to manage your salary

Particularly, for example, as soon as your salary is credited:

  • Furthermore, pay your rent or home loan.
  • Finally, clear all utility bills.
  • Specifically, pay EMIs before the due date.
  • Specifically, first, pay insurance premiums.
  • Then, first, next, mark every payment as completed.
  • Then, use the remaining money for daily spending.

Pro Tip: Set up AutoPay or automatic bill payments for recurring expenses. This helps you avoid missed due dates, protects your credit history, and gives you peace of mind every month.

Moreover, now that your savings are secured and your essential bills you pay, the next step is to create a realistic monthly budget so every remaining rupee has a clear purpose.

Step 4: Create a Monthly Budget That Gives Every Rupee a Purpose: Complete Guide to how to manage your salary

Consequently, after you’ve calculated your Net Salary, saved first, and paid your essential bills, the next step is creating a monthly budget. A budget isn’t about restricting your life—it’s about telling your money where to go instead of wondering where it went.

Overall, many people think budgeting is only for those with a low salary. In reality, people with high incomes also struggle financially when they don’t follow a proper budget. A well-planned budget helps you cover your expenses, save consistently, and achieve your financial goals without unnecessary stress.

Golden Rule: Every rupee should have a job before you spend it.

Why Is a Monthly Budget Important?: Complete Guide to how to manage your salary

However, without a budget, it’s easy to overspend on small purchases that don’t seem significant individually but add up over time.

In fact, notably, for example:

  • ₹250 coffee × 10 times = ₹2,500
  • Additionally, food delivery = ₹3,000
  • Furthermore, notably, online shopping = ₹4,000
  • OTT subscriptions = ₹800

By the end of the month, you’ve spent ₹10,000+ without realizing it.

A monthly budget gives you complete visibility over your money and helps you make smarter financial decisions.

A Practical Real-Life Example: Complete Guide to how to manage your salary

In fact, suppose Aman receives a Net Salary of ₹50,000.

Instead of spending randomly, he creates a budget before making any purchases.

Budget CategoryAmountPercentage
Savings & Investments₹10,00020%
Rent & Bills₹18,00036%
Groceries₹7,00014%
Transportation₹3,0006%
Personal & Entertainment₹7,00014%
Emergency Buffer₹5,00010%
Total₹50,000100%

Because every rupee has a purpose, Aman knows exactly how much he can spend without affecting his savings or financial goals.

Budget Comparison Table: Complete Guide to how to manage your salary

Without a BudgetWith a Budget
Money disappears quicklyEvery expense is planned
Frequent impulse buyingControlled spending
No idea where money wentEvery rupee is tracked
Little or no savingsSavings become automatic
Financial stressBetter financial confidence

A Simple Salary Budget Formula: Complete Guide to how to manage your salary

A beginner-friendly budgeting formula looks like this:

CategoryRecommended Allocation
Savings & Investments20%
Essential Bills40–50%
Daily Living Expenses20–30%
Wants & Entertainment10–20%

Particularly, as a result, this isn’t a fixed rule. In addition, adjust the percentages according to your income, responsibilities, and financial goals.

Common Budgeting Mistakes: Complete Guide to how to manage your salary

Moreover, avoid these mistakes while creating your monthly budget:

  • ❌ Creating a budget but never following it.
  • ❌ Forgetting irregular expenses like annual insurance or festivals.
  • ❌ Spending first and budgeting later.
  • ❌ Not reviewing your budget every month.
  • ❌ Ignoring emergency savings.

Monthly Budget Checklist

TaskStatus
Calculate Net Salary
Save First
Pay Essential Bills
Create Monthly Budget
Track Weekly Expenses⬜
Review Budget at Month-End⬜

Quick Action Plan

Before the first week of every month:

  • Additionally, write down your exact Net Salary.
  • Furthermore, divide your income into categories.
  • Finally, allocate money for savings first.
  • Specifically, budget for fixed and variable expenses.
  • Additionally, next, first, keep a small emergency buffer.
  • Then, next, review and improve your budget every month.

Pro Tip: A budget isn’t meant to control your life—it gives you the freedom to spend confidently because you already know your money is working toward your financial goals.

Additionally, the next step is to divide your salary into weekly spending limits, making it much easier to avoid overspending before the end of the month.

Step 5: Divide Your Salary Into Weekly Spending Limits

Furthermore, notably, after creating your monthly budget, don’t leave all your remaining money in one place. One of the smartest salary management techniques is to divide your monthly spending budget into weekly spending limits. This simple habit helps you control expenses, reduce impulse purchases, and avoid running out of money before your next payday.

Specifically, many financial experts recommend breaking large financial goals into smaller, manageable parts. The same principle applies to your salary. However, managing one week’s expenses is much easier than trying to control an entire month’s spending.

According to the Reserve Bank of India (RBI), maintaining financial discipline and planning your expenses are important habits for improving long-term financial well-being.

Golden Rule: Control one week at a time, and you’ll automatically control the entire month.

Why Do People Run Out of Money Before Month-End?

Additionally, have you ever received your salary and felt rich for the first few days?

Moreover, for example, many people do things like:

  • Finally, buy new clothes because of online sales.
  • Additionally, order food almost every day.
  • Specifically, plan expensive weekend outings.
  • Then, first, for example, purchase gadgets on EMI.
  • Additionally, next, spend without checking their remaining budget.

During the first week, everything feels affordable.

By the third week, reality changes.

Consequently, for example, the bank balance becomes smaller, bills are still pending, and people start thinking about using their credit card or borrowing money until the next salary arrives.

In addition, the problem isn’t always a low salary.

Consequently, the real problem is spending too much too early.

A Practical Real-Life Example

However, let’s understand this with a realistic example.

Aman earns a Net Salary of ₹50,000 every month.

However, after following the first four steps, his money looks like this:

CategoryAmount
Net Salary₹50,000
Savings & Investments₹10,000
Essential Bills₹20,000
Emergency Fund₹4,000
Remaining Spending Budget₹16,000

Instead of keeping the entire ₹16,000 in his spending account, Aman divides it equally across four weeks.

WeekMaximum Spending Limit
Week 1₹4,000
Week 2₹4,000
Week 3₹4,000
Week 4₹4,000

Therefore, now every Sunday, Aman checks how much money he spent during the week.

If he spends only ₹3,500, the remaining ₹500 is transferred to his emergency fund instead of being spent unnecessarily.

In fact, this simple habit helps him stay within budget every single month.

What Happens Without Weekly Planning?

In fact, imagine another employee, Rahul, earning exactly the same ₹50,000 salary.

Moreover, after paying his bills, he also has ₹16,000 left.

However, he doesn’t divide his money weekly.

During the first week:

  • Consequently, new shoes – ₹3,000
  • Then, weekend trip – ₹4,000
  • However, food delivery – ₹2,500
  • Additionally, shopping – ₹3,000

Particularly, within seven days, Rahul has already spent ₹12,500.

Moreover, notably, only ₹3,500 remains for the next three weeks.

Overall, as a result:

  • Furthermore, in fact, he cancels important plans.
  • Finally, uses his credit card for groceries.
  • Moreover, borrows money from friends before payday.
  • Specifically, feels stressed every month.

Additionally, the difference isn’t salary.

Overall, notably, the difference is financial discipline.

Weekly Budget Planner

Expense CategoryWeekly Budget
Groceries₹1,400
Transportation₹800
Food & Snacks₹700
Entertainment₹500
Miscellaneous₹600
Total₹4,000

Furthermore, notably, as a result, for example, this table gives every rupee a purpose and prevents overspending.

Weekly Progress Tracker

WeekBudgetActual SpendingMoney Saved
Week 1₹4,000₹3,650₹350
Week 2₹4,000
Week 3₹4,000
Week 4₹4,000

Additionally, update this table every weekend.

Consequently, you’ll quickly identify where you’re overspending and where you can save more.

Why This Method Works

Furthermore, weekly budgeting offers several benefits:

  • ️ Makes spending easier to control.
  • ️ Prevents impulse buying.
  • ️ Reduces financial stress.
  • ️ Improves saving habits.
  • ️ Helps you reach month-end without borrowing money.
  • ️ Makes budgeting feel simple instead of overwhelming.

Common Mistakes to Avoid

However, avoid these habits if you want your weekly budget to succeed:

  • ❌ Spending next week’s budget early.
  • ❌ Ignoring small online purchases.
  • ❌ Shopping during every sale.
  • ❌ Treating your credit card as extra income.
  • ❌ Not reviewing weekly expenses.

Specifically, even small expenses of ₹200–₹300 every day can quietly consume thousands of rupees over a month.

Quick Weekly Money Challenge

In fact, try this for the next 30 days:

  • Furthermore, first, notably, monday: Track every expense.
  • Finally, next, wednesday: Avoid unnecessary online shopping.
  • Additionally, friday: Review your remaining weekly budget.
  • Then, sunday: Calculate how much money you saved.

If you repeat this routine every week, you’ll gradually build better financial habits without feeling restricted.

Pro Tip: Don’t wait until the end of the month to check your finances. A 10-minute review every Sunday is enough to keep your salary under control and prevent financial mistakes before they become serious.

Specifically, as a result, for example, now that you’ve learned how to divide your salary into weekly spending limits, the next step is to track every expense, identify money leaks, and make sure every rupee is working toward your financial goals.

Step 6: Track Every Expense to Stop Money Leaks

Moreover, after creating a monthly budget and dividing your salary into weekly spending limits, the next habit that separates financially successful people from everyone else is tracking every expense.

Consequently, many people believe they know where their money goes every month. But when they actually record every expense for 30 days, they’re often surprised to discover that hundreds or even thousands of rupees were spent on things they barely remember buying.

According to the Reserve Bank of India (RBI), responsible money management begins with understanding your spending habits. You can’t improve your finances if you don’t know where your money is going.

Golden Rule: What gets tracked gets controlled.

Why Expense Tracking Is So Important

In addition, notably, most financial problems aren’t caused by one big purchase.

Instead, they’re caused by dozens of small expenses that seem harmless.

However, for example:

  • Additionally, for example, morning coffee – ₹120
  • Furthermore, evening snacks – ₹180
  • Consequently, food delivery – ₹450
  • Finally, online subscription – ₹299
  • However, cab ride – ₹320

Additionally, individually, these expenses don’t look expensive.

But over one month, they can quietly cost ₹6,000–₹10,000 or even more.

Therefore, tracking every expense helps you identify these “money leaks” before they become a habit.

A Practical Real-Life Example

In fact, for example, imagine Rohit, who earns a Net Salary of ₹45,000 every month.

Particularly, he always believed he couldn’t save money because his salary was too low.

Consequently, one day, he decided to record every expense for 30 days.

At the end of the month, he found this:

ExpenseMonthly Cost
Coffee & Tea₹2,200
Food Delivery₹4,500
Online Shopping₹3,800
Ride Booking Apps₹2,400
Unused Subscriptions₹900
Total Unplanned Spending₹13,800

Moreover, rohit realized the problem wasn’t his salary.

However, the problem was spending money without tracking it.

Overall, the following month, he reduced these unnecessary expenses and saved more than ₹8,000 without earning a single extra rupee.

How to Track Every Expense

In fact, expense tracking doesn’t have to be complicated.

Additionally, notably, simply record every expense immediately after spending.

Moreover, you can use:

  • A notebook.
  • Specifically, notes app on your phone.
  • Specifically, first, in fact, google Sheets or Excel.
  • Additionally, first, next, any trusted expense-tracking application.

Furthermore, as a result, the important thing is consistency—not the tool you use.

Daily Expense Tracker

DateExpenseCategoryAmount
2 JanGroceriesFood₹850
2 JanCoffeeFood₹120
3 JanPetrolTransport₹700
3 JanOTT SubscriptionEntertainment₹299

Additionally, notably, recording expenses every day takes less than two minutes, but it can completely change your financial habits.

Identify Your Biggest Money Leaks

At the end of every week, ask yourself:

  • Moreover, did Ensure you spend on something I didn’t need?
  • Then, which category consumed the most money?
  • Additionally, notably, could Clearly have avoided any purchase?
  • Furthermore, did this purchase improve my life?
  • Additionally, can I reduce this expense next month?

Furthermore, these questions help you make smarter financial decisions instead of emotional ones.

The 24-Hour Rule

Before buying anything that isn’t essential, wait 24 hours.

Additionally, ask yourself:

  • Finally, do I really need this?
  • Specifically, for example, will I still want it tomorrow?
  • Furthermore, next, first, does this purchase fit within my weekly budget?
  • Consequently, will buying this delay my savings goal?

Specifically, many impulse purchases disappear after just one day.

Weekly Expense Review

Specifically, for example, for example, every Sunday evening, spend 10 minutes reviewing your expenses.

WeekBudgetActual SpendingDifference
Week 1₹4,000₹3,650+₹350
Week 2₹4,000₹4,200-₹200
Week 3₹4,000
Week 4₹4,000

Consequently, this review helps you correct mistakes before they become month-end financial problems.

Common Expense Tracking Mistakes

Consequently, avoid these common mistakes:

  • ❌ Recording expenses only once a month.
  • ❌ Ignoring cash payments.
  • ❌ Forgetting online subscriptions.
  • ❌ Not categorizing expenses.
  • ❌ Stopping after one week.

In addition, remember, consistency matters more than perfection.

7-Day Expense Tracking Challenge

However, for the next seven days:

  • Then, record every rupee you spend.
  • Additionally, categorize each expense.
  • Furthermore, review your spending every night.
  • Finally, highlight unnecessary purchases.
  • Specifically, transfer the money you saved into your emergency fund or savings account.

However, after just one week, you’ll have a much clearer picture of your financial habits.

Pro Tip: Most people think they need a higher salary to save more money. In reality, they first need better awareness of where their current salary is going. Therefore, tracking your expenses is one of the fastest ways to improve your financial health without increasing your income.letest post reed more

In fact, now that you know exactly where your money goes, the next step is to avoid impulse buying and lifestyle inflation, two of the biggest reasons people remain stuck living paycheck to paycheck.

Step 7: Avoid Impulse Buying and Lifestyle Inflation

Therefore, you’ve calculated your Net Salary, paid yourself first, cleared your essential bills, created a budget, divided your salary into weekly spending limits, and started tracking every expense. Now it’s time to protect all that hard work.

Moreover, one of the biggest reasons people fail to build wealth isn’t because they earn too little—it’s because they spend more every time they earn more. This habit we call this lifestyle inflation.

At the same time, impulse buying silently drains your salary through unplanned purchases that provide only temporary happiness.

According to the Reserve Bank of India (RBI), making informed financial decisions and avoiding unnecessary borrowing are important parts of maintaining long-term financial stability.

Golden Rule: Increase your savings before you increase your lifestyle.

What Is Impulse Buying?

In fact, impulse buying means purchasing something without planning for it.

Particularly, notably, these purchases are usually driven by emotions rather than actual needs.

Moreover, common examples include:

  • Finally, first, next, buying products because they’re on sale.
  • However, ordering food just because you’re bored.
  • Then, purchasing gadgets after watching social media reviews.
  • Additionally, in fact, buying clothes you don’t actually need.
  • Furthermore, upgrading your phone even though the current one works perfectly.

Additionally, most impulse purchases feel exciting for a few minutes—but they reduce your financial freedom for months.

What Is Lifestyle Inflation?

Overall, lifestyle inflation happens when your expenses increase every time your income increases.

Additionally, for example, for example, notably, for example, for example:

Consequently, as a result, rahul earns ₹30,000 and buys a bike on EMI.

Consequently, after one year, his salary increases to ₹40,000.

Instead of increasing his investments, he upgrades his phone, starts eating at expensive restaurants, buys premium subscriptions, and spends more every weekend.

Although Rahul now earns ₹10,000 more, he still struggles to save money.

Additionally, his income increased—but so did his lifestyle.

A Practical Real-Life Example

However, now look at Aman.

Furthermore, he also receives a salary hike from ₹30,000 to ₹40,000.

Instead of increasing his lifestyle immediately, he follows a simple rule.

  • Moreover, previous Monthly Savings: ₹4,000
  • Finally, new Monthly Savings: ₹8,000

In fact, he continues living almost the same lifestyle for another year.

At the end of 12 months:

PersonSalaryMonthly SavingsTotal Savings After 1 Year
Rahul₹40,000₹2,000₹24,000
Aman₹40,000₹8,000₹96,000

Specifically, both earned the same salary.

Moreover, the difference was their financial habits—not their income.

Ask Yourself These 5 Questions Before Every Purchase

Before buying anything that’s not essential, pause and ask yourself:

  1. Do I really need this, or do I simply want it?
  2. Will I still want this after 24 hours?
  3. Can I pay for this without touching my savings?
  4. Does this purchase help me achieve my financial goals?
  5. If I don’t buy this today, what will I lose?

If you can’t answer these questions confidently, it’s usually better to wait.

Needs vs Wants Comparison

NeedsWants
RentNew branded shoes
GroceriesDining at expensive restaurants
Electricity BillLatest smartphone upgrade
MedicinesPremium streaming subscriptions
InsuranceLuxury fashion shopping

Learning to identify the difference between needs and wants is one of the most valuable money skills you’ll ever develop.

The 30-Day Rule for Expensive Purchases

In addition, for example, for expensive purchases like:

  • Specifically, notably, smartphones
  • Specifically, next, first, laptops
  • Additionally, smartwatches
  • Then, next, furniture
  • Then, for example, luxury fashion
  • Additionally, gaming devices

Consequently, notably, wait 30 days before buying.

If you still genuinely need the item after 30 days—and it fits within your budget—you can purchase it without guilt.

In addition, this simple rule prevents emotional spending and helps you make rational financial decisions.

Common Mistakes That Increase Lifestyle Inflation

Additionally, avoid these habits:

  • ❌ Increasing expenses after every salary hike.
  • ❌ Shopping during every online sale.
  • ❌ Buying things to impress others.
  • ❌ Upgrading gadgets too frequently.
  • ❌ Using credit cards for luxury purchases.
  • ❌ Treating salary increments as spending money instead of wealth-building opportunities.

Lifestyle Inflation Checklist

QuestionYesNo
Did I save before spending?⬜⬜
Was this purchase planned?⬜⬜
Does it fit my monthly budget?⬜⬜
Can I afford it without debt?⬜⬜
Will it improve my life long-term?⬜⬜

If you answer “No” to most of these questions, consider postponing the purchase.

Quick Action Plan

However, starting today:

  • Additionally, follow the 24-hour rule for small purchases.
  • Furthermore, follow the 30-day rule for expensive purchases.
  • Finally, save at least 50% of every salary increment before increasing your lifestyle.
  • Specifically, buy based on your financial goals—not your emotions.
  • Furthermore, first, first, review every unnecessary purchase at the end of the month.

Pro Tip: The fastest way to become financially strong isn’t earning more money—it’s keeping more of the money you already earn. In fact, every unnecessary purchase delays your financial freedom, while every thoughtful decision brings you one step closer to it.

Therefore, for example, now that you’ve learned how to control impulse buying and lifestyle inflation, the next step is to build an emergency fund so unexpected expenses never force you into debt.

Step 8: Build an Emergency Fund Before an Emergency Happens

In fact, no matter how carefully you manage your salary, life is unpredictable. A sudden medical emergency, job loss, family responsibility, vehicle repair, or unexpected home expense can disrupt your financial plan overnight.

Consequently, this is why every salaried employee should build an Emergency Fund. Particularly, think of it as your financial safety net. It protects you from borrowing money, taking personal loans, or using credit cards during difficult times.

According to the Reserve Bank of India (RBI), maintaining financial resilience through savings and responsible financial planning is an important part of personal financial management.

Golden Rule: Build your emergency fund when life is normal, not when an emergency has already arrived.


What Is an Emergency Fund?

Particularly, an Emergency Fund is money that you keep aside only for genuine emergencies—not for shopping, vacations, festivals, or buying the latest smartphone.

However, this money should only be used in situations like:

  • Consequently, medical emergencies
  • Furthermore, sudden job loss
  • However, family emergencies
  • Finally, unexpected house repairs
  • Specifically, in fact, vehicle breakdown
  • Finally, next, next, first, urgent travel
  • Moreover, temporary income loss

If the expense isn’t urgent and can wait, it shouldn’t come from your emergency fund.


Why Every Salaried Employee Needs an Emergency Fund

Moreover, many people believe emergencies happen only to others.

In fact, unfortunately, life doesn’t work that way.

Overall, imagine these situations:

  • Then, next, your company delays salary by two weeks.
  • Then, notably, you suddenly lose your job.
  • A family member requires immediate medical treatment.
  • Additionally, your laptop stops working if you work from home.
  • Additionally, your bike or car needs expensive repairs.

Moreover, without an emergency fund, most people have only three options:

  • Furthermore, borrow money from friends or relatives.
  • Finally, for example, take a personal loan.
  • Specifically, use a credit card and pay high interest.

However, notably, an emergency fund helps you avoid all three.

Instead of panicking, you simply use the money you’ve already prepared.


A Practical Real-Life Example

Therefore, as a result, notably, let’s compare two colleagues.

Rahul

Additionally, rahul earns ₹45,000 every month.

Additionally, he spends almost his entire salary on rent, shopping, food delivery, and entertainment.

Furthermore, he believes:

“I’ll start saving next year when my salary increases.”

Specifically, for example, one day, Rahul’s company announces restructuring, and his salary is delayed by three weeks.

Since he has no emergency savings:

  • Consequently, he borrows ₹15,000 from a friend.
  • Additionally, first, uses his credit card for groceries.
  • However, pays late fees on his EMI.
  • Furthermore, next, feels stressed throughout the month.

Aman

In fact, for example, aman earns exactly the same salary.

Consequently, every month, he transfers ₹3,000 into his emergency fund before spending on anything else.

Consequently, after two years:

₹3,000 × 24 months = ₹72,000

When his company delays salaries, Aman continues paying rent, bills, groceries, and transportation without borrowing a single rupee.

However, his income didn’t protect him.

In addition, his preparation did.


How Much Emergency Fund Should You Have?

In fact, financial planners generally recommend saving enough money to cover 3–6 months of essential living expenses.

However, here’s a simple example:

Monthly Essential ExpensesEmergency Fund Goal
₹20,000₹60,000–₹1,20,000
₹30,000₹90,000–₹1,80,000
₹40,000₹1,20,000–₹2,40,000
₹50,000₹1,50,000–₹3,00,000

If your job is unstable or you’re the only earning member in your family, consider building a fund closer to 6–12 months of essential expenses.


Start Small—Consistency Matters More Than Amount

Moreover, many people never start because they think they need thousands of rupees every month.

Therefore, that’s a mistake.

In fact, notably, even if you save:

  • ₹500 every month
  • ₹1,000 every month
  • ₹2,000 every month

you’re building one of the strongest financial habits.

Particularly, small savings become large security over time.


Where Should You Keep Your Emergency Fund?

Additionally, your emergency fund should be:

  • Then, in fact, safe
  • Additionally, easily accessible
  • Moreover, separate from your daily spending account

Moreover, good places include:

  • Furthermore, high-interest savings account
  • Finally, notably, sweep-in fixed deposit
  • Specifically, liquid mutual fund (for those who understand the risks and liquidity)

Overall, for example, avoid keeping your emergency fund in:

  • Additionally, stocks
  • Finally, first, cryptocurrency
  • Specifically, next, for example, high-risk investments
  • Then, long lock-in investments

Particularly, notably, the goal isn’t high returns.

Consequently, the goal is quick access when you need the money most.


Emergency Fund Growth Example

Monthly Saving1 Year2 Years3 Years
₹1,000₹12,000₹24,000₹36,000
₹2,000₹24,000₹48,000₹72,000
₹5,000₹60,000₹1,20,000₹1,80,000

Moreover, as a result, this table shows that consistent saving is far more powerful than waiting for a higher salary.


Common Mistakes to Avoid

However, don’t make these mistakes:

  • ❌ Using your emergency fund for shopping.
  • ❌ Spending it on vacations.
  • ❌ Buying gadgets from it.
  • ❌ Investing the entire emergency fund in risky assets.
  • ❌ Keeping it in the same account as your daily spending money.
  • ❌ Stopping contributions after saving a few thousand rupees.

Additionally, remember:

An emergency fund is insurance for your financial life—not extra spending money.


Emergency Fund Readiness Checklist

QuestionYesNo
Do Consistently have a separate emergency fund account?⬜⬜
Can it cover at least 3 months of expenses?⬜⬜
Am I adding money every month?⬜⬜
Do I use it only for real emergencies?⬜⬜
Do Proactively rebuild it after using it?⬜⬜

30-Day Emergency Fund Challenge

During your next salary cycle:

Week 1

  • Consequently, transfer money to your emergency fund immediately after salary day.

Week 2

  • Additionally, cut one unnecessary expense and add that money to your fund.

Week 3

  • However, sell unused items and deposit the money.

Week 4

  • Furthermore, review your progress and increase your monthly contribution if possible.

In fact, repeat this challenge every month.


Pro Tip: An emergency fund doesn’t make you rich overnight, but it prevents a temporary financial problem from becoming a long-term financial crisis. The day you actually need it, you’ll be grateful that you started building it long before the emergency arrived.

Furthermore, now that you’ve created a financial safety net, the next step is to invest a part of your salary every month, allowing your money to grow instead of simply sitting in your bank account.

Step 10: Review Your Salary Plan at the End of Every Month and Improve It

Moreover, managing your salary doesn’t end after creating a budget, saving money, or investing. The final and most overlooked step is reviewing your financial progress every month.

Specifically, many people work hard to create a budget in January but never look at it again. In fact, they repeat the same financial mistakes every month because they never stop to analyze what went right and what went wrong.

Overall, for example, notably, successful money management isn’t about creating the perfect budget—it’s about improving your budget every single month.

According to the Consumer Financial Protection Bureau (CFPB), regularly reviewing your spending, savings, and financial goals helps people make better money decisions and build healthier financial habits over time.

Golden Rule: What you review regularly, you improve consistently.


Why a Monthly Financial Review Matters

Consequently, imagine driving from Delhi to Mumbai without ever looking at the fuel gauge or the map.

Additionally, sooner or later, you’ll take the wrong route or run out of fuel.

In addition, managing your salary works the same way.

If you never review your finances, you’ll never know:

  • Finally, in fact, where your money actually went.
  • Specifically, which expenses were unnecessary.
  • Whether you achieved your savings goal.
  • If you stayed within your budget.
  • Moreover, how much you invested.
  • Then, first, first, what you should improve next month.

A monthly review turns experience into financial wisdom.


A Practical Real-Life Example

However, for example, let’s compare Rahul and Aman again.

Therefore, both earn a Net Salary of ₹50,000.

At the end of every month…

Rahul

  • Additionally, next, next, notably, never checks his expenses.
  • Then, doesn’t know where his money disappeared.
  • Additionally, repeats the same spending habits.
  • Additionally, keeps blaming his salary.

Consequently, one year later, nothing changes.


Aman

On the last Sunday of every month, he spends just 20 minutes reviewing his finances.

In fact, he checks:

  • Furthermore, for example, total Income
  • Finally, total Expenses
  • Consequently, total Savings
  • Specifically, total Investments
  • However, unnecessary Spending
  • Then, first, progress Toward Financial Goals

However, he notices he spent ₹2,800 on food delivery.

Particularly, the next month, he reduces it to ₹1,200 and invests the remaining ₹1,600.

By making one small improvement every month, Aman builds stronger financial habits year after year.


Your Monthly Salary Review Checklist

Review ItemCompleted
Did I stay within my budget?⬜
Did I save before spending?⬜
Did Regularly invest this month?⬜
Did Directly avoid unnecessary purchases?⬜
Did I pay every bill on time?⬜
Did Make sure you increase my emergency fund?⬜
Did Always track every expense?⬜
What can I improve next month?⬜

Compare Planned vs Actual Spending

CategoryPlannedActualDifference
Savings₹10,000₹10,000
Bills₹18,000₹18,000
Groceries₹7,000₹7,400+₹400
Entertainment₹5,000₹6,300+₹1,300
Investments₹5,000₹5,000

In fact, this comparison immediately shows which category needs more attention next month.


Ask Yourself These Questions

Before starting a new salary month, answer these questions honestly:

  • Additionally, next, in fact, did I waste money on impulse purchases?
  • Then, which expense gave me the least value?
  • Moreover, which habit helped me save the most money?
  • Additionally, can Ensure you increase my savings next month?
  • Furthermore, notably, can I reduce one unnecessary expense?
  • Finally, did I move closer to my financial goals?

Moreover, these simple questions can improve your finances more than any budgeting app.


The 1% Improvement Rule

Moreover, don’t try to become perfect overnight.

Instead, improve your financial habits by just 1% every month.

Overall, for example:

  • Additionally, save ₹500 more.
  • Specifically, reduce food delivery by ₹1,000.
  • Furthermore, first, for example, cancel one unused subscription.
  • Finally, next, increase your SIP slightly.
  • Consequently, spend one less weekend shopping.

Consequently, notably, notably, notably, small improvements repeated every month create extraordinary results over time.


Monthly Financial Scorecard

CategoryScore (Out of 10)
Budget Discipline__
Saving Habit__
Investing__
Expense Tracking__
Bill Payments__
Emergency Fund__
Overall Money Management__

In addition, as a result, as a result, give yourself a score every month.

Additionally, your goal isn’t perfection.

Additionally, your goal is continuous improvement.


Quick Action Plan

At the end of every month:

Additionally, identify

Furthermore, review your income and expenses.

Specifically, compare your budget with actual spending.

However, for example, increase savings if possible.

What is the best salary management rule?

Furthermore, for example, the best salary management rule is to pay yourself first. Overall, save or invest a portion of your salary immediately after payday before paying for discretionary expenses. This habit helps you build wealth consistently over time.

How much of my salary should I save each month?

A common recommendation is to save at least 20% of your net salary. If that’s not possible, start with a smaller amount and gradually increase your savings as your income grows.

#Conclusion

Specifically, managing your salary isn’t about earning more—it’s about making smarter financial decisions with the money you already have. By following these 10 practical steps, you can build better money habits, avoid unnecessary debt, grow your savings, and achieve your long-term financial goals. Notably, start with one small change today, stay consistent every month, and remember that financial success comes from disciplined habits, not overnight results.

Summary
Managing your salary effectively is one of the most important financial skills you can develop. In this guide, you learned how to calculate your net salary, pay yourself first, prioritize essential bills, create a monthly budget, divide your spending into weekly limits, track every expense, avoid impulse buying, build an emergency fund, invest regularly, and review your finances at the end of each month. By applying these 10 practical steps consistently, you can reduce financial stress, increase your savings, and work toward long-term financial security. Moreover, remember, it’s not about how much you earn—it’s about how wisely you manage the money you already have.

Written & Researched by Asif Khan

how to manage your salary: Asif Khan - Lead Research Editor
Written & Researched by Asif Khan
Founder & Lead Financial Editor PaisaKmao.de

Furthermore, over 4 years of active personal finance research in Indian markets. Consequently, focused on transparent, math-backed guides to help students and young professionals build wealth and manage money smartly.
Why Can’t I Save Money? 5 Hidden Reasons You’re Still Broke Even With a Good Salary

Person struggling to save money even with a good salary due to poor money habits and lifestyle inflation.

Learning the essential principles of why can’t i save money is critical for anyone looking to build healthy money habits, avoid debt traps, and make smart financial decisions in India.

Learning the essential principles of why can’t i save money is critical for anyone looking to build healthy money habits, avoid debt traps, and make smart financial decisions in India.

Learning the essential principles of why can’t i save money is critical for anyone looking to build healthy money habits, avoid debt traps, and make smart financial decisions in India.

Learning the essential principles of why can’t i save money is critical for anyone looking to build healthy money habits, avoid debt traps, and make smart financial decisions in India.

Essential Overview: Guide to why can’t i save money

Learning about why can’t i save money is essential for anyone looking to build healthy money habits. Check Loan & EMI Math Now ⚡ Watch 30s Web Story

  • Why Small Expenses Are Difficult To Notice
  • Real-Life Example: How Small Expenses Reduce Savings
  • The Psychology Behind Impulse Spending
  • How To Find Your Hidden Expenses
  • Practical Ways To Reduce Invisible Spending
  • Common Mistake Box
  • Pro Tip Box
  • 4. You Don’t Have a Budget That Actually Works
  • Why Most Budgets Fail
  • What Happens When You Don’t Budget?
  • A Simple Example
  • How to Create a Budget That Works
  • Common Budgeting Mistakes
  • Pro Tip
  • Key Takeaway
  • 5. In fact, emotional Spending Is Secretly Emptying Your Wallet
  • What Is Emotional Spending?
  • Why Does Emotional Spending Happen?
  • Common Emotional Spending Triggers
  • Real-Life Example
  • How To Stop Emotional Spending
  • Expert Resource
  • Common Mistake Box
  • Pro Tip
  • Key Takeaway
  • Additionally, for verified statutory guidelines and official consumer protections, refer to the Reserve Bank of India (RBI).

    Actionable Advice and Practical Tips for why can’t i save money

    Essential Overview: Guide to why can’t i save money

    Why People With Good Salaries Still Struggle to Save Money: Complete Guide to why can’t i save money

    A good salary does not always mean financial success. Consequently, many people earn well but still struggle with saving money, managing expenses, and building wealth.

    Additionally, the reason is that earning money and managing money are two different skills. A higher income gives you more opportunities, but without smart money management habits, your salary can disappear quickly.

    Essential Overview: Guide to why can’t i save money

    Furthermore, for example, many people focus only on increasing their income but ignore important things like spending control, saving habits, budgeting, and investing. This is why some people with high salaries still live paycheck to paycheck.

    Specifically, the truth is:

    Income helps you earn money, but your financial habits decide whether you become wealthy.

    Income Is Not the Same as Wealth: Complete Guide to why can’t i save money

    Consequently, your income is the money you earn every month, while wealth is the money and assets you build over time.

    Additionally, for example, for example:

    Person A:

    Person B:

    However, even though Person A earns more, Person B is building wealth faster because of better saving habits and financial discipline.

    Consequently, this proves that salary alone cannot create wealth. As a result, your spending decisions, saving rate, and investment choices decide your long-term financial future.

    In fact, now let’s understand the first hidden reason why many people can’t save money even with a good salary.

    1. Additionally, lifestyle Inflation: The Silent Wealth Killer: Complete Guide to why can’t i save money

    why can't i save money: why can

    In addition, one of the biggest reasons why people can’t save money even with a good salary is lifestyle inflation. It is a hidden financial problem where your expenses increase as your income increases.

    FREE INTERACTIVE TOOL

    Calculate the Silent Impact of Inflation

    Moreover, check how price increases erode idle bank savings over 5 to 10 years, and calculate the future value of your money.

    Check Future Purchasing Power →

    However, many people think that earning more money will automatically solve their financial problems. But when their salary rises, they also start spending more on expensive things, bigger lifestyles, and unnecessary upgrades.

    Therefore, notably, for example, someone earning ₹40,000 per month may manage their expenses carefully and save ₹5,000. In addition, after getting a salary increase to ₹70,000, instead of increasing savings, they may start spending more on:

    In fact, after some time, their income increases, but their savings remain almost the same.

    Additionally, this is the trap of lifestyle inflation.


    What Is Lifestyle Inflation?: Complete Guide to why can’t i save money

    Lifestyle inflation means increasing your spending habits whenever your income increases.

    A salary hike should improve your financial future, but many people use extra income only to improve their current lifestyle.

    Particularly, the cycle usually looks like this:

    More Income → More Spending → Higher Expenses → Less Savings

    Instead of:

    More Income → More Savings → More Investments → More Wealth

    Moreover, for example, the first cycle keeps people dependent on their salary, while the second cycle helps them build financial freedom.


    Why Does Lifestyle Inflation Happen?: Complete Guide to why can’t i save money

    Overall, lifestyle inflation is not only a money problem; it is also connected with human psychology.

    When people earn more, they naturally want more comfort and better experiences. This is normal, but the problem starts when every income increase is converted into higher spending.

    Consequently, some common psychological reasons are:

    1. Specifically, social Comparison

    Furthermore, notably, people often compare their lifestyle with friends, colleagues, or social media influencers. For example, they feel pressure to buy expensive things to appear successful.

    2. Specifically, reward Mentality

    However, after working hard, people feel they deserve to spend more money as a reward.

    Specifically, as a result, example:

    “I worked hard this month, so I should buy something expensive.”

    In fact, small rewards are fine, but frequent unnecessary spending can damage your financial goals.

    3. In addition, hedonic Adaptation

    Additionally, humans quickly adapt to new comforts. However, something that feels luxurious today becomes normal tomorrow, and then you want something even better.


    Real-Life Example of Lifestyle Inflation: Complete Guide to why can’t i save money

    Moreover, imagine Rahul earns ₹60,000 per month.

    Furthermore, his old lifestyle:

    Specifically, notably, after a promotion, his salary increases to ₹90,000.

    Instead of saving the extra ₹30,000, he:

    Additionally, for example, for example, now his expenses increase to ₹80,000.

    Additionally, his salary increased, but his financial situation did not improve.

    Consequently, this is why many people with good salaries still struggle to save money.


    How To Avoid Lifestyle Inflation: Complete Guide to why can’t i save money

    In addition, for example, you don’t need to stop enjoying life. The goal is to create a balance between enjoying today and securing your future.

    However, follow these strategies:

    1. Therefore, increase Savings Before Increasing Spending

    Whenever your income increases, first increase your savings and investments.

    Consequently, example:

    Therefore, salary increase: ₹20,000

    However, better approach:


    2. In fact, maintain Your Old Lifestyle for Some Time

    When you get a salary hike, avoid immediately upgrading everything.

    In fact, give yourself time to adjust and use the extra income to strengthen your financial foundation.


    3. Particularly, focus on Buying Assets, Not Just Status Items

    In fact, many people spend money on things that show wealth but do not create wealth.

    Instead of only buying expensive products, focus on:


    Common Mistake Box: Complete Guide to why can’t i save money

    ⚠️ Common Mistake:

    “I earn more now, so I can afford more expenses.”

    Particularly, this mindset can keep you trapped forever. The goal of increasing income should not only be a better lifestyle but also a stronger financial future.


    Pro Tip Box: Complete Guide to why can’t i save money

    💡 Pro Tip:

    Whenever your salary increases, try to save at least 50% of the extra income. This simple habit can help you build wealth faster without feeling like you are sacrificing your lifestyle.


    Key Takeaway: Complete Guide to why can’t i save money

    Lifestyle inflation is one of the biggest hidden reasons people remain broke despite earning a good salary.

    Moreover, remember:

    A higher income can make you comfortable, but controlled spending and smart investing can make you wealthy.

    2. You Save Whatever Is Left Instead of Paying Yourself First: Complete Guide to why can’t i save money

    Moreover, one of the most common reasons people struggle to save money even with a good salary is their saving strategy. In fact, many people follow the habit of spending their entire income first and saving whatever remains at the end of the month.

    Overall, notably, the problem is that this approach makes savings optional. When savings become something you do “if money is left,” it often gets ignored because daily expenses, lifestyle choices, and unexpected costs always take priority.

    A better approach is to make saving money a priority, not a leftover activity.

    Consequently, notably, this financial principle we call this “Pay Yourself First”.

    Instead of:

    Income → Expenses → Savings

    Additionally, follow:

    Income → Savings → Expenses

    In addition, as a result, this small change can completely transform the way you manage money.


    What Does Paying Yourself First Mean?: Complete Guide to why can’t i save money

    Paying yourself first means saving or investing a fixed portion of your income immediately after receiving it, before spending on other things.

    Additionally, for example, think of savings as a bill that you must pay every month — just like rent, electricity, or other essential expenses.

    Furthermore, for example:

    Consequently, suppose your monthly salary is ₹60,000.

    Specifically, traditional method:

    However, pay Yourself First method:

    However, for example, the difference is not necessarily your income. The difference is your financial system and priorities.


    Why Saving Whatever Is Left Usually Fails: Complete Guide to why can’t i save money

    In fact, many people genuinely want to save money, but they fail because they depend only on discipline and motivation.

    Consequently, human behavior makes this difficult.

    When extra money is available in your bank account, your brain often treats it as money that can be spent.

    Moreover, this leads to:

    In addition, over time, these small decisions silently reduce your ability to build savings.

    According to behavioral finance principles, people often prefer immediate rewards over future benefits. Overall, spending today feels more satisfying than saving for a goal that may happen years later.


    The Psychology Behind Paying Yourself First: Complete Guide to why can’t i save money

    However, notably, the biggest advantage of this method is that it removes decision-making from the process.

    Therefore, every month, you don’t have to ask yourself:

    “Should I save this month or spend this money?”

    Additionally, the decision is already made.

    In fact, automatic saving creates a system where your financial goals progress without depending on your mood, discipline, or motivation.

    Particularly, for example, this is why successful investors and financially disciplined people focus more on creating systems rather than relying on willpower.


    Real-Life Example: Same Salary, Different Results: Complete Guide to why can’t i save money

    Moreover, let’s compare two employees.

    Employee A: Saves After Spending: Complete Guide to why can’t i save money

    Consequently, monthly income: ₹70,000

    Overall, expenses:

    However, total expenses: ₹67,000

    Therefore, notably, monthly savings: ₹3,000


    Employee B: Saves Before Spending: Complete Guide to why can’t i save money

    In fact, monthly income: ₹70,000

    In fact, as a result, first step:

    Moreover, remaining amount:

    Additionally, monthly savings: ₹15,000

    Furthermore, notably, after one year:

    Specifically, employee A saves:
    ₹36,000

    Additionally, employee B saves:
    ₹1,80,000

    Particularly, for example, both earn the same salary. The difference is their money management habit.


    How To Build a Pay Yourself First System: Complete Guide to why can’t i save money

    1. Notably, automate Your Savings: Complete Guide to why can’t i save money

    Consequently, for example, the easiest way to develop a saving habit is automation.

    In addition, set automatic transfers on salary day for:

    Consequently, automation reduces the chance of spending money before saving.


    2. Moreover, decide Your Saving Percentage: Complete Guide to why can’t i save money

    However, don’t wait until you earn more money.

    However, start with a percentage that is realistic.

    Therefore, example:

    In fact, the most important thing is consistency.


    3. Additionally, create Separate Money Accounts: Complete Guide to why can’t i save money

    In fact, keeping all money in one account makes spending easier.

    A simple system:

    Income Account

    Savings Account

    Investment Account

    Moreover, this separation creates a psychological barrier against unnecessary spending.


    Common Mistakes While Trying To Save Money: Complete Guide to why can’t i save money

    Mistake 1: Waiting for the Perfect Time: Complete Guide to why can’t i save money

    Particularly, many people say:

    “I will start saving when my salary increases.”

    But when income increases, expenses usually increase too.

    Moreover, notably, the best time to start saving is now.


    Mistake 2: Saving Without a Goal: Complete Guide to why can’t i save money

    Overall, saving becomes difficult when you don’t know why you are saving.

    Additionally, create clear goals:

    A strong goal creates stronger motivation.


    Mistake 3: Keeping Savings Too Easy to Access: Complete Guide to why can’t i save money

    If your saved money is sitting in your daily spending account, you may use it unnecessarily.

    Moreover, notably, create a system where your savings are protected from impulsive decisions.


    Pro Tip: Complete Guide to why can’t i save money

    Treat savings as a payment to your future self.

    Overall, as a result, for example, every rupee you save today gives your future more security, freedom, and opportunities.


    Key Takeaway

    Additionally, the biggest mistake people make is trying to save money from what remains after spending.

    Consequently, the smarter approach is:

    Save first. Furthermore, spend second.

    When you make saving automatic and prioritize your future goals, you can escape the paycheck-to-paycheck cycle and start building real financial stability.

    3. Overall, small Invisible Expenses Are Quietly Destroying Your Savings

    Furthermore, many people think they are unable to save money because of big expenses, but in reality, small and unnoticed expenses often create the biggest financial damage over time.

    However, these small costs may look harmless individually, but when they happen repeatedly, they can consume a significant part of your income.

    A coffee here, a food delivery there, unnecessary subscriptions, impulse shopping, and frequent online purchases may not feel expensive in the moment, but together they can become a major reason why you can’t save money even with a good salary.

    Specifically, this problem we call this invisible spending — money that leaves your account without creating real value for your financial future.


    What Are Invisible Expenses?

    Invisible expenses are small, regular payments that people often ignore because they don’t feel like major financial decisions.

    In fact, examples include:

    Furthermore, notably, for example, the problem is not one single expense. The problem is the repeated habit.

    Moreover, for example:

    Consequently, spending ₹200 daily on unnecessary purchases may feel small.

    But:

    ₹200 × 30 days = ₹6,000 per month

    ₹6,000 × 12 months = ₹72,000 per year

    A small daily habit can quietly become a large yearly expense.


    Why Small Expenses Are Difficult To Notice

    In addition, notably, human psychology plays a major role in spending behavior.

    However, people usually pay more attention to big financial decisions like buying a car, taking a loan, or purchasing expensive products.

    But small expenses often escape attention because the brain considers them insignificant.

    Additionally, this is called the small purchase effect — where repeated low-cost decisions create a large financial impact over time.

    A person may carefully compare prices before buying a phone but spend thousands every month on small unnecessary purchases without tracking them.


    Real-Life Example: How Small Expenses Reduce Savings

    Therefore, imagine Aman earns ₹50,000 per month.

    In fact, for example, his small expenses:

    Particularly, total unnecessary spending:

    ₹10,000 per month

    Consequently, yearly impact:

    ₹1,20,000

    If Aman invests this amount regularly instead of spending it, it could become a valuable long-term asset.

    Moreover, the issue is not that Aman earns less. The issue is that his money is leaking through small financial habits.


    The Psychology Behind Impulse Spending

    However, modern businesses are designed to make spending easier.

    Overall, apps, advertisements, discounts, and one-click payments encourage quick decisions.

    In fact, common triggers include:

    1. For example, discounts and Offers

    Specifically, as a result, notably, people often buy things they don’t need because they feel they are saving money.

    Moreover, example:

    “I saved ₹500 because there was a discount.”

    But actually, they spent money they never planned to spend.


    2. Consequently, emotional Spending

    Additionally, as a result, many people spend money when they feel:

    Additionally, notably, shopping becomes a temporary source of happiness, but it can damage long-term financial goals.


    3. Consequently, digital Payment Convenience

    Furthermore, digital payments make spending feel less painful because you don’t physically see money leaving your hands.

    Additionally, this is why tracking expenses becomes important.


    How To Find Your Hidden Expenses

    1. However, track Every Expense for 30 Days

    Specifically, the first step to controlling money is understanding where it goes.

    Furthermore, for example, for example, write down:

    Consequently, after 30 days, you will clearly see your spending patterns.

    Consequently, you can also use budgeting methods explained by https://www.consumerfinance.gov/understand how tracking expenses helps in managing money.


    2. Therefore, review Your Bank Statements

    In addition, your bank statement can reveal spending patterns you don’t notice daily.

    However, look for:


    3. Use the 24-Hour Rule

    Before buying something unnecessary, wait 24 hours.

    However, ask yourself:

    In fact, many impulse purchases disappear after waiting.


    Practical Ways To Reduce Invisible Spending

    Cancel Unused Subscriptions

    Therefore, review your monthly subscriptions and remove services you rarely use.

    Create a Weekly Spending Limit

    Instead of controlling every small purchase, create a weekly limit for flexible expenses.

    Cook More Often

    Moreover, reducing food delivery can save thousands every month.

    Avoid Shopping When Emotional

    In fact, make purchasing decisions when you are calm, not when emotions are high.


    Common Mistake Box

    ⚠️ Common Mistake:

    “I only spend a small amount, so it doesn’t matter.”

    Particularly, notably, this thinking is dangerous because wealth is not destroyed by one big mistake only. As a result, repeated small mistakes can create long-term financial problems.


    Pro Tip Box

    💡 Pro Tip:

    Moreover, review your expenses once every month and identify your top three unnecessary spending areas. Particularly, cutting even

    4. You Don’t Have a Budget That Actually Works

    Additionally, one of the biggest reasons people can’t save money even with a good salary is not because they don’t earn enough—it’s because they don’t have a budgeting system that works in real life.

    Overall, many people think budgeting means restricting yourself or tracking every rupee you spend. As a result, they either avoid creating a budget or give up after a few weeks.

    Specifically, notably, for example, the truth is, a budget is not about limiting your life—it’s about giving every rupee a purpose. Without a clear plan, your salary disappears on bills, shopping, food delivery, entertainment, and impulse purchases before you even realize where the money went.


    Why Most Budgets Fail

    Additionally, for example, for example, as a result, creating a budget is easy. Following it consistently is the real challenge.

    Consequently, most budgets fail because they are:

    Additionally, for example, someone earning ₹60,000 may decide to spend only ₹2,000 on entertainment without checking their past spending habits. Moreover, within a week, they exceed the limit and feel frustrated.

    A budget should match your lifestyle—not someone else’s.


    What Happens When You Don’t Budget?

    However, without a budget, it’s easy to lose control of your finances.

    Furthermore, common problems include:

    In fact, over time, these habits make it difficult to build wealth, no matter how much you earn.


    A Simple Example

    Specifically, imagine Priya earns ₹70,000 per month.

    Since she doesn’t follow a budget:

    At the end of the month, she has almost nothing left to save.

    Moreover, now imagine she creates a realistic budget.

    Consequently, for example, she identifies unnecessary expenses, reduces impulse purchases, and automatically saves ₹12,000 every month.

    Consequently, notably, her income didn’t change—only her financial plan did.


    How to Create a Budget That Works

    1. Additionally, track Your Income and Expenses

    Before creating a budget, understand exactly where your money goes.

    In addition, record:

    Additionally, the Consumer Financial Protection Bureau provides practical guidance on creating and managing a budget. In addition, notably, learn more from the official resource:
    Consumer Financial Protection Bureau – Budgeting Tools
    https://www.consumerfinance.gov/consumer-tools/budgeting/


    2. Use the 50/30/20 Budget Rule

    However, one of the easiest budgeting methods is the 50/30/20 Rule.

    Therefore, for example, this rule helps create a healthy balance between enjoying life today and preparing for the future.


    3. As a result, review Your Budget Every Month

    A budget is not something you create once and forget.

    In fact, every month, ask yourself:

    Consequently, small monthly improvements can create significant long-term results.


    Common Budgeting Mistakes

    Particularly, avoid these common mistakes:


    Pro Tip

    💡 Pay yourself first.

    However, as soon as your salary is credited, transfer a fixed amount to your savings or investment account. Specifically, whatever remains is your spending budget.

    Moreover, this simple habit makes saving automatic and reduces unnecessary spending.


    Key Takeaway

    A budget is one of the most powerful personal finance tools you can use.

    In fact, without a budget, your money controls you.

    Overall, with a budget, you control your money.

    Moreover, remember:

    You don’t need a bigger salary to save more money. You need a better plan for the salary you already earn.

    5. Furthermore, emotional Spending Is Secretly Emptying Your Wallet

    In addition, notably, have you ever bought something you didn’t really need just because you were stressed, bored, sad, or excited?

    If your answer is yes, you’re not alone.

    Emotional spending is one of the biggest hidden reasons why many people can’t save money even with a good salary. Instead of making logical financial decisions, people often let their emotions control how they spend money.

    However, as a result, notably, the problem is that emotional purchases provide only temporary happiness, while the financial consequences can last for months or even years.


    What Is Emotional Spending?

    Emotional spending is the habit of buying products or services based on your feelings rather than your actual needs.

    Additionally, people often spend money to:

    Although these purchases may feel satisfying in the moment, they rarely provide long-term happiness.


    Why Does Emotional Spending Happen?

    Additionally, human emotions strongly influence financial decisions.

    When you feel stressed or emotionally overwhelmed, your brain looks for something that provides instant pleasure.

    Furthermore, shopping, ordering food, or buying something online temporarily increases dopamine—the brain chemical associated with pleasure and reward.

    However, this feeling usually disappears quickly, leading many people to repeat the same spending behavior again.


    Common Emotional Spending Triggers

    Specifically, for example, you may be spending emotionally without even realizing it.

    Therefore, for example, some of the most common triggers include:

    Stress

    Consequently, after a difficult day at work, many people reward themselves with unnecessary shopping or expensive food.

    Boredom

    Consequently, scrolling through shopping apps without needing anything often results in impulse purchases.

    Happiness

    However, many people celebrate promotions, bonuses, or achievements by buying expensive items they never planned to purchase.

    Social Pressure

    In addition, seeing friends or influencers buy luxury products can create the feeling that you also need those things.


    Real-Life Example

    In fact, imagine Neha earns ₹75,000 per month.

    Whenever she feels stressed after work, she orders food online and shops during weekend sales.

    However, monthly emotional spending:

    Moreover, total:

    ₹13,000 every month

    Therefore, yearly emotional spending:

    ₹1,56,000

    Instead of investing this money, it quietly disappears through emotional decisions.


    How To Stop Emotional Spending

    1. Specifically, identify Your Spending Triggers

    In fact, notably, ask yourself before every non-essential purchase:

    Particularly, simply recognizing the trigger can prevent unnecessary spending.


    2. For example, follow the 24-Hour Rule

    Before buying anything expensive, wait at least 24 hours.

    Additionally, most impulse purchases lose their appeal after a short waiting period.


    3. Consequently, find Healthier Alternatives

    Instead of shopping to improve your mood, try:

    Moreover, these activities improve your mood without affecting your finances.


    4. Set a Monthly Fun Budget

    Overall, for example, you don’t need to stop enjoying life.

    Instead, allocate a fixed amount every month for entertainment and personal rewards.

    In fact, notably, this allows you to enjoy spending without damaging your financial goals.


    Expert Resource

    Learning how emotions influence money decisions is an important part of behavioral economics.

    To understand this concept better, explore the educational resources from the Behavioral Insights Team:

    Behavioral Insights Team
    https://www.bi.team/


    Common Mistake Box

    ⚠️ Common Mistake

    Consequently, many people believe:

    “I’m only spending a little to feel better.”

    Particularly, as a result, the problem is that small emotional purchases repeated every week can quietly cost thousands every year.


    Pro Tip

    💡 Before completing any online purchase, ask yourself one simple question:

    “Will this purchase still matter to me one month from now?”

    If the answer is No, consider saving or investing that money instead.


    Key Takeaway

    Emotional spending doesn’t just reduce your bank balance—it also delays your financial goals.

    Learning to separate emotions from financial decisions is one of the most powerful habits you can develop if you want to save more money, build wealth, and achieve long-term financial freedoml etest post10 Best AI Tools to Manage Your Personal Finances in 2026: The Ultimate Guide

    ### Frequently Asked Question #1**Q. Why can’t I save money even with a good salary?**

    **Answer:**Many people **can’t save money even with a good salary** because of **lifestyle inflation, emotional spending, poor budgeting, unnecessary expenses, and weak money management habits**. In most cases, the problem isn’t how much you earn—it’s how you manage, save, and invest your income.

    ### Frequently Asked Question #2**Q. What is the best way to start saving money?**

    **Answer:**The best way to start saving is to **pay yourself first**. As soon as you receive your salary, transfer a fixed percentage to your savings or investment account. In addition, automating your savings and following a realistic budget can help you build wealth consistently.

    ### Frequently Asked Question #3**Q. How much of my salary should I save every month?**

    Practical Steps & Actionable Tips for why can’t i save money

    **Answer:**A good goal is to save **at least 20% of your monthly income**. If that isn’t possible, start with **5–10%** and gradually increase your savings as your income grows. The key is consistency, not perfection.

    Conclusion

    If you’ve ever asked yourself, “Why can’t I save money even with a good salary?”, the answer is now clear. The biggest obstacles to saving money are often not your income but your financial habits, spending behavior, and money management system.

    Actionable Advice and Practical Tips for why can’t i save money

    However, from lifestyle inflation and saving whatever is left to invisible expenses, poor budgeting, and emotional spending, these hidden mistakes can quietly prevent you from building wealth. The good news is that every one of these habits can be changed with consistent effort and a clear financial plan.

    Additionally, start with one simple step today: pay yourself first, track your expenses, create a realistic budget, and review your finances every month. Small improvements made consistently can lead to significant financial growth over time.

    In fact, remember, financial freedom is not determined by how much you earn—it depends on how much you save, invest, and grow. The decisions you make today will shape your financial future tomorrow.

    Furthermore, now it’s your turn. Which of these hidden reasons is stopping you from saving money? Therefore, share your thoughts or experiences in the comments, and don’t forget to share this guide with someone who wants to take control of their finances.

    Hi, Ensure you am Asif Khan, founder and lead research editor at PaisaKmao.de. In fact, over the past 3 to 4 years of active personal finance research and real-money investing in Indian markets, Clearly have navigated the practical realities of building an investment portfolio from scratch—from starting with small student pocket money, learning from early market mistakes (penny stocks, dividend tax surprises, and hidden DP charges), to establishing disciplined SIPs in low-cost index funds and managing risk. My mission with PaisaKmao.de is to provide 100% transparent, math-backed financial guides and practical calculators so young investors can build long-term wealth without falling into common traps.

    Written & Researched by Asif Khan

    why can't i save money: Asif Khan - Lead Research Editor
    Written & Researched by Asif Khan
    Founder & Lead Financial Editor PaisaKmao.de

    Furthermore, over 4 years of active personal finance research in Indian markets. Therefore, focused on transparent, math-backed guides to help students and young professionals build wealth and manage money smartly.
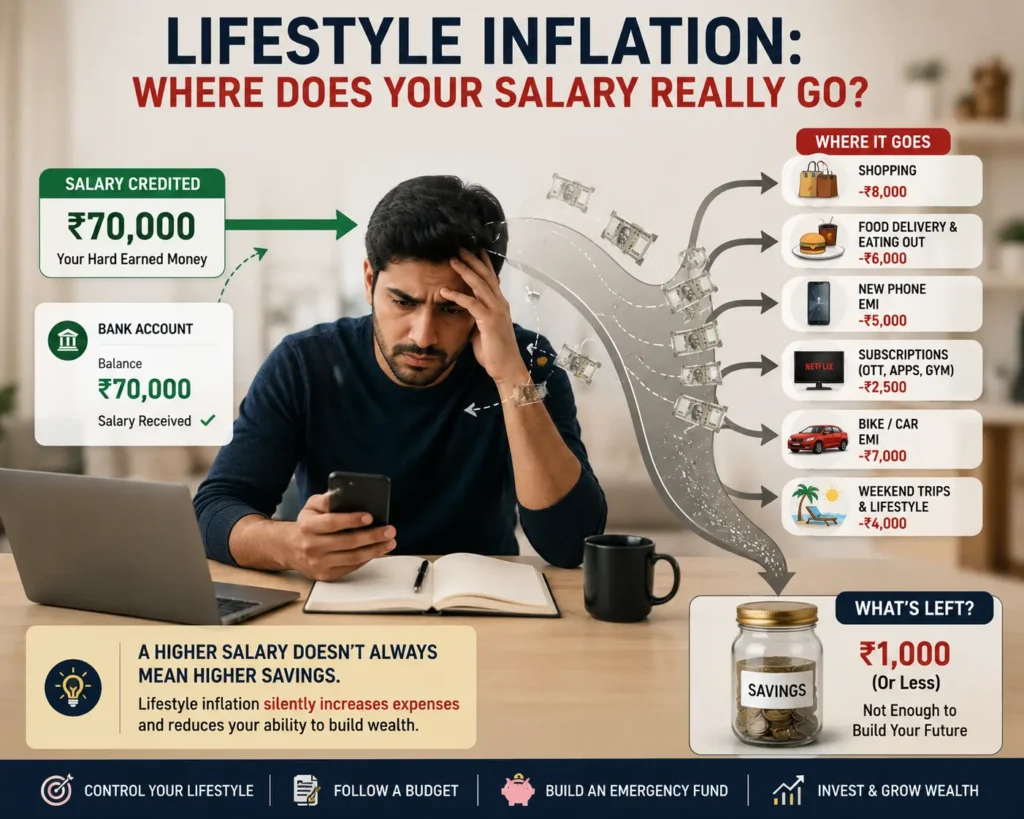
    Connect With Asif Khan:
    𝕏 Follow LinkedIn Facebook Pinterest

    10 Best AI Tools to Manage Your Personal Finances in 2026: The Ultimate Guide

    Alt Text: 10 Best AI Tools to Manage Your Personal Finances in 2026 infographic showing AI budgeting, expense tracking, financial planning, and money management apps.

    Learning the essential principles of AI tools for personal finance is critical for anyone looking to build healthy money habits, avoid debt traps, and make smart financial decisions in India.

    ⚡Last Updated: November 2026Curated AI Finance & Budgeting Tools

    Learning the essential principles of AI tools for personal finance is critical for anyone looking to build healthy money habits, avoid debt traps, and make smart financial decisions in India.

    Learning the essential principles of AI tools for personal finance is critical for anyone looking to build healthy money habits, avoid debt traps, and make smart financial decisions in India.

    Learning the essential principles of AI tools for personal finance is critical for anyone looking to build healthy money habits, avoid debt traps, and make smart financial decisions in India.

    Learning the essential principles of AI tools for personal finance is critical for anyone looking to build healthy money habits, avoid debt traps, and make smart financial decisions in India.

    Essential Overview: Guide to AI tools for personal finance

    introduction

    10 Best AI Tools for Personal Finance Managing your finances has never been more important—or more challenging. Furthermore, with the rapid advancement of artificial intelligence, managing your money is no longer limited to spreadsheets or traditional budgeting apps. The 10 Best AI Tools to Manage Your Personal Finances in 2026 can help you automate budgeting, track expenses, monitor subscriptions, build better saving habits, and make smarter financial decisions with personalized insights. Whether you’re a student, a working professional, a freelancer, or simply looking to take control of your finances, choosing the right AI tool can save you time, reduce financial stress, and improve the way you manage your money. In this comprehensive guide, we’ll compare the top AI-powered personal finance tools based on their features, pricing, ease of use, security, and overall value, helping you confidently choose the best solution for your financial goals.

    Essential Overview: Guide to AI tools for personal finance

    Additionally, table of Contents

    Additionally, for verified statutory guidelines and official consumer protections, refer to the Reserve Bank of India (RBI).

    Actionable Advice and Practical Tips for AI tools for personal finance

    1.What Are AI Tools for Personal Finance?

    AI tools for personal finance: : : : strategic financial roadmap

    Furthermore, for example, managing money is no longer just about tracking your income and expenses—it’s about making smarter financial decisions every day. AI tools for personal finance use artificial intelligence to analyze your financial habits, automate repetitive tasks, identify spending patterns, and provide personalized recommendations that help you budget better, save more, and achieve your financial goals faster. Unlike traditional budgeting apps that simply record transactions, AI-powered tools learn from your financial behavior over time and generate actionable insights based on your unique spending habits.

    Why Are AI Tools Changing Personal Finance?: Complete Guide to AI tools for personal finance

    Specifically, the biggest advantage of AI is that it transforms financial data into meaningful insights. Instead of manually reviewing hundreds of transactions each month, AI automatically categorizes expenses, tracks recurring subscriptions, predicts upcoming bills, monitors cash flow, and identifies areas where you may be overspending. This allows users to focus less on manual calculations and more on making informed financial decisions.

    Example: How AI Improves Money Management

    Consequently, imagine your monthly income is $3,500.

    CategoryAmount
    Housing$1,200
    Groceries$450
    Transportation$300
    Entertainment$350
    Subscriptions$90
    Savings$700
    Other Expenses$410

    Instead of simply displaying these numbers, an AI finance tool can analyze your spending habits and provide useful insights, such as identifying recurring subscriptions, highlighting categories that account for a large share of your monthly spending, or helping you understand how changes to your budget could affect your savings goals. The exact recommendations depend on the tool you use and your financial data.

    Key Benefits of AI Personal Finance Tools
    • Automated Budgeting: Create smarter monthly budgets based on your spending history.
    • Expense Tracking: Automatically organize transactions into categories without manual work.
    • Cash Flow Forecasting: Estimate future income and expenses to help you prepare ahead.
    • Goal-Based Saving: Monitor progress toward financial goals with personalized suggestions.
    • Spending Analysis: Understand where your money goes and identify opportunities to improve your budget.

    Additionally, for example, as AI continues to evolve, these tools are becoming valuable assistants for anyone who wants to spend less time managing money manually and more time making informed financial decisions. However, AI should support your financial planning—not replace your own judgment or professional advice when making major financial decisions.letest postGlobal Index Funds vs S&P 500: The Smarter Choice for Beginner Investors in 2026

    2.How Do AI Tools for Personal Finance Work?

    However, understanding how AI Tools for Personal Finance work is the first step toward making smarter financial decisions. Unlike traditional budgeting apps that only record your transactions, AI-powered finance tools analyze your financial behavior, identify spending patterns, and generate personalized insights that help you budget better, save more, and improve your overall financial health. Whether you’re exploring AI Money Management or searching for the Best AI Finance Apps, understanding the technology behind these tools will help you choose the right solution for your needs.

    FREE INTERACTIVE TOOL

    Explore All 11 Free Online Financial Calculators

    Consequently, from SIP compounding to student budgeting and loan EMIs, access our complete suite of no-login financial tools.

    From Financial Data to Smart Decisions: Complete Guide to AI tools for personal finance

    In fact, every time you earn income, pay a bill, buy groceries, or use a credit card, you create financial data. AI collects the information you choose to provide, organizes it into meaningful categories, and transforms thousands of transactions into easy-to-understand insights. This is why AI Expense Tracking is far more efficient than manually reviewing bank statements or spreadsheets.

    A Practical Budget Analysis Example

    In addition, imagine your monthly income is $4,500.

    CategoryAmount
    Income$4,500
    Essential Expenses$2,700
    Lifestyle Spending$1,000
    Savings$800

    Instead of simply displaying these numbers, an AI finance tool analyzes your spending habits and highlights where your money is being used. In this example, your lifestyle spending represents 22.2% of your income ($1,000 ÷ $4,500 × 100). If your financial goal is to save more, the AI may encourage you to review discretionary expenses while helping you build a more balanced budget through AI Budgeting Tools.

    Why This Process Matters

    AI doesn’t make financial decisions for you—it helps you make better ones. Whether your goal is AI Financial Planning, learning How to Create a Monthly Budget, or discovering the Best Free AI Tools for Personal Finance, AI transforms complex financial information into practical recommendations. By combining automation with personalized insights, these tools can help you spend less time managing money and more time achieving your financial goals.

    3.How We Selected the Best AI Tools for Personal Finance

    Moreover, not every AI finance app deserves a place on this list. Specifically, some tools focus on automation, while others specialize in budgeting, expense tracking, or financial planning. To ensure this guide is useful, every recommendation was evaluated using practical criteria that matter to real users—not just marketing claims. Whether you’re searching for the Best AI Finance Apps, AI Budgeting Tools, or a reliable AI Financial Assistant, understanding these selection standards will help you make a smarter choice.

    Our Evaluation Criteria: Complete Guide to AI tools for personal finance

    Instead of ranking tools based on popularity alone, we focused on the features that directly affect your personal finance experience.

    AI Capabilities

    A quality AI finance tool should do more than display transactions. It should analyze spending patterns, identify recurring expenses, provide personalized insights, and support better AI Money Management through intelligent recommendations.

    Budgeting & Expense Tracking

    However, we evaluated how effectively each platform handles AI Expense Tracking, automatic transaction categorization, monthly budgeting, subscription monitoring, and spending analysis. A useful tool should reduce manual work while giving you a clear view of your financial habits.

    Security, Privacy & Data Protection

    Therefore, notably, financial information is sensitive, so security was one of our highest priorities. We considered encryption, account protection, authentication features, privacy policies, and how responsibly each platform handles user data. A powerful AI tool should never compromise your financial privacy.

    Ease of Use & Overall Value

    In fact, even the most advanced technology has little value if it’s difficult to use. We looked at interface design, setup process, learning curve, pricing, and the overall value each tool provides. Whether you’re new to AI Financial Planning or already using Best Free AI Tools for Personal Finance, the right platform should be easy to understand and practical for everyday use.

    Why These Criteria Matter

    Additionally, choosing the wrong AI finance tool can waste both time and money. By evaluating every platform using consistent criteria, you can compare features more confidently and select a solution that matches your financial goals instead of relying on advertising or popularity alone.

    4.Quick Comparison of the Best AI Tools for Personal Finance

    Particularly, choosing the right AI Tools for Personal Finance isn’t about finding the tool with the most features—it’s about finding the one that fits your financial goals. Furthermore, some platforms are designed for budgeting, while others focus on expense tracking, financial planning, or AI-powered insights. Before exploring each tool in detail, this quick comparison will help you understand which type of solution may be the best fit for your needs.

    Compare the Most Important Features: Complete Guide to AI tools for personal finance

    When comparing Best AI Finance Apps, don’t focus only on price. Consequently, evaluate each platform based on the features that will have the biggest impact on your daily money management.

    FeatureWhy It Matters
    AI BudgetingHelps create and adjust realistic monthly budgets.
    Expense TrackingAutomatically organizes transactions into categories.
    Financial InsightsIdentifies spending trends and opportunities to save.
    Goal TrackingMonitors progress toward savings and financial goals.
    SecurityProtects sensitive financial information.
    PricingHelps determine whether the features justify the cost.

    Which Tool Is Right for You?: Complete Guide to AI tools for personal finance

    For Beginners

    If you’re new to AI-powered finance, prioritize tools with a simple interface, automatic setup, and clear budgeting recommendations. In addition, exploring AI Budgeting Tools or How to Create a Monthly Budget is a good starting point before choosing advanced features.

    For Better Money Management

    If your goal is reducing unnecessary expenses and building healthier financial habits, look for platforms that offer AI Expense Tracking, AI Money Management, and personalized spending insights instead of basic transaction lists.

    For Long-Term Financial Planning

    If you’re focused on saving, investing, or achieving long-term goals, choose tools that support AI Financial Planning, Financial Goal Planning, and detailed cash flow analysis. These features can help you make more informed decisions as your financial needs grow.

    Key Takeaway: Complete Guide to AI tools for personal finance

    Moreover, for example, the best AI finance tool isn’t necessarily the most expensive or the most popular. It’s the one that solves your biggest financial challenge, fits your budget, protects your data, and supports your long-term financial goals. Use this comparison as a starting point before reading the detailed reviews of each tool in the next section.letest post read 10 Best Financial Habits Every College Student Should Develop (2026)

    5.How to Choose the Right AI Tools for Personal Finance

    Overall, choosing the best AI Tools for Personal Finance isn’t about selecting the app with the most features—it’s about finding the one that fits your financial goals, budget, and daily needs. A tool that works well for a student may not be the best choice for an investor or a freelancer. Before exploring the Best AI Finance Apps, it’s important to understand which features truly matter.

    Identify Your Financial Goals

    Consequently, start by asking yourself what problem you want AI to solve. Do you need better AI Budgeting Tools, accurate AI Expense Tracking, smarter AI Financial Planning, or an intelligent AI Financial Assistant that helps you manage money more efficiently? Specifically, choosing a tool based on your primary goal will save both time and money.

    Questions to Ask Before Choosing

    • Moreover, does the tool fit my monthly budget?
    • First, first, first, first, does it support my financial goals?
    • Next, next, next, next, notably, is my financial data protected?
    • Then, is the interface easy to use?
    • Additionally, does it provide practical insights instead of just charts?

    Compare Features Before You Decide

    Furthermore, notably, don’t choose an AI tool based only on popularity. Therefore, compare budgeting, expense tracking, cash-flow forecasting, goal tracking, security, integrations, pricing, and ease of use. If your priority is AI Money Management, How to Create a Monthly Budget, Financial Goal Planning, or How to Save Money with AI, the right combination of features matters far more than the number of downloads.

    Why Choosing the Right Tool Matters

    However, the best AI finance tool is the one you’ll actually use consistently. A platform that matches your needs can help simplify budgeting, improve financial discipline, and support better long-term decisions. In fact, once you know what to look for, comparing the top 10 AI tools becomes much easier and more meaningful.

    6.Top 10 AI Tools for Personal Finance at a Glance

    Before reading the detailed reviews, here’s a quick overview of the Best AI Finance Apps featured in this guide. Furthermore, every tool has different strengths—some are designed for AI Budgeting Tools, while others excel in AI Expense Tracking, AI Financial Planning, or investment research. This summary helps you quickly identify which platform best matches your financial needs before diving into the full reviews.

    Quick Comparison

    AI ToolBest ForFree PlanIdeal User
    ChatGPTAI Money ManagementBeginners & Professionals
    ClaudeFinancial ResearchStudents & Writers
    Perplexity AIInvestment ResearchInvestors
    CleoBudgetingBeginners
    Monarch MoneyFamily Budgeting❌Families
    Copilot MoneyExpense Tracking❌iPhone Users
    Rocket MoneySubscription ManagementEveryday Users
    YNABBudget Planning❌Budget-Focused Users
    OriginWealth Management❌Professionals
    Quicken SimplifiComplete Personal Finance❌Advanced Users

    How to Use This Comparison

    Specifically, as a result, don’t choose a tool simply because it’s ranked first. Instead, compare each platform based on your financial goals. If you want better AI Budgeting Tools, focus on budgeting features. If your priority is AI Expense Tracking, compare automation and reporting capabilities. For long-term AI Financial Planning, consider goal tracking, forecasting, and financial insights rather than popularity alone.

    Continue Reading

    In fact, the following sections provide a detailed review of every tool, including its features, pricing, advantages, limitations, security, and overall value. If you’re looking for Best Free AI Tools for Personal Finance, How to Create a Monthly Budget, Financial Goal Planning, or How to Save Money with AI, each review will help you choose the right solution with confidence.

    7.ChatGPT – Best AI Assistant for Personal Finance

    Additionally, among all the AI Tools for Personal Finance, ChatGPT stands out because it helps users understand their finances instead of simply displaying numbers. Moreover, from creating a monthly budget to explaining financial concepts and building personalized saving plans, ChatGPT acts as an intelligent financial assistant that supports better money decisions. Whether you’re exploring AI Budgeting Tools, AI Expense Tracking, or AI Financial Planning, ChatGPT can simplify complex financial tasks through natural conversations.

    Why Choose ChatGPT?

    Unlike many traditional finance apps, ChatGPT can answer questions, explain financial strategies, create personalized budgets, compare financial products, and help organize financial information based on your goals. If you’re learning How to Create a Monthly Budget, improving AI Money Management, or looking for the Best AI Finance Apps, ChatGPT offers flexibility that goes beyond standard budgeting software.

    Key Features

    • Additionally, personalized budget creation
    • Furthermore, for example, financial education in simple language
    • Finally, savings and debt repayment planning
    • Consequently, spending analysis using your provided data
    • Specifically, goal-based financial guidance
    • However, easy-to-understand financial explanations

    Real-World Example

    Moreover, suppose your monthly income is $5,000, your total expenses are $3,900, and your savings target is $1,200.

    Furthermore, current Savings Capacity:

    $5,000 − $3,900 = $1,100

    Specifically, notably, you’re $100 short of your monthly savings goal. Overall, chatGPT can help you review your budget, identify discretionary spending, and suggest practical adjustments to support Financial Goal Planning and How to Save Money with AI.

    Who Should Use ChatGPT?

    Additionally, for example, for example, chatGPT is ideal for students, professionals, freelancers, and anyone who wants practical guidance for AI Money Management, Best Free AI Tools for Personal Finance, and smarter everyday financial decisions without needing advanced financial knowledge.

    8.Claude – Best AI Tool for Financial Research and Decision Support

    If your goal is to understand financial topics in greater depth rather than simply track expenses, Claude is a strong choice. Consequently, among today’s Best AI Finance Apps, Claude excels at breaking down complex financial concepts, comparing investment ideas, summarizing reports, and helping users make informed decisions. It workClaudehttps://s particularly well alongside AI Financial Planning and AI Money Management by turning complicated information into clear, structured explanations.

    Why Choose Claude?

    Additionally, claude is designed for thoughtful analysis instead of quick answers alone. Whether you’re researching investment strategies, comparing financial products, or creating a long-term budget, it can organize large amounts of information into practical insights. If you’re interested in How to Create a Monthly Budget, Financial Goal Planning, or improving your financial knowledge, Claude can help simplify the learning process.

    Key Features

    • Then, first, deep financial research assistance
    • Additionally, next, in fact, long-document analysis
    • Then, budget planning support
    • Moreover, investment comparison
    • Additionally, financial report summaries
    • Furthermore, notably, personalized financial explanations
    • Finally, goal-based planning assistance

    Practical Example

    Consequently, suppose you’re comparing two investment options.

    InvestmentExpected Annual ReturnRisk Level
    Fund A8%Medium
    Fund B11%High

    Instead of recommending one option outright, Claude can help you compare the trade-offs, explain how risk and return relate, and organize the information into an easy-to-understand comparison. It supports better AI Financial Planning by helping you evaluate choices rather than making decisions for you.

    Pros

    • Additionally, excellent for financial learning and research
    • Specifically, easy-to-understand explanations
    • Furthermore, first, for example, strong document analysis
    • Finally, next, helpful for comparing financial options

    Cons

    • Consequently, not a banking or budgeting application
    • Then, does not automatically connect to financial accounts

    Best For

    In addition, for example, students, investors, bloggers, researchers, and professionals looking to improve AI Money Management, explore Best Free AI Tools for Personal Finance, strengthen AI Budgeting Tools, and make better-informed financial decisions through deeper analysis.

    9.Perplexity AI – Best AI Tool for Real-Time Financial Research

    When you need up-to-date financial information, perplexity.ai/can be a useful research assistant. Unlike traditional budgeting apps, it helps you find and summarize current information from multiple sources, making it valuable for learning about markets, financial products, and personal finance topics. If you’re exploring Best AI Finance Apps, improving AI Financial Planning, or researching smarter money strategies, Perplexity AI can help you gather information more efficiently.

    Why Choose Perplexity AI?

    However, perplexity AI is designed for research rather than budgeting. It can help you compare financial products, understand investment concepts, summarize articles, and answer finance-related questions with source-backed information. If you’re learning How to Create a Monthly Budget, researching AI Money Management, or comparing different financial options, it can save significant research time.

    Key Features

    • However, real-time financial research
    • Additionally, source-backed answers
    • Furthermore, in fact, investment and market summaries
    • Finally, product comparisons
    • Moreover, financial learning support
    • Specifically, fast information discovery
    • Specifically, first, notably, easy-to-read explanations

    Practical Example

    Consequently, imagine you’re comparing two savings accounts.

    OptionInterest RateAnnual Interest on $10,000*
    Account A3.5%$350
    Account B4.2%$420

    *Illustrative calculation before taxes, fees, or compounding differences.

    Instead of manually searching dozens of websites, Perplexity AI can help you collect relevant information, compare key features, and understand the differences more quickly. You should always verify important financial details with the official provider before making a decision.

    Pros

    • Then, first, next, fast research with cited sources
    • Additionally, excellent for financial learning
    • Then, easy product comparisons
    • Additionally, for example, simple and beginner-friendly interface

    Cons

    • Furthermore, not a budgeting application
    • Consequently, does not manage bank accounts or investments directly

    Best For

    Therefore, students, investors, bloggers, researchers, and anyone looking to strengthen AI Financial Planning, //investor.gov/ explore AI Expense Tracking solutions, discover Best Free AI Tools for Personal Finance, and make more informed financial decisions through efficient research.

    Final Verdict: Which AI Tool for Personal Finance Should You Choose?

    However, after comparing the 10 Best AI Tools to Manage Your Personal Finances in 2026, the right choice ultimately depends on your financial goals, experience level, and the features you value most. As a result, there isn’t a single tool that’s perfect for everyone. Additionally, some excel at budgeting, others at financial research, while a few are designed for long-term money management and planning.

    Our Top Recommendations

    If you’re looking for an all-around AI assistant for budgeting, financial education, and planning, ChatGPT is an excellent choice. For deeper document analysis and financial research, Claude offers strong reasoning capabilities. If your priority is real-time financial research with source-backed answers, Perplexity AI is one of the best options available.

    Which Tool Matches Your Goal?

    Final Thoughts

    In fact, the best AI finance tool isn’t necessarily the one with the most features—it’s the one you’ll actually use consistently. In addition, start with a tool that matches your current needs, learn its features, and build better financial habits over time. As your goals evolve, you can always switch to a platform that offers more advanced capabilities. Specifically, making informed financial decisions consistently is far more important than choosing the most popular app.

    What is the best AI tool for personal finance in 2026?


    The best AI Tool for Personal Finance depends on your financial goals. ChatGPT is ideal for budgeting and financial guidance, Claude is excellent for in-depth financial research, and Perplexity AI is a strong choice for real-time financial information. For example, budgeting-focused users may also prefer YNAB or Rocket Money.

    Are AI tools for personal finance safe to use

    In fact, are AI tools for personal finance safe to use?Yes, most reputable AI Finance Apps use encryption and industry-standard security practices to protect user data. Before using any platform, review its privacy policy, enable two-factor authentication when available, and avoid sharing highly sensitive financial information unless necessary.

    Practical Steps & Actionable Tips for AI tools for personal finance

    Can AI help me save more money?Yes. Specifically, modern AI Budgeting Tools

    Particularly, can AI help me save more money?Yes. In addition, modern AI Budgeting Tools analyze your spending habits, categorize expenses, identify recurring subscriptions, and provide personalized suggestions that may help you improve your budget and increase savings. AI should be used as a decision-support tool rather than a replacement for your own financial judgment.

    Article Summtools for personal finance ary
    AI tools for personal finance are transforming the way people manage money by simplifying budgeting, expense tracking, savings, and financial planning. In this guide, we explored how AI finance tools work, the key factors to consider before choosing one, and the 10 best AI tools for personal finance in 2026. We also compared their features, strengths, limitations, pricing, and ideal use cases to help you make an informed decision. Whether you’re a beginner looking for smarter budgeting or a professional seeking advanced financial insights, the right AI tool can save time, improve financial habits, and support better long-term money management. The best choice is the one that aligns with your financial goals, budget, and everyday needs.

    Actionable Advice and Practical Tips for AI tools for personal finance

    Written & Researched by Asif Khan

    AI tools for personal finance: Asif Khan - Lead Research Editor
    Written & Researched by Asif Khan
    Founder & Lead Financial Editor PaisaKmao.de

    Additionally, over 4 years of active personal finance research in Indian markets. Focused on transparent, math-backed guides to help students and young professionals build wealth and manage money smartly.
    Connect With Asif Khan:

    10 Best Financial Habits Every College Student Should Develop (2026)

    10 Best Financial Habits Every College Student Should Develop to Save Money, Budget Better, and Build Long-Term Wealth

    Learning the essential principles of financial habits for college students is critical for anyone looking to build healthy money habits, avoid debt traps, and make smart financial decisions in India.

    ⚡Last Updated: November 2026College Financial Literacy Edition

    Learning the essential principles of financial habits for college students is critical for anyone looking to build healthy money habits, avoid debt traps, and make smart financial decisions in India.

    Learning the essential principles of financial habits for college students is critical for anyone looking to build healthy money habits, avoid debt traps, and make smart financial decisions in India.

    Learning the essential principles of financial habits for college students is critical for anyone looking to build healthy money habits, avoid debt traps, and make smart financial decisions in India.

    Additionally, mastering sound financial habits for college students sets the foundation for lifelong wealth, smart investing, and complete debt freedom.

    📌

    Key Takeaways: Essential Financial Habits for Students

    • Start With ₹500/Month: Building the habit of saving consistently matters far more than the initial amount during your college years.
    • Track Daily Outflows: Log everyday small expenses (canteen, tea, outings) using simple budgeting tools to prevent end-of-month cash emergencies.
    • Beware of Debt Traps: Strictly stay away from predatory instant loan apps, unregulated credit schemes, and unnecessary Buy Now Pay Later (BNPL) loans.
    • Build an Emergency Buffer: Keep at least 1–2 months of living allowance in a digital zero-balance savings account for unexpected academic or travel needs.

    Learning about financial habits for college students is essential for anyone looking to build healthy money habits. INTRODUCTION

    Additionally, starting college is exciting, but it also brings new financial responsibilities. For many students, this is the first time they have complete control over their money. Whether you receive a monthly allowance from your family, earn ₹10,000–₹20,000 ($100–$300) from a part-time job, or manage a scholarship, every financial decision you make today shapes your future.

    Furthermore, for example, table of Contents

    Practical Steps & Actionable Tips for financial habits for college students

    Specifically, for verified statutory guidelines and official consumer protections, refer to the Reserve Bank of India (RBI).

    1.Why Financial Habits Matter in College: Complete Guide to financial habits for college students

    financial habits for college students: : : : strategic financial roadmap

    Consequently, college is more than a place to earn a degree—it’s where your financial future quietly begins. For many students, this is the first time they manage their own money, make independent financial decisions, and learn the real difference between needs and wants. Whether your monthly income comes from a scholarship, a part-time job, freelancing, or family support, the habits you develop today will shape your financial life long after graduation.

    Additionally, for example, the 10 Best Financial Habits Every College Student Should Develop aren’t simply money-saving tips. Furthermore, they are lifelong principles that help you build discipline, reduce financial stress, avoid unnecessary debt, and create a strong foundation for financial independence. Moreover, according to the Consumer Financial Protection Bureau (CFPB), students who learn budgeting and responsible money management early are more likely to achieve long-term financial stability.

    The Long-Term Impact of Small Money Decisions: Complete Guide to financial habits for college students

    However, many students believe that financial success depends on earning more money. In reality, it depends on making better decisions with the money you already have.

    Consequently, imagine spending just ₹200 ($2.40) every day on coffee, food delivery, online shopping, or impulse purchases. It doesn’t feel expensive because it’s only one small transaction. However, over one year, that habit costs nearly ₹73,000 ($880+)—enough to buy a quality laptop, build an emergency fund, pay for professional certifications, or even start investing.

    In fact, now imagine doing the exact opposite.

    Instead of spending that ₹200 every day, you save or invest it consistently. Overall, without increasing your income, you’ve already created a financial system that works for you rather than against you.

    In addition, this is why experts often say that wealth isn’t built by one big decision—it is built by thousands of small decisions repeated consistently.

    A Simple Real-Life Example

    Moreover, consider two college students who each receive ₹15,000 ($180) every month.

    However, the first student spends money whenever they feel like it. Consequently, they never check where their money goes and often run out of cash before the month ends.

    Therefore, notably, the second student receives the same amount but saves 20% (₹3,000 / $36) before spending anything else. As a result, they follow a simple budget, review their expenses every weekend, and avoid unnecessary purchases.

    In fact, after one year, both students earned exactly the same amount of money.

    Additionally, the only difference is that one developed financial stress, while the other developed financial freedom.

    Why Building Financial Habits Early Gives You a Competitive Advantage: Complete Guide to financial habits for college students

    Particularly, good financial habits work like compound interest—the earlier you build them, the greater the rewards become over time.

    Moreover, for example, research from the OECD Financial Education shows that people with stronger financial literacy are more likely to save regularly, avoid unnecessary debt, and make informed financial decisions throughout their lives.

    Overall, you don’t need a six-figure salary to start building wealth.

    Consequently, you need the discipline to make one smart financial decision today, then repeat it tomorrow, next week, next month, and next year.

    Key Takeaway

    Furthermore, notably, your salary may determine how much money enters your bank account.

    However, your financial habits determine how much of that money stays there.

    Start building the right habits in college, and your future self will thank you for every smart financial decision you make today.

    2. Additionally, create a Monthly Budget That Actually Works: Complete Guide to financial habits for college students

    A budget isn’t about restricting your life—it’s about giving every rupee and dollar a purpose. One of the biggest financial mistakes college students make is spending first and wondering where their money went at the end of the month. A simple monthly budget helps you stay in control, reduce financial stress, and make smarter decisions without sacrificing the things you enjoy.

    FREE INTERACTIVE TOOL

    Start Habit #1: Track Your Student Budget Today

    Specifically, as a result, take 2 minutes to calculate your exact monthly pocket money, hostel spends, and discretionary savings.

    Whether your monthly income is ₹10,000 ($120) or ₹25,000 ($300), budgeting ensures that your essential expenses, savings, and personal spending remain balanced. In addition, according to the Consumer Financial Protection Bureau (CFPB), creating and following a budget is one of the most effective ways to improve financial health and avoid unnecessary debt.

    Why Every College Student Needs a Budget: Complete Guide to financial habits for college students

    In fact, without a budget, it’s easy to underestimate small daily expenses. A few online orders, food deliveries, subscriptions, and impulse purchases may not seem expensive individually, but together they can consume a large portion of your monthly income.

    A well-planned budget helps you:

    • First, first, first, first, know exactly where your money goes.
    • However, avoid overspending before the month ends.
    • Next, next, next, next, save consistently for future goals.
    • Then, in fact, prepare for unexpected expenses.
    • Additionally, spend with confidence instead of guilt.

    A Simple Student Budget Example

    CategoryRecommended AllocationExample (₹15,000 / $180)
    Essential Expenses50%₹7,500 ($90)
    Savings20%₹3,000 ($36)
    Learning & Skill Development20%₹3,000 ($36)
    Entertainment & Personal Spending10%₹1,500 ($18)

    Additionally, this isn’t a fixed rule. Specifically, adjust the percentages based on your income and responsibilities, but always make saving a priority before spending.

    Budgeting Isn’t About Spending Less—It’s About Spending Smarter: Complete Guide to financial habits for college students

    Moreover, many students think budgeting means giving up everything they enjoy. In reality, budgeting gives you permission to spend on what truly matters while avoiding wasteful expenses that don’t improve your life.

    Furthermore, research from the OECD Financial Education shows that people who regularly plan and monitor their finances are more likely to achieve long-term financial security than those who spend without a plan.

    A budget doesn’t limit your freedom—it protects your future by making every rupee and dollar work with purpose.

    3. For example, save Money Before You Spend: Complete Guide to financial habits for college students

    Specifically, notably, one of the biggest differences between students who achieve financial stability and those who constantly struggle isn’t how much they earn—it’s when they choose to save. Specifically, most people spend first and save whatever is left at the end of the month. In addition, unfortunately, for many college students, nothing is left to save.

    financial habits for college students: : : : Kotak 811 Zero Balance Savings Account - Instant Video KYC
    ★ Zero-Balance Digital Banking 100% Online 18+ Eligible

    Kotak 811 Digital Savings Account

    Additionally, for example, for example, practice “Paying Yourself First” by routing your college savings directly into a separate zero-maintenance digital bank account.

    ₹0 Min Balance 3-Min Video KYC Free Virtual Debit Card

    Affiliate Disclosure: This article contains an affiliate link. If you open an account through this link, we may earn a commission at no additional cost to you.

    Additionally, financially successful people follow a different approach known as “Pay Yourself First.” Instead of treating savings as an afterthought, they make it their first financial priority. However, even if you can only save ₹100–₹300 ($1–$4) a day, that habit can grow into thousands of rupees or hundreds of dollars over time.

    According to the Consumer Financial Protection Bureau (CFPB), automatically saving a portion of your income before spending can improve financial security and help you prepare for unexpected expenses.

    What Does “Pay Yourself First” Really Mean?: Complete Guide to financial habits for college students

    Consequently, the moment your monthly allowance, scholarship, freelance payment, or salary arrives, move a fixed percentage directly into your savings account before paying for anything else.

    In addition, for example, this simple habit changes your mindset from:

    “I’ll save whatever is left.”

    to

    “I’ll spend only what’s left after saving.”

    However, that small shift can completely transform your financial future.

    How Much Should a College Student Save?

    Monthly IncomeMinimum Savings (10%)Ideal Savings (20%)
    ₹10,000 ($120)₹1,000 ($12)₹2,000 ($24)
    ₹15,000 ($180)₹1,500 ($18)₹3,000 ($36)
    ₹20,000 ($240)₹2,000 ($24)₹4,000 ($48)
    ₹25,000 ($300)₹2,500 ($30)₹5,000 ($60)

    Consequently, don’t worry if you can’t save 20% immediately. The most important goal is to build the habit of saving consistently, even if you start with a smaller amount.

    Why Saving First Is More Powerful Than Saving Later: Complete Guide to financial habits for college students

    Therefore, imagine two students who each receive ₹15,000 ($180) every month.

    Student A spends freely throughout the month and tries to save whatever remains. Therefore, most months, nothing is left.

    Student B immediately transfers ₹3,000 ($36) into a savings account on the day the money arrives. In fact, they learn to live comfortably on the remaining ₹12,000 ($144).

    However, after one year, Student B has saved ₹36,000 ($430+) without increasing their income. Particularly, more importantly, they’ve built a habit that can continue for decades.

    In fact, research from the OECD Financial Education shows that consistent saving habits are strongly linked to better financial resilience, lower debt, and greater long-term financial confidence.

    You don’t become wealthy because you save what’s left after spending. You build wealth by spending what’s left after saving.

    4. In fact, track Every Expense Without Making It Complicated

    In fact, many college students believe they don’t spend much money. However, the real problem isn’t always how much they spend—it’s not knowing where their money goes. Overall, small daily expenses like coffee, food delivery, online subscriptions, and impulse purchases can quietly drain your budget without you noticing.

    Particularly, tracking your expenses isn’t about recording every rupee forever. It’s about understanding your spending habits so you can make smarter financial decisions. Notably, according to the Consumer Financial Protection Bureau (CFPB), regularly monitoring your spending is one of the simplest ways to improve budgeting and avoid unnecessary financial stress.

    A Simple Expense Tracking Method

    CategoryExample
    🍽️ Food & Drinks₹3,500 ($42)
    🚕 Transportation₹1,200 ($14)
    📚 Education₹2,000 ($24)
    🎬 Entertainment₹1,000 ($12)
    💰 Savings₹3,000 ($36)
    📱 Other Expenses₹1,300 ($16)

    Moreover, you don’t need expensive apps to do this. A simple notes app, spreadsheet, or budgeting app is enough to record your daily spending for just 30 days. By the end of the month, you’ll clearly see where your money is going and which expenses can be reduced.

    Pro Tip

    At the end of every week, spend 10 minutes reviewing your expenses. This small habit helps you identify unnecessary spending before it becomes a long-term financial problem.

    You can’t improve what you don’t measure. Moreover, tracking your expenses is the first step toward taking control of your money.

    5. Additionally, build an Emergency Fund Before You Need It

    Moreover, life is unpredictable. A medical emergency, laptop repair, unexpected travel, or a sudden loss of income can happen when you least expect it. Furthermore, without savings, many college students rely on credit cards or borrow money from friends and family, creating unnecessary financial stress.

    Overall, notably, an emergency fund is money set aside specifically for unexpected expenses—not for shopping, vacations, or entertainment. Overall, according to the Consumer Financial Protection Bureau (CFPB), having emergency savings can help people avoid debt and recover from financial setbacks more quickly.

    How Much Should a College Student Save?

    Monthly ExpensesRecommended Emergency Fund
    ₹8,000 ($95)₹16,000–₹24,000 ($190–$285)
    ₹12,000 ($145)₹24,000–₹36,000 ($285–$430)
    ₹15,000 ($180)₹30,000–₹45,000 ($360–$540)
    ₹20,000 ($240)₹40,000–₹60,000 ($480–$720)

    Consequently, notably, don’t worry if you can’t build this amount immediately. For example, start by saving a small portion every month. Consequently, even ₹500–₹1,000 ($6–$12) saved consistently can grow into a reliable financial safety net over time.

    Where Should You Keep Your Emergency Fund?

    Additionally, keep this money in a separate savings account where it’s easy to access during emergencies but not so convenient that you’re tempted to spend it on everyday purchases.

    An emergency fund doesn’t make you richer overnight—it gives you peace of mind when life doesn’t go according to plan.

    6. Consequently, avoid Impulse Buying and Think Before You Spend

    In addition, as a result, impulse buying is one of the biggest reasons college students struggle to save money. However, flash sales, limited-time offers, social media ads, and one-click online shopping make it easy to spend money on things you never planned to buy. While a single purchase may seem harmless, repeated impulse spending can quietly damage your monthly budget.

    Additionally, for example, building the habit of thinking before spending helps you stay in control of your money instead of letting emotions control your decisions. Therefore, according to the Consumer Financial Protection Bureau (CFPB), creating a spending plan and avoiding emotional purchases are important steps toward better financial health.

    The 24-Hour Rule

    Before buying any non-essential item, wait 24 hours.

    Furthermore, ask yourself these simple questions:

    • Do I really need this, or do I just want it?
    • Will I still use it after one month?
    • Does this purchase fit my monthly budget?
    • Can this money be used for something more valuable?

    Consequently, most impulse purchases lose their appeal after a day, helping you save money without feeling deprived.

    Smart Spending Checklist

    Before You BuyAsk Yourself
    Need or Want?Is this essential?
    Budget CheckCan I afford it without affecting my savings?
    Future ValueWill this improve my life or skills?
    24-Hour RuleCan this purchase wait until tomorrow?

    Every purchase is a financial decision. As a result, spend with purpose today, and your future self will thank you tomorrow.

    7. Particularly, start Investing Early—Even with a Small Amount

    Specifically, many college students believe they need thousands of rupees or dollars before they can start investing. In reality, the most valuable advantage an investor has isn’t a large amount of money—it’s time. Moreover, starting early allows your investments more time to grow through the power of compounding.

    However, you don’t have to begin with a large portfolio. Additionally, even investing ₹500–₹1,000 ($6–$12) every month can help you develop the habit of investing while learning how financial markets work. The goal during college isn’t to become rich overnight—it’s to become a disciplined long-term investor.

    According to the U.S. In addition, notably, securities and Exchange Commission – Investor.gov, investing regularly over a long period and understanding compound growth are key principles for building long-term wealth.

    What Should College Students Focus On?

    Before investing, make sure you have:

    • A monthly budget
    • Then, consistent savings
    • Additionally, an emergency fund
    • Furthermore, basic investment knowledge

    However, for example, once these foundations are in place, you can gradually begin your investing journey.

    Investment HabitWhy It Matters
    Invest Every MonthBuilds discipline and consistency
    Think Long-TermReduces emotional decisions
    Keep LearningHelps you make smarter investment choices
    Avoid “Get Rich Quick” SchemesProtects your money from unnecessary risks

    A Long-Term Mindset Wins

    In fact, successful investing isn’t about predicting tomorrow’s market. It’s about staying patient, investing consistently, and allowing time to work in your favor.

    The best time to start investing was yesterday. The second-best time is today. As a result, small investments made consistently can grow into significant wealth over the long term.

    8. Specifically, avoid High-Interest Debt and Borrow Responsibly

    Consequently, debt isn’t always bad, but high-interest debt can quickly become a financial burden—especially for college students with limited income. Furthermore, many students borrow money for non-essential purchases, use credit cards carelessly, or take personal loans without understanding how interest works. These small decisions can create long-term financial stress.

    Learning to borrow responsibly is one of the best financial habits every college student should develop. If you need to borrow money, make sure it’s for an important purpose such as education, an emergency, or something that genuinely improves your future—not for impulse shopping or luxury purchases.

    According to the Consumer Financial Protection Bureau (CFPB), understanding interest rates, repayment terms, and borrowing limits can help consumers avoid unnecessary debt and protect their financial well-being.

    Good Debt vs. Bad Debt

    Type of DebtSmart or Risky?Example
    📚 Education Loan Good (when planned wisely)College tuition or skill development
    🏥 Emergency Medical Loan GoodUnexpected medical expenses
    📱 Buying the Latest Phone on Credit❌ RiskyNon-essential purchase
    🛍️ Shopping with Borrowed Money❌ RiskyClothes, gadgets, luxury items

    Borrow Only When Necessary

    Before taking any loan or using a credit card, ask yourself:

    • Do I really need this money?
    • Can I comfortably repay it on time?
    • Will this borrowing improve my future or just satisfy a temporary desire?

    If the answer is no, it’s usually better to wait, save, and pay with your own money.

    Debt can be a useful financial tool when used wisely—but when used carelessly, it can delay your financial freedom for years.

    9. Set Clear Financial Goals and Review Your Progress

    Moreover, without a clear goal, it’s easy to spend money without thinking about the future. Specifically, financial goals give your money a purpose and help you stay motivated, even when it’s tempting to make unnecessary purchases. Whether your goal is building an emergency fund, buying a laptop, starting to invest, or graduating without debt, having a written plan makes it much easier to stay on track.

    In addition, the best financial habits every college student should develop include setting both short-term and long-term goals. For example, according to the Consumer Financial Protection Bureau (CFPB), people who write down their financial goals and regularly review their progress are more likely to achieve them than those who simply keep goals in their mind.

    Set SMART Financial Goals

    However, notably, your financial goals should be Specific, Measurable, Achievable, Relevant, and Time-bound (SMART).

    GoalTargetTime Frame
    💰 Build an Emergency Fund₹30,000 ($360)12 Months
    💻 Buy a Laptop₹60,000 ($720)18 Months
    📈 Start Investing₹1,000/monthThis Month
    📚 Skill DevelopmentComplete 2 Online Courses6 Months

    Review Your Goals Every Month

    At the end of each month, ask yourself:

    • Finally, did I stay within my budget?
    • Specifically, did I save the amount I planned?
    • Then, first, am I getting closer to my financial goal?
    • Additionally, next, what financial mistake can Always avoid next month?

    Therefore, even if your progress is slow, consistency matters more than perfection.

    A goal without a plan is only a wish. Consequently, give every rupee and every dollar a purpose, and your financial future will become much clearer.

    10. In addition, review Your Finances Every Month and Keep Improving

    Additionally, building good financial habits isn’t a one-time task—it’s an ongoing process. Even the best budget won’t help if you never review it. That’s why one of the best financial habits every college student should develop is setting aside a few minutes every month to evaluate their financial progress.

    A monthly financial review helps you understand what’s working, identify unnecessary expenses, improve your savings, and make better decisions for the next month. Therefore, according to the Consumer Financial Protection Bureau (CFPB), regularly reviewing your budget, savings, and financial goals can improve money management and reduce financial stress over time.

    Zero Balance Digital Account
    Ready to Open Your Free Kotak 811 Account?
    Build your financial foundation with a 100% paperless student-friendly zero balance account.
    Check Account Details →

    Affiliate Disclosure: This article contains an affiliate link. If you open an account through this link, we may earn a commission at no additional cost to you.

    Your 15-Minute Monthly Money Review

    At the end of each month, answer these questions honestly:

    Review QuestionYour Goal
    💰 Did I stay within my monthly budget?Yes
    📊 Did I save at least 10–20% of my income?Yes
    🛒 What was my biggest unnecessary expense?Identify & reduce it
    🎯 Am I closer to my financial goals?Measure your progress
    📚 What financial lesson did I learn this month?Improve next month

    In fact, you don’t need complicated spreadsheets or expensive apps. A notebook, spreadsheet, or budgeting app is enough to review your finances in just 15 minutes every month.

    Small Improvements Lead to Big Results

    If you improve your financial habits by just 1% every month, you’ll make significantly better financial decisions over the course of a year. In fact, review your progress, celebrate small wins, learn from mistakes, and keep moving forward.

    Financial success isn’t about being perfect every month—it’s about becoming a little smarter with your money every single month.

    ### Can college students become financially independent while studying?

    Particularly, for example, yes. In addition, financial independence doesn’t happen overnight, but college students can begin building it by following a budget, saving consistently, developing valuable skills, earning through part-time work or freelancing, and avoiding unnecessary debt. The earlier you start, the stronger your financial future becomes.

    What is the 50/30/20 budgeting rule for college students?

    Moreover, the 50/30/20 budgeting rule recommends using **50%** of your income for essential needs, **30%** for personal wants, and **20%** for savings or investments. It’s a simple budgeting framework that helps college students manage money more effectively and build healthy financial habits.

    How much emergency savings should a college student have?

    Practical Steps & Actionable Tips for financial habits for college students

    A good starting goal is to save enough to cover **one to three months of essential expenses**. If that’s not possible, begin with a smaller target such as **₹10,000–₹20,000 ($120–$240)** and increase your emergency fund gradually through consistent monthly savings.

    ### Which financial skill should every college student learn first?

    Consequently, budgeting is the most important financial skill for college students. Moreover, once you understand how to manage your income and expenses, it becomes much easier to save money, avoid debt, invest wisely, and achieve your long-term financial goals.

    Actionable Insights and Smart Advice for financial habits for college students

    ## ConclusionDeveloping strong financial habits during college is one of the smartest investments you can make for your future. By creating a budget, saving consistently, tracking expenses, avoiding unnecessary debt, and setting clear financial goals, you’ll build a solid foundation for long-term financial success.Remember, financial freedom doesn’t depend on how much you earn—it depends on how wisely you manage your money. Overall, start with one habit, stay consistent, and improve a little every month. However, over time, these small actions can lead to greater financial confidence, stability, and lasting wealth.**The best financial habits you build today can shape a more secure and successful tomorrow.**

    Written & Researched by Asif Khan

    financial habits for college students: Asif Khan - Lead Research Editor
    Written & Researched by Asif Khan
    Founder & Lead Financial Editor PaisaKmao.de

    Additionally, over 4 years of active personal finance research in Indian markets. Therefore, focused on transparent, math-backed guides to help students and young professionals build wealth and manage money smartly.
    Connect With Asif Khan:

    Best Investments for College Students with $100: A Complete Beginner’s Guide (2026)

    Best Investments for College Students with $100 featuring index funds ETFs and fractional shares for beginners

    Learning the essential principles of best investments for college students is critical for anyone looking to build healthy money habits, avoid debt traps, and make smart financial decisions in India.

    Learning the essential principles of best investments for college students is critical for anyone looking to build healthy money habits, avoid debt traps, and make smart financial decisions in India.

    Learning the essential principles of best investments for college students is critical for anyone looking to build healthy money habits, avoid debt traps, and make smart financial decisions in India.

    Learning the essential principles of best investments for college students is critical for anyone looking to build healthy money habits, avoid debt traps, and make smart financial decisions in India.

    Learning the essential principles of best investments for college students is critical for anyone looking to build healthy money habits, avoid debt traps, and make smart financial decisions in India.

    best investments for college students: : : : strategic financial roadmap

    introduction

    Best Investments for College Students with $100 might sound impossible if you’re living on a tight student budget—but what if your first $100 could become the beginning of long-term wealth?

    Essential Overview: Guide to best investments for college students

    Additionally, the truth is, you don’t need thousands of dollars to start investing. Furthermore, thanks to modern investment platforms, college students can begin investing with as little as $100 while learning valuable financial skills for the future.

    In this complete beginner’s guide, you’ll discover the Best Investments for College Students with $100, learn how to choose the right investment, avoid costly beginner mistakes, and build a smart investing strategy that can grow with you for years to come.

    Furthermore, for example, for verified statutory guidelines and official consumer protections, refer to the Securities and Exchange Board of India (SEBI).

    Why Should College Students Start Investing with $100?: Complete Guide to best investments for college students

    best investments for college students: : : : strategic financial roadmap

    Specifically, many people think Best Investments for College Students with $100 is just another finance topic, but it’s actually about building a strong financial future with a small amount of money. You don’t need thousands of dollars to start investing. What matters most is starting early, learning consistently, and allowing time to work in your favor.

    Why $100 Is More Than Enough to Start: Complete Guide to best investments for college students

    Consequently, starting with $100 helps you build confidence and practical investing experience without taking unnecessary financial risks. Specifically, many modern brokerage platforms allow beginners to invest in ETFs, index funds, mutual funds, and fractional shares with a small investment.

    What Can You Invest In?

    • However, index Funds
    • ETFs (Exchange-Traded Funds)
    • First, first, first, first, mutual Funds
    • Next, next, next, next, in fact, fractional Shares
    • Then, high-Yield Savings Accounts

    Before making your first investment, spending time with Investment Basics for Beginners can help you understand how markets work and make smarter decisions.

    The Biggest Advantage College Students Have: Complete Guide to best investments for college students

    Additionally, for example, most people believe money is the biggest advantage in investing. In reality, time is your greatest asset. The earlier you begin, the more opportunity your investments have to grow through compounding.

    Why Starting Early Matters

    • Moreover, more years for your investments to grow.
    • Additionally, small investments can become significant over time.
    • Furthermore, notably, less pressure to invest large amounts later in life.
    • Finally, better opportunity to recover from market downturns.

    Learning about Compound Interest is one of the best ways to understand why starting with $100 today can be more valuable than waiting until you have thousands of dollars.

    Build Financial Habits That Last a Lifetime: Complete Guide to best investments for college students

    However, finding the Best Investments for College Students with $100 is only the first step. Furthermore, long-term success depends on developing smart financial habits that you continue after graduation.

    Essential Habits Every Student Investor Should Build

    • Additionally, invest consistently.
    • Specifically, create a monthly budget.
    • Then, first, for example, reinvest your returns whenever possible.
    • Additionally, next, keep learning through trusted resources like Investopedia, Morningstar, and the Vanguard Learning Center.
    • Consequently, understand Investment Diversification before building your portfolio.

    Focus on Learning Before Chasing Profits: Complete Guide to best investments for college students

    Consequently, many beginners expect quick profits and become disappointed when markets fluctuate. Consequently, successful investors focus on gaining knowledge first and returns second. The more you learn today, the better your investment decisions will be in the future.Global Index Funds vs S&P 500: The Smarter Choice for Beginner Investors in 2026

    Things to Do Before Investing Your First $100: Complete Guide to best investments for college students

    Before choosing the Best Investments for College Students with $100, you should prepare yourself financially. In addition, even the best investment can become a bad decision if you invest without a plan. These simple steps will help you protect your money and make smarter investment decisions from the beginning.

    FREE INTERACTIVE TOOL

    Project Your Small Investment Returns

    In fact, calculate how modest starting capital grows when reinvested regularly into diversified index funds and equities.

    Set a Clear Financial Goal: Complete Guide to best investments for college students

    In addition, don’t invest just because everyone else is investing. Specifically, decide whether your goal is long-term wealth, saving for future education, buying a laptop, or achieving financial independence. A clear goal helps you choose the right investment strategy and stay focused.

    Questions to Ask Yourself

    • Then, why am I investing?
    • When will I need this money?
    • However, how much risk can I take?

    Create a Small Emergency Fund: Complete Guide to best investments for college students

    Before investing your first $100, keep some cash aside for emergencies. This prevents you from selling your investments during unexpected situations like medical expenses or urgent travel.

    A Good Starting Target

    • Additionally, save at least $100–$300.
    • Furthermore, in fact, keep it in a safe savings account.
    • Finally, use it only for real emergencies.

    Understand Your Risk Tolerance

    Moreover, every investment carries some level of risk. Therefore, some investments offer higher growth but greater volatility, while others are more stable. In fact, learning your Risk Tolerance helps you make better investment choices instead of following trends.

    Simple Risk Check

    • Moreover, can you leave your money invested for 5 years?
    • Specifically, will you stay calm if the market falls?
    • Furthermore, first, notably, are you investing for short-term or long-term goals?

    Learn Before You Invest

    However, knowledge is one of the best investments you’ll ever make. Furthermore, spend time learning from trusted resources like Investopedia, https://www.investor.gov/and before investing your money. The more you learn today, the fewer mistakes you’ll make tomorrow.Related Reading I Need to Make $100 as a Student 7 Easy Ways That Actually Work

    Best Investment Options for College Students with $100

    Therefore, notably, choosing the Best Investments for College Students with $100 isn’t about chasing the highest returns—it’s about selecting investments that match your financial goals, risk tolerance, and time horizon. Moreover, even with just $100, you can build a diversified portfolio and start your wealth-building journey.

    Index Funds – Best for Long-Term Growth

    Index Funds are one of the smartest choices for beginners because they invest in hundreds of companies at once. Overall, they offer diversification, low fees, and strong long-term growth potential.

    Why Choose Index Funds?

    • Finally, next, low investment risk
    • Additionally, broad diversification
    • Then, low expense ratio
    • Additionally, for example, beginner-friendly

    In fact, learn more from Investopedia and S&P 500.

    ETFs – Flexible and Affordable Investing

    ETFs work like stocks but provide the diversification of mutual funds. Consequently, they’re easy to buy, low-cost, and perfect for students starting with $100.

    Key Benefits

    • Furthermore, low fees
    • Consequently, easy trading
    • Finally, diversified portfolio
    • However, long-term growth

    Additionally, explore ETF Investing and Morningstar for deeper insights.

    Fractional Shares – Invest in Top Companies

    Particularly, with Fractional Shares, you can own a small piece of companies like Apple or Microsoft without buying a full share.

    Best For

    • Specifically, small budgets
    • Specifically, first, in fact, first-time investors
    • Then, first, next, long-term investing

    Moreover, for example, understand how Fractional Investing works before getting started.

    High-Yield Savings Account – Safety First

    If you may need your money soon, a High-Yield Savings Account offers a safer place to keep your savings while earning interest.

    Best For

    • Moreover, emergency funds
    • Then, short-term goals
    • Additionally, notably, low-risk investors

    Overall, compare options using Bankrate.

    Which Investment Is Right for You?

    Consequently, the Best Investments for College Students with $100 depend on your personal goals.

    • Furthermore, long-term growth → Index Funds
    • Additionally, flexibility → ETFs
    • Finally, individual companies → Fractional Shares
    • Specifically, for example, maximum safety → High-Yield Savings Account

    Before investing, continue learning through Investopedia, https://www.investor.gov/ and https://www.morningstar.com/the Vanguard Learning Center to make smarter financial decisions.Releted post Top 10 Finance Skills That Can Help Students Earn Money in Real Life

    How to Build Your First $100 Investment Portfolio

    Furthermore, notably, after understanding the Best Investments for College Students with $100, the next step is creating a simple portfolio. A portfolio is a collection of investments that helps you reduce risk while giving your money the opportunity to grow over time. Instead of investing your entire $100 in one place, spreading it across different assets can be a smarter strategy.

    A Simple $100 Portfolio Example

    Investment OptionAllocationAmount
    Index Fund50%$50
    ETF30%$30
    Fractional Shares20%$20

    Why This Portfolio Works

    • Additionally, next, first, reduces investment risk through diversification.
    • Consequently, gives exposure to both the overall market and individual companies.
    • Then, next, beginner-friendly and easy to manage.
    • However, helps build long-term investing habits.

    To understand portfolio building, learn about Asset Allocation and Diversification before making your first investment.

    Invest Consistently Instead of Waiting

    However, your first $100 is only the beginning. If you continue investing even a small amount every month, your portfolio can grow significantly over time. This strategy we call this Dollar-Cost Averaging, where you invest regularly regardless of market conditions.

    Monthly Investment Example

    Monthly Investment1 Year5 Years
    $25$300 Invested$1,500 Invested
    $50$600 Invested$3,000 Invested
    $100$1,200 Invested$6,000 Invested

    Specifically, as a result, continue improving your investing knowledge through https://www.morningstar.com/portfolios andhttps://www.schwab.com/learn Investor.gov, and the Vanguard Learning Center while reviewing your portfolio once or twice a year.

    Common Mistakes College Students Should Avoid When Investing $100

    In fact, choosing the Best Investments for College Students with $100 is only the beginning. As a result, many beginners lose money not because they choose the wrong investment, but because they make avoidable mistakes. Additionally, understanding these common mistakes can help you invest with more confidence and build long-term wealth.

    Investing Without a Clear Goal

    Additionally, many students start investing simply because everyone else is doing it. Before investing, decide whether your goal is long-term wealth, passive income, or gaining investing experience. A clear goal helps you make better financial decisions.

    Ask Yourself Before Investing

    • Then, why am I investing?
    • Additionally, in fact, how long can I keep this money invested?
    • Furthermore, what is my financial goal?

    Trying to Get Rich Quickly

    Moreover, one of the biggest mistakes beginners make is chasing quick profits. In addition, successful investing is based on patience, consistency, and long-term thinking—not overnight success.

    Focus on Long-Term Growth

    • Moreover, invest regularly.
    • Finally, ignore short-term market noise.
    • Specifically, notably, stay invested during market ups and downs.

    Furthermore, learn more from Behavioral Finance.

    Ignoring Diversification

    Specifically, notably, putting your entire $100 into a single stock increases risk. Specifically, diversifying your investments through index funds or ETFs can provide better stability and reduce the impact of market volatility.

    A Smarter Strategy

    • Additionally, first, diversify your investments.
    • Additionally, review your portfolio yearly.
    • Furthermore, next, avoid emotional investing.

    Additionally, for example, for example, explore Morningstar to compare funds and portfolios.

    Final Takeaway

    Additionally, the Best Investments for College Students with $100 are the ones that match your goals, fit your risk tolerance, and help you stay invested consistently. For example, start small, keep learning, and remain patient. Specifically, over time, those small investments can become the foundation of lasting financial success.

    Consequently, frequently Asked Questions (FAQs)

    Can college students really start investing with just $100?

    In addition, for example, yes. In addition, many modern investment platforms allow college students to start investing with as little as $100. You can invest in Index Funds, ETFs, or Fractional Shares, making it easier to begin your investing journey without needing a large amount of money.

    What is the best investment for college students with $100?

    However, for most beginners, Index Funds are often considered one of the Best Investments for College Students with $100 because they offer diversification, lower risk, and long-term growth potential. However, the best choice depends on your financial goals and risk tolerance.

    Practical Steps & Actionable Tips for best investments for college students

    Can I lose money if Always invest $100?

    Consequently, yes. However, every investment carries some level of risk, especially in the stock market. However, investing in diversified assets like Index Funds or ETFs and staying invested for the long term can help reduce risk over time.

    4. Therefore, should I choose Index Funds or ETFs as a beginner?

    Therefore, both are excellent options for beginners. In fact, index Funds are ideal for long-term, hands-off investing, while ETFs offer more flexibility because they can be traded throughout the day. Particularly, your choice should depend on your investing style and financial goals.

    Actionable Advice and Practical Tips for best investments for college students

    Conclusion
    Finding the Best Investments for College Students with $100 doesn’t require a large budget—it requires the right mindset and a smart strategy. By starting early, choosing beginner-friendly investments like Index Funds or ETFs, and investing consistently, you can build a strong financial foundation for the future.
    Remember, successful investing isn’t about getting rich overnight. It’s about making informed decisions, staying patient, and allowing your investments to grow over time. In fact, even your first $100 can be the beginning of a lifelong wealth-building journey.
    Related Articles
    How to Start Investing with Little Money
    Best Budgeting Tips for College Students
    Index Funds vs ETFs for Beginners

    Written & Researched by Asif Khan

    best investments for college students: Asif Khan - Lead Research Editor
    Written & Researched by Asif Khan
    Founder & Lead Financial Editor PaisaKmao.de

    Additionally, over 4 years of active personal finance research in Indian markets. Consequently, focused on transparent, math-backed guides to help students and young professionals build wealth and manage money smartly.
    Connect With Asif Khan: