Planning for multiple financial goals can feel overwhelming. This simple guide shows you how to prioritize your goals, set realistic targets, calculate monthly savings, and stay on track for 2027.
Saving for one goal is simple. But when you have several goals at the same time—such as an emergency fund, annual expenses, a new laptop, a trip, or future needs—it can become difficult to know where your money should go first.
The key is not to save for everything equally. You need to organize multiple savings goals, set priorities, and decide how much to save for each goal based on its deadline and importance.
In this guide, you’ll learn how to organize your savings goals, set realistic targets, calculate your monthly savings, and create a simple plan you can follow before 2027.
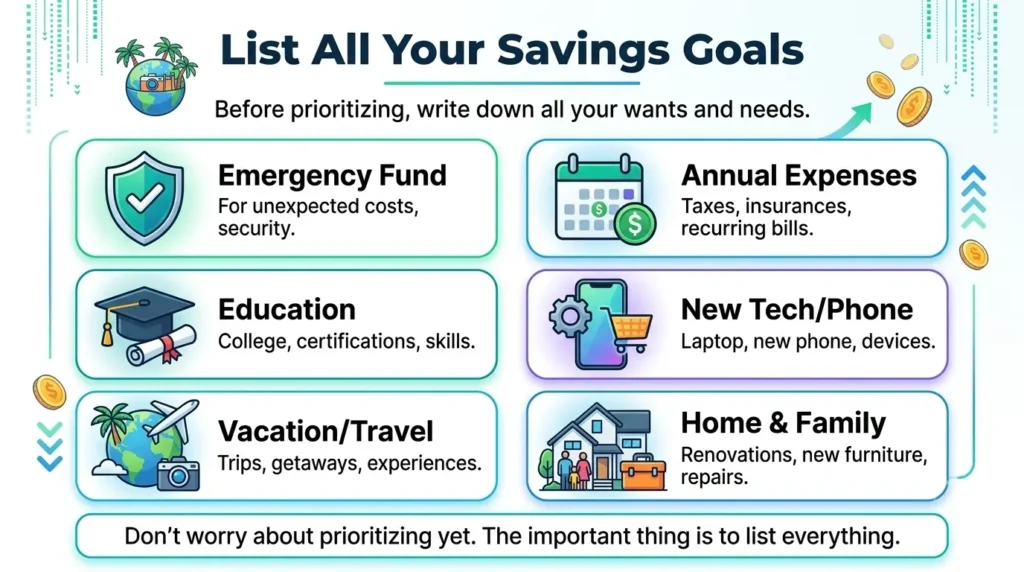
Step 1: List All Your Savings Goals
Before deciding how much to save for each goal, write down everything you want or need to save for.
Include both important financial goals and upcoming expenses, such as:
Emergency fund
Annual bills or expenses
Education
New phone or laptop
Vacation or travel
Home or family expenses
Other planned purchases
Don’t worry about prioritizing them yet. The first goal is simply to get a clear picture of where your money may need to go.
Once you have listed everything, you can group the goals by time frame, importance, and deadline. This makes it much easier to decide which goals should receive more attention first.
Step 2: Separate Short-Term, Medium-Term, and Long-Term Savings Goals
Not every savings goal has the same deadline. A bill due next month needs a different approach from a car you want to buy in three years or a future financial goal that may take much longer.
That is why one of the easiest ways to organize multiple savings goals is to separate them by time frame.
Short-Term Savings Goals
Short-term goals are goals you expect to reach relatively soon, such as annual bills, emergency expenses, a phone, or a planned purchase.
These goals usually need more immediate attention because their deadlines are closer.
Medium-Term Savings Goals
Medium-term savings goals sit between immediate expenses and long-term financial goals. They may take several months or a few years to complete, depending on the size and deadline of the goal.
Common examples include:
Buying a car
Saving for education or training
A major home expense
Starting a small business
Saving for a wedding or major event
Preparing for a large planned purchase
The advantage of a medium-term goal is that you have more time to build the money. Instead of trying to save a large amount at once, you can break the target into smaller monthly savings contributions.
For example, suppose your goal is to save $3,000 in 30 months.
$3,000 ÷ 30 = $100 per month
So your basic monthly savings target would be $100.
Goal
Target
Time Remaining
Monthly Target
Priority
Education
$3,000
30 months
$100
High
Car fund
$6,000
36 months
$167
Medium
Major purchase
$1,500
24 months
$63
Low
This gives you a clearer picture of how much each goal requires instead of simply saving money without knowing whether you are on track.
What If the Monthly Amount Is Too High?
This is where a realistic savings plan matters.
If your calculated monthly contribution does not fit your budget, you have several options:
Extend the deadline if possible.
Reduce the target amount.
Give the goal a lower priority.
Temporarily focus on a more important goal.
Look for ways to reduce expenses or increase available savings.
You do not have to abandon a goal just because the first calculation does not fit your current cash flow.
The Consumer Financial Protection Bureau recommends breaking savings goals into manageable targets and considering the amount needed and the time available when creating a savings plan.
For a broader reference, you can also review the CFPB’s savings and goal-setting tools, which include tools for setting goals, planning savings, tracking money, and preparing for large purchases.
For your own numbers, you can use our budget calculator to see how your income and expenses affect the amount available for different savings goals.
The important point is simple: medium-term goals should have a target, deadline, and monthly contribution. Once those three numbers are clear, a large future expense becomes much easier to manage.
Step 3: Prioritize Your Savings Goals
Once you have separated your goals by time frame, the next step is to decide which savings goals should come first.
When you have multiple savings goals, you do not always need to divide your money equally. Some goals are more important because they protect your financial stability, have a fixed deadline, or could create a bigger problem if you do not prepare for them.
A simple priority system can help you decide where your monthly savings should go first.
Start With Financial Safety
Before putting a large amount toward optional goals, consider whether you have enough money set aside for unexpected expenses.
An emergency fund can help cover unexpected costs such as an urgent repair, medical expense, or temporary loss of income without forcing you to depend on debt.
Your financial priorities will depend on your situation, but building a basic financial safety net is often an important starting point.
For a broader overview, read our guide to the 7 rules of personal finance, which explains the role of budgeting, emergency savings, debt management, and long-term financial goals.
Consider the Deadline and Consequences
Not every savings goal has the same level of urgency. A goal with a fixed deadline may need more attention than a goal that can be delayed.
Before deciding how to divide your savings, ask yourself:
Does this expense have a fixed deadline?
What happens if I do not save enough by that date?
Is the goal essential or optional?
Can I delay the goal without creating a financial problem?
Could failing to prepare lead to debt or another financial cost?
Does this goal protect my basic financial needs?
For example, an annual insurance payment due in three months may deserve more attention than a vacation planned for next year.
The vacation can still be an important savings goal, but its deadline and consequences are different.
Use a High, Medium, and Low Priority System
A simple three-level priority system makes it easier to manage multiple savings goals without feeling overwhelmed.
Priority
Type of Goal
Example
High
Financial safety or essential deadline
Emergency fund, essential annual expense
Medium
Important planned expense
Education, major repair, vehicle
Low
Optional or flexible goal
Vacation, new gadget, entertainment
This does not mean low-priority goals should never receive money. It simply means they should not take money away from a more important financial need when your available savings are limited.
How to Divide Money Between Savings Goals
If your monthly savings amount is limited, a useful starting order is:
Financial safety
Essential upcoming expenses
Important planned goals
Optional goals
For example, suppose you can save $300 per month and you have three goals:
Emergency fund — High priority
Education — Medium priority
Vacation — Low priority
Instead of automatically giving each goal $100, you could direct more of your available savings toward the emergency fund and education while making a smaller contribution toward the vacation.
The exact amounts depend on your income, essential expenses, current savings, and the deadlines of your goals.
One common mistake when managing multiple savings goals is assuming that every goal should receive the same amount of money.
For example, imagine you have $500 available for savings and the following goals:
Goal
Amount Needed
Deadline
Priority
Emergency fund
$1,500
Flexible
High
Annual bill
$600
4 months
High
Laptop
$1,000
10 months
Medium
Vacation
$1,200
12 months
Low
An equal split would give each goal $125. But the annual bill has a much closer deadline, while the vacation may be more flexible.
Your savings plan should reflect importance and urgency, not simply equality.
What If Two Savings Goals Have the Same Priority?
When two goals are equally important, use their deadlines to decide which one should receive more attention.
As a simple rule, consider the goal that:
Has the earlier deadline.
Requires a larger monthly contribution.
Has greater consequences if you miss the target.
You can also change the priority later. Your income, expenses, deadlines, and financial goals may change, so your savings plan should be flexible enough to change with them.
Keep Your Savings Priorities Simple
You do not need a complicated financial planning system to organize multiple savings goals.
For each goal, know these four things:
What you are saving for
How much you need
When you need it
How important it is compared with your other goals
Once these details are clear, it becomes much easier to decide where your money should go each month.
The goal is not to create a perfect plan that never changes. The goal is to build a practical savings plan that gives every dollar a purpose while keeping your most important financial goals on track.
Step 4: Set a Target Amount and Deadline for Every Savings Goal
Once you know which savings goals are most important, give each goal a specific target amount and deadline.
“I want to save more money” is a good intention, but it is difficult to follow because there is no clear finish line. A better savings plan tells you exactly how much you need, when you need it, and how much you should save each month.
This approach can make multiple savings goals much easier to organize and track.
Give Every Financial Goal a Specific Target
Start by deciding the approximate amount you need for each goal.
For example, instead of writing:
Save for a laptop
Save for a trip
Save for education
Turn them into measurable goals:
Laptop — $1,000
Trip — $1,500
Education — $3,000
A specific target gives you something you can calculate against. It also makes it easier to see whether your current monthly savings are enough.
Set a Realistic Savings Deadline
After deciding the target amount, choose when you want or need to reach it.
Your deadline can be based on:
A fixed bill or payment date
A planned purchase
A school or education deadline
A planned trip or event
A personal financial milestone
A timeframe that is realistic for your income
Try not to choose a deadline simply because it sounds good. A deadline should be realistic enough that you can continue making the required monthly contribution without putting your essential expenses under pressure.
Calculate the Time You Have Left
Once you know the target and deadline, calculate how many months you have remaining.
For example:
Goal
Target
Time Available
Approx. Monthly Saving
Laptop
$1,000
10 months
$100
Trip
$1,500
12 months
$125
Education
$3,000
24 months
$125
These numbers give you a starting point for building your monthly savings plan. In the next step, we will use the same information to calculate the required monthly contribution more precisely.
Use the SMART Approach for Savings Goals
A useful way to make a savings goal clearer is to make it specific and measurable, with a realistic timeframe.
For example:
Vague goal: “I want to save for a laptop.”
Clear goal: “I want to save $1,000 for a laptop within 10 months.”
The second goal gives you three important pieces of information:
You do not need to convert these amounts into one currency. Keep each goal in the currency you will actually spend.
What If the Target Is Too High for Your Income?
This is where your savings plan becomes practical.
Suppose you calculate that you need to save $400 per month for several goals, but after essential expenses you can realistically save only $250.
Do not simply assume you have failed. Rework the plan.
You could:
Extend the deadline
Reduce the target amount
Give higher priority to the most important goal
Temporarily pause a lower-priority goal
Reduce unnecessary expenses
Increase your savings contribution when your income rises
A realistic savings target that you can consistently follow is usually more useful than an aggressive target that makes your monthly budget impossible to maintain.
Keep Your Savings Goals in One Simple Table
Once you have several goals, put the important numbers in one place. This makes it easier to see the complete picture instead of keeping separate notes in your head.
Goal
Target
Saved
Remaining
Deadline
Priority
Emergency fund
$1,500
$600
$900
Flexible
High
Laptop
$1,000
$250
$750
10 months
Medium
Vacation
$1,200
$300
$900
12 months
Low
This simple savings tracker gives you a quick view of what you are saving for, how much you have already saved, what remains, and which goals deserve the most attention.
Once every goal has a target and deadline, the next step is to calculate exactly how much you need to save each month.
Step 5: Calculate Your Monthly Savings for Each Goal
Now that every savings goal has a target amount and deadline, you can calculate how much you need to save each month.
This is the point where a list of financial goals becomes an actual savings plan. Instead of guessing how much to put aside, you can work backward from the amount you need and the time available.
For example, suppose you want to save $1,200 for a planned purchase and you have 12 months remaining.
$1,200 ÷ 12 = $100 per month
So, you would need to set aside approximately $100 each month to reach the target, assuming the money you save does not earn additional returns and there are no extra costs.
Calculate Each Savings Goal Separately
When you have multiple savings goals, calculate the monthly contribution for each one instead of combining all the targets into one number.
Goal
Amount Remaining
Months Remaining
Monthly Savings
Emergency fund
$1,000
10
$100
Laptop
$900
9
$100
Vacation
$1,200
12
$100
In this example, the total monthly requirement would be:
$100 + $100 + $100 = $300 per month
Now you can compare that $300 requirement with the amount your monthly budget can realistically provide.
Check Your Monthly Savings Capacity
Before committing to a savings target, look at your actual cash flow.
If your savings goals require $300 per month and you can realistically save $400, the plan has some room for unexpected expenses or faster progress.
If your goals require $550 but your realistic savings capacity is only $400, you need to adjust the goals rather than forcing an unrealistic budget.
Use a Budget Calculator to Find Your Available Savings
Working out your income and expenses manually can become difficult when you have several financial goals.
You can use our Budget Calculator to organize your income and spending and get a clearer idea of how much money may be available for savings each month.
Once you know your available savings amount, you can compare it with the monthly contribution required for each goal.
What If Your Monthly Savings Requirement Is Too High?
This is one of the most important parts of creating a realistic savings plan.
If the numbers do not fit your budget, do not simply cut essential expenses or put yourself under unnecessary financial pressure. Rework the plan.
You can:
Extend the deadline: Give yourself more months to reach the target.
Reduce the target: Look for a lower-cost version of the planned purchase.
Prioritize: Put more money toward essential or time-sensitive goals.
Pause a lower-priority goal: Temporarily stop funding a flexible goal.
Increase your savings capacity: Reduce unnecessary spending or direct future extra income toward the goal.
Review the target: Make sure the original amount is still realistic.
A savings plan should fit your real financial situation. A target that looks impressive on paper but cannot be maintained every month is not a useful target.
Use the Deadline to Adjust Your Monthly Contribution
Your monthly savings requirement can change when the deadline changes.
Target
Deadline
Monthly Savings
$1,200
6 months
$200
$1,200
12 months
$100
$1,200
18 months
About $67
This shows why the deadline matters. The same savings goal can require very different monthly contributions depending on how much time you have.
Do Not Forget the Amount You Have Already Saved
If you have already saved part of the money, calculate the monthly requirement using the remaining amount, not the original target.
This makes your savings target more accurate and prevents you from saving more than necessary for the same goal.
Keep a Small Buffer for Real Life
Monthly budgets do not always go exactly as planned. An unexpected expense can temporarily reduce the amount you are able to save.
For that reason, avoid building a savings plan that uses every available dollar with no flexibility.
If your calculations show that you can save $400 per month, but your goals require exactly $400, consider whether you need some breathing room for irregular expenses before committing to the full amount.
This is especially important when your income changes from month to month.
Once you calculate the monthly requirement for every goal, add them together and compare the total with your realistic monthly savings capacity.
If required savings ≤ available savings: Your plan may be realistic.
If required savings > available savings: Prioritize the goals and adjust the deadlines, targets, or contributions.
This simple comparison can prevent a common problem: creating too many savings goals without checking whether your income can actually support them.
In the next step, we will look at how to divide your available money between multiple savings goals when you cannot fully fund every goal at the same time.
Step 6: How to Divide Money Between Multiple Savings Goals
Knowing how much you need to save each month is only half the job. When you have several financial goals, you also need to decide how to divide your available savings between them.
You do not have to give every goal the same amount. The right approach depends on each goal’s priority, deadline, target amount, and how much you can realistically save after your regular expenses.
The aim is to create a savings plan that is realistic enough to follow every month while still moving your most important financial goals forward.
First, Know How Much You Can Save Each Month
Before deciding how much goes into each goal, calculate your available monthly savings.
For example, if your monthly income is $2,500, essential expenses are $1,700, and other required payments and regular spending total $400, you may have around $400 available for savings.
You can use our Budget Calculator to organize your income and expenses and get a clearer picture of how much you may be able to save each month.
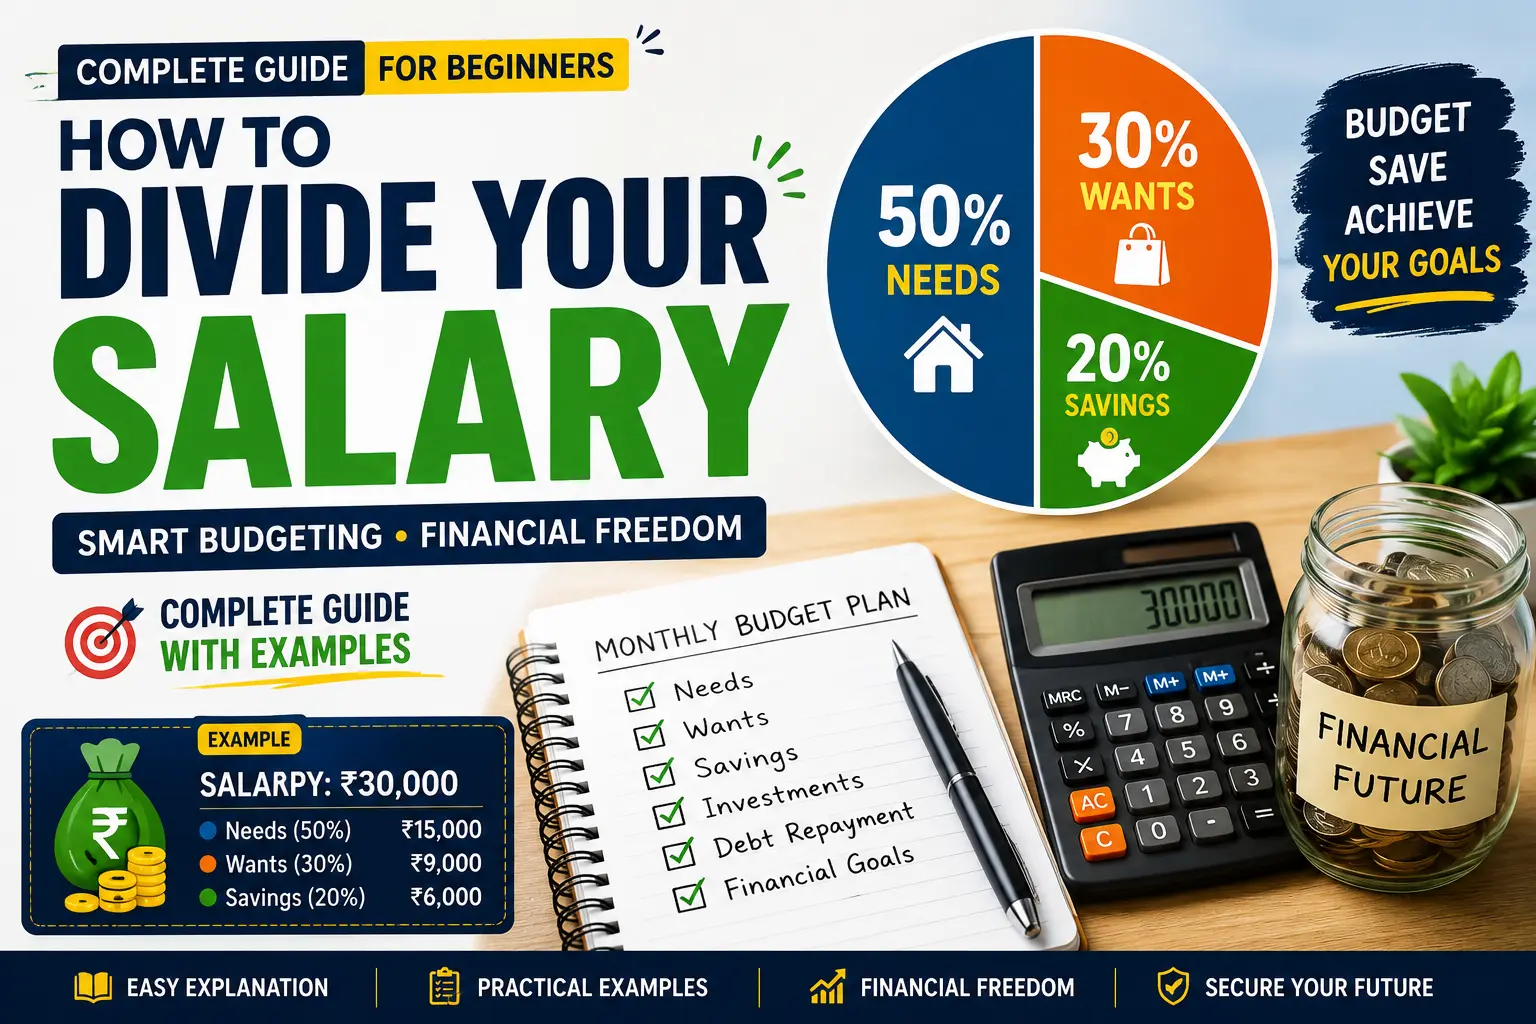
If you want a broader approach to dividing your income between spending, savings, and financial priorities, you can also read our guide on how to divide your salary for beginners.
Method 1: Equal Contribution for Multiple Savings Goals
The simplest approach is to divide your available savings equally between your goals.
For example, if you can save $300 per month and have three goals, you could contribute:
Goal 1 — $100 per month
Goal 2 — $100 per month
Goal 3 — $100 per month
This method is easy to understand and can work well when the goals have similar importance and similar deadlines.
However, equal contributions are not always the best option. If one goal has a much earlier deadline or greater financial importance, it may need a larger share of your monthly savings.
Method 2: Priority-Based Savings
With a priority-based savings plan, you give more of your available money to goals that are more important and reduce contributions to goals that can wait.
A simple order could be:
Financial safety
Essential upcoming expenses
Important planned goals
Optional goals
For example, if you are building an emergency fund while also saving for a vacation, you may decide that the emergency fund deserves a larger contribution because it provides greater financial protection.
This method can be especially useful when your monthly savings are limited and you cannot fully fund every goal at the same time.
Method 3: Deadline-Based Savings
Another practical method is to divide your savings according to how soon each goal needs to be funded.
Suppose you have the following goals:
Goal
Amount Remaining
Time Remaining
Priority
Annual bill
$600
4 months
High
Laptop
$1,000
10 months
Medium
Vacation
$1,200
12 months
Low
The annual bill has the closest deadline, so it may need more immediate attention. The laptop and vacation goals have more time, which gives you greater flexibility with their contributions.
This method is particularly useful for short-term and medium-term savings goals where missing a deadline could create a financial problem.
Which Savings Method Should You Choose?
There is no single method that works for every person or every savings goal. You can choose one method or combine several.
Method
Best For
Main Advantage
Equal contribution
Goals with similar importance
Simple and easy to maintain
Priority-based
Limited monthly savings
Focuses money on important goals
Deadline-based
Goals with different due dates
Helps prevent missed deadlines
For example, you could use a priority-based approach for your emergency fund and essential expenses, then divide whatever remains between flexible goals.
Example: Dividing $500 Between Multiple Savings Goals
Suppose you have $500 available for savings each month and four goals:
Goal
Priority
Monthly Contribution
Emergency fund
High
$200
Annual expenses
High
$150
Laptop
Medium
$100
Vacation
Low
$50
Total
$500
This is only an illustrative example, not a universal rule. Your own allocation should be based on your income, expenses, current savings, deadlines, and priorities.
The important idea is that you do not need to divide your money equally just because you have multiple goals.
Match Your Savings Allocation With Your Financial Plan
Your savings goals should not exist separately from the rest of your budget. They should fit into your overall financial plan.
Consider:
Your monthly income
Essential living expenses
Existing debt or required payments
Emergency savings
Upcoming annual expenses
Short-term financial goals
Longer-term goals
Our guide to financial planning for beginners explains how different money priorities can be organized into a broader financial plan.
This is completely normal. Having several savings goals does not mean you have to make progress on all of them at the same speed.
If your required monthly contributions are higher than your available savings, you can:
Focus on the highest-priority goal first.
Give more time to a flexible goal.
Reduce the target amount if appropriate.
Temporarily pause a lower-priority goal.
Redirect money to another goal after completing one target.
Increase contributions later when your financial situation improves.
A realistic savings plan is better than a complicated plan that consistently leaves you short of money.
Review and Rebalance Your Savings Goals
Your savings allocation does not need to remain unchanged throughout the year.
Review your plan at least once a month and consider whether:
Your income has changed.
Your regular expenses have increased or decreased.
A deadline is getting closer.
You have already reached one of your targets.
A new essential expense has appeared.
One goal has become more or less important.
For example, once you finish saving for an annual expense, you can redirect that monthly contribution toward your next priority instead of leaving the money unassigned.
A Simple Rule for Dividing Your Savings
If you are unsure where your money should go, ask yourself three questions every month:
What is most important right now?
Which goal has the nearest deadline?
How much can I realistically save this month?
Your answers can help you decide how to divide money between multiple savings goals without making your budget unnecessarily complicated.
The goal is not to save the same amount for everything. The goal is to give your available money a clear purpose while keeping your most important financial goals on track.
How many savings goals should I have at one time?
There is no fixed number of savings goals you should have. Start with the goals that are most important and realistic for your current income. Too many goals can make it harder to stay consistent, so focus on your priorities first.
Should I save for multiple goals at the same time?
Yes. If your budget allows, you can save for several goals at the same time. Give more money to urgent or essential goals and smaller amounts to flexible goals.
What should I do if I cannot save enough for all my goals?
Prioritize your most important goals instead of trying to fund everything equally. You can reduce optional targets, extend deadlines, or increase your monthly savings later when your income improves.
How often should I review my savings goals?
Review your savings plan at least once a month. Check your progress, remaining amount, deadlines, and monthly contributions. Adjust the plan whenever your income, expenses, or priorities change
Final Thoughts: How to Organize Multiple Savings Goals
Managing multiple savings goals becomes much easier when every goal has a clear target, deadline, and priority. Instead of trying to save for everything equally, focus your money on what matters most and adjust your plan as your situation changes.
Start small, stay consistent, and review your progress each month. A simple plan you can follow is more valuable than a complicated plan you cannot maintain.
Hi, I’m Asif Khan, the voice behind paisakmao.de. For the past two years, I’ve been blogging about financial education, income skills, and mindset development for students and young minds. My mission is to empower every youth with financial literacy and practical money-making skills at an early age. Through paisakmao.de, I share actionable guides for students to start earning early, money wisdom that schools don’t teach, and mindset lessons from successful people and modern psychology. Whether you’re a teenager looking to earn your first income or a student exploring side hustles, you’re in the right place. Financial freedom begins with the right mindset and the right knowledge. Let’s grow, earn, and evolve together — welcome to the movement!
Managing money can feel difficult when small purchases keep adding up throughout the month. The cash stuffing method offers a simple way to give each spending category a clear limit and make your budget easier to see and follow.Instead of keeping your entire spending budget in one place, you divide cash into separate categories such as groceries, transportation, eating out, or personal spending. When an envelope gets low, you know exactly how much is left for that category.In this guide, you’ll learn how cash stuffing works, how to set up your first envelopes, how much to allocate to each category, and how to adapt the method for different budgets and payment habits.
What Is the Cash Stuffing Method for Beginners?
The cash stuffing method for beginners is a simple way to organize your spending by separating money into different categories. Instead of keeping all your spending money together, you decide how much you want to use for groceries, transportation, eating out, entertainment, or other everyday expenses.
The basic idea is simple: give your money a purpose before you spend it.
For example, if you have $500 available for flexible spending, you might divide it between several categories instead of treating the entire $500 as available for anything. In India, the same idea could be applied to ₹40,000 of monthly income or spending money. The actual amounts depend on your income, bills, and personal circumstances.
How Does Cash Stuffing Work
Traditional cash stuffing uses physical envelopes. Each envelope represents a spending category, and you place the amount you’ve budgeted for that category inside it.
A simple setup might include:
Groceries
Transportation
Eating out
Entertainment
Personal spending
Miscellaneous
When you spend money, you take it from the relevant category. If your grocery envelope has $150 left, for example, you know that $150 is what remains for groceries under that budget.
The system is closely related to the cash envelope system and traditional envelope budgeting. The Consumer Financial Protection Bureau (CFPB) has also discussed the envelope approach as a way of separating money for different spending categories.
Why Do People Use Cash Stuffing?
The main attraction is visibility.
When your spending money is separated into categories, it can be easier to notice how much you have left before making another purchase.
That doesn’t mean cash stuffing will automatically stop overspending. It simply gives you a clear spending boundary to work with.
For someone who regularly wonders, “Where did my money go this month?”, seeing separate amounts for different categories can make budgeting feel more concrete.
Does Cash Stuffing Mean Using Only Physical Cash?
Not necessarily.
Physical envelopes are the traditional version, but the underlying idea can also work with digital budgeting.
Someone in the US might use cash envelopes for groceries and entertainment while keeping rent and online bills in a bank account.
A UK reader might use digital “pots” for some categories.
In India, where UPI and digital payments are widely used, someone may prefer a hybrid approach—keeping some categories in cash while tracking other spending digitally.
The important principle is separating money by purpose, not carrying every expense in your wallet.
Cash Stuffing at a Glance
Element
What it means
Income
Money available for your budget
Categories
Different types of spending
Envelopes
Separate places for each category
Spending limit
Amount assigned to a category
Tracking
Recording what you spend
Review
Checking what worked and what needs adjusting
This is only the basic idea. The next step is understanding how to actually set up a cash stuffing budget, choose the right categories, and decide how much money should go into each one.
How Much Money Should You Put in Each Cash Stuffing Envelope?
Once you know your income and regular expenses, the next step is deciding how much money to put into each envelope.
There is no single amount that works for everyone. Your cash stuffing budget should reflect your income, essential expenses, family situation, location, and normal spending habits.
A good starting point is to look at what you actually spend rather than copying someone else’s envelope amounts.
Start With Your Real Spending
Before setting your limits, look at your recent bank statements, receipts, or budgeting records.
You might notice that groceries regularly cost more than you expected, while entertainment spending is much smaller.
That information is useful.
Try to identify the categories where your spending is both variable and controllable.
Common examples include:
Groceries
Eating out
Transportation
Entertainment
Clothing
Personal spending
Household purchases
Miscellaneous expenses
If you don’t know your spending patterns yet, track them for a few weeks before creating strict limits.
This makes the cash envelope system more realistic and easier to maintain.
Separate Fixed Bills From Flexible Spending
Cash stuffing doesn’t require you to put every expense into a physical envelope.
Some expenses are already predictable or automatically paid from your bank account.
For example:
Rent or mortgage
Insurance
Loan payments
Subscriptions
Internet and phone bills
Other recurring payments
Cash envelopes are usually more useful for spending that can change from week to week.
The goal is not to make your finances complicated. It’s to create a clear boundary around the spending you can control.
A Simple Cash Stuffing Example
Imagine someone in the US takes home $2,500 a month.
After accounting for essential bills, savings, and other financial commitments, they have $600 available for selected flexible expenses.
They might start with:
Category
Example Amount
Groceries
$300
Transportation
$100
Eating out
$75
Personal spending
$75
Miscellaneous
$50
Total
$600
These numbers are only an example. They are not recommended spending limits.
A person in the UK might work with £500, while someone in India might have ₹10,000 available for similar variable categories.
The currency and cost of living change, but the basic idea remains the same: divide the money according to your own spending needs.
Don’t Set Unrealistic Envelope Limits
One common beginner mistake is trying to make the budget look perfect on paper.
Suppose you normally spend around $350 on groceries but decide to put only $200 into your grocery envelope because you want to save more.
If you run out of money halfway through the month, the problem may not be the cash stuffing method. Your original limit may simply have been unrealistic.
A better approach is to start with your actual spending and make gradual adjustments
What If Your Income Changes?
The cash stuffing method for beginners can also be adapted for irregular income.
If you receive money weekly, work freelance, or have changing monthly income, you don’t necessarily need to decide your entire month’s envelope amounts at once.
Instead, you can allocate money when you actually receive it.
This helps prevent a common mistake: filling your envelopes first and discovering later that you don’t have enough money for an important bill.
Start Small
You don’t need ten or twenty envelopes on your first attempt.
Start with three to five categories that are genuinely useful for your spending habits.
For example:
Groceries
Transportation
Eating out
Personal spending
Miscellaneous
After a month, review what happened.
If one envelope consistently has money left over, you can reconsider its limit.
If another runs out too quickly, look at your actual spending before simply adding more money.
Your first cash stuffing budget doesn’t need to be perfect. It needs to be realistic enough to help you understand and control your spending.
What Categories Should You Use for Cash Stuffing?
You don’t need a separate envelope for every expense. Start with the spending categories where you are most likely to overspend.
Best Cash Stuffing Categories for Beginners
Common categories include:
Groceries — food and household shopping
Transportation — fuel, bus, train, or local travel
Eating Out — restaurants, snacks, and coffee
Personal Spending — small personal purchases
Entertainment — movies, games, and hobbies
Gifts — birthdays, festivals, and special occasions
Category
Example
Groceries
$250 / £200 / ₹8,000
Transportation
$100 / £80 / ₹3,000
Eating Out
$75 / £60 / ₹2,500
Personal
$75 / £60 / ₹2,500
These amounts are only examples. Your actual budget should depend on your income and regular spending.
Don’t Put Every Expense in an Envelope
Fixed expenses such as rent, mortgage payments, electricity bills, and subscriptions usually don’t need physical cash envelopes. You can continue paying them digitally or through your bank account.
For irregular expenses like gifts, clothing, or annual costs, a sinking fund can be useful. MoneyHelper explains sinking funds as a way to prepare for expenses that don’t happen every month.
If you are unsure how much you can actually afford for each category, first use the Budget Calculator.
Start small: 3–5 useful categories are usually easier to manage than 15–20 envelopes. Once the system becomes a habit, you can add more categories if needed.
How to Start Cash Stuffing: A Step-by-Step Setup
Starting the cash stuffing method is easier when you follow a simple routine instead of trying to change all your spending habits at once. The basic idea is to decide your limits, separate the money into categories, and track what you spend.
1. Choose Your Budget Period
First, decide how often you want to organize your envelopes.
You can use a:
Weekly system if you prefer tighter spending control
Biweekly system if you get paid every two weeks
Monthly system if you receive a monthly salary
Your choice should match your income schedule and spending pattern.
If your income is very tight and covering basic expenses is already difficult, see our paycheck-to-paycheck budgeting guide for a more focused approach.
The goal is not to follow a perfect envelope system. The goal is to create a spending system that you can realistically follow every pay period.
What Happens When a Cash Stuffing Envelope Runs Out?
One of the biggest questions beginners have is: What should you do when an envelope reaches $0 before the end of the month?
It doesn’t automatically mean your budget has failed. It may simply mean that your spending limit needs to be reviewed.
Check Before Moving Money
First, ask whether the expense is actually necessary.
For example, if your entertainment envelope is empty, you may decide to wait until the next budget period. But if your grocery budget is short because food prices were higher than expected, the situation may be different.
A simple rule is:
Needs first, wants second.
Situation
What You Can Do
Non-essential spending
Wait until the next period
Essential expense
Consider moving money from a lower-priority category
Unexpected expense
Use an appropriate emergency/savings fund
Budget repeatedly runs short
Recalculate your category limits
Can You Move Money Between Envelopes?
Yes. Your budget doesn’t have to be completely rigid.
Suppose your Eating Out envelope has $40 left, while your Groceries envelope needs another $25. If groceries are the priority, you could move $25 from Eating Out to Groceries.
The important part is to record the transfer so you know where your money went.
What If This Happens Every Month?
If the same envelope runs out repeatedly, don’t simply keep adding money to it.
Look at your actual spending and adjust the budget.
For example, if you regularly spend $300 on groceries but your budget allows only $250, your original limit may not reflect your real situation.
Our salary division guide can help you review how your income is being allocated across different priorities.
What About Leftover Money?
If an envelope still has money at the end of the period, you have several options:
Carry it into the next period
Move it toward a planned expense
Add it to savings
Keep a small buffer for future spending
For irregular expenses, a sinking-fund approach can make budgeting easier. MoneyHelper’s sinking-fund guidance explains how setting money aside over time can help prepare for expenses that don’t happen every month.
The goal of cash stuffing isn’t to punish yourself for spending. It’s to make your spending choices visible and intentional. If you’re already struggling to cover essential expenses, our paycheck-to-paycheck budgeting guide covers a more focused approach for tight budgets.
Cash Stuffing vs. Digital Budgeting: Which Is Better?
Cash stuffing works by making your spending limits visible through separate cash envelopes. Digital budgeting uses bank accounts, budgeting apps, spreadsheets, or digital savings pots to organize the same idea electronically.
Neither method is automatically better. The right choice depends on how you normally spend and how often you use cash.
Feature
Cash Stuffing
Digital Budgeting
Spending visibility
Very high
High
Physical cash needed
Yes
No
Card/UPI payments
Limited unless hybrid
Easy
Tracking
Manual
Often automatic
Best for
Controlling flexible spending
Digital-first spending
When Cash Stuffing Can Work Well
Physical cash can make a spending limit feel more concrete. Once the envelope is nearly empty, you can immediately see that you’re approaching your limit.
This can be particularly useful for categories such as groceries, eating out, entertainment, or personal spending.
When Digital Budgeting Makes More Sense
Cash isn’t practical for every expense. Rent, subscriptions, online shopping, bills, and many everyday transactions are normally paid digitally.
That’s why a hybrid cash stuffing system can be useful. You might use cash for flexible spending while keeping fixed bills and other payments in your bank account.
For readers in the UK, MoneyHelper’s jam jar approach shows how separating money into different pots can also be done digitally.
In India, where digital payments are widely used, you can combine cash envelopes with separate bank-account or savings categories rather than forcing every expense into physical cash.
Which Should Beginners Choose?
Start with the method you are most likely to follow consistently.
If you often overspend on small purchases, physical envelopes may give you stronger spending awareness. If you rarely use cash, a digital or hybrid approach may be more practical.
The goal isn’t to use cash simply because it’s called “cash stuffing.” The goal is to give every spending category a clear limit and make your money easier to manage.
Common Cash Stuffing Mistakes Beginners Should Avoid
Cash stuffing looks simple, but a few common mistakes can make the system difficult to maintain. The good news is that most of them are easy to fix.
1. Creating Too Many Envelopes
You don’t need an envelope for every small expense.
Starting with 15–20 categories can make your budget feel like another chore. Begin with 3–5 important spending categories and add more only when necessary.
2. Setting Unrealistic Limits
A budget shouldn’t be based on what you wish you spent. It should reflect your actual situation.
If you normally spend $300 on groceries but set a $150 limit without a realistic plan to reduce costs, the envelope may run out quickly.
Review your real spending before changing your limits. Our Budget Calculator can help you organize your numbers.
3. Trying to Use Cash for Everything
Not every expense needs a physical envelope.
Rent, subscriptions, online payments, and many bills can remain digital. A hybrid budgeting system can be more practical than forcing every payment into cash.
4. Forgetting to Track Spending
Cash can disappear quickly when you make several small purchases.
Write down each transaction or keep a simple note on your phone. This makes it easier to understand where your money is actually going.
5. Taking Money From Other Envelopes Without Recording It
Moving money between categories is sometimes reasonable. But repeatedly doing it without tracking the changes can hide the real problem.
If you keep taking money from groceries to cover entertainment, for example, your category limits may need to be reviewed.
6. Ignoring Irregular Expenses
Some expenses don’t appear every month but still need planning.
Gifts, annual subscriptions, clothing, repairs, and seasonal expenses can be handled through a sinking fund rather than pretending they don’t exist.
Don’t try to make your cash stuffing system perfect. Make it sustainable.
Start with a few categories, use realistic limits, track your spending, and adjust the system when your circumstances change. That’s what turns cash stuffing from a budgeting experiment into a habit you can actually maintain.
Is cash stuffing good for beginners?
Yes. Cash stuffing can be beginner-friendly because it gives each spending category a clear limit and makes it easier to see how much money is available.
How much money should I put in cash stuffing envelopes?
Use an amount that fits your actual budget. After essential expenses, divide your flexible spending money between categories such as groceries, transportation, personal spending, and entertainment.
What happens if I run out of money in an envelope?
Check whether the expense is essential. If it is, you can move money from a lower-priority category and record the transfer. For non-essential spending, waiting until the next budget period may be the better option.
Can I do cash stuffing without using physical cash?
Yes. You can use a digital or hybrid system with bank accounts, savings pots, spreadsheets, or budgeting apps. The principle remains the same: separate your money into spending categories with clear limits
Conclusion
The cash stuffing method can be a simple way to make everyday spending easier to understand and control. Instead of treating your entire budget as one amount, you give different spending categories clear limits.
You don’t need to start with a complicated system. Choose a few categories, set realistic amounts, track your spending, and adjust your envelopes when your real spending doesn’t match your original plan.
And remember, cash stuffing doesn’t have to mean using physical cash for everything. A digital or hybrid approach can work too, especially for bills and online payments.
The best budgeting system is the one you can understand, follow, and maintain consistently. Start small, learn from each budget period, and improve your system over time.
Hi, I’m Asif Khan, the voice behind paisakmao.de. For the past two years, I’ve been blogging about financial education, income skills, and mindset development for students and young minds. My mission is to empower every youth with financial literacy and practical money-making skills at an early age. Through paisakmao.de, I share actionable guides for students to start earning early, money wisdom that schools don’t teach, and mindset lessons from successful people and modern psychology. Whether you’re a teenager looking to earn your first income or a student exploring side hustles, you’re in the right place. Financial freedom begins with the right mindset and the right knowledge. Let’s grow, earn, and evolve together — welcome to the movement!
If your paycheck runs out before your next payday, budgeting can feel almost impossible—especially when your income is already low. The problem may not be unnecessary spending; your essential expenses may simply leave too little room.This guide explains how to budget when living paycheck to paycheck on a low income, find where your money is actually going, and create a practical plan to make each paycheck last longer.
Find Out Why Your Paycheck Runs Out Before Payday
Before changing your budget, first find out why your money is running out. If you don’t know where the shortage is coming from, cutting random expenses may not solve the problem.
Start with your take-home income for one pay period. Then list the expenses that must be paid before your next paycheck, such as housing, food, transportation, utilities, and required payments.
For example, if you receive ₹10,000 and need ₹4,000 for housing, ₹2,000 for food, ₹1,000 for transportation, and ₹1,500 for essential bills, you have ₹1,500 left.
Now ask yourself: Can that ₹1,500 realistically cover everything until your next payday?
If yes, the problem may be how the remaining money is being spent or when certain expenses occur. If no, your essential costs may already be leaving too little income available.
The same calculation works whether your paycheck is ₹10,000, $1,000, or £900. The amounts will differ, but the question stays the same: how much income is left after the expenses you cannot avoid?
This simple check helps you identify whether your main problem is spending, payment timing, or an income that is not enough to cover essential costs. Once you know the actual problem, you can build a budget around it instead of guessing where your money is going.
Calculate Your Minimum Amount Needed Until the Next Paycheck
Once you know why your paycheck is disappearing, calculate the minimum amount you actually need before the next payday. This gives you a clear spending limit instead of treating your whole paycheck as available money.
Start with the expenses that cannot reasonably be postponed until later. For example, if your next paycheck is 10 days away, include the food, transportation, bills, and other essential payments you need during those 10 days.
Suppose you receive ₹10,000 and your next paycheck is 10 days away:
Essential food: ₹2,000
Transportation: ₹1,000
Upcoming bill: ₹2,500
Other required expense: ₹1,000
Your minimum amount needed is ₹6,500.
That means the remaining ₹3,500 should not automatically be treated as spending money. It can become a buffer, cover an upcoming expense, or help reduce the pressure on your next paycheck.
The same method works with $1,000 or £900. The numbers will change depending on your location and expenses, but the principle remains the same: separate money you must use from money you can safely leave untouched.
This small calculation can change the way you look at each paycheck. Instead of asking, “How much money do I have?” you start asking, “How much of this money is actually available?”
Build a Paycheck Plan Around Your Essential Expenses
When you are living paycheck to paycheck, a budget should do more than divide your income into categories. It should help you control the timing of your money so that an expense due next week does not compete with today’s spending.
After calculating what you need until your next paycheck, give each important amount a specific job. This creates a simple cash-flow plan without forcing every household into the same percentage-based budget.
Reserve Money for Bills Before They Are Due
Start with bills that will need to be paid before your next paycheck arrives. These might include rent, utilities, phone bills, transportation payments, or other unavoidable commitments.
For example, suppose you receive ₹10,000 today and ₹3,500 of bills are due before your next payday. That ₹3,500 should be treated as committed money even though it is still sitting in your account.
The same idea applies to a $1,000 or £900 paycheck. The currency changes, but the problem is the same: money can look available simply because the bill has not arrived yet.
Once upcoming bills are protected, calculate what you need for essential day-to-day spending until payday.
Imagine you have 10 days remaining and expect to spend about ₹200 per day on necessary food and transportation:
₹200 × 10 days = ₹2,000
Instead of treating your whole account balance as spendable, ₹2,000 becomes the working amount for those essentials.
You can use the same calculation with dollars or pounds. For example, if your essential daily spending is $12 and you have 8 days until payday, your basic requirement would be $96.
This creates a useful distinction: your account balance shows what you have, while your spending limit shows what you can safely use.
Leave Room for Small Unplanned Expenses
A budget that leaves no flexibility can be difficult to follow. A small unexpected expense can force you to take money from a bill or another essential category.
After covering your required expenses, keep a modest flexible amount that fits your situation.
₹500 for a ₹10,000 example paycheck
$30 for a $1,000 example paycheck
£25 for a £900 example paycheck
These numbers are examples, not recommended percentages. Your flexible amount should depend on your actual income and expenses.
The important rule is simple: once this amount is used, do not automatically increase it by taking money reserved for essential expenses.
Give the Remaining Money a Specific Job
After protecting bills, essential daily spending, and a small flexible amount, look at what remains. Do not automatically label it as “extra money.” Decide what that money is supposed to do.
₹10,000 Paycheck
Amount
Purpose
Upcoming bills
₹3,500
Protect until due date
Food + transportation
₹2,000
10-day essentials
Flexible spending
₹500
Small unexpected needs
Remaining amount
₹4,000
Protect for the next financial need
The ₹4,000 remaining in this example should not automatically become shopping or entertainment money. It could help cover an upcoming expense, provide breathing room for the next pay period, or be directed toward another priority once your immediate needs are secure.
This is similar to the basic idea behind MoneyHelper’s jam-jar budgeting approach, where money is separated into different pots for different purposes so that spending money is less likely to interfere with money reserved for bills.
When Money Is Unassigned
When Money Has a Job
The full balance feels available
Only the appropriate amount feels available
Upcoming bills are easy to forget
Upcoming bills are protected
Daily spending can consume future money
Daily spending has a defined limit
Payday feels like a reset
Each paycheck is planned around the next one
If you want to understand broader salary allocation, you can also read your existing guide to dividing your salary. That article covers percentage-based allocation and salary budgeting; this section focuses specifically on protecting cash between paychecks, so the two articles serve different purposes.
The goal is not to make every paycheck fit a perfect formula. It is to make sure money needed for the next few days and weeks is protected before you decide what you can actually spend.
Create a Survival Budget for the Lowest-Income Weeks
When you live paycheck to paycheck, your budget cannot depend on every paycheck being the same. A week with fewer working hours, lower overtime, or an unexpected expense can leave you with much less money than usual.
Instead of rebuilding your entire budget whenever income falls, create a survival budget based on the minimum amount you need to keep your essential expenses covered.
Find Your Bare-Minimum Monthly Cost
Start by identifying the expenses you cannot reasonably stop or postpone when your income is lower.
Housing and essential household costs
Basic food
Necessary transportation
Essential utilities and communication
Required debt or other unavoidable payments
For example, if your normal monthly income is ₹20,000 but your essential expenses are ₹13,000, then ₹13,000 is much more important for your survival budget than your usual spending level.
A person earning $2,500 or £2,000 would use the same method: first identify the minimum cost of keeping essential needs covered, rather than copying someone else’s budget percentages.
Separate Fixed Costs From Expenses You Can Adjust
Not every expense has the same level of flexibility. When income falls, knowing which costs can actually be reduced is more useful than simply cutting everything by the same percentage.
Type of Expense
Usually Harder to Change Quickly
Often More Flexible
Housing
Rent or essential housing payment
Some optional housing-related spending
Food
Basic groceries
Takeaways and non-essential purchases
Transportation
Necessary travel to work
Optional trips
Subscriptions
Essential communication services
Entertainment subscriptions
This gives you a priority order. You are not trying to make every category smaller. You are protecting the expenses that keep your household functioning and adjusting the areas where you have genuine control.
What to Cut First When Your Paycheck Is Smaller
When a paycheck comes in lower than expected, make the adjustment based on priority rather than emotion.
For example, suppose your usual income is ₹20,000 but this month you receive only ₹15,000. If essential expenses remain around ₹12,000, you have only ₹3,000 available for everything else.
Monthly Situation
Income
Essential Costs
Amount Left
Normal month
₹20,000
₹12,000
₹8,000
Lower-income month
₹15,000
₹12,000
₹3,000
The lesson is not to spend the extra ₹8,000 simply because it was available in the normal month. Your flexible spending has to respond when your income changes.
The same principle applies if income falls from $2,500 to $2,000 or from £2,000 to £1,600. The actual figures differ by country and household, but the budgeting decision is the same: protect essential costs first, then reduce flexible spending.
What to Do When the Budget Still Doesn’t Balance
Sometimes cutting flexible spending is not enough. If your essential expenses are already higher than your income, the problem is no longer simply about better budgeting.
At that point, look at the gap itself.
Check whether any payment can be moved to a more suitable date.
Look for temporary reductions in non-essential commitments.
Review recurring expenses that are no longer necessary.
Consider realistic ways to increase income if the shortfall continues.
Contact the relevant provider early if you are struggling with an important payment rather than waiting until it becomes overdue.
Do not treat every low-income month as a failure. A temporary income drop requires a different spending plan. If the gap continues for several months, however, it is a signal that the underlying income-versus-expense problem needs to be addresse provide practical information for managing income and expenses. UK readers can also use MoneyHelper’s budgeting guidance for country-specific budgeting information.
If you already have a broader article about dividing your salary, use it as a supporting internal link for the normal-income budgeting side. This section has a different purpose: it explains how to adapt when your income falls below normal.
A survival budget is not meant to be your permanent lifestyle. It is a practical fallback system that helps you protect essential expenses during a low-income period without pretending that every month will look the same.
Build a Small Buffer Between Your Paychecks
When you are living paycheck to paycheck, even a small unexpected expense can create a problem because most of your income is already committed before the next payday arrives.
The solution is not to suddenly save a large amount. A more realistic approach is to create a small buffer between paychecks and increase it gradually as your cash flow improves.
Why Every Paycheck Should Not Be Fully Spent
If your entire paycheck is allocated before the next one arrives, there is no room for a small surprise expense. A transport problem, higher grocery bill, or unexpected household purchase can force you to reduce something else or depend on borrowing.
For example, if you receive ₹20,000 and normally spend almost all of it before the next payday, try leaving a small amount untouched instead of treating the full balance as available spending money.
The same idea applies to someone earning $2,000 or £1,600. The amount of the buffer will depend on local costs and income, but the purpose is the same: create a little space between what you earn and what you immediately spend.
Start With a Buffer You Can Actually Keep
Your first target does not need to be a large emergency fund. If money is already tight, setting an unrealistic target can make the system impossible to maintain.
Start with an amount that would make one small unexpected expense easier to handle.
Stage
Illustrative Buffer
Main Purpose
Starting point
₹300 / $5 / £5
Creates the first small cushion
Small cushion
₹1,000 / $25 / £20
Handles minor unexpected costs
Several days of essentials
Based on your actual costs
Provides more breathing room
Larger buffer
Based on your income and expenses
Reduces pressure between paychecks
These are illustrative examples, not recommended savings targets for every country or household. Your starting point should match what you can realistically leave untouched.
Turn Leftover Money Into Next-Paycheck Protection
One useful habit is to stop treating every leftover amount as permission to spend more.
Suppose you planned to spend ₹2,000 during a week but actually spent ₹1,750. Instead of automatically using the remaining ₹250, you can leave it available for the next pay period.
Over time, several small amounts can create a useful cushion without requiring one large contribution from a low income.
If you want a separate collection of practical saving strategies, you can read how to save money fast in 30 days. That article covers broader saving techniques; this section is specifically about creating protection between paychecks.
How a Buffer Changes Your Next Paycheck
Situation
Without a Buffer
With a Small Buffer
Small unexpected expense
May reduce money available for essentials
Can be covered from the cushion
Lower-than-usual paycheck
Immediate pressure on spending
Previous buffer provides some breathing room
Money left at the end of the week
May be spent automatically
Can remain available for the next period
Next payday
Starts with little or no flexibility
Starts with some money already protected
The goal is not to make your bank balance look bigger. The goal is to make your next payday less fragile.
Increase the Buffer Gradually
Once your first small cushion becomes easy to maintain, increase it only when your budget can support the change.
Keep the first small amount untouched.
Add a little more when you genuinely have money left over.
Use part of the buffer only for situations that actually need it.
Rebuild the buffer after using it.
Increase the target when your income becomes more stable.
This creates a simple cycle:
Paycheck → essential spending → controlled flexible spending → small amount protected → next paycheck starts with a cushion.
If you are still struggling to keep any money aside despite earning a reasonable income, the problem may be different from simply needing a larger buffer. In that situation, why you can’t save money despite earning a good salary is a more relevant supporting guide.
When a Buffer Is Not Enough
A small buffer can help with timing problems and minor unexpected expenses, but it cannot solve a permanent gap between income and essential costs.
If your essential expenses are consistently higher than your reliable income, calculate the shortfall instead of simply trying to save more.
Essential expenses − reliable income = monthly shortfall
For example, if essential expenses are ₹16,000 and reliable income is ₹14,000, there is a ₹2,000 monthly gap. A buffer can temporarily reduce pressure, but the underlying gap still needs to be addressed.
For broader personal-finance fundamentals, you can also use this beginner’s personal finance guide to review the wider system without repeating those topics here.
A buffer is not about becoming wealthy overnight. It is about creating a small gap between your income and your immediate spending so that one minor problem does not automatically become a next-paycheck problem.
Start small, protect the amount, rebuild it when you use it, and increase it only when your actual budget allows.
Handle a Shortfall Before It Becomes a Bigger Problem
Sometimes a low-income budget does not fail because of unnecessary spending. The real problem can be that your essential expenses are already close to, or higher than, your reliable income.
When that happens, the first step is not to cut random expenses. Find the exact size of the gap and determine whether it is temporary or happening repeatedly.
Calculate Your Exact Monthly Shortfall
Start with your reliable take-home income and subtract only the expenses you genuinely need to keep covered.
Reliable income − essential expenses = money available for everything else
For example, if your reliable income is ₹15,000 and essential expenses are ₹13,500, you have ₹1,500 available for flexible spending and other priorities.
But if essential expenses are ₹16,000, you already have a ₹1,000 shortfall before discretionary spending begins.
Situation
Income
Essential Expenses
Result
Expenses fit income
₹15,000
₹13,500
₹1,500 remaining
Small shortfall
₹15,000
₹16,000
₹1,000 gap
Larger shortfall
₹15,000
₹18,000
₹3,000 gap
The same calculation works for other currencies. Someone earning $2,000 with $2,200 of essential expenses has a $200 gap. Someone earning £1,600 with £1,750 of essential expenses has a £150 gap.
Separate a Temporary Gap From a Recurring Problem
Not every shortfall requires the same response.
Temporary Shortfall
Recurring Shortfall
Income was unusually low for one period
Income is regularly below essential costs
An unusual expense caused the problem
Basic monthly costs are structurally too high
Normal income may solve it next payday
The underlying income-expense gap needs attention
Small adjustments may be enough
Both expenses and income may need to change
This distinction matters because repeatedly using a credit card, borrowing money, or taking from your next paycheck can hide a recurring shortfall instead of solving it.
Decide What Can Be Delayed or Reduced
If the gap is temporary, review your expenses according to priority rather than cutting everything equally.
Reduce: flexible food spending, entertainment, shopping, and other non-essential categories.
Delay: purchases or goals that are useful but not urgent.
Review: recurring subscriptions and commitments that may no longer provide enough value.
The purpose is to create enough breathing room to get through the weaker income period without sacrificing expenses that keep your basic needs covered.
If the issue is connected to inconsistent income rather than a single low paycheck, your guide on budgeting with an irregular income is the more relevant supporting resource. It covers a different situation, so this section does not need to repeat that system.
When Cutting Expenses Is No Longer Enough
There is a point where reducing discretionary spending cannot solve the problem. If your essential expenses are already higher than your reliable income, the budget needs to address the gap itself.
For example, if your essential expenses are ₹18,000 and your reliable income is ₹15,000, cutting ₹500 of entertainment does not remove the entire ₹3,000 shortfall.
At that stage, consider both sides of the equation:
Can an essential cost be reduced or changed?
Can a payment date be adjusted where appropriate?
Is there a temporary expense that can be postponed?
Can reliable working hours or income be increased?
Is the shortfall temporary or likely to continue?
If debt payments are part of the problem, avoid treating new borrowing as income. A recurring gap financed by new debt can make future paychecks even harder to manage.
Know When Your Budget Needs a Structural Change
A budget is useful when it reflects reality. If your income repeatedly cannot cover your essential expenses, changing the spreadsheet without changing the underlying situation will not fix the problem.
Track the shortfall for several pay periods and look for a pattern. If the same gap keeps appearing, you have identified a structural problem rather than a one-time budgeting mistake.
For broader financial planning, you can refer to your financial planning guide for beginners. Keep this article focused on the paycheck-to-paycheck problem instead of repeating the full financial-planning framework.
official guidance on managing income and expenses. UK readers can use MoneyHelper’s budgeting guidance for additional country-specific information.
The key is to identify the problem early. A one-time ₹1,000, $100, or £100 shortfall can be handled differently from a gap that appears every month. Once you know which situation you have, you can choose the appropriate next step instead of repeatedly starting over on payday.
Create a Simple Weekly System That Keeps You Ahead of Payday
A budget only works when you can follow it after the planning is finished. If you are living paycheck to paycheck, you do not need to check your finances every hour. A short weekly routine can be enough to see what has been spent, what is still available, and what needs attention before the next payday.
The goal of this system is simple: make your money decisions before your balance becomes a problem.
Check Your Available Money Once a Week
Choose one fixed day each week to check your bank balance and recent spending. Sunday can work well, but the best day is the one you can repeat consistently.
Do not look only at your total balance. Separate the money that is already committed from the money you can actually use during the next few days.
Check your current balance.
Check essential payments due before the next review.
Check what you spent during the previous week.
Check how much flexible money remains.
Move any genuine leftover amount into your protected buffer when appropriate.
This five-minute check can reveal a problem while it is still small instead of waiting until the final days before payday.
Set a Spending Limit for the Next Seven Days
Once you know what money is already committed, give yourself a realistic limit for the coming week.
For example, if you have ₹2,800 available for flexible spending and four weeks remain in your planning period, you might initially work with a limit of around ₹700 per week. Your actual number should come from your own expenses rather than a fixed budgeting rule.
A US reader might work with a $150 weekly limit, while a UK reader might use £100. The currency does not matter as much as giving the remaining money a clear time period.
Weekly Check
Question to Ask
Action
Balance
How much money is available?
Record the amount
Upcoming bills
What must be paid before next week?
Protect that money
Recent spending
Where did last week’s money go?
Identify unusual spending
Flexible money
How much can I safely spend?
Set the week’s limit
Buffer
Did any money genuinely remain?
Keep it protected when possible
Check Upcoming Bills Before You Spend
A weekly spending limit is not enough if a large payment is due in the same week.
Before using your available balance, look at the next few days and check whether rent, utilities, transportation, insurance, debt payments, or another essential expense is approaching.
The Consumer Financial Protection Bureau’s bill-calendar guidance recommends putting income and bill dates together so you can see when money comes in and when payments leave your account. That cash-flow view is especially useful when the timing of your income creates pressure before payday. 1
This is different from simply asking, “How much money is in my bank account?” The better question is, “How much of that balance is actually available after the money I already need to protect?”
Adjust the Next Week Instead of Giving Up on the Budget
Suppose you planned to spend ₹700 during the week but ended up spending ₹900. Do not treat the entire monthly budget as failed.
First, identify why the extra ₹200 was spent. Was it a necessary expense, a one-time purchase, or something you could have avoided?
If the expense was genuinely necessary, adjust the following week’s flexible spending if your overall cash flow allows it. If it was avoidable, use the information to prevent the same pattern from repeating.
What Happened
Better Response
Necessary expense was higher
Adjust the next week’s flexible amount
One-time unexpected cost
Use the buffer if appropriate and rebuild it later
Repeated unnecessary spending
Identify the category and reduce it
Essential costs exceed income
Recalculate the shortfall instead of cutting random expenses
This makes the budget a feedback system rather than a punishment system.
Use a Simple Payday-to-Payday Checklist
At the beginning of each pay period, run through the same short checklist:
☐ Confirm your actual take-home income.
☐ Protect bills due before the next paycheck.
☐ Set aside the amount needed for essential daily spending.
☐ Decide your flexible spending limit.
☐ Keep your existing buffer protected.
☐ Check your finances once during each week.
☐ Review what changed before the next payday.
If your income changes from one pay period to another, use the lower reliable income as the safer starting point rather than assuming your best paycheck will arrive every time.
For a broader system covering salary management across the month, your Day 1 to Day 30 salary management guide can support the reader after this article. This article has a narrower purpose: keeping a low-income paycheck under control between paydays. 2
Make the System Easier Every Payday
You do not need a complicated spreadsheet or a new financial rule every week. The system becomes useful when the same few decisions become automatic.
Each payday, protect essential money. Each week, check your actual spending. When income falls, reduce flexible spending before essential needs. When money remains, protect part of it instead of automatically spending it.
Over time, this changes the way you experience payday. Instead of starting every pay period wondering how long your money will last, you start with a clear picture of what is committed, what is available, and what needs to happen next.
That is the real purpose of a paycheck-to-paycheck budget: not perfection, but enough control to make the next payday less stressful than the last one.
Can you budget if you
Yes. When your income baseline is low, structural percentage allocations become even more critical to safeguard your primary needs and prevent cascading high-interest debt cycles.
What is the 70/20/10 rule for low income?
This alternate budgeting blueprint allocates 70% of total funds for essential living needs, 20% to clear debts or build savings, and exactly 10% for variable personal lifestyle choices.
How do I start an emergency fund on a tight budget
Begin by automating microscopic milestones. Setting aside just $5 or ₹500 immediately on Day 1 establishes consistent behavioral habits without fracturing your day-to-day liquidity.
What is the fastest way to break the paycheck cycle
The fastest way is shifting to physical cash tracking via the envelope system for variable costs and performing a immediate subscription audit to reclaim lost margins.
Hi, I’m Asif Khan, the voice behind paisakmao.de. For the past two years, I’ve been blogging about financial education, income skills, and mindset development for students and young minds. My mission is to empower every youth with financial literacy and practical money-making skills at an early age. Through paisakmao.de, I share actionable guides for students to start earning early, money wisdom that schools don’t teach, and mindset lessons from successful people and modern psychology. Whether you’re a teenager looking to earn your first income or a student exploring side hustles, you’re in the right place. Financial freedom begins with the right mindset and the right knowledge. Let’s grow, earn, and evolve together — welcome to the movement!
Getting a salary every month feels good, but managing that money wisely can be challenging, especially when you are just starting to manage your finances. Bills, daily expenses, savings, debt, and personal spending can quickly compete for the same income.
Learning how to divide your salary for beginners can make this much easier. Instead of spending first and trying to save whatever is left, you can give each part of your income a clear purpose from the beginning.
In this guide, you’ll learn practical ways to divide your salary, how the 50/30/20 rule works, when other budgeting methods may be better, and how to adjust your plan based on your income and expenses. You’ll also see real salary examples and simple steps you can use every month.
The goal is not to follow a percentage blindly, but to build a salary plan that works in your real life.
How Should a Beginner Divide Their Salary?
Getting started with salary budgeting does not mean following one fixed percentage. A beginner should first understand how much money comes in, what must be paid, what should be saved, and how much can be used for personal spending.
A simple starting order is:
Take-home salary → Essential expenses → Savings → Debt and financial goals → Personal spending → Monthly review
Start With Your Take-Home Salary
Use the amount you actually receive in your bank account each month, not your gross salary. This gives you a realistic starting point for your monthly budget.
Separate Needs From Wants
Start by identifying essential expenses such as rent, food, utilities, transportation, insurance, and necessary family expenses. Then separate them from wants such as shopping, entertainment, eating out, and hobbies.
This helps you see where your salary is actually going before deciding how much you can spend or save.
Set Aside Savings Before Extra Spending
Instead of waiting until the end of the month to see what is left, decide on a savings amount in advance. This makes saving a planned part of your salary rather than something you do only when extra money remains.
You can divide this money between short-term goals, emergency savings, and other financial goals based on your situation.
Include Debt and Financial Goals
If you have debt, loan payments should be included in your monthly salary allocation. You may also need to set aside money for goals such as education, a major purchase, or long-term financial plans.
Your allocation should change when your priorities change.
Keep a Realistic Amount for Personal Spending
A good budget should still leave room for reasonable personal spending. Giving yourself a clear limit for wants can make your plan easier to follow without feeling unnecessarily restrictive.
Use Percentages as a Starting Point
Percentage-based budgeting can make salary allocation simpler for beginners. However, percentages are not strict rules. Your ideal allocation may be different because of your income, living costs, debt, family responsibilities, and financial goals.
For example, a person with high rent may need to spend more on essential expenses, while someone with lower fixed costs may be able to save more.
Example: Dividing a ₹30,000 Monthly Salary
A simple starting example could look like this:
Category
Percentage
Amount
Essential expenses
50%
₹15,000
Wants and personal spending
30%
₹9,000
Savings and financial goals
20%
₹6,000
This is only a starting example. If your essential expenses are higher, you can adjust the percentages instead of forcing your budget to fit a rule.
The 50/30/20 rule is one of the most popular ways beginners can structure their salary, so let’s look at how it works in detail.
What is the 50/30/20 rule for splitting your salary?
The 50/30/20 rule is a simple way to budget your take-home pay by splitting it into 50% for needs, 30% for wants, and 20% for savings or financial goals. The Consumer Financial Protection Bureau (CFPB) describes it as an easy method to help you organize your spending and saving.
If you’re just getting started with money management, this rule helps you give every rupee a job instead of spending first and saving whatever is left. If you’re new to this, our Personal Finance for Beginners guide covers the basics of budgeting and saving.
50% for Needs
Needs are the things you can’t really avoid in daily life, like:
Rent or housing
Groceries
Utilities
Transportation
Phone and internet
Insurance
Minimum debt payments
For a ₹30,000 salary, 50% comes to ₹15,000. If your actual essential expenses are lower, you can put the extra into savings or investments.
30% for Wants
Wants are the fun or optional things you spend on, like:
Eating out
Entertainment
Shopping
Subscriptions
Travel
Hobbies
For a ₹30,000 salary, 30% is ₹9,000. If you don’t use it all, you can move the leftover into savings or use it to pay off debt.
20% for Savings and Goals
This part is for your future and financial security, such as:
Emergency fund
Debt repayment
Investments
Retirement savings
Big planned purchases
For a ₹30,000 salary, 20% is ₹6,000. It’s usually a good idea to start with an emergency fund or high-interest debt first. The SEC’s Investor.gov also talks about why saving and investing regularly matters.
50/30/20 Salary Breakdown
Monthly Salary
Needs (50%)
Wants (30%)
Savings (20%)
₹20,000
₹10,000
₹6,000
₹4,000
₹30,000
₹15,000
₹9,000
₹6,000
₹50,000
₹25,000
₹15,000
₹10,000
These are just examples, not strict rules.
What If It Doesn’t Fit?
The 50/30/20 rule isn’t fixed—you can tweak it based on your situation. If your needs take up more of your income, you could try something like:
How to Allocate Your Salary Based on Actual Expenses
The 50/30/20 rule is a good starting point, but your budget should really match your actual income and spending habits. Fixed percentages don’t always work well when rent, EMIs, and basic living costs vary a lot from person to person.
A better way is to build a salary plan based on what you actually spend.
Start With Your Take-Home Salary
Start with your net (in-hand) salary after taxes and deductions.
For example, if you earn ₹30,000 a month, use that amount for planning instead of your gross salary.
Identify Fixed Expenses
Fixed expenses are the things you pay every month, such as:
Rent
Loan EMIs
Insurance
Internet and mobile bills
Subscriptions
Adding these up helps you see how much of your income is already committed.
Assess Variable Expenses
Variable expenses change from month to month, such as:
Groceries
Transportation
Eating out
Shopping
Entertainment
Looking at your past spending can help you figure out a realistic average and spot where you might cut back if needed.
Distinguish Between Needs and Wants
Needs are the essentials like rent, food, and utilities. Wants are things like dining out, shopping, and entertainment.
This makes it easier to see whether your lifestyle spending is affecting your savings.
Define Savings and Financial Goals
After covering expenses, decide how much you can put toward savings and goals like:
Emergency fund
Loan repayment
Investments
Retirement savings
For example, with a ₹30,000 salary: ₹16,000 needs + ₹6,000 wants = ₹8,000 savings
That comes out to roughly a 53% / 20% / 27% split, which is often more realistic than sticking to a fixed rule.
The main idea is to build a budget that actually fits your life and adjust it as your income or expenses change.
How to Create a Monthly Salary Budget That Actually Works
A good monthly salary budget is not about tracking every rupee perfectly. It is about knowing where your money should go before you start spending it.
Start With Your Take-Home Salary
Start with your take-home salary—the amount that actually reaches your bank account after taxes and other deductions.
For example, if you take home ₹30,000 per month, use ₹30,000 as the starting point for your budget instead of your gross salary.
Then list your regular expenses, such as:
Rent or housing
Groceries
Utilities and phone bills
Transportation
Loan EMIs
Subscriptions
Other regular spending
This gives you a clear picture of where your income is going.
If you are still learning the basics, our Personal Finance for Beginners guide can help you understand how budgeting fits into your overall financial plan.
Set Realistic Spending Limits
Once you know your regular expenses, set a realistic spending limit for each major category.
Instead of simply telling yourself to “spend less,” decide how much you can reasonably spend on groceries, eating out, shopping, entertainment, and other flexible expenses.
For example, you might set limits for:
Groceries: ₹4,000
Eating out: ₹1,500
Entertainment: ₹1,000
Shopping: ₹1,500
The exact numbers will depend on your income and lifestyle.
A good budget should feel manageable. If your limits are too strict, you may find it difficult to follow them consistently.
Prioritize Savings and Financial Goals
Do not wait until the end of the month to see whether you have money left to save.
Decide in advance how much you want to put toward important financial goals, such as:
Emergency savings
Debt repayment
Investments
Retirement
A planned purchase
If possible, move your planned savings soon after receiving your salary. This makes saving a regular habit instead of something you do only when extra money is available.
The Consumer Financial Protection Bureau (CFPB) recommends getting a clear picture of your income and spending, creating a realistic working budget, and updating it when your income or spending habits change.
Review What You Actually Spent
A monthly budget becomes more useful when you compare what you planned to spend with what you actually spent.
For example, suppose you planned to spend ₹4,000 on groceries but ended the month at ₹5,000.
Instead of simply calling it overspending, ask why it happened. Maybe prices increased, you made extra purchases, or you underestimated your normal grocery costs.
Then use that information to make next month’s budget more realistic.
Adjust Your Budget When Your Life Changes
Your salary budget should not remain fixed forever.
A salary increase, new EMI, higher rent, family responsibility, or change in daily expenses can affect how you should divide your money.
If your income increases, you do not necessarily need to increase your lifestyle spending by the same amount. You could direct part of the extra income toward savings, debt repayment, or long-term financial goals.
The same applies when your expenses increase. Instead of abandoning your budget, review your categories and adjust them based on your new situation.
The goal is not to create a perfect budget. It is to build a simple monthly spending plan that fits your real life, gives every rupee a purpose, and is realistic enough to follow consistently.
How Much Should You Save From Your Salary?
There is no single savings amount that works for everyone. The right amount depends on your income, essential expenses, debt, and financial goals.
The 20% in the 50/30/20 rule can be a useful starting point, but you do not have to force yourself to save exactly 20% if your current situation does not allow it.
Start With an Amount You Can Maintain
If you cannot save 20% of your salary right now, start with an amount you can consistently set aside.
For example, if you earn ₹25,000 and can comfortably save ₹2,500 each month, that is still a good starting point. As your income increases or your expenses decrease, you can gradually increase the amount.
The important part is to make saving a regular habit rather than waiting for a month when you have extra money.
Build an Emergency Fund First
Before focusing heavily on long-term goals, build money that can help you handle unexpected expenses.
An emergency fund can be useful for situations such as:
Unexpected medical or household expenses
Temporary loss of income
Urgent repairs
Other necessary costs you did not plan for
The Consumer Financial Protection Bureau (CFPB) explains that an emergency fund is money set aside for unplanned expenses and that even a small amount can provide some financial security.
Keep this money separate from your normal spending account so you are less likely to use it for everyday purchases.
Save for Short-Term and Long-Term Goals
Not every savings goal has the same time frame.
Short-term goals might include a planned purchase, travel, education, or an upcoming expense. Long-term goals may include retirement or building long-term wealth.
Giving each goal a purpose makes it easier to decide where your savings should go instead of treating all saved money as one large amount.
If you are building your broader financial plan, our Financial Planning for Beginners guide can help you connect saving with other financial priorities.
Increase Your Savings When Your Income Grows
You do not have to keep the same savings amount forever.
If you receive a raise, bonus, or additional income, consider directing part of the increase toward savings before increasing your lifestyle spending.
For example, if your salary rises from ₹30,000 to ₹35,000, you could increase your monthly savings by ₹2,000 and use the remaining increase for other priorities.
This allows your savings rate to grow without making your monthly budget feel dramatically tighter.
The goal is not to save the highest possible percentage of your salary. It is to build a savings habit that is realistic today and can grow with your income over time.
How to Divide Your Salary Between Bills, Spending, and Savings
Once you know your income and your financial priorities, the next step is to decide how much of your salary should go toward bills, everyday spending, savings, and other financial goals.
The exact percentages do not have to match the 50/30/20 rule. Your rent, debt, family responsibilities, and income may require a different balance.
Cover Essential Bills First
Start by separating the expenses you need to pay every month from the expenses you can control or reduce.
Essential expenses may include:
Rent or housing
Electricity, water, and other utilities
Groceries and basic food
Transportation
Insurance
Minimum debt or EMI payments
These expenses should come first because missing essential bills or debt payments can create bigger financial problems later.
If your essential expenses already consume more than 50% of your salary, do not force yourself to follow the 50/30/20 rule. Instead, look for areas where you can gradually reduce costs while keeping your basic needs covered.
The FDIC explains that budgeting can help you track income, expenses, and savings while making better decisions about needs and wants.
Set a Limit for Everyday Spending
After covering essential bills, decide how much you can reasonably spend on things that are not necessary for basic living.
This may include:
Eating out
Entertainment
Shopping
Hobbies
Subscriptions
Social activities
Giving these expenses a limit does not mean you have to remove all enjoyment from your budget. It simply prevents optional spending from taking money away from important financial goals.
For example, instead of spending whenever you feel like it, you might give yourself a fixed monthly amount for eating out and entertainment. Once that amount is used, you can wait until the next month.
Give Savings a Fixed Place in Your Salary
Savings should not depend entirely on whatever money is left after spending.
Choose an amount that you can realistically save every month and treat it as one of your regular financial commitments.
You can divide your savings between different goals, such as:
Emergency fund
Short-term purchases
Debt repayment
Investments
Retirement
If you are still building your overall financial plan, our Financial Planning for Beginners guide can help you connect your monthly budget with longer-term goals.
Use a Realistic Salary Example
Suppose your monthly take-home salary is ₹40,000.
You might create a starting allocation like this:
₹20,000 for essential bills and needs
₹5,000 for flexible spending
₹15,000 for savings, debt repayment, and financial goals
That gives you a 50% / 12.5% / 37.5% split. It is very different from a strict 50/30/20 allocation, but it may work well if your lifestyle allows you to save more.
The numbers are only an example. Someone with higher rent or family responsibilities may need to allocate much more toward essential expenses.
Keep Your Salary Budget Flexible
Your salary allocation does not have to remain exactly the same every month.
You may have a higher electricity bill one month, a medical expense the next, or an unexpected repair. These changes are part of real life.
Instead of abandoning your budget when something unexpected happens, adjust your flexible spending first and protect your essential bills and important financial goals as much as possible.
As your income changes, review the whole allocation again. A salary increase can create an opportunity to increase savings, while a new EMI may require you to reduce discretionary spending.
The goal is not to divide your salary perfectly. It is to create a system where your bills are covered, your spending stays under control, and your money continues moving toward your financial goals.
How to Adjust Your Salary Budget When Your Income or Expenses Change
Your salary budget should not be treated as a fixed formula. Your income and expenses can change over time, so your budget should change with them.
A raise, new EMI, higher rent, unexpected expense, or change in your family responsibilities can all affect how much money you have available each month.
Review Your Budget After a Salary Increase
When your income increases, it can be tempting to immediately increase your lifestyle spending.
Instead, give the extra income a purpose before you start spending it. You could divide the increase between savings, debt repayment, investments, and a reasonable increase in your lifestyle spending.
For example, if your salary increases from ₹30,000 to ₹35,000, you do not have to spend the entire ₹5,000 increase. You might put ₹2,500 toward savings or investments and use the remaining ₹2,500 for other priorities.
This helps prevent lifestyle inflation, where spending rises every time your income rises.
Adjust When Your Expenses Increase
Sometimes your income stays the same while your expenses increase. Rent may go up, an EMI may start, or household costs may become more expensive.
When this happens, review your flexible spending before cutting important financial goals completely.
For example, you might temporarily reduce eating out, shopping, entertainment, or unused subscriptions to make room for a necessary increase in expenses.
Plan for Irregular Expenses
Not every expense arrives every month. Insurance renewals, repairs, annual subscriptions, travel, and other occasional costs can catch you off guard if you only budget for regular monthly bills.
A simple solution is to estimate these expenses in advance and set aside a small amount each month.
For example, if you expect an annual expense of ₹12,000, setting aside around ₹1,000 per month can make the eventual payment much easier to handle.
Review Your Budget Regularly
You do not need to rebuild your entire budget every week. A monthly review is usually enough for most people.
At the end of each month, check three things:
What did I actually spend?
Which category went over budget?
Did I save the amount I planned to save?
Use the answers to make small adjustments for the following month. If you are struggling to save despite having a reasonable income, our guide to why you can’t save money can help you identify common spending and saving problems.
Do Not Abandon Your Budget After One Bad Month
One expensive month does not mean your entire financial plan has failed.
Unexpected expenses happen. The important thing is to understand what caused the overspending and adjust your next month’s plan instead of giving up completely.
A useful salary budget is a flexible system that changes as your financial situation changes. The goal is to keep your spending under control while continuing to make progress toward your savings and financial goals.
Common Salary Budgeting Mistakes to Avoid
Even with a basic salary budget, it is easy to make mistakes that slowly affect your savings and financial progress. The problem is usually not the budgeting rule itself, but how the budget is used in real life.
1. Budgeting With Your Gross Salary
One common mistake is creating a budget using your gross salary instead of the amount you actually receive.
Your budget should start with your take-home salary because that is the money available for your monthly expenses, savings, and financial goals.
2. Saving Only What Is Left
If you spend first and plan to save whatever remains at the end of the month, there may be very little left.
A better approach is to decide your savings amount in advance and treat it as part of your monthly financial plan.
3. Following a Percentage Too Strictly
The 50/30/20 rule is a useful framework, but it is not a requirement that every person must follow exactly.
Someone paying high rent or supporting a family may need a different allocation. The goal is to create a budget that fits your actual circumstances rather than forcing your expenses into fixed percentages.
4. Ignoring Small and Irregular Expenses
Small purchases can look harmless individually but become significant when they happen repeatedly.
Subscriptions, frequent food deliveries, small online purchases, and convenience spending can quietly reduce the money available for savings.
Irregular expenses can cause another problem. Annual insurance payments, repairs, travel, or other occasional costs should be considered before they arrive.
5. Forgetting to Build an Emergency Fund
A budget that only covers normal monthly expenses can still leave you vulnerable when something unexpected happens.
Building an emergency fund gives you a separate pool of money for necessary unplanned expenses instead of forcing you to rely on credit or new debt.
6. Increasing Lifestyle Spending Too Quickly
When your salary increases, it is natural to want a better lifestyle. But increasing every expense at the same time can prevent your savings from growing.
Instead, consider putting part of every raise or bonus toward savings, investments, or debt repayment before increasing discretionary spending.
A budget is not something you create once and forget about.
Your income, bills, priorities, and spending habits can change. Review your actual spending regularly and make small adjustments when necessary.
If you notice that a particular category repeatedly goes over budget, do not simply keep setting the same unrealistic limit. Find the reason and change the plan.
8. Giving Up After One Bad Month
Unexpected expenses can make one month look completely different from your original plan. That does not mean your entire budget has failed.
Look at what caused the difference, make the necessary adjustment, and start again the following month.
The best salary budget is not the one that looks perfect on paper. It is the one you can actually follow, review, and adjust as your financial life changes.
What is the 50/30/20 rule for salary?
The 50/30/20 rule suggests using 50% of your take-home income for needs, 30% for wants, and 20% for savings and financial goals. It is a flexible starting point rather than a strict rule.
How much of my salary should I save each month?
A 20% savings target can be a useful starting point if your budget allows it. If 20% is not realistic, start with an amount you can consistently save and increase it over time.
How should I budget a ₹30,000 monthly salary?
Start by calculating essential expenses such as rent, food, transportation, utilities, and EMIs. Then control flexible spending and allocate the remaining amount toward savings and financial goals.
Is the 50/30/20 rule realistic for a low salary?
Not always. If essential expenses consume most of your income, focus on covering your needs, controlling flexible expenses, and saving whatever amount you can consistently.
Conclusion: Build a Salary Budget That Fits Your Life
Dividing your salary is not about following one perfect formula. The 50/30/20 rule can give you a useful starting point, but your actual budget should reflect your income, essential expenses, debt, lifestyle, and financial goals.
Start with your take-home salary, cover your essential needs, set a realistic limit for flexible spending, and give your savings a clear place in your monthly plan. Then review your actual spending and adjust the budget whenever your income or expenses change.
Most importantly, do not worry if your numbers do not perfectly match a standard percentage. A simple budget that you can follow consistently, review regularly, and improve over time is more useful than a perfect-looking budget that does not work in real life.
Start with what you can manage today, and let your salary budget grow with your income and financial goals.
Post Summary Learn how to divide your salary effectively with this beginner-friendly guide. Discover the 50/30/20 rule, practical salary allocation examples, savings strategies, budgeting tips, common mistakes, and simple ways to build a monthly budget that fits your real income and expenses.
Managing money can feel confusing when you are just starting. You may earn money but still wonder where it goes, struggle to save consistently, or feel unsure about budgeting, debt, emergency funds, and investing.
The good news is that personal finance does not have to be complicated. You do not need a high income, advanced financial knowledge, or a perfect plan to begin. You only need to understand your current situation, make a few practical decisions, and build better money habits over time.
This Personal Finance for Beginners guide will help you understand the essential steps needed to take control of your money. You will learn how to track your income and expenses, create a realistic budget, build savings, prepare for emergencies, manage debt, and start investing according to your financial goals.
In this guide, we will break everything down into 10 practical steps. Each step includes clear explanations, realistic examples, and simple actions you can apply in your daily life. Whether you are a student, a beginner, a salaried employee, or someone trying to improve your financial situation, this guide will help you build a stronger financial foundation and create a clear plan for your money in 2026.
Step 1: Understand Your Current Financial Situation
Before creating a budget, building an emergency fund, paying off debt, or investing, you need to understand where you currently stand with your money. Many people know their monthly salary, but they do not know exactly where that money goes. They may feel that they are always short of money, even when their income seems reasonable.
For personal finance beginners, understanding your current financial situation is the foundation of good money management. You do not need advanced financial knowledge, expensive software, or complicated calculations. A notebook, a spreadsheet, your bank statements, and your UPI transaction history are enough to begin.
Your goal is not to judge yourself or feel guilty about past spending. The goal is to understand your financial reality. Once you know how much you earn, spend, save, and owe, you can create a financial plan that fits your actual life instead of following advice that may not work for your situation.
Start by reviewing these five areas:
Your monthly income
Your regular and flexible expenses
Your savings and emergency money
Your loans and other debts
Your monthly cash flow
SEBI explains that documenting income and expenses can help people understand their financial position, control spending, manage debt, save money, and work toward financial goals. You can read its official guide on financial goals and budgeting for additional financial education.
1. Calculate Your Actual Monthly Income
The first step is to calculate the money you actually receive during a normal month. Include your salary, wages, freelance income, business income, commissions, part-time earnings, rental income, or other regular sources.
If you have a fixed job, use your take-home income, not only the salary written in your employment agreement. Take-home income is the amount that actually reaches your bank account after deductions.
For example, if your monthly salary is ₹30,000 but ₹2,000 is deducted before payment, your usable monthly income is ₹28,000. Your budget should be based on ₹28,000 because that is the amount available for expenses, savings, and financial goals.
Income Source
Monthly Amount
Salary
₹25,000
Part-time work
₹3,000
Freelance work
₹2,000
Total Monthly Income
₹30,000
If your income changes every month, do not create your financial plan using your highest-income month. Review your income from the previous three to six months and calculate a realistic average. You can also use your lowest normal monthly income as a safer starting point for essential expenses.
If your earnings are irregular, read our detailed guide on how to budget with an irregular income. It explains how to calculate a minimum income level, prioritize essential expenses, and manage months when earnings are lower.
2. Track Your Monthly Expenses Before Creating a Budget
After calculating your income, review where your money is going. Do not depend only on memory because small expenses are easy to forget. A ₹100 snack, a ₹200 online purchase, or several small UPI payments may not seem important individually, but together they can affect your monthly savings.
Review your bank statements, UPI history, cash spending, and recurring payments. Record what you actually spent—not what you think you should have spent. An honest record gives you a useful starting point for improving your financial habits.
A practical way to organize expenses is to divide them into three groups.
Essential Expenses
Rent or housing
Groceries and basic food
Electricity, phone, and internet bills
Transport
Healthcare and medicines
Education expenses
Financial Commitments
Loan EMIs
Credit-card payments
Insurance premiums
Other required payments
Flexible Expenses
Eating out
Entertainment
Online shopping
Subscriptions
Impulse purchases
Optional lifestyle spending
You do not have to remove every flexible expense. The purpose of expense tracking is to understand your choices and identify spending that does not provide enough value. A good personal budget should be realistic and sustainable, not so restrictive that you abandon it after a few weeks.
SEBI’s official guide on managing income and expenses also recommends listing income sources, categorizing expenses, tracking spending, and allocating money toward savings and investments.
If you receive a regular salary, our Day 1 to Day 30 salary management plan can help you organize your income after payday and divide money between bills, savings, goals, and personal spending.
3. Calculate Your Monthly Cash Flow
Your monthly cash flow shows whether you are earning more than you spend. It is one of the simplest ways to understand your current financial health.
Monthly Cash Flow = Total Monthly Income − Total Monthly Expenses
Financial Item
Amount
Total monthly income
₹30,000
Essential expenses
₹17,000
Loan payments
₹4,000
Flexible expenses
₹5,000
Money Remaining
₹4,000
In this example, ₹4,000 remains after all monthly expenses. This amount could be used for savings, an emergency fund, additional debt repayment, investing, or another financial goal.
If your result is negative, it means your expenses are higher than your income. This is not a reason to panic. It is a signal that your current money system needs adjustment. You may need to reduce avoidable expenses, review recurring payments, increase income, or change the order of your financial priorities.
Do not try to fix everything at once. First, identify the largest reason for the negative cash flow. A single change—such as reducing an unnecessary recurring expense—may be more useful than making many small changes that are difficult to maintain.
4. Review Your Savings and Emergency Fund
Next, calculate how much money you have saved and how much is available for unexpected expenses. Include money in your savings account, a separate emergency fund, or another easily accessible account.
Ask yourself:
How much money can I access quickly if an emergency occurs?
Could I pay for an urgent medical bill or necessary repair?
How many months of essential expenses could my savings cover?
Is my emergency money separate from my everyday spending money?
For example, if your essential monthly expenses are ₹15,000 and you have ₹30,000 in accessible savings, your savings could cover approximately two months of essential expenses.
An emergency fund is generally meant for unexpected costs, such as urgent repairs, medical expenses, or a temporary loss of income. The amount you need depends on your income stability, responsibilities, expenses, and personal situation. The Consumer Financial Protection Bureau’s emergency-fund guide explains why emergency savings can reduce the need to depend on loans or credit when an unexpected expense occurs.
If you are starting from zero, you do not need to save a large amount immediately. You could begin with ₹500 or ₹1,000 per month and increase the amount when your income allows. Small, consistent savings can still create a useful financial cushion over time.
For practical ideas to create more room in your budget, read our guide on how to save money fast in 30 days. It includes realistic strategies for reducing unnecessary spending without making your daily life unnecessarily difficult.
5. List Your Debts and Monthly Payments
If you have a personal loan, education loan, credit-card balance, borrowed money, or another financial obligation, write down the details clearly. Avoiding debt information may temporarily feel easier, but it makes financial planning more difficult.
For each debt, record:
Total amount remaining
Interest rate, if known
Required monthly payment
Payment due date
Remaining repayment period
Debt
Amount Remaining
Monthly Payment
Personal loan
₹50,000
₹3,000
Credit-card balance
₹10,000
₹1,000
Once you can see all your debts in one place, you can compare the balances, interest rates, and payment requirements. Some people prefer paying the smallest debt first to build motivation, while others focus on higher-interest debt to reduce interest costs. The right approach depends on your financial situation and ability to make payments consistently.
Before taking a new loan, understand the total repayment responsibility, interest cost, fees, and repayment period. Borrowing can create long-term pressure if the monthly payment does not fit your income. For additional investor education, SEBI provides guidance on prioritizing needs, wants, and financial priorities.
6. Review Your Financial Habits and Spending Patterns
Your financial numbers show what is happening, but your habits often explain why it is happening. Two people with similar incomes may have very different financial results because their spending, saving, and decision-making habits are different.
Ask yourself:
Do I check my account balance before spending?
Do I save at the beginning of the month or only save what is left?
Do I make unplanned purchases because of discounts or social pressure?
Do I know how much I spend on subscriptions?
Do I review my finances regularly?
Do I compare prices before making a large purchase?
Good financial habits are usually built through small actions repeated over time. You do not need to change everything in one day. For example, reviewing your expenses every Sunday may help you notice problems before they become larger.
Students and young adults can also read our guide on financial habits every college student should develop. Many of these habits can help beginners build a stronger relationship with money before taking bigger financial decisions.
7. Use Financial Tools Carefully
Budgeting apps, expense trackers, banking tools, and AI-powered finance tools can help you organize expenses, monitor spending, set reminders, and understand financial information. However, a tool cannot automatically make the right financial decision for you. It should support your judgment, not replace it.
Before connecting an app to your financial accounts, review its privacy policy, permissions, security practices, and data-sharing rules. Avoid entering sensitive banking information into tools that you do not trust.
To explore useful options, read our guide on the best AI tools to manage personal finances. Choose a tool based on your actual needs instead of downloading many apps that you may never use.
A Simple Real-Life Example
Rahul earns ₹30,000 per month. He believes that he should be able to save ₹8,000, but his bank balance is almost empty before every payday.
After reviewing one month of transactions, Rahul discovers that ₹2,000 goes toward food delivery, ₹1,200 goes toward subscriptions he rarely uses, and ₹1,500 goes toward unplanned online purchases. None of these expenses seemed very large on their own, but together they were reducing his ability to save.
Rahul does not remove every enjoyable expense. Instead, he cancels unused subscriptions, sets a monthly limit for food delivery, and waits 24 hours before making non-essential purchases. These changes improve his monthly cash flow without making his budget too restrictive.
The lesson is simple: you cannot improve a financial problem until you understand what is causing it.
Common Mistake: Trying to Fix Everything at Once
A common mistake among personal finance beginners is trying to cut every expense, repay all debt, save a large amount, and start investing at the same time. This can create an unrealistic plan that is difficult to follow.
Instead, understand your current position first. Then choose one or two improvements that can make the biggest difference. For example, you could cancel one unused subscription, save ₹1,000 automatically, or pay an additional ₹500 toward a high-interest debt.
Review your bank statements, UPI history, and cash spending.
Track your expenses for at least 30 days.
Separate essential expenses from flexible spending.
Calculate your monthly cash flow.
Write down your savings and available emergency money.
List every debt and monthly payment.
Choose one financial habit to improve this month.
Quick Takeaway
Understanding your income, expenses, savings, debt, financial habits, and monthly cash flow gives you a strong foundation for managing money. You do not need to solve every financial problem today. First, understand your starting point. Once your numbers are clear, you can create realistic goals and build a financial plan that fits your actual situation.
Now that you understand your current financial position, the next step is to create a realistic budget that helps you control spending, protect your priorities, and make steady progress toward your financial goals.
2. Build an Emergency Fund to Protect Your Financial Future
Life does not always follow your monthly budget. A sudden medical bill, phone repair, job loss, family emergency, or unexpected travel expense can create financial pressure without warning. That is why building an emergency fund is one of the most important personal finance tips for beginners in 2026.
An emergency fund is money kept separately for genuine unexpected expenses. It is not money for shopping, entertainment, a planned vacation, or buying something just because it is on sale. Its main purpose is to give you financial breathing room when life becomes expensive unexpectedly.
According to the Consumer Financial Protection Bureau’s emergency fund guide, even a small amount of emergency savings can provide financial security and help people recover from unexpected expenses without immediately depending on credit or loans.
Why an Emergency Fund Matters in Personal Finance
Imagine that Rahul earns ₹25,000 per month. He spends almost all of his income and keeps no money aside. One day, his phone suddenly stops working, and the repair costs ₹6,000. Because Rahul has no emergency savings, he may need to borrow money, use a credit card, or delay another important payment.
Now imagine that Rahul had saved ₹500 every week. After several months, he would have built a useful financial cushion. The repair would still be inconvenient, but it would not automatically turn into debt.
This is the real value of an emergency fund. It may not make you rich, but it can stop a small financial problem from becoming a much larger one.
How Much Should You Keep in an Emergency Fund?
There is no single emergency-fund amount that is perfect for everyone. Your target should depend on your income, monthly essential expenses, job stability, family responsibilities, and how predictable your earnings are.
Financial Situation
Possible Emergency-Fund Goal
Student or beginner with limited income
Start with ₹5,000–₹10,000
Person with a stable monthly salary
Build 1–3 months of essential expenses
Freelancer or person with irregular income
Consider 3–6 months of essential expenses
Person supporting a family
Build a larger cushion based on responsibilities
For example, if your essential monthly expenses are ₹15,000, you could first aim for ₹15,000. After reaching that goal, you could gradually work toward ₹30,000 or more. You do not need to build the entire amount in one month.
If your income changes from month to month, your savings plan should also be flexible. You can learn a practical system for handling changing earnings in our guide on how to budget with an irregular income.
Start Small Instead of Waiting for the “Perfect Time”
Many people believe they must earn a high salary before they can start saving. In reality, waiting for the perfect income can delay the habit for years. A small and consistent contribution is often more useful than an ambitious plan that you stop after two weeks.
Save ₹20 or ₹50 whenever you receive money.
Set aside ₹100–₹500 every week if your budget allows.
Save a percentage of extra income, bonuses, or freelance payments.
Increase your contribution when your income grows.
For example, saving ₹50 per day could build approximately ₹1,500 in one month. Saving ₹500 per week could create around ₹26,000 in one year, before considering any interest. The amount may look small at first, but consistency creates momentum.
If saving feels difficult even when you earn a reasonable income, first identify where your money is quietly disappearing. Our article on why you can’t save money even with a good salary explains hidden spending patterns and practical ways to improve your savings.
Keep Your Emergency Money Separate
Keeping emergency money in the same account you use for daily spending can make it easier to spend accidentally. A separate savings account or another clearly labelled account can help create a mental boundary between everyday money and emergency money.
You could name the account “Emergency Fund” and avoid connecting it to routine shopping payments. The money should remain accessible when a genuine emergency happens, but it should not be so convenient that you spend it on ordinary wants.
Before choosing where to keep your emergency savings, consider three things:
Safety: The money should not be exposed to unnecessary risk.
Accessibility: You should be able to access it when a real emergency occurs.
Stability: The value should not fluctuate heavily when you may need the money soon.
Emergency money is different from long-term investment money. Investments may rise or fall in value, while an emergency fund is designed primarily for financial stability and quick access.
Use Your Emergency Fund Only for Real Emergencies
Before withdrawing money, ask yourself:
“Is this expense unexpected, necessary, and difficult to manage without using my emergency savings?”
A sudden medical expense, urgent home repair, essential vehicle repair, or temporary loss of income may qualify. A planned holiday, new gadget, festival shopping, or a discount offer usually does not.
After using the fund, begin rebuilding it gradually. You do not need to replace the entire amount immediately. Return to your normal saving routine and increase contributions when possible.
A Simple 30-Day Emergency-Fund Action Plan
Week
Action
Week 1
Calculate your essential monthly expenses.
Week 2
Open or choose a separate place for emergency savings.
Week 3
Save your first amount, even if it is only ₹100 or ₹500.
Week 4
Review your spending and choose a realistic monthly saving amount.
For a broader step-by-step money system, you can also read our guide on financial planning for beginners. It explains how budgeting, saving, debt management, and long-term goals can work together.
Key Takeaway
Building an emergency fund is not about saving a huge amount overnight. It is about creating a financial safety net one small contribution at a time. Start with a realistic target, keep the money separate, use it only for genuine emergencies, and rebuild it after you use it.
Among the most practical personal finance tips for beginners, this habit can reduce financial stress and help you avoid unnecessary debt when unexpected expenses appear.
Next: Once you have started building a financial safety net, the next step is to understand how to reduce expensive debt without damaging your monthly budget.
Step 3: Pay Off High-Interest Debt and Avoid Unnecessary Borrowing
Debt can help you pay for an important need, such as education, a home, or an emergency. However, debt can become difficult to manage when monthly payments take a large part of your income or when high interest causes the total amount to grow over time.
For personal finance beginners, learning how to manage debt is an important part of building financial stability. The goal is not always to become debt-free overnight. The goal is to understand what you owe, make payments on time, reduce expensive debt strategically, and avoid borrowing for expenses you may not be able to afford.
Before choosing a repayment strategy, create a clear list of every loan, credit-card balance, EMI, or other amount you owe. When all your debt is visible in one place, it becomes easier to decide what to pay first and how much you can realistically contribute each month.
Understand the True Cost of Your Debt
Many people focus only on the monthly EMI. However, the EMI does not always show the complete cost of borrowing. You should also understand the interest rate, repayment period, processing fees, late-payment charges, and total amount you may repay.
For example, two loans may have the same monthly payment but different interest rates or repayment periods. The loan with the higher interest rate may cost more over time, even if the monthly payment appears manageable.
Debt Type
Amount Remaining
Interest Rate
Minimum Monthly Payment
Credit-card balance
₹20,000
36% per year
₹2,000
Personal loan
₹50,000
16% per year
₹3,000
Education loan
₹1,50,000
9% per year
₹4,000
In this example, the credit-card balance has the highest interest rate. If all minimum payments are affordable and current, paying extra toward the highest-interest debt may reduce interest costs. However, your repayment plan should consider your complete financial situation.
Before borrowing, review the repayment responsibility carefully. SEBI’s official guide on thinking before you borrow money explains that borrowing creates financial responsibilities and should not be used for avoidable or unnecessary expenses.
Create a Complete Debt List
Write down every debt in one place. Do not rely only on memory because it is easy to forget due dates, fees, or small balances.
Your debt list should include:
The name of the lender
The total amount remaining
The interest rate
The minimum monthly payment
The payment due date
The remaining repayment period
Any late-payment fees or penalties
Once your list is complete, calculate the total amount you pay toward debt every month. Compare that number with your monthly take-home income and essential expenses.
If you have not created a clear monthly spending plan yet, review Step 2: Create a Realistic Budget before increasing your debt payments. A repayment plan should fit your budget so that you can continue paying consistently.
Choose a Debt-Repayment Method
Two popular debt-repayment methods are the debt avalanche and the debt snowball. Both can work, but they focus on different priorities.
Method 1: The Debt Avalanche
With the debt avalanche method, you continue making the required minimum payments on all debts. Any extra money is directed toward the debt with the highest interest rate.
After the highest-interest debt is paid off, you move the extra payment to the debt with the next-highest interest rate.
With the debt snowball method, you continue making the required payments on all debts and direct extra money toward the smallest balance first.
After paying off the smallest debt, you add that payment amount to the next-smallest debt. This creates a series of small wins that may help some people stay motivated.
The debt snowball may not always minimize total interest, but motivation can be valuable if it helps you continue the repayment plan.
Method
Priority
Possible Benefit
Debt avalanche
Highest interest rate first
May reduce total interest costs
Debt snowball
Smallest balance first
May create faster motivational wins
Choose the method that you can follow consistently. A mathematically efficient plan is less useful if it is too difficult to maintain.
Always Pay Required Amounts on Time
Even when you are focusing extra money on one debt, continue making the required payments on your other debts. Missing payments may result in late fees, additional interest, or other financial consequences.
Set reminders a few days before each due date. If your income arrives on a predictable schedule, you may also consider automatic payments, provided you keep enough money in your account.
RBI’s Financial Literacy Guide includes responsible borrowing and timely repayment as important financial education topics.
Do Not Borrow More While Paying Off Existing Debt
It is difficult to reduce debt if new borrowing continues to replace the amount you repay. Before taking another loan or using credit for a non-essential purchase, ask yourself:
Is this expense necessary?
Can I wait and save for it instead?
Can I afford the monthly payment after paying essential expenses?
What will the total borrowing cost be?
Will this new payment make my current debt harder to manage?
A new loan may be appropriate for some important needs, but it should not be treated as free money. Every borrowed amount has a repayment responsibility.
SEBI also advises investors not to borrow money for securities-market investments. You can review its official investment dos and don’ts before making investment decisions.
Use Extra Income Strategically
If you receive a bonus, freelance payment, tax refund, or other extra income, you do not have to use all of it for debt. However, allocating a planned portion toward high-interest debt may help you reduce the balance faster.
For example, imagine that you receive an extra ₹10,000:
Purpose
Amount
Emergency savings
₹3,000
Extra high-interest debt payment
₹5,000
Upcoming essential expense
₹2,000
This is only an example. If you have no emergency savings, keeping some money available may help you avoid borrowing again when an unexpected expense occurs.
Arman has three debts: a ₹5,000 credit-card balance, a ₹20,000 personal loan, and a ₹40,000 education loan. He pays the required amount on each debt but has an additional ₹2,000 available every month.
Using the debt avalanche method, Arman directs the extra ₹2,000 toward the debt with the highest interest rate while continuing the required payments on the other two debts. When the first debt is paid off, he adds its previous payment to the next priority.
Using the debt snowball method, he would pay the smallest balance first. Both approaches can create progress. The important part is that Arman has a clear plan and avoids adding unnecessary new debt.
Common Debt-Management Mistakes to Avoid
Looking only at the EMI and ignoring the interest rate
Taking a new loan to pay for avoidable expenses
Missing due dates because payments are not tracked
Paying extra toward one debt while missing required payments on another
Using new credit while trying to reduce existing debt
Ignoring fees, penalties, and the total repayment cost
Borrowing money to make high-risk investments
Step 3 Debt-Repayment Action Plan
List every debt, balance, interest rate, and due date.
Calculate your total required monthly debt payments.
Make a realistic budget before increasing repayments.
Choose the debt avalanche or debt snowball method.
Continue making required payments on all debts.
Direct extra money toward your chosen priority debt.
Avoid unnecessary new borrowing.
Review your progress once each month.
Quick Takeaway
Managing debt is not only about paying money faster. It is about understanding interest costs, making payments on time, choosing a realistic strategy, and avoiding unnecessary borrowing.
For personal finance beginners, a clear debt plan can reduce financial pressure and create more room for savings and future goals. Progress may be gradual, but consistent payments and better borrowing decisions can make a meaningful difference over time.
Now that you have started protecting yourself with savings and managing expensive debt, the next step is to automate your savings and build consistent financial habits.
Step 4: Automate Your Savings and Investments for Consistent Growth
Creating a budget and building an emergency fund are important, but consistency is what turns good financial intentions into long-term progress. Many people plan to save money every month, yet they wait until the end of the month and discover that very little is left. Automating your money can help solve this problem.
For personal finance beginners, automation means setting up a planned transfer so that a portion of your income moves toward savings or investments automatically. Instead of depending only on memory, motivation, or willpower, you create a system that supports your financial goals every time you receive money.
Automation does not guarantee investment returns, and it does not replace financial planning. However, it can make saving more consistent and reduce the temptation to spend money that was intended for your future.
What Does Automating Your Finances Mean?
Financial automation means using your bank, investment platform, or payment system to complete selected money tasks automatically on a fixed date.
For example, if you receive your salary on the 5th of every month, you could arrange:
₹1,000 to move into your emergency savings account on the 6th
₹2,000 to be invested through a planned investment contribution on the 7th
Your regular EMI or bill payment to be scheduled before its due date
This approach follows a simple principle: save first and spend the remaining amount according to your budget. It is often easier than trying to save whatever remains after a month of spending.
Why Automation Can Improve Your Money Habits
People are busy, and financial tasks are easy to postpone. You may tell yourself that you will transfer money tomorrow, but an unexpected expense or an attractive purchase can change the plan.
Automation reduces the number of decisions you need to make each month. Once the system is set up correctly, your planned contribution can happen without requiring repeated effort.
Manual Saving
Automated Saving
You must remember to transfer money
The transfer follows a scheduled date
Saving may be delayed
Saving can happen soon after income arrives
Spending may happen before saving
Money is assigned to goals earlier
Progress may depend heavily on motivation
A system supports consistency
Automation is useful because it creates a repeatable process. However, you should still review your account balance and financial plan regularly. An automatic payment is helpful only when the amount and timing are appropriate for your income.
Start With a Small Automatic Savings Amount
You do not need to automate a large amount immediately. Start with an amount that fits your current budget and does not make it difficult to pay essential expenses.
For example, if your monthly income is ₹20,000, your first automated plan could look like this:
Financial Purpose
Monthly Amount
Transfer Date
Emergency fund
₹1,000
One day after income arrives
Long-term investment
₹2,000
Two days after income arrives
Future annual expenses
₹500
One day after income arrives
In this example, ₹3,500 is assigned to future goals. The remaining income can then be used for essential expenses, debt payments, and personal spending according to the budget.
If ₹3,500 is not affordable, start with ₹500 or ₹1,000. The purpose is to build a sustainable habit. You can increase the amount after reviewing your income and expenses.
Automate Savings Before Automating Investments
If you have no emergency savings and your financial situation is unstable, building a basic emergency fund may be more important than increasing investment contributions. Investment values can rise or fall, while emergency money is intended to remain available for unexpected essential expenses.
A practical order may be:
Pay essential bills and required debt payments.
Build a basic emergency fund.
Automate regular savings.
Begin long-term investing according to your goals and risk tolerance.
Increase contributions gradually as your financial position improves.
In India, many investors use a Systematic Investment Plan, commonly called a SIP, to invest a fixed amount at regular intervals in a mutual fund. A SIP is a method of investing regularly; it does not guarantee profits or protect against market losses.
According to the Association of Mutual Funds in India (AMFI), a SIP allows investors to invest a fixed amount periodically. Before investing, understand the fund’s objective, risk level, costs, and whether it matches your financial goals.
For example, someone may invest ₹2,000 per month through a SIP for a long-term goal. The investment amount remains fixed, but the value of the investment can move up or down depending on market performance.
If you are new to mutual funds, your article on best-performing FlexiCap funds can be linked here only if that is the exact working URL. Otherwise, search for the article inside WordPress and select the correct page before publishing.
Choose the Right Date for Automatic Transfers
The timing of automation matters. Setting a transfer date before your income arrives may cause a failed transaction or create pressure on your account balance.
A simple approach is to schedule savings one or two days after your salary, business income, or regular payment usually arrives.
For example:
Income arrives: 5th of the month
Emergency-fund transfer: 6th
Investment contribution: 7th
Bill and EMI payments: According to their due dates
Budget review: Last day of the month
If your income is irregular, avoid setting an automatic amount that could leave you short of money. You may prefer to transfer a percentage of each payment manually or automate a small base amount.
A Simple Automation Example
Meera earns ₹30,000 per month. She wants to save and invest but usually spends most of her money before the month ends.
She creates the following system:
Purpose
Amount
Emergency savings
₹2,000
Long-term investment
₹3,000
Future expenses
₹1,000
Every month, ₹6,000 is assigned automatically after she receives her income. She then manages the remaining ₹24,000 using her monthly budget.
After three months, Meera reviews the plan. Because her essential expenses are under control, she increases her savings contribution by ₹500. She does not make a large change all at once; she improves the system gradually.
Review Automated Payments Regularly
Automation should not become “set it and forget it.” Your income, expenses, goals, and financial responsibilities may change.
Review your automated transfers at least every three to six months and ask:
Is the savings amount still affordable?
Have my essential expenses increased?
Is my emergency fund progressing toward its target?
Does my investment still match my financial goal and risk tolerance?
Have any automatic payments become unnecessary?
Is there enough money in my account before each payment date?
The SEBI Investor Education portal provides educational information about investing and investor awareness. Before investing, understand the product instead of choosing it only because it is popular or has performed well recently.
Common Automation Mistakes to Avoid
Automating an amount that is too large for your budget
Scheduling transfers before income usually arrives
Ignoring account balances and payment failures
Investing emergency money in volatile assets
Increasing investment contributions while high-interest debt remains unmanaged
Choosing an investment without understanding its risks
Never reviewing old automatic payments or subscriptions
Step 4: 15-Minute Automation Action Plan
Review your monthly income and essential expenses.
Choose a realistic savings amount.
Select a separate account for emergency savings.
Schedule the transfer one or two days after income arrives.
Decide whether you are financially ready for long-term investing.
Set up investment contributions only after understanding the risks and product.
Turn on transaction alerts and check that payments are successful.
Review the entire system every three to six months.
Key Takeaway
Automating savings and investments can make financial progress more consistent because it turns a good intention into a repeatable system. Start with an affordable amount, protect your emergency savings, understand investment risks, and review your automatic payments regularly.
For personal finance beginners, the goal is not to automate the largest possible amount. The goal is to create a sustainable financial system that supports your needs today while helping you prepare for future goals.
Next: After creating a consistent savings system, the next step is to diversify your investments and manage risk instead of depending too heavily on a single asset or investment.
Step 5: Diversify Your Investments and Manage Risk Wisely
After building an emergency fund, managing expensive debt, and creating a regular saving habit, you may begin thinking about long-term investing. However, investing all your money in one company, one sector, one fund, or one type of asset can create unnecessary risk.
For personal finance beginners, diversification means spreading your investments instead of depending too heavily on a single investment. Diversification cannot guarantee profits or prevent all losses, but it may reduce the damage if one investment performs poorly.
A strong investment plan is not only about finding the investment with the highest recent return. It should also consider your financial goals, time horizon, risk tolerance, emergency savings, existing debt, and the purpose of the money you are investing.
What Does Investment Diversification Mean?
Diversification is often explained with the phrase, “Do not put all your eggs in one basket.” In personal finance, this means avoiding excessive dependence on one company, industry, asset class, or investment idea.
For example, imagine that Ravi invests his entire ₹1,00,000 in shares of only one company. If that company faces financial problems, the value of a large part of his investment may fall.
Now imagine that another investor spreads money across different investments based on their goals and risk capacity. If one investment performs poorly, the other investments may reduce the overall impact. This does not remove risk, but it can reduce concentration risk.
Highly Concentrated Portfolio
More Diversified Portfolio
Most money is invested in one company or asset
Money is spread across multiple investments
One poor investment may have a large impact
The effect of one investment may be reduced
Higher concentration risk
Risk may be spread across different areas
Returns depend heavily on one outcome
The portfolio is less dependent on one investment
The Investor.gov guide to diversification explains that diversification involves spreading investments among different assets to reduce the impact of a single investment on an overall portfolio.
Understand the Main Types of Investment Risk
Investment risk is not only the possibility that prices may fall. Different investments can involve different risks, and understanding them can help you make more informed decisions.
Market risk: Investment values may rise or fall because of economic conditions, interest rates, company performance, or market sentiment.
Concentration risk: Too much money is invested in one company, sector, asset, or investment theme.
Liquidity risk: You may not be able to access your money quickly without selling at an unfavorable price.
Inflation risk: Your money may lose purchasing power if its growth does not keep up with rising prices.
Credit risk: A borrower or issuer may fail to make expected payments.
Understanding these risks does not mean avoiding every investment. It means knowing what could happen before you commit your money.
Match Your Investments With Your Financial Goals
Before choosing an investment, decide what the money is for and when you may need it. Money needed next year may require a different approach from money intended for a goal that is ten or twenty years away.
Financial Goal
Possible Time Horizon
Important Consideration
Emergency expense
Any time
Safety and quick access may be more important than growth
Course fee or planned purchase
1–2 years
Avoid taking unnecessary market risk with money needed soon
Buying a home
5–10 years
Consider the target date and your ability to handle investment changes
Long-term financial independence
10+ years
Long-term growth, risk, and diversification may become more relevant
Emergency savings should remain separate from long-term investments because you may need emergency money quickly. If you have not built an emergency fund yet, return to Step 2: Build an Emergency Fund and create a basic financial safety net first.
For a broader money-management framework, you can also read our guide on Financial Planning for Beginners: 10 Simple Steps. It explains how budgeting, saving, debt management, financial goals, and investing can work together.
Understand Asset Allocation
Asset allocation means deciding how your investment money is divided among different investment categories. There is no single allocation that is suitable for everyone.
Your financial goals, income, responsibilities, time horizon, and ability to handle losses can affect the type of allocation that may be appropriate for you.
For educational purposes, a sample portfolio could look like this:
Investment Category
Example Allocation
Possible Purpose
Equity-oriented investments
50%
Long-term growth potential
Debt or fixed-income investments
30%
Potential stability and income
Cash or short-term savings
20%
Liquidity and near-term needs
This is only an example for understanding asset allocation. It is not a recommended portfolio. Your own allocation should be based on your financial goals, risk capacity, and time horizon.
Diversification Does Not Mean Buying Everything
Some beginners believe that buying many investments automatically creates diversification. However, owning a large number of products does not always reduce risk.
For example, buying shares of ten companies from the same industry may still create concentration risk. Similarly, investing in several funds that hold many of the same companies may create more overlap than you expect.
Before adding a new investment, ask:
What does this investment add to my portfolio?
Does it hold many of the same assets I already own?
Does it support one of my financial goals?
Do I understand its risks and costs?
Am I buying it because of a clear plan or only because it recently performed well?
The goal is not to own the largest number of investments. The goal is to avoid unnecessary concentration while keeping your financial plan understandable.
Understand Mutual Funds Before Investing
Mutual funds may provide exposure to multiple securities through a single investment product. However, different funds have different objectives, risks, costs, investment styles, and portfolio holdings.
Before investing, read the scheme information, understand the investment objective, review the risk level, and check whether the fund matches your financial goal.
The AMFI Investor Knowledge Centre provides educational information about mutual funds, investor awareness, and important investment concepts.
If you want to learn more about one mutual-fund category, read our detailed guide on Best Performing FlexiCap Funds. The article can help you understand what to examine beyond past returns, including investment strategy, risk, consistency, and long-term suitability.
A Practical Diversification Example
Suppose Sana has ₹1,20,000 available. Before investing, she checks whether she has enough emergency savings, whether she has expensive debt, and when she may need the money.
She realizes that she may need ₹20,000 within the next year and wants to keep ₹30,000 available for emergencies. Instead of investing the entire ₹1,20,000 in one company, she separates the money according to its purpose.
Financial Purpose
Example Amount
Emergency savings
₹30,000
Near-term planned expense
₹20,000
Long-term investment goal
₹70,000
This example shows that diversification is not only about dividing investments. It also includes separating emergency money, short-term goal money, and long-term investment money.
Review Your Investments Without Reacting Emotionally
Investment prices may change every day. Checking your portfolio constantly can increase stress and may encourage emotional decisions.
Instead, review your investments on a planned schedule, such as every six or twelve months, or when your financial goals change.
During a review, ask:
Does this investment still support my financial goal?
Has my time horizon changed?
Has my income or financial responsibility changed?
Has one investment become too large a part of my portfolio?
Do I understand what I own?
Are the risks and costs still acceptable?
A review does not always mean buying or selling. Sometimes the correct action is to continue following a suitable long-term plan.
Use Reliable Investment Information
Investment decisions should not be based only on social-media trends, advertisements, or promises of guaranteed returns. Check official information and understand the product before investing.
The SEBI Investor Education portal provides investor-awareness information and educational resources. It can help beginners understand important investment concepts and recognize the need for informed decision-making.
If you are using digital tools to organize your financial information, read our guide on 10 Best AI Tools to Manage Your Personal Finances in 2026. These tools may help with budgeting, expense tracking, planning, and research, but important financial information should always be verified.
Common Diversification Mistakes to Avoid
Investing all your money in one company or sector
Choosing investments only because of recent high returns
Copying another person’s portfolio without understanding it
Investing emergency money in volatile assets
Buying many funds without checking portfolio overlap
Ignoring investment costs and risk information
Making decisions because of short-term market fear or excitement
Assuming diversification guarantees profit or eliminates all losses
Step 5: Investment Diversification Action Plan
Write down your financial goals and target dates.
Keep emergency savings separate from long-term investments.
Review your current investments and identify concentration risk.
Check whether multiple investments hold similar assets.
Understand the purpose, risk, and cost of every investment.
Choose an allocation based on your goals and risk capacity.
Avoid investing only because of recent returns or online trends.
Review your portfolio periodically instead of reacting to daily price changes.
Key Takeaway
Diversification is a risk-management strategy, not a guarantee of profit. By spreading investments thoughtfully, matching them with your financial goals, and avoiding excessive dependence on one asset, you can build a more balanced financial plan.
For personal finance beginners, the most important rule is to understand what you own and why you own it. Keep emergency money separate, invest according to your time horizon, and avoid making decisions based only on recent performance.
Next: After building a diversified investment approach, the next step is to improve your financial knowledge and stay informed without becoming overwhelmed by financial news, trends, or social-media advice.
Step 6: Improve Your Financial Knowledge and Stay Informed
Managing money is not only about earning, budgeting, saving, or investing. Good financial decisions also depend on understanding how money works. Financial products, interest rates, investment options, technology, and economic conditions can change over time. That is why improving your financial knowledge can help you make more informed decisions and avoid costly mistakes.
For personal finance beginners, financial education does not mean becoming an accountant, economist, or investment expert. It means learning enough to understand your financial choices, compare options, recognize risks, ask useful questions, and avoid making decisions only because something is popular on social media.
You do not need to study finance for several hours every day. Even 20 to 30 minutes of focused learning each week can improve your understanding when you apply what you learn to your own income, expenses, savings, debt, investments, and financial goals.
Why Financial Knowledge Is Important
Many financial problems happen because people do not fully understand interest rates, loan terms, investment risks, fees, inflation, or the long-term effect of their decisions.
For example, imagine that two people want to invest ₹2,000 every month. The first person invests because a social-media creator says that a particular investment will provide very high returns. The second person spends time learning about risk, diversification, investment time horizons, fees, and how the investment actually works.
Neither person can predict future returns. However, the second person is more likely to understand the possible benefits and risks before investing.
Learn the Most Important Personal Finance Topics First
There is a huge amount of financial information online. Trying to learn everything at once can create confusion. A better approach is to begin with the topics that directly affect your financial life.
Financial Topic
What You Should Learn
Why It Matters
Budgeting
Income, expenses, spending limits, and monthly planning
Helps you understand where your money goes
Saving
Emergency funds, savings goals, and consistent saving habits
Helps create financial security
Debt
Interest rates, EMIs, repayment periods, and borrowing costs
Helps you manage debt responsibly
Investing
Risk, return, diversification, time horizon, and fees
Helps you make informed long-term decisions
Financial Goals
Target amounts, deadlines, and monthly contributions
Gives your money a clear purpose
Credit
Payment history and responsible borrowing
Can affect future borrowing opportunities
Start with the topic that is most important to your current situation. If you are struggling to save money, first learn about spending habits and budgeting. If you have expensive debt, understand interest costs and repayment strategies before focusing heavily on investing.
If you earn regularly but still struggle to save, read our detailed guide on why you can’t save money even with a good salary. It explains hidden spending patterns and practical ways to improve your saving habits.
Use Reliable Financial Sources Instead of Following Every Trend
Social media can help you discover financial ideas, but short videos and viral posts often leave out important details. A person may show high investment returns without explaining the risks, fees, losses, taxes, or time involved.
Before acting on financial information, check whether the source is reliable and whether the information applies to your situation.
Ask these questions:
Who published this information?
Is the source a government agency, financial regulator, recognized institution, or qualified professional?
Does the content explain risks as well as possible benefits?
Is the information current?
Is someone trying to sell a financial product?
Can the information be verified through another reliable source?
For beginner investment education, Investor.gov’s introduction to investing explains important topics such as financial goals, risk, diversification, long-term investing, and the difference between saving and investing.
Use Financial Technology to Learn and Manage Money
Technology can make financial learning easier. Budgeting apps, expense trackers, calculators, banking tools, and AI-powered financial tools can help you organize information and understand your financial habits.
However, a tool should support your decisions rather than replace your judgment. Before sharing financial information with an app or AI tool, check its privacy policy, security practices, and the type of information it collects.
To explore useful tools in more detail, read our guide on 10 Best AI Tools to Manage Your Personal Finances in 2026. The article explains how different tools may help with budgeting, expense tracking, financial planning, and money management.
Financial tools can help you organize information, but they may not understand your complete financial situation. Verify important information before making a major financial decision.
Understand an Investment Before You Put Money Into It
One of the most useful financial habits is refusing to invest in something you do not understand. A product may have a professional-looking website, a popular name, or strong past returns, but those factors do not automatically make it suitable for your goals.
Before investing, try to answer these questions in simple language:
What does this investment actually do?
How can it make or lose money?
What are its main risks?
How long may I need to keep my money invested?
Can I access the money quickly if necessary?
What fees or charges may apply?
Does this investment match my financial goal and risk tolerance?
The Investor.gov guide to investment options explains that different investments have different risks, potential returns, and characteristics. Understanding these factors can help investors make more informed decisions.
If you want to understand one mutual-fund category in greater detail, read our guide on Best Performing FlexiCap Funds. It explains important factors to evaluate beyond past returns, including investment strategy, risk, consistency, and long-term suitability.
Create a Simple Weekly Financial Learning Routine
You do not need a complicated study plan. A small routine is easier to follow and becomes more valuable when you apply the lessons to your own finances.
Day
Learning Activity
Suggested Time
Monday
Read one reliable article about budgeting or saving
10 minutes
Wednesday
Learn one financial term, such as inflation or interest
10 minutes
Friday
Study one investment concept or financial risk
15 minutes
Sunday
Apply one lesson to your own financial plan
15 minutes
The most important part is application. Reading about budgeting is useful, but reviewing your own spending is more practical. Learning about emergency funds is useful, but saving your first ₹100 or ₹500 turns knowledge into action.
Keep a Personal Finance Learning Notebook
Create a notebook, document, or digital note where you explain financial concepts in your own words. Avoid copying complicated definitions without understanding them.
Financial Concept
Simple Meaning
Personal Action
Emergency Fund
Money reserved for unexpected essential expenses
I will begin by saving ₹5,000
Interest Rate
The cost of borrowing or the return offered by some savings products
I will compare rates before borrowing
Diversification
Spreading investments to reduce dependence on one investment
I will avoid putting all my money into one company
Writing financial ideas in your own words can help you identify what you understand and what you need to learn further.
Learn From Your Own Financial Decisions
Your monthly financial activity is also a learning opportunity. At the end of each month, review your decisions and look for useful patterns.
Ask yourself:
Where did I spend more than expected?
Did I save the amount I planned?
Did I borrow money? If yes, why?
Which expense gave me real value?
Which expense could I reduce next month?
Did I make a financial decision without enough information?
For example, suppose you planned to spend ₹3,000 on food but spent ₹4,500. Instead of only saying that your budget failed, find the reason. Did prices increase? Did you order food more often? Did you forget to include an important expense?
The answer can help you create a more realistic financial plan next month.
A Practical Financial Learning Example
Arif wants to invest ₹3,000 every month. Before investing, he spends one week learning about risk, diversification, investment time horizons, and fees.
He discovers that he may need part of the money within one year. Instead of investing the complete ₹3,000 without a plan, he separates his short-term needs from his long-term goals.
Financial Purpose
Monthly Amount
Short-term savings goal
₹1,000
Emergency savings
₹1,000
Long-term investment goal
₹1,000
The amounts are only examples. The important lesson is that financial knowledge helped Arif create a plan based on his own needs instead of copying someone else’s investment decision.
Common Financial Learning Mistakes to Avoid
Believing every viral financial video
Following investment tips without checking the source
Focusing only on returns and ignoring risk
Learning advanced investing before understanding budgeting
Buying a financial product without reading important information
Assuming past performance guarantees future results
Copying another person’s financial plan without considering your own goals
Reading financial content without applying anything to your own situation
Step 6: Financial Learning Action Plan
Choose one personal finance topic to study this week.
Use an official or reliable educational source.
Learn the concept in simple language.
Write the main lesson in your own words.
Check how the concept applies to your income, expenses, savings, or goals.
Take one small action based on what you learned.
Review the result at the end of the month.
Continue learning without rushing into financial products.
Key Takeaway
Financial knowledge is not about memorizing complicated terms. It is about understanding how your money decisions affect your present and future.
For personal finance beginners, learning the basics of budgeting, saving, debt, investing, risk, and financial goals can improve decision-making over time. Use reliable sources, question unrealistic promises, apply what you learn, and continue improving your financial knowledge step by step.
Next: After improving your financial knowledge, the next step is to use financial technology and digital money tools wisely while protecting your personal and financial information.
Step 7: Use Financial Technology and Money Tools Wisely
Financial technology has made managing money faster and more convenient. Today, you can check your bank balance, track expenses, pay bills, create a budget, invest, and monitor financial goals using a smartphone. However, technology is only useful when it helps you make better decisions instead of encouraging unnecessary spending or creating security risks.
For personal finance beginners, financial tools can simplify money management by organizing financial information in one place. A budgeting app may show where your money goes, an expense tracker may help identify unnecessary spending, and an automated transfer can make saving more consistent.
However, no app can automatically create good financial habits. A tool can show that you spent too much, but you still need to decide what to change. Use technology as a support system—not as a replacement for financial knowledge and personal responsibility.
How Financial Technology Can Help You Manage Money
Different financial tools are designed for different purposes. You do not need to install every app. Choose tools that solve a specific problem in your financial life.
Financial Tool
How It Can Help
What to Check
Banking App
Check balances, review transactions, transfer money, and pay bills
Security settings and transaction alerts
Budgeting App
Plan monthly income and expenses
Privacy policy and data access
Expense Tracker
Identify spending patterns
Accuracy and account permissions
Goal Tracker
Monitor progress toward savings goals
Whether the goals are realistic
Investment Platform
View investments and research products
Fees, risks, and regulatory information
AI Financial Tool
Organize information and explain financial concepts
Accuracy, privacy, and limitations
The best financial tool is not always the one with the most features. It is the one you can understand, use consistently, and trust with your information.
Use Budgeting and Expense-Tracking Tools to Understand Your Spending
Many people know their monthly income but cannot clearly explain where all their money goes. Small expenses can become difficult to notice when they happen through digital payments.
An expense tracker can help you categorize spending, such as:
Rent or housing
Food and groceries
Transportation
Mobile and internet bills
Entertainment
Shopping
Loan or EMI payments
Savings and investments
For example, suppose your monthly income is ₹25,000. You believe that you spend only ₹2,000 on online shopping and food delivery. After tracking your expenses for one month, you discover that the actual amount is ₹4,500.
The tool did not create the problem. It simply made the spending pattern visible. You can now decide whether reducing that category would help you save more.
If you are earning regularly but still struggle to save, read our guide on why you can’t save money even with a good salary. It explains hidden spending habits and practical ways to improve your savings.
Use Automation to Make Saving More Consistent
Automation can reduce the need to make the same financial decision every month. For example, you may schedule an automatic transfer to a savings account shortly after receiving your income.
Suppose you earn ₹30,000 per month and want to save ₹3,000. Instead of waiting until the end of the month to see what remains, you may automatically move ₹3,000 into savings after your income arrives.
Without Automation
With Automation
Save whatever remains at the end of the month
Move a planned amount soon after receiving income
Saving may be affected by unnecessary spending
Savings become part of the monthly system
Requires a new decision every month
Reduces repeated manual effort
Automation should still be reviewed regularly. If your income changes or you have an unexpected expense, you may need to adjust the amount.
Use AI Tools as Financial Assistants, Not Financial Decision-Makers
AI tools can help explain financial terms, summarize information, create a basic budget template, organize expenses, compare general financial concepts, and generate questions for research.
For example, you can ask an AI tool:
“Help me create a monthly budget using an income of ₹25,000.”
“Explain the difference between saving and investing in simple language.”
“Create a checklist for comparing two financial products.”
“Help me identify possible unnecessary expenses from this spending list.”
However, AI-generated information can be incomplete, outdated, or incorrect. Do not treat an AI response as personalized financial advice. Verify important information using official sources before making major decisions.
Convenience should not come at the cost of security. Financial apps may contain sensitive information, including account details, transaction history, personal information, and spending patterns.
Before installing or connecting a financial app, check what information it requests and why it needs that access.
Follow these basic security practices:
Use a strong and unique password for important financial accounts.
Enable two-factor authentication when available.
Keep your phone and financial apps updated.
Do not share OTPs, passwords, PINs, or security codes.
Avoid entering financial information on suspicious websites.
Review app permissions before connecting bank accounts.
Check Privacy Before Connecting Your Financial Accounts
Some financial tools request permission to access account information or transaction data. Before approving access, read the privacy policy and understand what data the company collects, stores, shares, or uses.
Ask these questions:
What financial information will the app access?
Why does the app need this information?
Does the company explain how it protects user data?
Can you delete your data or close your account?
Does the company share information with third parties?
Can you use the tool without connecting your bank account?
Do not connect an account only because an app promises convenience. The benefit should be worth the information you are sharing.
Use Investment Apps Carefully
Investment apps can make buying and selling easier, but convenience may also encourage frequent decisions. Seeing prices change every minute can create fear or excitement and lead to emotional actions.
Before using an investment platform, understand:
What investment products are available?
What fees or charges may apply?
What risks are involved?
How quickly can you access your money?
Is the platform regulated where required?
Does the investment match your financial goal?
The SEBI Investor Education portal provides educational information to help investors understand financial markets, investment risks, and informed decision-making.
Before selecting a mutual fund or investment category, you can also read our guide on Best Performing FlexiCap Funds. Past performance alone should not be the only factor in an investment decision.
A Practical Example: Creating a Simple Digital Money System
Suppose Sameer earns ₹30,000 per month. He wants to improve his money management but does not want to use many different apps.
He creates a simple system:
Financial Activity
Tool or Method
Monthly Action
Track spending
Expense tracker
Review expenses every Sunday
Save money
Automatic bank transfer
Move ₹3,000 after receiving income
Pay bills
Banking app reminder
Check due dates before payment
Monitor goals
Simple spreadsheet
Update savings progress monthly
Learn about finance
Reliable educational websites
Study one topic each week
Sameer does not need ten financial apps. He uses a small number of tools with clear purposes and reviews them regularly.
Common Financial Technology Mistakes to Avoid
Installing many financial apps without using them consistently
Giving unnecessary permissions to an app
Sharing OTPs, PINs, passwords, or security codes
Trusting AI-generated financial information without verification
Making investment decisions because an app makes trading easy
Ignoring privacy policies and data-sharing practices
Using the same password for multiple financial accounts
Following notifications that encourage unnecessary spending
Connecting financial accounts to unknown or unverified apps
Step 7: Financial Technology Action Plan
Choose one financial problem you want technology to help solve.
Select one simple and reliable tool instead of downloading many apps.
Use an expense tracker for at least 30 days.
Turn on useful transaction and payment alerts.
Automate a realistic savings amount if your cash flow allows it.
Review app permissions and privacy settings.
Enable strong security and two-factor authentication.
Verify important financial information before acting on it.
Review your tools every three to six months.
Key Takeaway
Financial technology can make money management easier, but it cannot replace financial knowledge, discipline, or careful decision-making.
For personal finance beginners, the best approach is to use a small number of reliable tools for clear purposes—such as tracking expenses, automating savings, monitoring goals, and learning financial concepts. Protect your information, review permissions, and verify important financial details before taking action.
Next: After creating a simple financial system, the next step is to set clear financial goals and track your progress so that your income, savings, and investments have a defined purpose.
Step 8: Set Clear Financial Goals and Track Your Progress
Saving money without a clear purpose can feel difficult. When you do not know what you are saving or investing for, it becomes easier to spend the money on short-term wants. Financial goals give your money a direction and help you make decisions based on what matters most to you.
For personal finance beginners, setting financial goals does not mean creating an unrealistic plan to become wealthy quickly. It means deciding what you want your money to help you achieve, estimating how much you may need, choosing a realistic timeline, and taking small, consistent steps.
Your goals may include building an emergency fund, paying off debt, buying a phone, funding education, starting a business, purchasing a home, or preparing for retirement. The goal can be different for every person because income, responsibilities, priorities, and financial situations are different.
Why Financial Goals Are Important
A financial goal turns a general wish into a measurable plan.
For example, saying, “I want to save more money,” is a good intention, but it does not explain how much you want to save or when you want to achieve it.
A clearer goal would be:
“I want to save ₹30,000 for my emergency fund within 12 months by saving ₹2,500 every month.”
This goal has a target amount, a timeline, and a monthly action. You can measure your progress and adjust the plan if your income or expenses change.
Understand the Three Main Types of Financial Goals
Dividing your goals by time can help you decide how much money you need and when you may need it.
Goal Type
Typical Time Frame
Examples
Short-Term Goals
Less than 1–2 years
Emergency savings, a course fee, a phone, or paying a small debt
Medium-Term Goals
Approximately 2–5 years
Starting a business, buying a vehicle, or funding higher education
Long-Term Goals
More than 5 years
Buying a home, retirement, or long-term financial independence
The time frame is not fixed. A goal that is short-term for one person may take longer for another person. Your income, responsibilities, and available savings will affect the timeline.
Turn a Financial Wish Into a SMART Goal
A useful financial goal should be clear enough that you can measure and review it. You can use the SMART framework:
SMART Element
Meaning
Example
Specific
Clearly define the goal
Build an emergency fund
Measurable
Choose a target amount
Save ₹30,000
Achievable
Keep the plan realistic
Save ₹2,500 per month
Relevant
Connect the goal to your needs
Prepare for unexpected expenses
Time-Bound
Set a target date
Complete the goal in 12 months
A SMART goal may look like this:
“I will save ₹24,000 in 12 months by transferring ₹2,000 into my savings account every month.”
This is easier to follow than saying, “I will try to save more.”
Calculate How Much You Need to Save Each Month
Once you know your target amount and deadline, calculate the approximate monthly amount required.
Simple formula:
Monthly Savings Needed = Total Goal Amount ÷ Number of Months
Example:
Financial goal: ₹60,000
Time available: 20 months
₹60,000 ÷ 20 = ₹3,000 per month
In this example, you would need to save approximately ₹3,000 each month if your income and expenses remain stable.
However, do not create a savings target that forces you to miss essential expenses or rely on expensive borrowing. If ₹3,000 is not realistic, extend the timeline or reduce the target amount.
Prioritize Your Financial Goals
You may have several goals at the same time, but your income may not be enough to fund all of them equally. Prioritization helps you decide where your money should go first.
Priority Level
Example Goal
Reason
High Priority
Emergency fund or high-interest debt
May protect financial stability and reduce expensive costs
Medium Priority
Education, skill development, or a planned purchase
Important but may have a flexible timeline
Long-Term Priority
Retirement or long-term investing
May require consistent contributions over many years
For example, if you have high-interest debt and no emergency savings, it may be more practical to improve those areas before putting a large amount into a long-term investment.
Financial priorities can change. A new job, family responsibility, income reduction, or unexpected expense may require you to adjust your plan.
Create a Goal-Based Money Plan
Instead of keeping all your money in one general savings category, assign each amount a purpose. This can make your progress easier to understand.
Suppose Ayaan has ₹5,000 available each month after essential expenses:
Financial Goal
Monthly Amount
Purpose
Emergency fund
₹2,000
Prepare for unexpected essential expenses
Debt repayment
₹1,500
Reduce an existing financial obligation
Education or skill fund
₹1,000
Support future learning
Personal goal
₹500
Save for a planned purchase
This is only an example. Your own plan should depend on your income, essential expenses, debt, emergency needs, and priorities.
Track Your Financial Progress Regularly
Setting a goal is only the first step. Tracking helps you see whether your actions are moving you closer to the target.
You can track progress using:
A notebook
A spreadsheet
A budgeting app
A savings tracker
Your banking app
A simple monthly checklist
For example:
Month
Target Savings
Actual Savings
Total Progress
January
₹2,500
₹2,500
₹2,500
February
₹2,500
₹2,000
₹4,500
March
₹2,500
₹3,000
₹7,500
Progress does not need to be perfect every month. If you save less during one month because of an important expense, review the reason and adjust the next month instead of abandoning the goal.
Use Financial Tools to Track Goals More Easily
Digital tools can make goal tracking faster. A budgeting app, spreadsheet, expense tracker, or AI-powered financial tool may help you organize your income, expenses, savings targets, and progress.
However, technology should support your plan rather than create unnecessary complexity. You do not need ten different apps to track one financial goal.
To explore useful digital tools, read our detailed guide on 10 Best AI Tools to Manage Your Personal Finances in 2026. It explains how different tools may support budgeting, expense tracking, financial planning, and money management.
Review Goals Without Feeling Discouraged
Your financial plan should be flexible. If your income changes, an emergency occurs, or your expenses increase, you may need to change the amount or timeline.
For example, suppose your goal is to save ₹30,000 in one year, but you can save only ₹15,000 after six months. Instead of giving up, review your situation:
Can you reduce one unnecessary expense?
Can you increase your income?
Can you extend the deadline?
Can you reduce the target amount?
Was there an unexpected expense that affected your progress?
Adjusting a financial goal is not the same as failing. A realistic plan should be able to adapt to changes in your life.
If you are earning a reasonable income but still cannot save consistently, our guide on why you can’t save money even with a good salary may help you identify hidden spending patterns and improve your savings system.
Use Long-Term Goals to Guide Investment Decisions
Long-term financial goals can help you decide why you are investing and how much risk may be appropriate. Before choosing an investment, consider when you may need the money and whether you can handle changes in its value.
The Investor.gov investing basics explain that financial goals, time horizon, risk tolerance, and investment choices are connected.
If you are researching mutual funds, you can also read our guide on Best Performing FlexiCap Funds. Past returns should not be the only factor; the investment strategy, risk, costs, and suitability for your goal are also important.
A Practical Financial Goal Example
Suppose Sana wants to build a ₹50,000 emergency fund within 20 months.
She calculates:
₹50,000 ÷ 20 months = ₹2,500 per month
Her plan looks like this:
Action
Plan
Monthly savings target
₹2,500
Transfer date
Within two days of receiving income
Tracking method
Simple spreadsheet
Review schedule
Last Sunday of every month
Adjustment plan
Extend the timeline if income falls
After four months, Sana has saved ₹9,000 instead of the planned ₹10,000 because of an unexpected expense. She reviews her budget and decides to add ₹500 during the next two months. Her goal remains flexible and realistic.
Common Financial Goal Mistakes to Avoid
Setting a goal without choosing a target amount
Creating an unrealistic deadline
Trying to fund too many goals at the same time
Ignoring emergency savings
Saving without tracking progress
Using borrowed money to meet a savings target
Comparing your financial progress with other people
Giving up after one difficult month
Never reviewing or updating your goals
Step 8: Financial Goal Action Plan
Write down your three most important financial goals.
Choose a target amount for each goal.
Set a realistic deadline.
Calculate the approximate monthly amount required.
Rank your goals by priority.
Choose a simple tracking method.
Review your progress once every month.
Adjust the amount or timeline when your financial situation changes.
Celebrate progress without creating unnecessary spending.
Key Takeaway
Financial goals give your money a purpose. A clear target, realistic timeline, regular contribution, and simple tracking system can make a large financial goal feel more manageable.
For personal finance beginners, the best approach is to start with one important goal, take small and consistent actions, and review your progress regularly. Your financial plan does not need to be perfect—it needs to be realistic enough to continue.
Next: After setting clear financial goals, the next step is to build and protect a healthy credit profile by understanding responsible borrowing, timely payments, and credit-report monitoring.
What is personal finance for beginners?
Personal finance for beginners means learning how to manage income, expenses, savings, debt, insurance, and investments. The goal is to make informed money decisions, build financial security, and work toward short-term and long-term financial goals.
How should a beginner start managing money?
A beginner can start by tracking monthly income and expenses, creating a simple budget, saving a small amount regularly, building an emergency fund, and avoiding unnecessary debt. Start with a simple system that you can follow consistently.
How much money should a beginner save each month?
There is no single amount that works for everyone. Start with an amount that fits your income and essential expenses, even if it is small. Saving consistently is usually more sustainable than setting an unrealistic target and stopping after a few months.
Conclusion:
Personal finance does not require a high income, complicated calculations, or perfect money habits. It starts with understanding where your money comes from, where it goes, and what you want it to achieve.
By following these 10 steps, you can create a realistic budget, control unnecessary expenses, build an emergency fund, manage debt responsibly, set clear financial goals, and make better decisions about saving and investing. You do not need to complete everything at once. Start with one small action, such as tracking your expenses for a week or saving a fixed amount every month.
Your financial plan should also change as your income, responsibilities, and goals change. Review your progress regularly, learn from mistakes, and adjust your plan when necessary. A missed savings target or an unexpected expense does not mean your plan has failed—it simply shows that something may need to be improved.
For personal finance beginners, consistency is usually more valuable than trying to follow a perfect system. Small habits, repeated over time, can help you build greater financial confidence and move closer to long-term financial stability.
Start today: review your income and expenses, choose one financial goal, and take the first practical step toward managing your money better.
Personal Finance for Beginners: Quick Summary Personal finance for beginners starts with understanding your income, tracking expenses, and making a realistic plan for your money. You do not need a high income or a complicated system to begin. Small and consistent financial decisions can help you build better money habits over time. Understand your income, expenses, savings, and debts. Create a realistic monthly budget. Track spending and reduce unnecessary expenses. Build an emergency fund gradually. Manage debt responsibly and pay bills on time. Set clear short-term and long-term financial goals. Protect your finances with suitable insurance and basic security practices. Learn the basics before investing and understand the risks involved. Develop consistent financial habits instead of looking for quick results. Review your financial plan regularly and adjust it when your income, expenses, or goals change. The most important lesson is that financial progress does not usually happen through one big decision. It is built through small actions repeated consistently. Start with one practical step today, improve your system over time, and make decisions that support your financial goals.
How to Budget with Managing money becomes difficult when your income is not the same every month. Unlike salaried employees who receive a fixed paycheck, people with irregular income often face uncertainty — one month can bring high earnings, while the next month may be much lower.
The biggest challenge is not only earning money; it is creating a system that works when your income changes.
Many people with irregular income make the mistake of spending more during good months and struggling during slow months. Without a proper budgeting system, even a good income can disappear quickly.
This is where irregular income budgeting becomes important.
Instead of creating a budget based on your highest earning month, you need a flexible system that helps you manage expenses, save money, and prepare for unpredictable income.
In this guide, you will learn a practical step-by-step method to create a budget for irregular income, including how to calculate your minimum monthly expenses, manage variable spending, build an income buffer, and create a stable financial plan.
Whether you are a freelancer, self-employed professional, business owner, content creator, or anyone with changing income, this guide will help you take control of your money.
Now let’s start with the first and most important step: calculating your Minimum Monthly Expenses (Survival Budget).
What You Will Learn in This Guide
In this complete guide to budgeting with irregular income, you will learn:
How to calculate your minimum monthly expenses.
How to create a Survival Budget that works during low-income months.
How to separate essential expenses from unnecessary spending.
How to manage variable income without financial stress.
How to build an income buffer for unpredictable months.
How to create a long-term money management system.
This guide focuses on practical strategies that you can apply immediately, not just general budgeting advice.
Whether your income changes every week, every month, or seasonally, these methods will help you create a flexible financial system.
Now let’s start with the first step: calculating your Minimum Monthly Expenses (Survival Budget).
Step 1: Calculate Your Minimum Monthly Expenses (Survival Budget)
When your income changes every month, the first step is not deciding how much you should spend — it is understanding the minimum amount of money you actually need to run your life.
This amount is called your Survival Budget.
Your Survival Budget is the foundation of an effective irregular income budgeting system. It tells you the minimum money required to cover your essential expenses before you spend on lifestyle choices, entertainment, or other non-essential things.
For freelancers, self-employed professionals, business owners, and anyone with variable income, this system creates financial stability because you stop depending on your best earning months.
Why Your Survival Budget Is Important
Many people with irregular income follow an unstable money pattern:
The problem is not always income. The problem is not knowing your minimum financial requirement.
A Survival Budget helps you understand:
The minimum income you need every month.
Which expenses must be protected first.
How much extra money you can save or invest.
How to prepare for months when income is lower.
For example, if your minimum monthly expenses are $1,800, then your first financial target is not buying luxury items or increasing your lifestyle — it is securing that $1,800 amount first.
These expenses usually remain the same every month:
Rent or mortgage
Insurance
Phone and internet bills
Loan payments
Essential Variable Expenses
These expenses change but are necessary:
Groceries
Transportation
Electricity
Healthcare
Household needs
Minimum Financial Payments
Include all payments you cannot skip:
Credit card minimum payments
Loan installments
Other required payments
How to Calculate Your Minimum Monthly Expenses
1. Review Your Last 3–6 Months Spending
The first step is understanding your real spending pattern.
Check:
Bank statements
Payment apps
Credit card history
Expense tracking records
Write down every expense, including small purchases.
Many people underestimate small expenses because they seem insignificant. However, repeated small spending can reduce your savings significantly over time.
2. Separate Needs From Wants
After collecting your expenses, divide them into two categories.
Essential Expenses (Needs)
These are expenses required for your basic lifestyle:
Housing
Food
Utilities
Transportation
Healthcare
Insurance
Non-Essential Expenses (Wants)
These expenses are optional:
Eating outside
Entertainment
Shopping
Premium subscriptions
Luxury purchases
Reducing unnecessary expenses does not mean removing all enjoyment. It means creating space for your important financial goals.
This means you need at least $1,700 before spending money on optional things.
Any income above this amount can be used for:
Emergency savings
Investments
Debt reduction
Future low-income months
Common Mistakes To Avoid
Avoid these mistakes while creating your Survival Budget:
Planning your lifestyle around your highest income month.
Ignoring small recurring expenses.
Spending extra income immediately.
Not tracking your monthly cash flow.
Mixing business and personal expenses.
A proper Survival Budget protects you from financial uncertainty and gives you more control over your money.
Action Plan: Create Your Survival Budget Today
Follow these steps:
✅ Review your last 3–6 months of expenses. ✅ Write down every monthly cost. ✅ Separate needs and wants. ✅ Add only essential expenses. ✅ Calculate your Survival Budget number. ✅ Use this number as the base of your irregular income budget.
Once you know your Survival Budget, the next step is to calculate your Baseline Income — the income level you should target to create a stable financial system even when your earnings change every month.
Step 2: Calculate Your Baseline Income
Once you know your Survival Budget, the next step is to calculate your Baseline Income. This is one of the most important parts of budgeting with irregular income because it gives you a realistic income target instead of relying on your best earning month.
Many people make the mistake of planning their budget around the highest amount they have ever earned. For example, if you earned $5,000 last month, it’s easy to assume you’ll earn the same again. But irregular income rarely works that way. Some months are excellent, while others are much slower.
Your Baseline Income is the amount you can reasonably expect to earn on a consistent basis. It becomes the foundation for your monthly budget, savings plan, and financial decisions. Instead of chasing unpredictable numbers, you build your budget around a realistic average that keeps your finances stable throughout the year.
Why Your Baseline Income Matters
A Baseline Income helps you answer one simple question:
“How much money can I safely plan to spend every month?”
Without knowing this number, it becomes easy to overspend during good months and struggle during slow months.
Start by gathering your income from the last 6–12 months.
This may include:
Client payments
Freelance income
Business revenue
Commission earnings
Side hustle income
Part-time work
The longer the time period you review, the more accurate your Baseline Income will be.
2. Calculate Your Average Monthly Income
Add all your income from the past 6–12 months and divide it by the number of months.
Formula:
Baseline Income = Total Income ÷ Number of Months
Example:
Month
Income
January
$3,500
February
$2,400
March
$4,100
April
$2,800
May
$3,200
June
$3,000
Total Income = $19,000
Baseline Income = $19,000 ÷ 6 = $3,166
Instead of budgeting as if you’ll earn $4,100 every month, you should build your budget around $3,166, because it reflects your average earning pattern.
Don’t Budget Using Your Best Month
One of the biggest financial mistakes is treating your highest-income month as your normal income.
A better strategy is:
Budget using your Baseline Income.
Save extra income during high-earning months.
Use those savings to support low-income months.
This simple system creates consistency, even when your income is unpredictable.
Before moving to the next step, complete these tasks:
✅ Review your last 6–12 months of income.
✅ Add every income source.
✅ Calculate your average monthly income.
✅ Use this number as your Baseline Income.
✅ Ignore unusually high-income months when creating your budget.
Next Step: Now that you know your Baseline Income, the next step is to prioritize your expenses using a flexible budgeting system that works even when your income changes every month.
Step 3: Prioritize Essential Expenses First
Now that you know your Survival Budget and Baseline Income, it’s time to decide where your money should go first.
One of the biggest reasons people with irregular income struggle financially is not because they earn too little—but because they spend money in the wrong order.
Many people pay for shopping, entertainment, subscriptions, or lifestyle upgrades as soon as they receive income. Later, when rent, groceries, or utility bills are due, they find themselves short of cash.
A better approach is to prioritize your expenses based on importance, not urgency.
This simple habit ensures that even during a low-income month, your essential needs are always covered before you spend money on anything optional.
Why Prioritizing Expenses Is So Important
When your income changes every month, you cannot afford to treat every expense equally.
Some expenses keep your life running, while others simply make life more enjoyable.
If you pay for optional expenses before covering your basic needs, you’ll constantly feel financial pressure.
By prioritizing your expenses, you can:
Always pay your essential bills first.
Reduce financial stress during slow months.
Avoid relying on credit cards or loans.
Build better money habits.
Create a stable financial system even with unpredictable income.
Next Step: Now that your expenses are organized by priority, the next step is to build an Income Buffer that protects you during slow-income months and gives you greater financial confidence.
Step 4: Build an Income Buffer for Low-Income Months
By now, you’ve calculated your Survival Budget, estimated your Baseline Income, and learned how to prioritize essential expenses. The next step is creating an Income Buffer—a financial cushion that helps you stay stable during months when your income is lower than expected.
For people with irregular income, earning less in some months is completely normal. The real problem begins when there is no money set aside to cover essential expenses. That’s where an Income Buffer becomes one of the most powerful tools in your budgeting system.
Instead of worrying about whether next month’s income will be enough, you can use the money you’ve saved during high-income months to cover the gap. This creates peace of mind and helps you avoid borrowing money or using credit cards for everyday expenses.
Why an Income Buffer Is Important
An Income Buffer protects your monthly budget from unexpected income fluctuations.
Whether you’re a freelancer, self-employed professional, content creator, consultant, or seasonal worker, your income can change for many reasons—fewer clients, seasonal demand, delayed payments, or economic changes.
Without an Income Buffer, even a small drop in income can affect your ability to pay rent, buy groceries, or cover utility bills.
With an Income Buffer, your financial life becomes much more predictable because you already have money reserved for slower months.
According to the Consumer Financial Protection Bureau (CFPB), setting aside money for unexpected situations helps reduce financial stress and improves long-term financial stability.
How to Build an Income Buffer
1. Set a Clear Savings Target
Start with a realistic goal.
If you’re just beginning, aim to save enough money to cover one month of your Survival Budget.
Once you reach that goal, gradually increase it to cover:
One month of essential expenses.
Three months of essential expenses.
Six months of essential expenses for greater financial security.
Don’t try to save everything at once. Building an Income Buffer is a gradual process.
2. Save Extra Income During High-Earning Months
One of the biggest advantages of irregular income is that some months can be much better than others.
Instead of increasing your lifestyle during those months, save a portion of the extra income.
For example:
Survival Budget: $2,000
Monthly Income: $3,500
Instead of spending the extra $1,500, move part of it into your Income Buffer.
Over time, these small contributions create a strong financial cushion.
3. Keep Your Income Buffer Separate
Avoid keeping your Income Buffer in the same account you use for daily spending.
A separate high-yield savings account or dedicated savings account makes it less tempting to spend the money on non-essential purchases.
The FDIC Money Smart Program also encourages building healthy saving habits and keeping emergency savings separate from everyday spending.
4. Rebuild Your Buffer After Using It
An Income Buffer is meant to be used when income falls—not for shopping, vacations, or impulse purchases.
If you use part of your buffer during a slow month, make rebuilding it your priority during the next high-income month.
This keeps your financial safety net ready for future income fluctuations.
Real-Life Example
Imagine David is a freelance photographer.
His average monthly income is around $3,200, but some months he earns only $1,800.
His Survival Budget is $2,000.
During a busy wedding season, David saves an extra $600 every month into his Income Buffer.
A few months later, when business slows down, he uses the buffer to cover the difference instead of borrowing money or missing bill payments.
Because he planned ahead, his lifestyle remains stable even when his income changes.
Common Mistakes to Avoid
Avoid these mistakes when building your Income Buffer:
Spending all extra income during good months.
Keeping your buffer in your daily spending account.
Using the buffer for luxury purchases.
Stopping contributions after reaching your first savings goal.
Waiting for a financial emergency before starting to save.
Action Plan
Before moving to the next step, complete these tasks:
✅ Calculate your first Income Buffer target.
✅ Open a separate savings account if possible.
✅ Save a portion of every high-income month.
✅ Use the buffer only when your income falls below your normal level.
✅ Rebuild your buffer immediately after using it.
For more practical guidance on building emergency savings and financial resilience, you can also explore: MyMoney.gov – Emergency Funds.
Next Step: Once you have an Income Buffer in place, the next step is to create a Zero-Based Budget so every dollar you earn has a clear purpose and nothing is wasted.
Step 5: Use the Zero-Based Budgeting Method
Now that you have a Survival Budget, a realistic Baseline Income, prioritized your expenses, and built an Income Buffer, it’s time to give every dollar a specific purpose.
This is where the Zero-Based Budgeting Method becomes one of the most effective budgeting strategies for people with irregular income.
Despite its name, Zero-Based Budgeting does not mean your bank account should reach zero. It simply means every dollar you earn is assigned a job before you spend it.
Instead of wondering where your money went at the end of the month, you decide in advance where every dollar will go. This gives you complete control over your finances and reduces unnecessary spending.
Why Zero-Based Budgeting Works for Irregular Income
When your income changes every month, spending money without a plan can quickly create financial problems.
Zero-Based Budgeting helps you:
Give every dollar a clear purpose.
Avoid impulse spending.
Control lifestyle inflation.
Save consistently during high-income months.
Stay organized even when your income fluctuates.
Unlike traditional budgeting, this method is flexible. Each month, you create a new budget based on the income you actually expect to receive instead of using the same budget every month.
It means every dollar has already been assigned to a category before you begin spending.
For example:
Monthly Baseline Income: $3,200
Housing: $900
Groceries: $350
Utilities: $180
Transportation: $170
Insurance: $120
Debt Payments: $200
Emergency Savings: $300
Investments: $400
Personal Spending: $280
Miscellaneous: $300
Money Remaining = $0
Every dollar now has a purpose.
How to Apply Zero-Based Budgeting
1. Start With Your Baseline Income
Never create your budget using your highest earning month.
Instead, use the Baseline Income you calculated in Step 2.
This makes your budget realistic and easier to follow.
2. Fund Essential Expenses First
Your first responsibility is covering your Survival Budget.
Always fund:
Housing
Food
Utilities
Transportation
Insurance
Minimum debt payments
Only after these expenses are covered should you move to savings, investing, and lifestyle spending.
3. Give Every Remaining Dollar a Job
Extra income should never remain “unplanned.”
Assign every remaining dollar to one of these categories:
Income Buffer
Emergency Fund
Investments
Debt repayment
Business growth
Personal goals
A clear plan prevents unnecessary spending and keeps your financial priorities on track.
Real-Life Example
Sarah is a freelance graphic designer.
Her Baseline Income is $2,800 per month.
Instead of spending money as clients pay her, she creates a Zero-Based Budget before the month begins.
She first funds her essential expenses, then adds money to her Income Buffer, contributes to her investments, and finally sets aside a small amount for entertainment.
When unexpected expenses arise, she already knows where her money is allocated, so she avoids using credit cards unnecessarily.
Common Mistakes to Avoid
Avoid these common mistakes:
Creating a budget after spending your money.
Forgetting to budget for savings.
Leaving extra income without a purpose.
Budgeting based on your highest-income month.
Not reviewing your budget when your income changes.
Next Step: Now that every dollar has a purpose, the next step is learning how to manage separate bank accounts for spending, savings, and taxes, making your irregular income even easier to control.
Step 6: Create Separate Accounts for Spending, Savings, and Taxes
One of the smartest habits of people who successfully manage irregular income is keeping their money organized. Instead of using one bank account for everything, they divide their money into separate accounts with a specific purpose.
When all of your income stays in one account, it’s easy to lose track of how much money is actually available to spend. You may accidentally use money meant for taxes, emergency savings, or future bills.
Creating separate accounts gives every part of your money a clear destination. This simple system reduces financial mistakes, improves cash flow, and makes budgeting much easier.
Why Separate Bank Accounts Matter
People with fixed salaries usually know exactly when and how much money they will receive. However, freelancers, self-employed professionals, creators, consultants, and small business owners often receive payments at different times and in different amounts.
Without a clear system, all your income mixes together, making it difficult to know:
How much you can safely spend.
How much should be saved.
How much belongs to future taxes.
How much is available for investing.
Separating your money creates financial discipline and reduces the temptation to spend savings on everyday purchases.
According to the Consumer Financial Protection Bureau (CFPB), organizing your finances and planning ahead can make budgeting easier and help you stay on track with your financial goals.
The 4-Account Money Management System
You don’t need dozens of accounts. For most people with irregular income, four accounts are enough.
1. Spending Account
This is your everyday account.
Use it only for:
Rent
Groceries
Utilities
Transportation
Healthcare
Daily living expenses
Transfer only your planned monthly spending amount into this account.
Once the money is used, avoid moving extra money from your savings unless it’s absolutely necessary.
2. Emergency Savings Account
This account is for unexpected situations, not everyday spending.
Examples include:
Medical emergencies
Emergency home repairs
Temporary income loss
Unexpected travel
Keep this money separate so you’re less likely to spend it impulsively.
3. Tax Account
If you’re self-employed, a freelancer, or a business owner, taxes should never be treated as spending money.
Every time you receive a payment, move a percentage into a dedicated tax account.
This simple habit prevents financial stress when tax payments become due.
Next Step: Once your money is organized into separate accounts, the next step is learning how to save more during high-income months so you can stay financially secure when income slows down.
Step 7: Save Extra Income During High-Earning Months
One of the biggest advantages of having an irregular income is that some months can bring significantly higher earnings than others. However, this advantage can quickly become a financial problem if you spend the extra money instead of preparing for future slow months.
Many freelancers, business owners, creators, and self-employed professionals celebrate a high-income month by upgrading their lifestyle. They buy expensive gadgets, eat out more often, or increase their monthly spending. When the next month brings lower income, they struggle to pay even their essential bills.
A smarter strategy is to treat every high-income month as an opportunity to strengthen your financial future—not your lifestyle.
Why Saving Extra Income Is So Important
Irregular income is unpredictable by nature. You cannot always control when clients pay you, how much business you’ll receive, or whether demand will slow down.
What you can control is what you do with the extra money you earn during good months.
Saving part of your extra income helps you:
Prepare for low-income months.
Reduce financial stress.
Avoid unnecessary debt.
Build long-term financial security.
Reach your financial goals faster.
According to the Consumer Financial Protection Bureau (CFPB), consistently setting aside money improves financial resilience and helps people handle unexpected financial challenges.
Follow the “Save First, Spend Later” Rule
Many people save whatever money is left at the end of the month.
Successful money management works the opposite way.
As soon as you receive a larger-than-normal payment:
Cover your essential expenses.
Add money to your Income Buffer.
Increase your emergency savings.
Invest toward your long-term goals.
Spend only the remaining amount.
This approach ensures that your future is funded before your lifestyle.
How Much Should You Save?
There isn’t one percentage that works for everyone, but having a target makes saving easier.
For example:
Save 20–30% of extra income if you’re still building an Income Buffer.
Save 30–50% if your emergency savings are not yet complete.
Invest a portion after your essential savings goals are covered.
The exact percentage depends on your financial situation, but consistency matters more than perfection.
Real-Life Example
Imagine Alex owns a small online business.
His average monthly income is $3,000, but during a holiday season he earns $5,500.
Instead of increasing his spending, Alex follows a simple plan:
Pays all essential expenses.
Adds money to his Income Buffer.
Increases his emergency savings.
Invests part of the remaining income.
Keeps a small amount for personal enjoyment.
A few months later, when sales slow down, he continues paying his bills without financial stress because he planned ahead.
Common Mistakes to Avoid
Avoid these common mistakes during high-income months:
Assuming every month will be equally profitable.
Increasing your lifestyle too quickly.
Spending bonuses immediately.
Ignoring future slow seasons.
Saving only when it’s convenient.
Small, consistent decisions during good months often determine your financial stability during difficult months.
Action Plan
Complete these steps whenever you earn more than usual:
✅ Cover your Survival Budget first.
✅ Add money to your Income Buffer.
✅ Increase your emergency savings.
✅ Invest toward your long-term goals.
✅ Spend only what remains after your priorities are funded.
For additional guidance on building healthy saving habits, you can also explore: MyMoney.gov – Save Money.
Next Step: Now that you’ve learned how to use high-income months wisely, the next step is to track your income and expenses regularly so you can identify spending patterns and improve your budget over time.
Step 8: Track Your Income and Expenses Every Week
Creating a budget is only the beginning. The real difference comes from tracking your income and expenses consistently.
For people with irregular income, waiting until the end of the month to review finances is often too late. By then, you may have already overspent or missed opportunities to save.
A simple weekly money review helps you stay in control of your cash flow, spot spending problems early, and make better financial decisions before small mistakes become expensive ones.
Instead of asking, “Where did all my money go?”, you’ll know exactly where every dollar was earned and spent.
Why Weekly Tracking Is Better Than Monthly Tracking
When your income changes every month, your financial situation can change quickly.
You might receive several client payments in one week and nothing in the next. If you only check your finances once a month, it’s easy to lose control of your spending.
A weekly review helps you:
Monitor your cash flow.
Stay within your budget.
Identify unnecessary expenses.
Track progress toward your savings goals.
Adjust your budget before problems grow.
According to the Consumer Financial Protection Bureau (CFPB), regularly reviewing your income and expenses helps you make informed financial decisions and stay on track with your budget.
What Should You Track Every Week?
You don’t need complicated software. A simple spreadsheet, budgeting app, or notebook is enough.
Focus on these four areas:
1. Income Received
Record every payment you receive, including:
Freelance payments
Business income
Salary
Side hustle earnings
Commissions
Passive income
Tracking income helps you compare your actual earnings with your expected Baseline Income.
2. Essential Expenses
Review all necessary spending, such as:
Rent
Groceries
Utilities
Transportation
Insurance
Healthcare
This ensures your Survival Budget stays under control.
3. Non-Essential Spending
Track optional expenses like:
Dining out
Shopping
Entertainment
Subscriptions
Online purchases
Small purchases may seem harmless individually, but together they can significantly reduce your savings.
4. Savings and Investments
Every week, ask yourself:
Did I add money to my Income Buffer?
Did I contribute to my emergency savings?
Did I invest toward my long-term goals?
Tracking progress keeps your financial goals visible and motivates you to stay consistent.
Create a Simple Weekly Money Review
Choose one day each week—such as Sunday evening—and spend 15 to 20 minutes reviewing your finances.
Ask yourself these questions:
How much money did I earn this week?
Where did I spend the most?
Were all my expenses necessary?
Did I follow my budget?
What should I improve next week?
A short review every week is much easier than trying to fix an entire month’s financial mistakes.
Real-Life Example
Sophia is a freelance writer whose income changes every month.
Before tracking her finances weekly, she often forgot about small subscriptions and online purchases.
After creating a 20-minute weekly review, she discovered she was spending over $150 every month on services she rarely used.
By canceling unnecessary subscriptions, she redirected that money into her Income Buffer and emergency savings.
Common Mistakes to Avoid
Avoid these common mistakes:
Reviewing finances only at the end of the month.
Ignoring small daily expenses.
Forgetting to record cash payments.
Tracking expenses but never reviewing them.
Giving up after missing one week.
Remember, consistency is more valuable than perfection.
Action Plan
Complete these steps every week:
✅ Record every source of income.
✅ Review essential and non-essential expenses.
✅ Compare your spending with your budget.
✅ Update your savings and investment progress.
✅ Make one small improvement for the following week.
Next Step: After tracking your finances consistently, the final step is to review and adjust your budget every month so it continues to work as your income and financial goals change.
Step 9: Review and Adjust Your Budget Every Month
A budget is not something you create once and forget. It should evolve as your income, expenses, and financial goals change. This is especially important if you have an irregular income, where no two months are exactly the same.
A monthly budget review helps you identify what worked, what didn’t, and what needs to change. Instead of repeating the same financial mistakes, you improve your budgeting system every month.
Think of your budget as a living financial plan—not a fixed document.
Why You Should Review Your Budget Every Month
Even if you followed your budget perfectly this month, your financial situation may be different next month.
For example:
You may earn more or less than expected.
Your rent or utility bills may increase.
You may have unexpected medical expenses.
You may reach a savings goal and set a new one.
Reviewing your budget regularly allows you to adapt instead of reacting.
According to the Consumer Financial Protection Bureau (CFPB), reviewing your spending plan regularly helps you make better financial decisions and stay aligned with your goals.
How to Review Your Budget
1. Compare Your Planned Budget With Actual Spending
Start by comparing what you planned to spend with what you actually spent.
Ask yourself:
Which categories stayed within budget?
Which categories exceeded the budget?
Why did those differences happen?
The goal is not perfection—it is learning from your spending habits.
2. Review Your Income
Compare your actual monthly income with your Baseline Income.
If you earned more than expected:
Increase your Income Buffer.
Save or invest the extra money.
If you earned less than expected:
Reduce non-essential spending.
Use your Income Buffer if necessary.
Avoid unnecessary debt.
3. Update Your Financial Goals
Your goals will change over time.
For example, after completing your emergency fund, you may decide to focus on:
Investing.
Paying off debt.
Saving for a home.
Growing your business.
Learning new skills.
Your budget should always support your current priorities.
Questions to Ask Every Month
At the end of each month, answer these questions honestly:
Did I follow my budget?
Which expenses were unnecessary?
Did I save enough?
Did I invest consistently?
What financial habit should I improve next month?
These simple questions help you improve your budgeting system month after month.
Real-Life Example
Michael is a self-employed photographer.
At the end of every month, he spends 30 minutes reviewing his finances.
One month, he notices that transportation costs are much higher than expected because of extra client visits.
Instead of ignoring the problem, he increases that category in next month’s budget while reducing entertainment expenses.
This small adjustment keeps his overall budget balanced without affecting his savings goals.
Common Mistakes to Avoid
Avoid these common mistakes:
Never reviewing your budget.
Ignoring overspending.
Making unrealistic budget changes.
Forgetting to adjust for income changes.
Giving up after one difficult month.
Remember, a budget should improve over time. Small monthly adjustments often produce better long-term results than making major changes once a year.
Action Plan
At the end of every month:
✅ Compare planned spending with actual spending.
✅ Review your monthly income.
✅ Identify unnecessary expenses.
✅ Update your savings and investment goals.
✅ Adjust next month’s budget based on what you learned.
Next Step: After building a budgeting system that adapts to changing income, the final step is to focus on long-term financial stability through emergency savings, investing, and continuous financial planning.
Step 10: Build Long-Term Financial Stability
Creating a budget for irregular income is not just about paying this month’s bills—it’s about building a financial system that continues to support you for years to come. Once you’ve learned how to calculate your Survival Budget, estimate your Baseline Income, prioritize expenses, build an Income Buffer, and track your spending, the final step is turning these habits into long-term financial stability.
Financial stability doesn’t mean earning a huge income. It means having enough control over your money that unexpected events don’t completely disrupt your life. Whether you earn $2,000 or $10,000 a month, consistent financial habits will always matter more than occasional high-income months.
Why Long-Term Financial Planning Matters
People with irregular income often focus only on the next payment. While this is understandable, constantly thinking short-term makes it difficult to build wealth.
A long-term financial plan helps you:
Stay financially secure during income fluctuations.
Reduce money-related stress.
Build wealth gradually.
Achieve important life goals.
Become financially independent over time.
According to the Investor.gov, investing consistently over time is one of the most effective ways to build long-term wealth.
Build Your Long-Term Financial System
Instead of relying only on budgeting, combine budgeting with saving, investing, and goal planning.
1. Maintain Your Emergency Fund
Your emergency fund is your first line of financial protection.
Aim to keep enough money to cover at least three to six months of essential living expenses.
Use this money only for genuine emergencies, such as:
Medical expenses
Temporary income loss
Major home or vehicle repairs
Unexpected family emergencies
Continue rebuilding the fund whenever you need to use it.
2. Invest Consistently
Once your emergency savings are in place, start investing regularly.
You don’t need to invest a large amount.
The most important habit is consistency.
Depending on your financial goals, you may choose investments such as:
Index funds
Mutual funds
Retirement accounts
Other diversified long-term investments
If you’re new to investing, begin with research and invest according to your risk tolerance and financial objectives.
3. Continue Learning About Personal Finance
Financial success is a continuous learning process.
Make time to improve your knowledge about:
Budgeting
Saving
Investing
Taxes
Debt management
Retirement planning
The more you understand money, the better financial decisions you’ll make throughout your life.
4. Review Your Financial Goals Every Year
Your priorities will change over time.
Once a year, review your goals and ask yourself:
Have my financial priorities changed?
Am I saving enough?
Am I investing consistently?
Do I need to increase my Income Buffer?
What is my next financial milestone?
Regular reviews help ensure your money continues working toward your future goals.
Real-Life Example
Emma is a self-employed photographer whose income changes throughout the year.
A few years ago, she lived from one payment to the next.
Today, she follows a complete financial system.
She maintains an emergency fund, invests a portion of every profitable month, reviews her budget monthly, and adjusts her financial goals every year.
Although her income is still irregular, her financial life is far more stable because her habits—not her income—create consistency.
Common Mistakes to Avoid
Avoid these long-term financial mistakes:
Stopping your budget after reaching one savings goal.
Ignoring investing.
Depending entirely on one source of income.
Never reviewing your financial goals.
Assuming high income automatically leads to wealth.
Financial stability is built through consistent decisions, not occasional success.
Action Plan
Complete these long-term financial habits:
✅ Maintain an emergency fund covering 3–6 months of essential expenses.
✅ Invest consistently, even if you start with a small amount.
✅ Continue improving your financial knowledge.
✅ Review your financial goals every year.
✅ Keep updating your budgeting system as your income and lifestyle change.
For trusted financial education and long-term investing guidance, you can explore: Investor.gov and MyMoney.gov.
Final Thoughts
Budgeting with irregular income may seem challenging at first, but it becomes much easier when you follow a proven system. By calculating your Survival Budget, estimating your Baseline Income, prioritizing essential expenses, building an Income Buffer, using Zero-Based Budgeting, organizing your accounts, saving during high-income months, tracking your finances, and reviewing your budget regularly, you can take control of your money with confidence.
Remember, financial success isn’t determined by earning the same income every month—it’s determined by how consistently you manage the income you have. Start with one step today, stay disciplined, and improve your system over time. Small actions repeated consistently can lead to lasting financial freedom.
What is the best budgeting method for irregular income
What is the best budgeting method for irregular income? The best budgeting method for irregular income is to combine a Survival Budget, Baseline Income, Income Buffer, and Zero-Based Budgeting. This system helps you cover essential expenses first, save during high-income months, and stay financially stable even when your income changes. FAQ 2 How much emergency savings should I have if my income is irregular? A good goal is to save at least three to six months of essential living expenses. If you're just starting, aim to build one month of expenses first and gradually increase your emergency fund over time. FAQ 3 Should I budget based on my highest-income month? No. Budgeting based on your highest-income month can lead to overspending during slower months. Instead, calculate your Baseline Income using your average earnings from the last 6–12 months and build your budget around that amount. FAQ 4 How often should I review my budget if I have irregular income? Review your budget every week to track income and expenses, and complete a full budget review at the end of each month. Regular reviews help you adjust your spending, improve savings, and stay on track with your financial goals. Key Takeaway 1 Know your Survival Budget before making any spending decisions. Key Takeaway 2 Save extra income during high-earning months instead of increasing your lifestyle. Key Takeaway 3 Track your income and expenses consistently because what gets measured gets managed. Key Takeaway 4 Review and improve your budget every month to keep it aligned with your changing income and financial goals.
Conclusion
Budgeting with irregular income may seem difficult at first, but it becomes much easier when you follow a proven system instead of relying on guesswork. The goal isn’t to predict exactly how much you’ll earn every month—it’s to build a financial plan that works whether your income is high or low.
By calculating your Survival Budget, estimating your Baseline Income, prioritizing essential expenses, building an Income Buffer, using Zero-Based Budgeting, organizing separate accounts, saving more during high-income months, tracking your finances weekly, and reviewing your budget regularly, you can create a stable financial system that grows with you.
Remember, financial success doesn’t depend on having a fixed salary. It depends on making consistent, smart decisions with the money you earn. Even small improvements, repeated every month, can lead to greater financial security, less stress, and long-term wealth.
Start with the first step today. You don’t need a perfect budget—you just need a system that you can follow consistently. Over time, those small habits will help you take full control of your finances, no matter how unpredictable your income may be.
Article Summary If your income changes every month, creating a traditional budget may not work. Instead, you need a flexible budgeting system designed specifically for irregular income. In this guide, you learned how to calculate your Survival Budget, estimate your Baseline Income, prioritize essential expenses, build an Income Buffer, use the Zero-Based Budgeting Method, organize separate bank accounts, save more during high-income months, track your finances every week, review your budget every month, and build long-term financial stability. By following these 10 practical steps, you can reduce financial stress, avoid overspending, prepare for low-income months, and make smarter financial decisions. The key is not earning the same amount every month—it’s creating a money management system that adapts to changing income while helping you save, invest, and achieve your long-term financial goals. Whether you’re a freelancer, self-employed professional, small business owner, content creator, or anyone with variable income, this budgeting method can help you stay in control of your money and build lasting financial confidence.
Hi, I’m Asif Khan, the voice behind paisakmao.de. For the past two years, I’ve been blogging about financial education, income skills, and mindset development for students and young minds. My mission is to empower every youth with financial literacy and practical money-making skills at an early age. Through paisakmao.de, I share actionable guides for students to start earning early, money wisdom that schools don’t teach, and mindset lessons from successful people and modern psychology. Whether you’re a teenager looking to earn your first income or a student exploring side hustles, you’re in the right place. Financial freedom begins with the right mindset and the right knowledge. Let’s grow, earn, and evolve together — welcome to the movement!