Learning the essential principles of living paycheck to paycheck is critical for anyone looking to build healthy money habits, avoid debt traps, and make smart financial decisions in India.
Learning the essential principles of living paycheck to paycheck is critical for anyone looking to build healthy money habits, avoid debt traps, and make smart financial decisions in India.
Learning the essential principles of living paycheck to paycheck is critical for anyone looking to build healthy money habits, avoid debt traps, and make smart financial decisions in India.
Learning the essential principles of living paycheck to paycheck is critical for anyone looking to build healthy money habits, avoid debt traps, and make smart financial decisions in India.
If your paycheck runs out before your next payday, budgeting can feel almost impossible—especially when your income is already low. The problem may not be unnecessary spending; your essential expenses may simply leave too little room.This guide explains how to budget when living paycheck to paycheck on a low income, find where your money is actually going, and create a practical plan to make each paycheck last longer.
Additionally, table of Contents
Practical Steps & Actionable Tips for living paycheck to paycheck
Additionally, for verified statutory guidelines and official consumer protections, refer to the Reserve Bank of India (RBI).
Find Out Why Your Paycheck Runs Out Before Payday: Complete Guide to living paycheck to paycheck
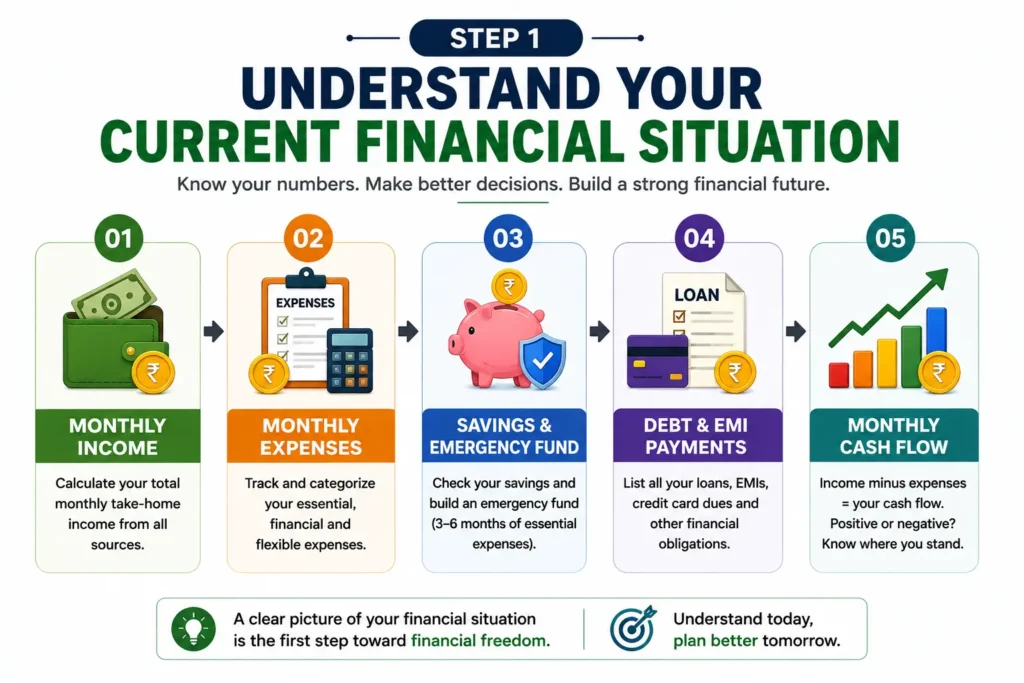
Before changing your budget, first find out why your money is running out. If you don’t know where the shortage is coming from, cutting random expenses may not solve the problem.
Furthermore, for example, start with your take-home income for one pay period. Then list the expenses that you must pay before your next paycheck, such as housing, food, transportation, utilities, and required payments.
Essential Overview: Guide to living paycheck to paycheck
Specifically, for example, if you receive ₹10,000 and need ₹4,000 for housing, ₹2,000 for food, ₹1,000 for transportation, and ₹1,500 for essential bills, you have ₹1,500 left.
Consequently, now ask yourself: Can that ₹1,500 realistically cover everything until your next payday?
If yes, the problem may be how the remaining money you spend or when certain expenses occur. If no, your essential costs may already be leaving too little income available.
Additionally, for example, the same calculation works whether your paycheck is ₹10,000, $1,000, or £900. The amounts will differ, but the question stays the same: how much income is left after the expenses you cannot avoid?
However, this simple check helps you identify whether your main problem is spending, payment timing, or an income that is not enough to cover essential costs. Furthermore, once you know the actual problem, you can build a budget around it instead of guessing where your money is going.
Calculate Your Minimum Amount Needed Until the Next Paycheck: Complete Guide to living paycheck to paycheck
Consequently, once you know why your paycheck is disappearing, calculate the minimum amount you actually need before the next payday. This gives you a clear spending limit instead of treating your whole paycheck as available money.
FREE INTERACTIVE TOOL
Calculate Your 3-Month Survival Buffer
In fact, break the paycheck cycle. Specifically, find the exact bare-minimum emergency cushion needed to protect you against sudden expenses.
In addition, start with the expenses that you cannot postpone until later. For example, if your next paycheck is 10 days away, include the food, transportation, bills, and other essential payments you need during those 10 days.
Moreover, suppose you receive ₹10,000 and your next paycheck is 10 days away:
First, first, first, first, for example, essential food: ₹2,000
Next, next, next, next, transportation: ₹1,000
Consequently, upcoming bill: ₹2,500
Then, other required expense: ₹1,000
However, your minimum amount needed is ₹6,500.
Therefore, notably, that means the remaining ₹3,500 do not treat as spending money. It can become a buffer, cover an upcoming expense, or help reduce the pressure on your next paycheck.
In fact, the same method works with $1,000 or £900. The numbers will change depending on your location and expenses, but the principle remains the same: separate money you must use from money you can safely leave untouched.
Additionally, this small calculation can change the way you look at each paycheck. Instead of asking, “How much money do Always have?” you start asking, “How much of this money is actually available?”
Build a Paycheck Plan Around Your Essential Expenses: Complete Guide to living paycheck to paycheck
When you are living paycheck to paycheck, a budget should do more than divide your income into categories. It should help you control the timing of your money so that an expense due next week does not compete with today’s spending.
Particularly, after calculating what you need until your next paycheck, give each important amount a specific job. This creates a simple cash-flow plan without forcing every household into the same percentage-based budget.
Reserve Money for Bills Before They Are Due: Complete Guide to living paycheck to paycheck
Moreover, for example, start with bills that you will need to pay before your next paycheck arrives. These might include rent, utilities, phone bills, transportation payments, or other unavoidable commitments.
Overall, for example, suppose you receive ₹10,000 today and ₹3,500 of bills are due before your next payday. That ₹3,500 you should treat as committed money even though it is still sitting in your account.
Consequently, the same idea applies to a $1,000 or £900 paycheck. The currency changes, but the problem is the same: money can look available simply because the bill has not arrived yet.
Turn the Remaining Days Into a Spending Limit: Complete Guide to living paycheck to paycheck
Furthermore, notably, once you protect upcoming bills, calculate what you need for essential day-to-day spending until payday.
However, imagine you have 10 days remaining and expect to spend about ₹200 per day on necessary food and transportation:
₹200 × 10 days = ₹2,000
Instead of treating your whole account balance as spendable, ₹2,000 becomes the working amount for those essentials.
Specifically, as a result, you can use the same calculation with dollars or pounds. For example, if your essential daily spending is $12 and you have 8 days until payday, your basic requirement would be $96.
In fact, this creates a useful distinction: your account balance shows what you have, while your spending limit shows what you can safely use.
Leave Room for Small Unplanned Expenses: Complete Guide to living paycheck to paycheck
A budget that leaves no flexibility can be difficult to follow. A small unexpected expense can force you to take money from a bill or another essential category.
Additionally, after covering your required expenses, keep a modest flexible amount that fits your situation.
₹500 for a ₹10,000 example paycheck
$30 for a $1,000 example paycheck
£25 for a £900 example paycheck
Moreover, these numbers are examples, not recommended percentages. Furthermore, your flexible amount should depend on your actual income and expenses.
Furthermore, the important rule is simple: once this amount is used, do not automatically increase it by taking money reserved for essential expenses.
Give the Remaining Money a Specific Job: Complete Guide to living paycheck to paycheck
Specifically, notably, after protecting bills, essential daily spending, and a small flexible amount, look at what remains. Do not automatically label it as “extra money.” Decide what that money is supposed to do.
₹10,000 Paycheck
Amount
Purpose
Upcoming bills
₹3,500
Protect until due date
Food + transportation
₹2,000
10-day essentials
Flexible spending
₹500
Small unexpected needs
Remaining amount
₹4,000
Protect for the next financial need
Additionally, for example, for example, the ₹4,000 remaining in this example should not automatically become shopping or entertainment money. It could help cover an upcoming expense, provide breathing room for the next pay period, or be directed toward another priority once your immediate needs are secure.
Additionally, this is similar to the basic idea behind MoneyHelper’s jam-jar budgeting approach, where money is separated into different pots for different purposes so that spending money is less likely to interfere with money reserved for bills.
Actionable Advice and Practical Tips for living paycheck to paycheck
When Money Is Unassigned
When Money Has a Job
The full balance feels available
Only the appropriate amount feels available
Upcoming bills are easy to forget
Upcoming bills are protected
Daily spending can consume future money
Daily spending has a defined limit
Payday feels like a reset
Each paycheck is planned around the next one
If you want to understand broader salary allocation, you can also read your existing guide to dividing your salary. That article covers percentage-based allocation and salary budgeting; this section focuses specifically on protecting cash between paychecks, so the two articles serve different purposes.
Consequently, the goal is not to make every paycheck fit a perfect formula. It is to make sure money needed for the next few days and weeks is protected before you decide what you can actually spend.
Create a Survival Budget for the Lowest-Income Weeks: Complete Guide to living paycheck to paycheck
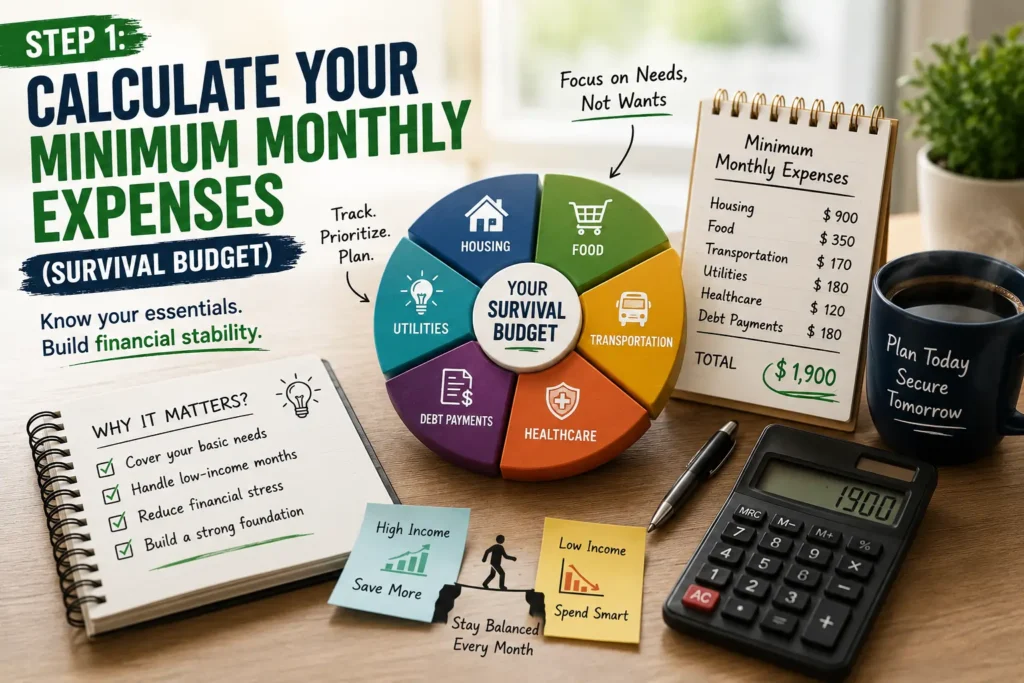
When you live paycheck to paycheck, your budget cannot depend on every paycheck being the same. A week with fewer working hours, lower overtime, or an unexpected expense can leave you with much less money than usual.
Instead of rebuilding your entire budget whenever income falls, create a survival budget based on the minimum amount you need to keep your essential expenses covered.
Find Your Bare-Minimum Monthly Cost: Complete Guide to living paycheck to paycheck
In addition, for example, start by identifying the expenses you cannot reasonably stop or postpone when your income is lower.
However, housing and essential household costs
Additionally, basic food
Furthermore, in fact, necessary transportation
Finally, essential utilities and communication
Moreover, required debt or other unavoidable payments
However, for example, if your normal monthly income is ₹20,000 but your essential expenses are ₹13,000, then ₹13,000 is much more important for your survival budget than your usual spending level.
A person earning $2,500 or £2,000 would use the same method: first identify the minimum cost of keeping essential needs covered, rather than copying someone else’s budget percentages.
Separate Fixed Costs From Expenses You Can Adjust: Complete Guide to living paycheck to paycheck
Consequently, not every expense has the same level of flexibility. When income falls, knowing which costs can actually be reduced is more useful than simply cutting everything by the same percentage.
Type of Expense
Usually Harder to Change Quickly
Often More Flexible
Housing
Rent or essential housing payment
Some optional housing-related spending
Food
Basic groceries
Takeaways and non-essential purchases
Transportation
Necessary travel to work
Optional trips
Subscriptions
Essential communication services
Entertainment subscriptions
Therefore, this gives you a priority order. You are not trying to make every category smaller. You are protecting the expenses that keep your household functioning and adjusting the areas where you have genuine control.
What to Cut First When Your Paycheck Is Smaller: Complete Guide to living paycheck to paycheck
When a paycheck comes in lower than expected, make the adjustment based on priority rather than emotion.
However, for example, suppose your usual income is ₹20,000 but this month you receive only ₹15,000. If essential expenses remain around ₹12,000, you have only ₹3,000 available for everything else.
Monthly Situation
Income
Essential Costs
Amount Left
Normal month
₹20,000
₹12,000
₹8,000
Lower-income month
₹15,000
₹12,000
₹3,000
In fact, the lesson is not to spend the extra ₹8,000 simply because it was available in the normal month. Consequently, your flexible spending has to respond when your income changes.
In fact, the same principle applies if income falls from $2,500 to $2,000 or from £2,000 to £1,600. The actual figures differ by country and household, but the budgeting decision is the same: protect essential costs first, then reduce flexible spending.
What to Do When the Budget Still Doesn’t Balance
Particularly, sometimes cutting flexible spending is not enough. If your essential expenses are already higher than your income, the problem is no longer simply about better budgeting.
At that point, look at the gap itself.
Specifically, check whether any payment can be moved to a more suitable date.
Then, first, notably, look for temporary reductions in non-essential commitments.
Additionally, next, review recurring expenses that are no longer necessary.
Additionally, consider realistic ways to increase income if the shortfall continues.
Then, contact the relevant provider early if you are struggling with an important payment rather than waiting until it becomes overdue.
Moreover, do not treat every low-income month as a failure. A temporary income drop requires a different spending plan. If the gap continues for several months, however, it is a signal that the underlying income-versus-expense problem needs to be addresse provide practical information for managing income and expenses. UK readers can also use MoneyHelper’s budgeting guidance for country-specific budgeting information.
If you already have a broader article about dividing your salary, use it as a supporting internal link for the normal-income budgeting side. This section has a different purpose: it explains how to adapt when your income falls below normal.
A survival budget is not meant to be your permanent lifestyle. It is a practical fallback system that helps you protect essential expenses during a low-income period without pretending that every month will look the same.
Build a Small Buffer Between Your Paychecks
When you are living paycheck to paycheck, even a small unexpected expense can create a problem because most of your income is already committed before the next payday arrives.
Moreover, the solution is not to suddenly save a large amount. A more realistic approach is to create a small buffer between paychecks and increase it gradually as your cash flow improves.
Why Every Paycheck you should not fully spend
If your entire paycheck is allocated before the next one arrives, there is no room for a small surprise expense. A transport problem, higher grocery bill, or unexpected household purchase can force you to reduce something else or depend on borrowing.
Overall, notably, for example, if you receive ₹20,000 and normally spend almost all of it before the next payday, try leaving a small amount untouched instead of treating the full balance as available spending money.
Consequently, notably, the same idea applies to someone earning $2,000 or £1,600. The amount of the buffer will depend on local costs and income, but the purpose is the same: create a little space between what you earn and what you immediately spend.
Start With a Buffer You Can Actually Keep
Additionally, your first target does not need to be a large emergency fund. If money is already tight, setting an unrealistic target can make the system impossible to maintain.
In addition, as a result, start with an amount that would make one small unexpected expense easier to handle.
Stage
Illustrative Buffer
Main Purpose
Starting point
₹300 / $5 / £5
Creates the first small cushion
Small cushion
₹1,000 / $25 / £20
Handles minor unexpected costs
Several days of essentials
Based on your actual costs
Provides more breathing room
Larger buffer
Based on your income and expenses
Reduces pressure between paychecks
Additionally, for example, these are illustrative examples, not recommended savings targets for every country or household. In addition, your starting point should match what you can realistically leave untouched.
Turn Leftover Money Into Next-Paycheck Protection
Furthermore, one useful habit is to stop treating every leftover amount as permission to spend more.
Consequently, suppose you planned to spend ₹2,000 during a week but actually spent ₹1,750. Instead of automatically using the remaining ₹250, you can leave it available for the next pay period.
Specifically, over time, several small amounts can create a useful cushion without requiring one large contribution from a low income.
If you want a separate collection of practical saving strategies, you can read how to save money fast in 30 days. That article covers broader saving techniques; this section is specifically about creating protection between paychecks.
How a Buffer Changes Your Next Paycheck
Situation
Without a Buffer
With a Small Buffer
Small unexpected expense
May reduce money available for essentials
you can cover from the cushion
Lower-than-usual paycheck
Immediate pressure on spending
Previous buffer provides some breathing room
Money left at the end of the week
May be spent automatically
Can remain available for the next period
Next payday
Starts with little or no flexibility
Starts with some money already protected
However, the goal is not to make your bank balance look bigger. The goal is to make your next payday less fragile.
Increase the Buffer Gradually
However, for example, once your first small cushion becomes easy to maintain, increase it only when your budget can support the change.
Additionally, for example, keep the first small amount untouched.
Furthermore, add a little more when you genuinely have money left over.
Consequently, use part of the buffer only for situations that actually need it.
Finally, rebuild the buffer after using it.
However, increase the target when your income becomes more stable.
In fact, this creates a simple cycle:
Paycheck → essential spending → controlled flexible spending → small amount protected → next paycheck starts with a cushion.
If you are still struggling to keep any money aside despite earning a reasonable income, the problem may be different from simply needing a larger buffer. In that situation, why you can’t save money despite earning a good salary is a more relevant supporting guide.
When a Buffer Is Not Enough
A small buffer can help with timing problems and minor unexpected expenses, but it cannot solve a permanent gap between income and essential costs.
If your essential expenses are consistently higher than your reliable income, calculate the shortfall instead of simply trying to save more.
Essential expenses − reliable income = monthly shortfall
Consequently, for example, if essential expenses are ₹16,000 and reliable income is ₹14,000, there is a ₹2,000 monthly gap. A buffer can temporarily reduce pressure, but the underlying gap still needs to be addressed.
Moreover, for broader personal-finance fundamentals, you can also use this beginner’s personal finance guide to review the wider system without repeating those topics here.
A buffer is not about becoming wealthy overnight. It is about creating a small gap between your income and your immediate spending so that one minor problem does not automatically become a next-paycheck problem.
Start small, protect the amount, rebuild it when you use it, and increase it only when your actual budget allows.
Handle a Shortfall Before It Becomes a Bigger Problem
However, notably, sometimes a low-income budget does not fail because of unnecessary spending. The real problem can be that your essential expenses are already close to, or higher than, your reliable income.
When that happens, the first step is not to cut random expenses. Specifically, find the exact size of the gap and determine whether it is temporary or happening repeatedly.
Calculate Your Exact Monthly Shortfall
Therefore, start with your reliable take-home income and subtract only the expenses you genuinely need to keep covered.
Reliable income − essential expenses = money available for everything else
Additionally, for example, if your reliable income is ₹15,000 and essential expenses are ₹13,500, you have ₹1,500 available for flexible spending and other priorities.
But if essential expenses are ₹16,000, you already have a ₹1,000 shortfall before discretionary spending begins.
Situation
Income
Essential Expenses
Result
Expenses fit income
₹15,000
₹13,500
₹1,500 remaining
Small shortfall
₹15,000
₹16,000
₹1,000 gap
Larger shortfall
₹15,000
₹18,000
₹3,000 gap
In fact, the same calculation works for other currencies. Therefore, someone earning $2,000 with $2,200 of essential expenses has a $200 gap. In fact, someone earning £1,600 with £1,750 of essential expenses has a £150 gap.
Separate a Temporary Gap From a Recurring Problem
Particularly, for example, not every shortfall requires the same response.
Temporary Shortfall
Recurring Shortfall
Income was unusually low for one period
Income is regularly below essential costs
An unusual expense caused the problem
Basic monthly costs are structurally too high
Normal income may solve it next payday
The underlying income-expense gap needs attention
Small adjustments may be enough
Both expenses and income may need to change
Moreover, this distinction matters because repeatedly using a credit card, borrowing money, or taking from your next paycheck can hide a recurring shortfall instead of solving it.
Decide What you can delay or reduce
If the gap is temporary, review your expenses according to priority rather than cutting everything equally.
Reduce: flexible food spending, entertainment, shopping, and other non-essential categories.
Delay: purchases or goals that are useful but not urgent.
Review: recurring subscriptions and commitments that may no longer provide enough value.
Consequently, the purpose is to create enough breathing room to get through the weaker income period without sacrificing expenses that keep your basic needs covered.
If the issue is connected to inconsistent income rather than a single low paycheck, your guide on budgeting with an irregular income is the more relevant supporting resource. It covers a different situation, so this section does not need to repeat that system.
When Cutting Expenses Is No Longer Enough
Overall, there is a point where reducing discretionary spending cannot solve the problem. If your essential expenses are already higher than your reliable income, the budget needs to address the gap itself.
However, for example, if your essential expenses are ₹18,000 and your reliable income is ₹15,000, cutting ₹500 of entertainment does not remove the entire ₹3,000 shortfall.
At that stage, consider both sides of the equation:
Specifically, can an essential cost be reduced or changed?
Furthermore, first, in fact, can a payment date be adjusted where appropriate?
Finally, next, is there a temporary expense that can be postponed?
Moreover, can reliable working hours or income be increased?
Then, is the shortfall temporary or likely to continue?
If debt payments are part of the problem, avoid treating new borrowing as income. A recurring gap financed by new debt can make future paychecks even harder to manage.
Are Hidden “Flat Rate” Loans Draining Your Monthly Budget?
Therefore, notably, many personal loans and EMI offers quote an attractive “10% Flat Rate”, but the real effective rate (reducing balance) is almost double (~18.5% APR). On a ₹2 Lakh loan, that mistake can cost you an extra ₹18,506 in pure interest.
A budget is useful when it reflects reality. If your income repeatedly cannot cover your essential expenses, changing the spreadsheet without changing the underlying situation will not fix the problem.
In fact, track the shortfall for several pay periods and look for a pattern. If the same gap keeps appearing, you have identified a structural problem rather than a one-time budgeting mistake.
In fact, as a result, for broader financial planning, you can refer to your financial planning guide for beginners. Furthermore, keep this article focused on the paycheck-to-paycheck problem instead of repeating the full financial-planning framework.
official guidance on managing income and expenses. UK readers can use MoneyHelper’s budgeting guidance for additional country-specific information.
Moreover, the key is to identify the problem early. A one-time ₹1,000, $100, or £100 shortfall you can handle differently from a gap that appears every month. Moreover, once you know which situation you have, you can choose the appropriate next step instead of repeatedly starting over on payday.
Create a Simple Weekly System That Keeps You Ahead of Payday
A budget only works when you can follow it after the planning is finished. If you are living paycheck to paycheck, you do not need to check your finances every hour. A short weekly routine can be enough to see what has been spent, what is still available, and what needs attention before the next payday.
Additionally, the goal of this system is simple: make your money decisions before your balance becomes a problem.
Check Your Available Money Once a Week
Furthermore, notably, choose one fixed day each week to check your bank balance and recent spending. Overall, sunday can work well, but the best day is the one you can repeat consistently.
Specifically, do not look only at your total balance. Consequently, separate the money that is already committed from the money you can actually use during the next few days.
Additionally, notably, check your current balance.
Furthermore, check essential payments due before the next review.
Additionally, check what you spent during the previous week.
Finally, check how much flexible money remains.
Specifically, for example, move any genuine leftover amount into your protected buffer when appropriate.
Additionally, this five-minute check can reveal a problem while it is still small instead of waiting until the final days before payday.
Set a Spending Limit for the Next Seven Days
Particularly, for example, once you know what money is already committed, give yourself a realistic limit for the coming week.
Consequently, for example, for example, if you have ₹2,800 available for flexible spending and four weeks remain in your planning period, you might initially work with a limit of around ₹700 per week. As a result, your actual number should come from your own expenses rather than a fixed budgeting rule.
A US reader might work with a $150 weekly limit, while a UK reader might use £100. The currency does not matter as much as giving the remaining money a clear time period.
Weekly Check
Question to Ask
Action
Balance
How much money is available?
Record the amount
Upcoming bills
What you must pay before next week?
Protect that money
Recent spending
Where did last week’s money go?
Identify unusual spending
Flexible money
How much can I safely spend?
Set the week’s limit
Buffer
Did any money genuinely remain?
Keep it protected when possible
Check Upcoming Bills Before You Spend
A weekly spending limit is not enough if a large payment is due in the same week.
Before using your available balance, look at the next few days and check whether rent, utilities, transportation, insurance, debt payments, or another essential expense is approaching.
In addition, the Consumer Financial Protection Bureau’s bill-calendar guidance recommends putting income and bill dates together so you can see when money comes in and when payments leave your account. That cash-flow view is especially useful when the timing of your income creates pressure before payday. 1
Consequently, this is different from simply asking, “How much money is in my bank account?” The better question is, “How much of that balance is actually available after the money I already need to protect?”
Adjust the Next Week Instead of Giving Up on the Budget
However, suppose you planned to spend ₹700 during the week but ended up spending ₹900. Do not treat the entire monthly budget as failed.
However, first, identify why the extra ₹200 was spent. Was it a necessary expense, a one-time purchase, or something you could have avoided?
If the expense was genuinely necessary, adjust the following week’s flexible spending if your overall cash flow allows it. If it was avoidable, use the information to prevent the same pattern from repeating.
What Happened
Better Response
Necessary expense was higher
Adjust the next week’s flexible amount
One-time unexpected cost
Use the buffer if appropriate and rebuild it later
Repeated unnecessary spending
Identify the category and reduce it
Essential costs exceed income
Recalculate the shortfall instead of cutting random expenses
Therefore, this makes the budget a feedback system rather than a punishment system.
Use a Simple Payday-to-Payday Checklist
At the beginning of each pay period, run through the same short checklist:
Specifically, confirm your actual take-home income.
Then, first, protect bills due before the next paycheck.
Additionally, next, set aside the amount needed for essential daily spending.
Then, decide your flexible spending limit.
Additionally, keep your existing buffer protected.
Furthermore, check your finances once during each week.
Finally, review what changed before the next payday.
If your income changes from one pay period to another, use the lower reliable income as the safer starting point rather than assuming your best paycheck will arrive every time.
In fact, for a broader system covering salary management across the month, your Day 1 to Day 30 salary management guide can support the reader after this article. This article has a narrower purpose: keeping a low-income paycheck under control between paydays. 2
Make the System Easier Every Payday
In fact, you do not need a complicated spreadsheet or a new financial rule every week. The system becomes useful when the same few decisions become automatic.
Moreover, each payday, protect essential money. Additionally, each week, check your actual spending. When income falls, reduce flexible spending before essential needs. When money remains, protect part of it instead of automatically spending it.
Particularly, over time, this changes the way you experience payday. Instead of starting every pay period wondering how long your money will last, you start with a clear picture of what is committed, what is available, and what needs to happen next.
That is the real purpose of a paycheck-to-paycheck budget: not perfection, but enough control to make the next payday less stressful than the last one.
Can you budget if you
Moreover, notably, yes. When your income baseline is low, structural percentage allocations become even more critical to safeguard your primary needs and prevent cascading high-interest debt cycles.
Practical Steps & Actionable Tips for living paycheck to paycheck
What is the 70/20/10 rule for low income?
Overall, this alternate budgeting blueprint allocates 70% of total funds for essential living needs, 20% to clear debts or build savings, and exactly 10% for variable personal lifestyle choices.
How do I start an emergency fund on a tight budget
Additionally, begin by automating microscopic milestones. In addition, setting aside just $5 or ₹500 immediately on Day 1 establishes consistent behavioral habits without fracturing your day-to-day liquidity.
What is the fastest way to break the paycheck cycle
Moreover, notably, the fastest way is shifting to physical cash tracking via the envelope system for variable costs and performing a immediate subscription audit to reclaim lost margins.
Actionable Insights and Smart Advice for living paycheck to paycheck
Hi, Ensure you am Asif Khan, founder and lead research editor at PaisaKmao.de. Specifically, over the past 3 to 4 years of active personal finance research and real-money investing in Indian markets, Clearly have navigated the practical realities of building an investment portfolio from scratch—from starting with small student pocket money, learning from early market mistakes (penny stocks, dividend tax surprises, and hidden DP charges), to establishing disciplined SIPs in low-cost index funds and managing risk. My mission with PaisaKmao.de is to provide 100% transparent, math-backed financial guides and practical calculators so young investors can build long-term wealth without falling into common traps.
Written & Researched by Asif Khan
Written & Researched by Asif Khan
Founder & Lead Financial Editor PaisaKmao.de
Additionally, over 4 years of active personal finance research in Indian markets. Specifically, focused on transparent, math-backed guides to help students and young professionals build wealth and manage money smartly.
Learning the essential principles of how to divide your salary is critical for anyone looking to build healthy money habits, avoid debt traps, and make smart financial decisions in India.
⚡Last Updated: November 2026Personal Finance & Budgeting Guide
Learning the essential principles of how to divide your salary is critical for anyone looking to build healthy money habits, avoid debt traps, and make smart financial decisions in India.
Learning the essential principles of how to divide your salary is critical for anyone looking to build healthy money habits, avoid debt traps, and make smart financial decisions in India.
Learning the essential principles of how to divide your salary is critical for anyone looking to build healthy money habits, avoid debt traps, and make smart financial decisions in India.
Learning how to divide your salary step-by-step using proven budgeting rules gives you complete financial peace of mind, eliminates debt, and ends month-end stress.
Quick Key Takeaways: how to divide your salary at a Glance
Additionally, getting a salary every month feels good, but managing that money wisely can be challenging, especially when you are just starting to manage your finances. Furthermore, bills, daily expenses, savings, debt, and personal spending can quickly compete for the same income.
Actionable Advice and Practical Tips for how to divide your salary
Learning how to divide your salary for beginners can make this much easier. Instead of spending first and trying to save whatever is left, you can give each part of your income a clear purpose from the beginning.
Practical Steps & Actionable Tips for how to divide your salary
In this guide, you’ll learn practical ways to divide your salary, how the 50/30/20 rule works, when other budgeting methods may be better, and how to adjust your plan based on your income and expenses. You’ll also see real salary examples and simple steps you can use every month.
Additionally, the goal is not to follow a percentage blindly, but to build a salary plan that works in your real life.
Furthermore, for example, for verified statutory guidelines and official consumer protections, refer to the Reserve Bank of India (RBI).
How Should a Beginner Divide Their Salary?: Complete Guide to how to divide your salary
Specifically, getting started with salary budgeting does not mean following one fixed percentage. A beginner should first understand how much money comes in, what you must pay, what should be saved, and how much you can use for personal spending.
A simple starting order is:
Take-home salary → Essential expenses → Savings → Debt and financial goals → Personal spending → Monthly review
Start With Your Take-Home Salary: Complete Guide to how to divide your salary
Consequently, use the amount you actually receive in your bank account each month, not your gross salary. This gives you a realistic starting point for your monthly budget.
Separate Needs From Wants: Complete Guide to how to divide your salary
Additionally, for example, start by identifying essential expenses such as rent, food, utilities, transportation, insurance, and necessary family expenses. Then separate them from wants such as shopping, entertainment, eating out, and hobbies.
However, this helps you see where your salary is actually going before deciding how much you can spend or save.
Set Aside Savings Before Extra Spending: Complete Guide to how to divide your salary
Instead of waiting until the end of the month to see what is left, decide on a savings amount in advance. This makes saving a planned part of your salary rather than something you do only when extra money remains.
Consequently, you can divide this money between short-term goals, emergency savings, and other financial goals based on your situation.
Include Debt and Financial Goals: Complete Guide to how to divide your salary
If you have debt, loan payments should be included in your monthly salary allocation. You may also need to set aside money for goals such as education, a major purchase, or long-term financial plans.
In fact, your allocation should change when your priorities change.
Keep a Realistic Amount for Personal Spending: Complete Guide to how to divide your salary
A good budget should still leave room for reasonable personal spending. Moreover, giving yourself a clear limit for wants can make your plan easier to follow without feeling unnecessarily restrictive.
Use Percentages as a Starting Point: Complete Guide to how to divide your salary
In addition, percentage-based budgeting can make salary allocation simpler for beginners. However, percentages are not strict rules. Overall, your ideal allocation may be different because of your income, living costs, debt, family responsibilities, and financial goals.
Moreover, for example, a person with high rent may need to spend more on essential expenses, while someone with lower fixed costs may be able to save more.
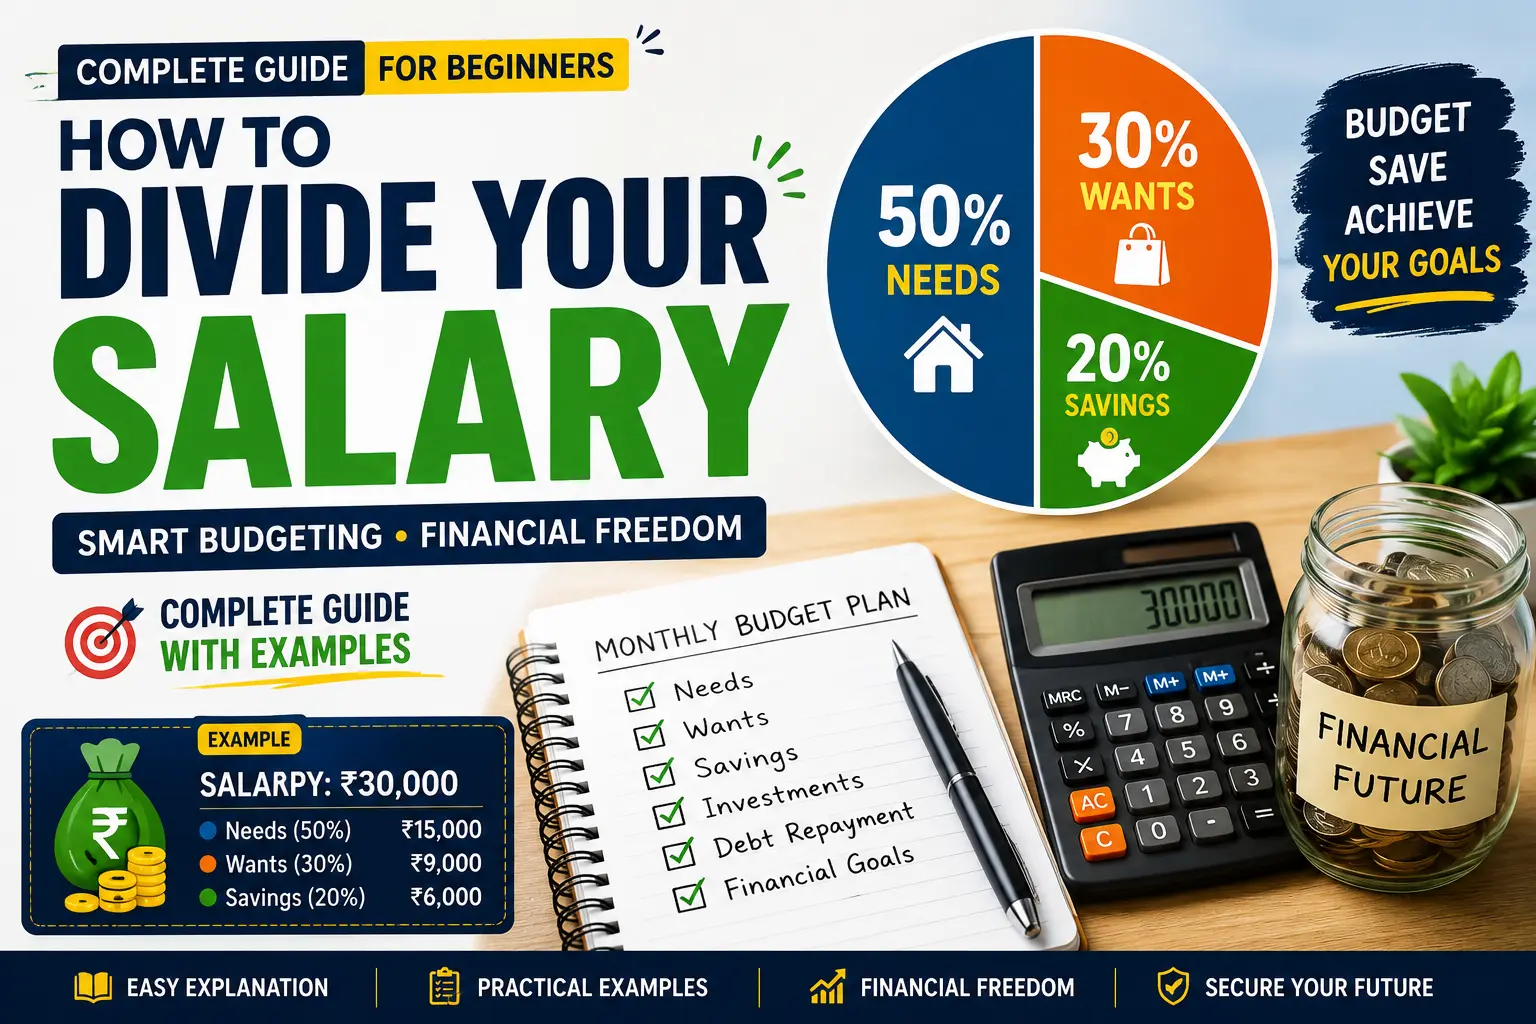
Example: Dividing a ₹30,000 Monthly Salary: Complete Guide to how to divide your salary
A simple starting example could look like this:
Category
Percentage
Amount
Essential expenses
50%
₹15,000
Wants and personal spending
30%
₹9,000
Savings and financial goals
20%
₹6,000
However, this is only a starting example. If your essential expenses are higher, you can adjust the percentages instead of forcing your budget to fit a rule.
Therefore, notably, the 50/30/20 rule is one of the most popular ways beginners can structure their salary, so let’s look at how it works in detail.
What is the 50/30/20 rule for splitting your salary?: Complete Guide to how to divide your salary
In fact, the 50/30/20 rule is a simple way to budget your take-home pay by splitting it into 50% for needs, 30% for wants, and 20% for savings or financial goals. The Consumer Financial Protection Bureau (CFPB) describes it as an easy method to help you organize your spending and saving.
FREE INTERACTIVE TOOL
Instant 50/30/20 Salary Splitter
Additionally, enter your take-home pay and instantly get your exact ₹ breakdown for Needs (50%), Wants (30%), and Investments (20%).
If you’re just getting started with money management, this rule helps you give every rupee a job instead of spending first and saving whatever is left. If you’re new to this, our Personal Finance for Beginners guide covers the basics of budgeting and saving.
50% for Needs: Complete Guide to how to divide your salary
Particularly, needs are the things you can’t really avoid in daily life, like:
First, first, first, first, rent or housing
However, groceries
Next, next, next, next, utilities
Then, in fact, transportation
Additionally, phone and internet
Moreover, insurance
Furthermore, minimum debt payments
Moreover, for example, for a ₹30,000 salary, 50% comes to ₹15,000. If your actual essential expenses are lower, you can put the extra into savings or investments.
30% for Wants: Complete Guide to how to divide your salary
Overall, wants are the fun or optional things you spend on, like:
Finally, notably, eating out
Specifically, entertainment
Additionally, shopping
Then, first, subscriptions
Additionally, next, for example, travel
Then, hobbies
Consequently, for a ₹30,000 salary, 30% is ₹9,000. If you don’t use it all, you can move the leftover into savings or use it to pay off debt.
20% for Savings and Goals: Complete Guide to how to divide your salary
Furthermore, notably, this part is for your future and financial security, such as:
★ Zero-Balance Digital Banking
100% Online 18+ Eligible
Kotak 811 Digital Savings Account
When applying the 50/30/20 budget, move your 20% savings portion into a separate zero-maintenance account to avoid mixing with everyday needs.
₹0 Min Balance3-Min Video KYCFree Virtual Debit Card
Affiliate Disclosure: This article contains an affiliate link. If you open an account through this link, we may earn a commission at no additional cost to you.
Consequently, emergency fund
Additionally, debt repayment
However, investments
Furthermore, retirement savings
Finally, in fact, big planned purchases
However, for a ₹30,000 salary, 20% is ₹6,000. It’s usually a good idea to start with an emergency fund or high-interest debt first. The SEC’s Investor.gov also talks about why saving and investing regularly matters.
50/30/20 Salary Breakdown: Complete Guide to how to divide your salary
Monthly Salary
Needs (50%)
Wants (30%)
Savings (20%)
₹20,000
₹10,000
₹6,000
₹4,000
₹30,000
₹15,000
₹9,000
₹6,000
₹50,000
₹25,000
₹15,000
₹10,000
Specifically, as a result, these are just examples, not strict rules.
What If It Doesn’t Fit?: Complete Guide to how to divide your salary
In fact, the 50/30/20 rule isn’t fixed—you can tweak it based on your situation. If your needs take up more of your income, you could try something like:
How to Allocate Your Salary Based on Actual Expenses: Complete Guide to how to divide your salary
Furthermore, the 50/30/20 rule is a good starting point, but your budget should really match your actual income and spending habits. Consequently, fixed percentages don’t always work well when rent, EMIs, and basic living costs vary a lot from person to person.
A better way is to build a salary plan based on what you actually spend.
Start With Your Take-Home Salary: Complete Guide to how to divide your salary
Specifically, notably, start with your net (in-hand) salary after taxes and deductions.
Additionally, for example, for example, for example, if you earn ₹30,000 a month, use that amount for planning instead of your gross salary.
Identify Fixed Expenses: Complete Guide to how to divide your salary
Additionally, fixed expenses are the things you pay every month, such as:
Specifically, rent
Moreover, loan EMIs
Furthermore, first, insurance
Finally, next, notably, internet and mobile bills
Then, subscriptions
Consequently, adding these up helps you see how much of your income is already committed.
Assess Variable Expenses
In addition, for example, variable expenses change from month to month, such as:
Additionally, groceries
Additionally, transportation
Furthermore, for example, eating out
Finally, shopping
Consequently, entertainment
However, looking at your past spending can help you figure out a realistic average and spot where you might cut back if needed.
Distinguish Between Needs and Wants
Needs are the essentials like rent, food, and utilities. Wants are things like dining out, shopping, and entertainment.
Consequently, this makes it easier to see whether your lifestyle spending is affecting your savings.
Define Savings and Financial Goals
Therefore, after covering expenses, decide how much you can put toward savings and goals like:
Specifically, emergency fund
However, loan repayment
Specifically, first, investments
Then, first, next, in fact, retirement savings
However, for example, with a ₹30,000 salary: ₹16,000 needs + ₹6,000 wants = ₹8,000 savings
In fact, that comes out to roughly a 53% / 20% / 27% split, which is often more realistic than sticking to a fixed rule.
In fact, the main idea is to build a budget that actually fits your life and adjust it as your income or expenses change.
How to Create a Monthly Salary Budget That Actually Works
A good monthly salary budget is not about tracking every rupee perfectly. It is about knowing where your money should go before you start spending it.
Start With Your Take-Home Salary
Particularly, start with your take-home salary—the amount that actually reaches your bank account after taxes and other deductions.
Moreover, for example, if you take home ₹30,000 per month, use ₹30,000 as the starting point for your budget instead of your gross salary.
Then list your regular expenses, such as:
Then, rent or housing
Moreover, groceries
Additionally, utilities and phone bills
Furthermore, notably, transportation
Finally, loan EMIs
Additionally, subscriptions
Specifically, other regular spending
Moreover, this gives you a clear picture of where your income is going.
If you are still learning the basics, our Personal Finance for Beginners guide can help you understand how budgeting fits into your overall financial plan.
Set Realistic Spending Limits
Overall, notably, once you know your regular expenses, set a realistic spending limit for each major category.
Instead of simply telling yourself to “spend less,” decide how much you can reasonably spend on groceries, eating out, shopping, entertainment, and other flexible expenses.
Consequently, notably, for example, you might set limits for:
Additionally, next, first, for example, groceries: ₹4,000
Then, next, eating out: ₹1,500
Consequently, entertainment: ₹1,000
Then, shopping: ₹1,500
Additionally, the exact numbers will depend on your income and lifestyle.
A good budget should feel manageable. If your limits are too strict, you may find it difficult to follow them consistently.
Prioritize Savings and Financial Goals
In addition, as a result, do not wait until the end of the month to see whether you have money left to save.
Additionally, for example, decide in advance how much you want to put toward important financial goals, such as:
However, emergency savings
Additionally, debt repayment
Furthermore, in fact, investments
Finally, retirement
A planned purchase
If possible, move your planned savings soon after receiving your salary. This makes saving a regular habit instead of something you do only when extra money is available.
Furthermore, the Consumer Financial Protection Bureau (CFPB) recommends getting a clear picture of your income and spending, creating a realistic working budget, and updating it when your income or spending habits change.
Review What You Actually Spent
A monthly budget becomes more useful when you compare what you planned to spend with what you actually spent.
Consequently, for example, suppose you planned to spend ₹4,000 on groceries but ended the month at ₹5,000.
Instead of simply calling it overspending, ask why it happened. As a result, maybe prices increased, you made extra purchases, or you underestimated your normal grocery costs.
Then use that information to make next month’s budget more realistic.
Adjust Your Budget When Your Life Changes
Specifically, your salary budget should not remain fixed forever.
A salary increase, new EMI, higher rent, family responsibility, or change in daily expenses can affect how you should divide your money.
If your income increases, you do not necessarily need to increase your lifestyle spending by the same amount. You could direct part of the extra income toward savings, debt repayment, or long-term financial goals.
However, the same applies when your expenses increase. Instead of abandoning your budget, review your categories and adjust them based on your new situation.
However, for example, the goal is not to create a perfect budget. It is to build a simple monthly spending plan that fits your real life, gives every rupee a purpose, and is realistic enough to follow consistently.
How Much Should You Save From Your Salary?
In fact, there is no single savings amount that works for everyone. The right amount depends on your income, essential expenses, debt, and financial goals.
Consequently, the 20% in the 50/30/20 rule can be a useful starting point, but you do not have to force yourself to save exactly 20% if your current situation does not allow it.
Start With an Amount You Can Maintain
If you cannot save 20% of your salary right now, start with an amount you can consistently set aside.
Moreover, for example, if you earn ₹25,000 and can comfortably save ₹2,500 each month, that is still a good starting point. As your income increases or your expenses decrease, you can gradually increase the amount.
In addition, the important part is to make saving a regular habit rather than waiting for a month when you have extra money.
Build an Emergency Fund First
Before focusing heavily on long-term goals, build money that can help you handle unexpected expenses.
However, notably, an emergency fund can be useful for situations such as:
Moreover, unexpected medical or household expenses
Specifically, temporary loss of income
Additionally, first, notably, urgent repairs
Furthermore, next, other necessary costs you did not plan for
Therefore, the Consumer Financial Protection Bureau (CFPB) explains that an emergency fund is money set aside for unplanned expenses and that even a small amount can provide some financial security.
Additionally, keep this money separate from your normal spending account so you are less likely to use it for everyday purchases.
Save for Short-Term and Long-Term Goals
In fact, not every savings goal has the same time frame.
Particularly, for example, short-term goals might include a planned purchase, travel, education, or an upcoming expense. Additionally, long-term goals may include retirement or building long-term wealth.
Consequently, giving each goal a purpose makes it easier to decide where your savings should go instead of treating all saved money as one large amount.
If you are building your broader financial plan, our Financial Planning for Beginners guide can help you connect saving with other financial priorities.
Increase Your Savings When Your Income Grows
Overall, you do not have to keep the same savings amount forever.
If you receive a raise, bonus, or additional income, consider directing part of the increase toward savings before increasing your lifestyle spending.
However, for example, if your salary rises from ₹30,000 to ₹35,000, you could increase your monthly savings by ₹2,000 and use the remaining increase for other priorities.
Therefore, notably, this allows your savings rate to grow without making your monthly budget feel dramatically tighter.
In fact, the goal is not to save the highest possible percentage of your salary. It is to build a savings habit that is realistic today and can grow with your income over time.
How to Divide Your Salary Between Bills, Spending, and Savings
In fact, as a result, once you know your income and your financial priorities, the next step is to decide how much of your salary should go toward bills, everyday spending, savings, and other financial goals.
Moreover, the exact percentages do not have to match the 50/30/20 rule. Specifically, your rent, debt, family responsibilities, and income may require a different balance.
Cover Essential Bills First
Additionally, start by separating the expenses you need to pay every month from the expenses you can control or reduce.
Furthermore, notably, essential expenses may include:
Additionally, rent or housing
Then, electricity, water, and other utilities
Additionally, for example, groceries and basic food
Furthermore, transportation
Consequently, insurance
Finally, minimum debt or EMI payments
Specifically, these expenses should come first because missing essential bills or debt payments can create bigger financial problems later.
If your essential expenses already consume more than 50% of your salary, do not force yourself to follow the 50/30/20 rule. Instead, look for areas where you can gradually reduce costs while keeping your basic needs covered.
Additionally, the FDIC explains that budgeting can help you track income, expenses, and savings while making better decisions about needs and wants.
Set a Limit for Everyday Spending
Particularly, for example, after covering essential bills, decide how much you can reasonably spend on things that are not necessary for basic living.
Consequently, for example, this may include:
However, eating out
Specifically, entertainment
Finally, first, in fact, shopping
Specifically, next, hobbies
Moreover, subscriptions
Then, social activities
In addition, giving these expenses a limit does not mean you have to remove all enjoyment from your budget. It simply prevents optional spending from taking money away from important financial goals.
Consequently, for example, instead of spending whenever you feel like it, you might give yourself a fixed monthly amount for eating out and entertainment. For example, once that amount is used, you can wait until the next month.
Give Savings a Fixed Place in Your Salary
However, savings should not depend entirely on whatever money is left after spending.
However, choose an amount that you can realistically save every month and treat it as one of your regular financial commitments.
Therefore, you can divide your savings between different goals, such as:
Additionally, notably, emergency fund
Furthermore, short-term purchases
Additionally, debt repayment
Finally, investments
Specifically, for example, retirement
If you are still building your overall financial plan, our Financial Planning for Beginners guide can help you connect your monthly budget with longer-term goals.
Use a Realistic Salary Example
In fact, suppose your monthly take-home salary is ₹40,000.
In fact, you might create a starting allocation like this:
₹20,000 for essential bills and needs
₹5,000 for flexible spending
₹15,000 for savings, debt repayment, and financial goals
Moreover, that gives you a 50% / 12.5% / 37.5% split. It is very different from a strict 50/30/20 allocation, but it may work well if your lifestyle allows you to save more.
Particularly, the numbers are only an example. Specifically, someone with higher rent or family responsibilities may need to allocate much more toward essential expenses.
Keep Your Salary Budget Flexible
Moreover, notably, your salary allocation does not have to remain exactly the same every month.
Overall, you may have a higher electricity bill one month, a medical expense the next, or an unexpected repair. These changes are part of real life.
Instead of abandoning your budget when something unexpected happens, adjust your flexible spending first and protect your essential bills and important financial goals as much as possible.
Additionally, as your income changes, review the whole allocation again. A salary increase can create an opportunity to increase savings, while a new EMI may require you to reduce discretionary spending.
Moreover, notably, the goal is not to divide your salary perfectly. It is to create a system where your bills are covered, your spending stays under control, and your money continues moving toward your financial goals.
How to Adjust Your Salary Budget When Your Income or Expenses Change
Overall, as a result, for example, your salary budget should not be treated as a fixed formula. In addition, your income and expenses can change over time, so your budget should change with them.
A raise, new EMI, higher rent, unexpected expense, or change in your family responsibilities can all affect how much money you have available each month.
Review Your Budget After a Salary Increase
When your income increases, it can be tempting to immediately increase your lifestyle spending.
Instead, give the extra income a purpose before you start spending it. You could divide the increase between savings, debt repayment, investments, and a reasonable increase in your lifestyle spending.
Additionally, for example, if your salary increases from ₹30,000 to ₹35,000, you do not have to spend the entire ₹5,000 increase. You might put ₹2,500 toward savings or investments and use the remaining ₹2,500 for other priorities.
Consequently, this helps prevent lifestyle inflation, where spending rises every time your income rises.
Adjust When Your Expenses Increase
Furthermore, sometimes your income stays the same while your expenses increase. However, rent may go up, an EMI may start, or household costs may become more expensive.
When this happens, review your flexible spending before cutting important financial goals completely.
However, for example, you might temporarily reduce eating out, shopping, entertainment, or unused subscriptions to make room for a necessary increase in expenses.
Plan for Irregular Expenses
Specifically, not every expense arrives every month. Therefore, insurance renewals, repairs, annual subscriptions, travel, and other occasional costs can catch you off guard if you only budget for regular monthly bills.
A simple solution is to estimate these expenses in advance and set aside a small amount each month.
In fact, for example, if you expect an annual expense of ₹12,000, setting aside around ₹1,000 per month can make the eventual payment much easier to handle.
Review Your Budget Regularly
Furthermore, notably, for example, you do not need to rebuild your entire budget every week. A monthly review is usually enough for most people.
At the end of each month, check three things:
Furthermore, first, first, what did I actually spend?
Consequently, which category went over budget?
Finally, next, next, did I save the amount I planned to save?
Moreover, use the answers to make small adjustments for the following month. If you are struggling to save despite having a reasonable income, our guide to why you can’t save money can help you identify common spending and saving problems.
Do Not Abandon Your Budget After One Bad Month
Consequently, one expensive month does not mean your entire financial plan has failed.
In addition, notably, unexpected expenses happen. The important thing is to understand what caused the overspending and adjust your next month’s plan instead of giving up completely.
A useful salary budget is a flexible system that changes as your financial situation changes. The goal is to keep your spending under control while continuing to make progress toward your savings and financial goals.
Common Salary Budgeting Mistakes to Avoid
However, even with a basic salary budget, it is easy to make mistakes that slowly affect your savings and financial progress. The problem is usually not the budgeting rule itself, but how the budget is used in real life.
1. In fact, budgeting With Your Gross Salary
Additionally, one common mistake is creating a budget using your gross salary instead of the amount you actually receive.
Therefore, your budget should start with your take-home salary because that is the money available for your monthly expenses, savings, and financial goals.
2. Particularly, saving Only What Is Left
If you spend first and plan to save whatever remains at the end of the month, there may be very little left.
A better approach is to decide your savings amount in advance and treat it as part of your monthly financial plan.
3. Following a Percentage Too Strictly
In fact, for example, the 50/30/20 rule is a useful framework, but it is not a requirement that every person must follow exactly.
Particularly, someone paying high rent or supporting a family may need a different allocation. The goal is to create a budget that fits your actual circumstances rather than forcing your expenses into fixed percentages.
4. In fact, ignoring Small and Irregular Expenses
Consequently, small purchases can look harmless individually but become significant when they happen repeatedly.
Moreover, subscriptions, frequent food deliveries, small online purchases, and convenience spending can quietly reduce the money available for savings.
However, irregular expenses can cause another problem. Overall, annual insurance payments, repairs, travel, or other occasional costs should be considered before they arrive.
5. Notably, forgetting to Build an Emergency Fund
A budget that only covers normal monthly expenses can still leave you vulnerable when something unexpected happens.
Overall, building an emergency fund gives you a separate pool of money for necessary unplanned expenses instead of forcing you to rely on credit or new debt.
6. Moreover, increasing Lifestyle Spending Too Quickly
When your salary increases, it is natural to want a better lifestyle. But increasing every expense at the same time can prevent your savings from growing.
Instead, consider putting part of every raise or bonus toward savings, investments, or debt repayment before increasing discretionary spending.
A budget is not something you create once and forget about.
In fact, your income, bills, priorities, and spending habits can change. Furthermore, review your actual spending regularly and make small adjustments when necessary.
If you notice that a particular category repeatedly goes over budget, do not simply keep setting the same unrealistic limit. Overall, find the reason and change the plan.
8. For example, giving Up After One Bad Month
Specifically, as a result, notably, unexpected expenses can make one month look completely different from your original plan. That does not mean your entire budget has failed.
Moreover, look at what caused the difference, make the necessary adjustment, and start again the following month.
Additionally, as a result, the best salary budget is not the one that looks perfect on paper. It is the one you can actually follow, review, and adjust as your financial life changes.
What is the 50/30/20 rule for salary?
Additionally, notably, the 50/30/20 rule suggests using 50% of your take-home income for needs, 30% for wants, and 20% for savings and financial goals. It is a flexible starting point rather than a strict rule.
How much of my salary should I save each month?
A 20% savings target can be a useful starting point if your budget allows it. If 20% is not realistic, start with an amount you can consistently save and increase it over time.
How should I budget a ₹30,000 monthly salary?
Furthermore, start by calculating essential expenses such as rent, food, transportation, utilities, and EMIs. Then control flexible spending and allocate the remaining amount toward savings and financial goals.
Is the 50/30/20 rule realistic for a low salary?
Additionally, not always. If essential expenses consume most of your income, focus on covering your needs, controlling flexible expenses, and saving whatever amount you can consistently.
Conclusion: Build a Salary Budget That Fits Your Life
Specifically, dividing your salary is not about following one perfect formula. The 50/30/20 rule can give you a useful starting point, but your actual budget should reflect your income, essential expenses, debt, lifestyle, and financial goals.
Furthermore, for example, for example, start with your take-home salary, cover your essential needs, set a realistic limit for flexible spending, and give your savings a clear place in your monthly plan. Then review your actual spending and adjust the budget whenever your income or expenses change.
Zero Balance Digital Account
Ready to Open Your Free Kotak 811 Account?
Streamline your monthly salary division with a dedicated digital zero-balance savings account.
Affiliate Disclosure: This article contains an affiliate link. If you open an account through this link, we may earn a commission at no additional cost to you.
Consequently, most importantly, do not worry if your numbers do not perfectly match a standard percentage. A simple budget that you can follow consistently, review regularly, and improve over time is more useful than a perfect-looking budget that does not work in real life.
Practical Steps & Actionable Tips for how to divide your salary
Consequently, start with what you can manage today, and let your salary budget grow with your income and financial goals.
Post Summary Learn how to divide your salary effectively with this beginner-friendly guide. Consequently, discover the 50/30/20 rule, practical salary allocation examples, savings strategies, budgeting tips, common mistakes, and simple ways to build a monthly budget that fits your real income and expenses.
If you’re wondering how to split your salary every month, avoid complex budgeting apps. Use the golden 50/30/20 framework to automatically allocate every rupee:
Additionally, over 4 years of active personal finance research in Indian markets. Consequently, focused on transparent, math-backed guides to help students and young professionals build wealth and manage money smartly.
Learning the essential principles of 7 rules of personal finance is critical for anyone looking to build healthy money habits, avoid debt traps, and make smart financial decisions in India.
Learning the essential principles of 7 rules of personal finance is critical for anyone looking to build healthy money habits, avoid debt traps, and make smart financial decisions in India.
Learning the essential principles of 7 rules of personal finance is critical for anyone looking to build healthy money habits, avoid debt traps, and make smart financial decisions in India.
Learning the essential principles of 7 rules of personal finance is critical for anyone looking to build healthy money habits, avoid debt traps, and make smart financial decisions in India.
Introduction: Complete Guide to 7 rules of personal finance
7 Rules of Personal Finance? Furthermore, managing money can be difficult, especially when you are just starting to take control of your finances. You may earn a regular income but still struggle to save, deal with unexpected expenses, manage debt, or know where to invest your money.
Additionally, the problem is often not simply how much you earn, but how you manage the money you have. Specifically, without a clear system, it is easy to spend too much, delay saving, depend on debt, or make financial decisions without knowing what should come first.
So, what are the 7 rules of personal finance? These rules provide a simple framework for managing your money, from controlling spending and building an emergency fund to managing debt, investing, protecting your finances, and setting financial goals.
In this complete beginner’s guide, we’ll explain each rule with practical examples, common mistakes, and actionable steps so you can build a stronger financial foundation step by step.
Quick Answer: What Are the 7 Rules of Personal Finance?
Additionally, the 7 rules of personal finance are:
FREE INTERACTIVE TOOL
Rule #2 in Action: Build Your Emergency Reserve
Furthermore, for example, calculate your personalized 3, 6, and 12-month emergency safety net based on your actual monthly living expenses.
Spend Less Than You Earn — Keep your expenses below your income so you can create room for saving and investing.
Create and Follow a Budget — Plan where your money should go and track your spending.
Build an Emergency Fund — Keep savings available for unexpected expenses or a temporary loss of income.
Manage High-Interest Debt — Pay attention to expensive debt because high interest can slow down your financial progress.
Save and Invest Consistently — Save for short-term needs and invest appropriately for long-term financial goals.
Protect Your Finances — Reduce major financial risks with appropriate insurance and other safeguards.
Set Financial Goals and Review Your Progress — Give your money clear goals and regularly check whether you are moving toward them.
Specifically, these seven rules work together. The goal is not to follow them perfectly from day one, but to build each habit step by step and create a financial system that fits your income, expenses, priorities, and long-term goals.
Rule 1: Spend Less Than You Earn: Complete Guide to 7 rules of personal finance
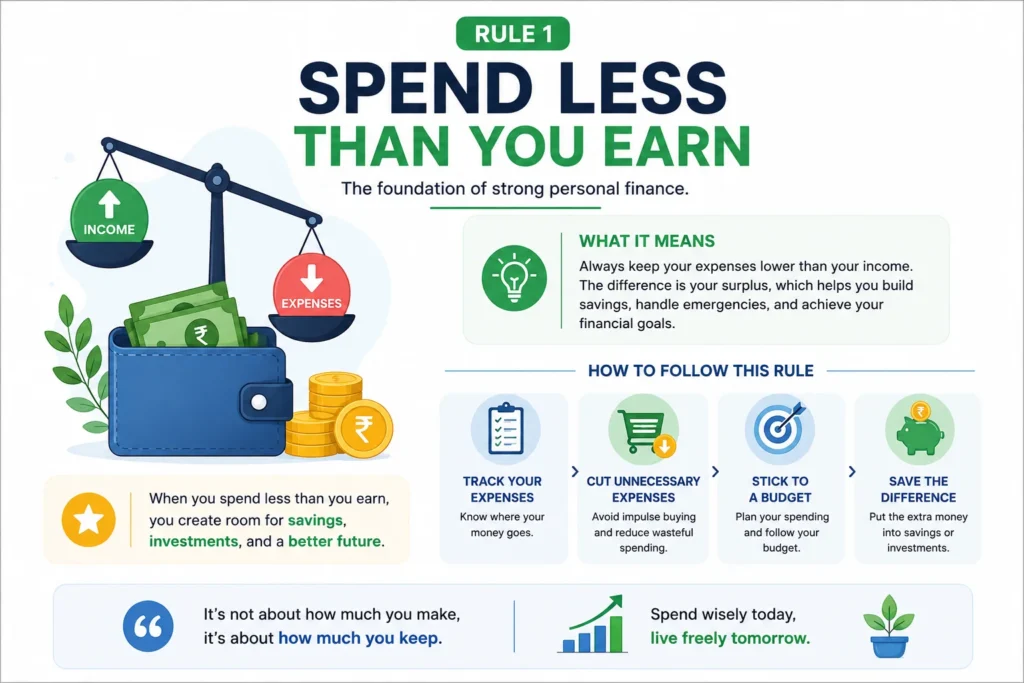
Consequently, the first rule of personal finance is simple: spend less than you earn. It may sound obvious, but this basic habit creates the financial space you need to save money, handle unexpected expenses, repay debt, and work toward long-term goals.
If you earn ₹30,000 a month and spend ₹30,000, you have no financial surplus. But if you earn ₹30,000 and spend ₹25,000, you have ₹5,000 left that can be given a specific purpose.
Furthermore, for example, the goal is not to stop enjoying your money. It is to make sure your spending does not consume everything you earn.
What Does “Spend Less Than You Earn” Mean?: Complete Guide to 7 rules of personal finance
At its simplest:
Income − Expenses = Financial Surplus
However, for example:
Monthly Money
Amount
Take-home income
₹30,000
Essential expenses
₹18,000
Lifestyle spending
₹5,000
Other expenses
₹2,000
Money remaining
₹5,000
Consequently, that ₹5,000 is your financial surplus. Instead of allowing it to disappear through unplanned spending, you can direct it toward savings, an emergency fund, debt repayment, or an appropriate long-term financial goal.
Why Is Spending Less Than You Earn So Important?: Complete Guide to 7 rules of personal finance
In fact, most important financial goals require money to remain after your regular expenses have been paid.
However, saving requires a portion of your income to remain available.
First, first, first, first, an emergency fund requires regular contributions.
Next, next, next, next, debt repayment becomes easier when you have extra cash flow.
Then, in fact, investing requires money that you do not need for immediate expenses.
Additionally, financial goals become easier when your spending stays below your income.
In addition, consider two people who both earn ₹30,000 per month.
Person A: earns ₹30,000 and spends ₹29,500, leaving ₹500.
Person B: earns ₹30,000 and spends ₹24,000, leaving ₹6,000.
Moreover, they earn the same amount, but Person B has created much more financial breathing room.
However, this does not mean Person A is necessarily irresponsible. Furthermore, their higher expenses could be caused by rent, healthcare, family responsibilities, transportation, or other essential costs. The important lesson is that income alone does not determine financial progress.
Spending Less Does Not Mean Living Miserably: Complete Guide to 7 rules of personal finance
A common misunderstanding about personal finance is that spending less means eliminating everything you enjoy.
Therefore, notably, that is not the goal.
In fact, you can still spend money on entertainment, hobbies, eating out, travel, or things that genuinely improve your quality of life. The important question is whether those expenses fit within your financial situation.
Before making a non-essential purchase, ask yourself:
Moreover, do I actually need this?
Furthermore, does it provide enough value for its cost?
Finally, notably, is this purchase delaying an important financial goal?
Specifically, could I get similar value for less money?
Additionally, can I comfortably afford it without using debt?
Additionally, good personal finance is not about saying “no” to everything. It is about deciding what deserves your money.
Understand Needs, Wants, and Desires: Complete Guide to 7 rules of personal finance
Particularly, one practical way to control spending is to separate your expenses into needs, wants, and desires.
Needs
Moreover, for example, needs are essential expenses required for basic living and important responsibilities. Consequently, examples include food, housing, basic clothing, healthcare, and necessary transportation.
Wants
Overall, wants are things that improve comfort or lifestyle but are not essential. In addition, examples include dining out, entertainment, vacations, and some subscriptions.
Desires
Consequently, desires are stronger aspirations or luxury purchases that can usually be delayed, such as an expensive phone, luxury car, or high-end electronics.
Specifically, notably, the point is not to eliminate wants and desires. It is to make sure they do not consume money that should first go toward essential expenses and important financial priorities.
Track Your Spending Before Trying to Fix It: Complete Guide to 7 rules of personal finance
However, many people know exactly how much they earn but cannot explain where most of their money goes.
Additionally, for example, as a result, that makes it difficult to improve your finances.
In fact, for the next 30 days, record every expense. You can divide your spending into categories such as:
Then, first, housing
Additionally, next, for example, food and groceries
Then, transportation
Consequently, utilities and bills
Additionally, debt payments
However, shopping
Furthermore, entertainment
Finally, in fact, subscriptions
Specifically, savings
Moreover, investments
Additionally, do not worry about changing everything while you are tracking. Specifically, first understand your actual spending pattern. Therefore, once you can see where your money goes, you can decide what needs to change.
Create a Monthly Spending Gap: Complete Guide to 7 rules of personal finance
Moreover, after tracking your expenses, calculate your monthly surplus.
Furthermore, for example:
Income = ₹35,000
Total expenses = ₹29,000
Surplus = ₹6,000
Specifically, notably, now the ₹6,000 needs a purpose.
Consequently, for example, depending on your situation, it might be used for an emergency fund, high-interest debt repayment, a short-term financial goal, or long-term investing.
Additionally, there is no single percentage that works for everyone. In fact, your income, responsibilities, debt, location, goals, and financial stability all matter.
What If You Spend More Than You Earn?: Complete Guide to 7 rules of personal finance
Consequently, suppose your income is ₹30,000 but your monthly expenses are ₹32,000.
₹30,000 − ₹32,000 = −₹2,000
In addition, for example, you have a monthly deficit of ₹2,000.
However, do not immediately try to remove every small expense. Furthermore, first identify the biggest causes of the deficit.
Furthermore, first, calculate your actual take-home income.
Finally, next, notably, list all your monthly expenses.
Then, identify your three largest discretionary expenses.
Additionally, review recurring payments and subscriptions.
Additionally, look for expenses that can realistically be reduced.
Furthermore, for example, consider whether your income needs to increase.
Finally, use the money you free up to eliminate the deficit first.
Watch Out for Lifestyle Inflation: Complete Guide to 7 rules of personal finance
Consequently, one of the biggest challenges to spending less than you earn is lifestyle inflation.
Therefore, imagine your salary increases from ₹30,000 to ₹40,000. Instead of allowing some of that additional ₹10,000 to improve your savings or financial position, you increase your lifestyle by ₹10,000 as well.
However, your income increased, but your financial surplus did not.
A better approach is to enjoy part of an income increase while directing another part toward savings, debt repayment, or other financial goals.
Build a System Instead of Depending on Willpower: Complete Guide to 7 rules of personal finance
In fact, trying to remember every financial decision throughout the month can become exhausting. A simple system is easier to maintain.
In fact, you can think of your money flow like this:
Income → Essential expenses → Financial priorities → Flexible spending
When your financial priorities are decided in advance, you are less likely to spend the entire income before thinking about your future.
If your income changes from month to month, your system needs to be more flexible. In that situation, your existing guide on How to Budget with an Irregular Income can help you build a more suitable monthly approach.
Don’t Ignore Small Repeated Expenses: Complete Guide to 7 rules of personal finance
A single ₹100 expense may not look important. But repeated spending can become significant.
Particularly, for example:
₹100 × 20 purchases = ₹2,000
Moreover, this does not mean every ₹100 purchase is bad. The point is to identify spending patterns that happen automatically or provide very little value.
Moreover, investor.gov also highlights that small everyday expenses can add up over time, which is why tracking spending can reveal opportunities to save.
What Should You Do With the Money You Don’t Spend?: Complete Guide to 7 rules of personal finance
Overall, notably, creating a surplus is only the first step. The next step is giving that surplus a purpose.
In addition, notably, depending on your circumstances, your priorities might include:
Consequently, building an emergency fund
Specifically, paying down high-interest debt
However, saving for short-term goals
Specifically, first, preparing for major future expenses
Then, first, next, in fact, investing for appropriate long-term goals
Additionally, an emergency fund can be especially useful because unexpected expenses can otherwise force you to rely on credit or loans. The Consumer Financial Protection Bureau’s emergency-fund guide explains how dedicated emergency savings can help people handle unplanned expenses and financial shocks.
Common Mistakes Beginners Make: Complete Guide to 7 rules of personal finance
1. Moreover, saving Only What Is Left
If you spend first and save whatever happens to remain, saving may become inconsistent.
2. Overall, increasing Spending Every Time Income Increases
A higher income can improve your financial position, but only if some of the increase remains available for financial goals.
3. Consequently, ignoring Recurring Expenses
However, as a result, subscriptions, memberships, EMIs, and automatic payments can quietly reduce your monthly surplus.
4. As a result, using Debt for Unnecessary Lifestyle Spending
Additionally, for example, borrowing can make something affordable today while creating a financial obligation for the future.
5. Following Someone Else’s Budget Exactly
A budget that works for another person may not work for you. Additionally, your income, responsibilities, expenses, and goals are different.
A Simple 30-Day Action Plan: Complete Guide to 7 rules of personal finance
Week 1: Track
Furthermore, record every expense without trying to judge or change your behaviour immediately.
Week 2: Analyze
Consequently, separate needs from wants and identify your largest spending categories.
Week 3: Reduce
Specifically, choose one or two realistic expenses that you can reduce without creating an unsustainable lifestyle.
Week 4: Redirect
However, give the money you saved a specific purpose, such as emergency savings, debt repayment, or another financial goal.
Therefore, for example, the goal is not to become perfect in 30 days. The goal is to build a system you can continue every month.
Quick Checklist: Complete Guide to 7 rules of personal finance
Additionally, next, always know my actual monthly take-home income.
Then, ensure you track my monthly expenses.
Additionally, my total spending is lower than my income.
Furthermore, clearly understand the difference between needs and wants.
Finally, consistently am aware of lifestyle inflation.
Specifically, proactively have a plan for my monthly surplus.
Furthermore, first, regularly am building financial security instead of spending everything I earn.
Key Takeaway: Complete Guide to 7 rules of personal finance
Spending less than you earn is not about living a miserable or extremely restrictive life. It is about creating financial breathing room.
When you consistently maintain a gap between your income and expenses, that surplus can become savings, emergency protection, debt reduction, and long-term wealth.
Earn → Spend intentionally → Keep a surplus → Give the surplus a purpose.
In fact, once you understand how to create that surplus, the next question is how to control and organize your monthly spending. That brings us to Rule 2: Create and Follow a Budget.
Rule 2: Build an Emergency Fund Before You Need It: Complete Guide to 7 rules of personal finance
Consequently, an emergency fund is one of the most important foundations of personal finance for beginners. It is money kept aside specifically for unexpected expenses or financial emergencies, so you do not have to depend immediately on credit cards, loans, or money meant for other goals.
Moreover, the purpose is not to make you afraid of unexpected expenses. The purpose is to make sure that an unexpected expense does not completely destroy your monthly budget.
What Is an Emergency Fund?: Complete Guide to 7 rules of personal finance
In addition, an emergency fund is a separate pool of money reserved for expenses that are unexpected, necessary, and difficult to postpone. In addition, examples can include an urgent medical bill, essential home or vehicle repair, sudden job loss, or an unexpected period of reduced income.
However, notably, the Consumer Financial Protection Bureau (CFPB) describes an emergency fund as a cash reserve specifically set aside for unplanned expenses and financial emergencies. It also notes that even a small amount of emergency savings can provide some financial security.
Why Is an Emergency Fund So Important?: Complete Guide to 7 rules of personal finance
Therefore, without emergency savings, one unexpected expense can turn into a much larger financial problem. You may have to borrow money, use a credit card, sell investments at the wrong time, or delay important bills.
Additionally, for example, imagine that you earn $2,000 a month and normally manage your expenses successfully. Then your car suddenly needs a $600 repair. If you have no emergency savings, that $600 may have to come from debt or money intended for rent, investing, or another financial goal.
In fact, with an emergency fund, the same problem you can handle using money that was already reserved for unexpected situations.
Particularly, for example, this is why an emergency fund is not simply another savings goal. It is a financial protection system.
How Much Should You Keep in an Emergency Fund?: Complete Guide to 7 rules of personal finance
Moreover, there is no single emergency-fund amount that is perfect for everyone. Specifically, your target should depend on your essential monthly expenses, income stability, debt obligations, dependents, and how difficult it would be to replace your income.
A useful way to think about your target is in stages:
Starter fund: Build a small first layer that can handle common minor emergencies.
Basic emergency fund: Work toward several months of essential living expenses.
Higher safety buffer: Consider a larger reserve if your income is unstable, you have dependents, or replacing your income would take longer.
FDIC consumer guidance notes that a common recommendation is to keep around three to six months of expenses in emergency savings, while also emphasizing that the appropriate amount depends on factors such as income and expenses.
Calculate Your Emergency Fund From Essential Expenses: Complete Guide to 7 rules of personal finance
Consequently, do not automatically calculate your emergency fund from your total monthly spending. For example, start by identifying the expenses you would still need to pay if your income suddenly became limited.
Overall, your essential monthly expenses might include:
Then, rent or housing costs
Moreover, basic groceries
Additionally, utilities
Furthermore, notably, essential transportation
Finally, insurance premiums
Additionally, minimum debt payments
Specifically, essential medical expenses
Finally, next, first, for example, other necessary household costs
However, for example, if your essential expenses are $1,500 per month and you decide that your initial target is three months of essential expenses:
$1,500 × 3 = $4,500
In fact, notably, your target would therefore be $4,500 for a three-month emergency reserve.
In fact, this is only an example. Specifically, your actual target should reflect your own circumstances rather than blindly copying someone else’s number.
Start Small If You Cannot Save Thousands: Complete Guide to 7 rules of personal finance
Particularly, as a result, one of the biggest mistakes beginners make is believing that an emergency fund is useless unless they can immediately save several months of expenses.
Moreover, that mindset can prevent people from starting at all.
If your income is limited, begin with an amount that is realistic for you. In addition, even a small reserve can be useful when an unexpected expense appears.
Additionally, for example, you could create milestones such as:
Then, next, first goal: build your first small emergency buffer.
Consequently, second goal: cover one common unexpected expense.
Then, third goal: build one month of essential expenses.
However, long-term goal: gradually increase the fund toward several months of essential expenses.
Furthermore, notably, the important principle is progress. However, your emergency fund does not have to be perfect on day one.
Where Should You Keep Your Emergency Fund?: Complete Guide to 7 rules of personal finance
Specifically, an emergency fund should be safe, accessible, and separated enough from everyday spending that you are not tempted to use it for unnecessary purchases.
A dedicated savings or bank account can make the purpose of the money clearer. The best place will depend on your country, available accounts, access requirements, fees, and applicable protections.
Additionally, the CFPB recommends considering safety and accessibility when deciding where to keep emergency savings.
Keep Your Emergency Fund Separate From Everyday Spending: Complete Guide to 7 rules of personal finance
If your emergency money sits in the same account you use for shopping, entertainment, subscriptions, and daily spending, it can become very easy to spend it without realizing it.
A simple system is:
Everyday money: regular bills and daily expenses.
Emergency money: unexpected and necessary expenses only.
Goal-based savings: planned purchases and short-term goals.
Investment money: long-term wealth-building.
Moreover, for example, this separation makes the purpose of each dollar easier to understand and reduces accidental spending.
What Counts as a Financial Emergency?: Complete Guide to 7 rules of personal finance
Consequently, for example, not every unexpected purchase is an emergency. A useful test is to ask three questions:
Additionally, was the expense genuinely unexpected?
Furthermore, in fact, is it necessary or financially important?
Finally, can the expense reasonably wait until it can be paid from normal income?
Furthermore, next, unexpected loss or reduction of income
Additionally, essential emergency travel
Then, other major unplanned expenses that you cannot postpone
What Should You NOT Use an Emergency Fund For?: Complete Guide to 7 rules of personal finance
Consequently, an emergency fund should not become a general-purpose spending account.
However, it is usually better not to use emergency savings for:
A new phone when your current phone works
Additionally, for example, shopping during a sale
Furthermore, planned vacations
Consequently, entertainment
Finally, luxury purchases
However, regular monthly bills that you already knew about
Specifically, investments that you simply want to make
However, planned expenses should normally have their own savings category instead of being taken from your emergency reserve.
Emergency Fund vs. Therefore, regular Savings: What Is the Difference?: Complete Guide to 7 rules of personal finance
Therefore, regular savings and emergency savings both involve putting money aside, but they serve different purposes.
Emergency Fund
Regular Savings
Unexpected financial problems
Planned future expenses
Medical emergency or urgent repair
Vacation or new phone
Unexpected income loss
Planned purchase
Used only when necessary
Used according to your savings goal
In fact, keeping these purposes separate helps you avoid spending your emergency reserve on expenses that could have been planned for in advance.
How Can You Build an Emergency Fund on a Low Income?: Complete Guide to 7 rules of personal finance
In fact, building emergency savings on a low income can be difficult, but the strategy does not have to be complicated.
Moreover, start by choosing a small amount that you can consistently save. It could be a fixed amount from every paycheck or a percentage of your income.
Particularly, for example, if you can comfortably save $25 from each paycheck, do not dismiss it because it seems small. In fact, consistency turns small contributions into a growing financial buffer.
Moreover, notably, you can also direct occasional extra money toward the fund, such as bonuses, gifts, refunds, or income from temporary work, while still keeping enough money available for your essential needs.
Overall, the CFPB also recommends starting with what you can afford and building the emergency fund over time rather than waiting until you can save a large amount at once.
What If Your Income Is Irregular?: Complete Guide to 7 rules of personal finance
If your income changes from month to month, an emergency fund becomes even more useful because your financial risk is different from someone with a highly predictable paycheck.
Instead of depending on a fixed monthly savings amount, you can use a flexible system:
Finally, first, in fact, save a minimum amount during low-income months.
Specifically, next, save more during stronger-income months.
Moreover, send part of unexpected extra income to your emergency fund.
Then, protect the fund from unnecessary withdrawals.
If your income is irregular, you can also learn more about creating a survival budget and managing variable income in your related guide:
Should You Build an Emergency Fund Before Investing?: Complete Guide to 7 rules of personal finance
Additionally, for many beginners, building at least an initial emergency buffer before taking significant investment risk can make the overall financial system more stable.
Overall, notably, the reason is simple: investments are designed for longer-term goals and can fluctuate in value. An emergency fund is designed for money you may need unexpectedly and should therefore prioritize accessibility and stability.
Furthermore, notably, as a result, for example, this does not mean every person must stop investing completely until they reach a large emergency-fund target. Particularly, your decision should consider your income, debt, financial responsibilities, and risk tolerance.
Additionally, the key principle is to avoid putting money into investments that you may suddenly need for an emergency.
What Should You Do If You Have to Use Your Emergency Fund?: Complete Guide to 7 rules of personal finance
Consequently, using your emergency fund does not mean you failed.
Furthermore, that is exactly what the fund is designed for.
If a genuine emergency happens and you need to use the money, focus first on solving the emergency. In fact, after the situation is under control, make rebuilding your emergency fund your next financial priority.
However, for example:
Emergency → Use the fund → Stabilize your finances → Rebuild the fund → Return to normal saving and investing.
Specifically, the CFPB specifically recommends rebuilding emergency savings after you have used it for an unexpected expense.
Common Emergency Fund Mistakes Beginners Make: Complete Guide to 7 rules of personal finance
1. Overall, waiting Until You Can Save a Large Amount
In fact, waiting for the perfect income level can delay your emergency savings for years. Notably, start with what is realistic today.
2. Moreover, keeping the Money Too Easy to Spend
If emergency savings are mixed with everyday spending money, you may accidentally treat them as available spending money.
3. Additionally, using the Fund for Wants
A discount, vacation, gadget, or entertainment purchase is not automatically an emergency just because it was unexpected.
4. Furthermore, never Rebuilding the Fund
Specifically, as a result, for example, after using emergency savings, some people simply continue with their normal budget. That leaves them exposed to the next unexpected expense.
5. Overall, copying Someone Else’s Target
Moreover, your emergency-fund requirement depends on your own expenses, income stability, responsibilities, and financial situation. A target that works for one household may be too small or unnecessarily large for another.
A Simple Emergency Fund Building System: Complete Guide to 7 rules of personal finance
Consequently, you can turn the rule into a simple system instead of relying on motivation.
Calculate essential monthly expenses.
Choose your first realistic savings milestone.
Create a separate place for emergency savings.
Automate or schedule contributions when possible.
Add extra money when your income allows.
Use the fund only for genuine emergencies.
Rebuild it after every major withdrawal.
Review the target whenever your income or responsibilities change.
In addition, notably, automatic transfers can make saving easier because the money is moved before you have an opportunity to spend it. FDIC consumer guidance also highlights automatic transfers as a practical way to build savings over time.
A Practical Example: Building an Emergency Fund Step by Step: Complete Guide to 7 rules of personal finance
However, imagine a beginner has essential monthly expenses of $1,200.
Instead of thinking, “I need thousands of dollars immediately,” the person can create milestones.
Phase 1 (Starter Buffer): Build a small starter buffer.
Step 2 (Expense Buffer): Increase the fund until it can handle a common unexpected expense.
Milestone 3 (1-Month Target): Reach one month of essential expenses.
Goal 4 (Full Safety Net): Continue building toward several months of essential expenses.
Additionally, this approach makes a large financial goal feel more achievable because you are focusing on the next milestone rather than the entire journey at once.
Emergency Fund Quick Checklist
Specifically, first, directly know my essential monthly expenses.
Then, first, next, make sure you have a separate emergency savings location.
Then, always have chosen a realistic first savings target.
Additionally, ensure you contribute regularly, even if the amount is small.
Furthermore, clearly know what qualifies as an emergency.
Finally, consistently avoid using emergency savings for wants.
Specifically, proactively increase my target when my financial responsibilities increase.
Additionally, next, first, regularly rebuild the fund after using it.
Key Takeaway
Therefore, an emergency fund is not about predicting exactly when something will go wrong. It is about preparing before something goes wrong.
In fact, for example, the strongest approach is to start with an amount you can realistically save, keep the money accessible and separate from everyday spending, use it only for genuine emergencies, and gradually increase the reserve as your financial situation improves.
Particularly, once you have a basic financial safety net, the next rule becomes important: protecting that progress by managing debt carefully and avoiding financial decisions that can push you backward.
Rule 3: Pay Off High-Interest Debt
Consequently, one of the most important rules of personal finance is to control and pay off high-interest debt. For example, debt itself is not always bad, but expensive debt can quietly consume your income and make it much harder to save, invest, or build financial security.
If a large part of your monthly income goes toward interest and debt payments, you have less money available for your future. That is why understanding which debt deserves the most attention is an essential part of personal finance for beginners.
Why High-Interest Debt Can Hold You Back
Moreover, imagine you have ₹50,000 of debt carrying a very high interest rate. Consequently, even if you make regular payments, a significant portion of your money may go toward interest instead of reducing the amount you originally borrowed.
However, this creates a cycle:
Debt → Interest → Higher payments → Less money available for saving → More dependence on credit.
Overall, the problem becomes even worse when you continue borrowing while trying to repay the old debt.
In fact, paying expensive debt down can therefore improve your monthly cash flow and give you more control over your money.
Not All Debt Is the Same
A common beginner mistake is treating every type of debt as equally dangerous.
Instead, look at three things:
Interest rate: How expensive is the debt?
Balance: How much do you still owe?
Purpose: What did the borrowed money pay for?
Additionally, notably, high-interest consumer debt generally deserves more urgent attention because the cost of carrying it can grow quickly.
Moreover, lower-cost debt used for an important long-term purpose may require a different strategy. The right decision depends on the interest rate, repayment terms, your cash flow, and your overall financial situation.
Find Your Most Expensive Debt First
⚠️ Must-Read Guide (2026)
16 min read
Flat vs Reducing Interest Rate: Why 10% Flat Rate Is Actually 18%+ Real APR
Before converting any credit card purchase into EMIs or signing a personal loan agreement, learn how flat interest secretly charges interest on money you already paid back. See real ₹2,00,000 calculation proof and RBI rules.
Furthermore, as a result, make a simple list of everything you owe.
Debt
Balance
Interest Rate
Priority
Credit card
₹40,000
High
High
Personal loan
₹80,000
Medium
Medium
Lower-rate loan
₹2,00,000
Lower
Lower
Additionally, notably, this simple comparison can reveal where your money is being lost most quickly.
Furthermore, do not choose a repayment strategy based only on the size of the balance. A smaller debt with a much higher interest rate can sometimes be costing you more than a larger, lower-rate debt.
Two Popular Ways to Pay Off Debt
Additionally, once you know which debts you have, two common approaches are the debt avalanche and the debt snowball.
Debt Avalanche
Specifically, with the avalanche method, you continue making required payments on all debts while directing extra money toward the debt with the highest interest rate.
Specifically, for example, for example, after that debt is cleared, you move the extra payment toward the next-highest-rate debt.
Best suited for: people who want to focus primarily on reducing interest costs.
Debt Snowball
Consequently, with the snowball method, you continue required payments on all debts but direct extra money toward the smallest balance first.
Consequently, once that debt disappears, you move the payment toward the next-smallest balance.
Best suited for: people who benefit from quick psychological wins and visible progress.
In addition, neither method is automatically perfect for everyone. The most useful strategy is the one you can consistently follow while meeting all required payments.
Never Ignore Minimum Payments
While aggressively paying one debt, do not simply stop paying your other debts.
However, your repayment system should first protect you from missed payments, penalties, and additional financial damage. Then any extra amount can be directed toward your priority debt.
A simple system is:
Pay required amounts on all debts → Choose one priority debt → Put extra money toward it → Clear it → Move to the next.
Should You Stop Saving While Paying Debt?
However, this is where many beginners make an extreme decision.
In fact, they either ignore debt completely while investing, or they put every available rupee into debt and keep absolutely no emergency savings.
A more balanced approach is often better.
Therefore, try to maintain at least a basic emergency buffer while aggressively dealing with expensive debt. Otherwise, one unexpected expense could force you to borrow again and undo your progress.
Moreover, your exact balance between debt repayment and saving depends on the interest rate, income stability, emergency needs, and financial responsibilities.
Stop the Debt From Coming Back
In fact, paying off debt is only half the solution.
If the behaviour that created the debt continues, the balance can return.
Before using credit for a purchase, ask:
Additionally, notably, can I afford this from my current income?
Furthermore, is this purchase necessary?
Additionally, am I borrowing because I genuinely need it or because I want it immediately?
Finally, will the repayment make next month’s budget harder?
If you repeatedly use debt to cover normal living expenses, the underlying problem may be that your spending is too high compared with your income. In that situation, return to the reasons you may be struggling to save money and identify the root cause instead of treating every new loan as a separate problem.
A Simple Debt-Payoff Plan
List every debt with its balance, interest rate, and required payment.
Protect your required payments so you do not create additional problems.
Choose one priority debt using the avalanche or snowball approach.
Put extra money toward that debt whenever your budget allows.
Avoid taking new unnecessary debt while paying the old debt.
Move the freed-up payment toward your next financial priority after the debt is cleared.
Quick Debt Checklist
Then, next, directly know exactly how much I owe.
Then, make sure you know the interest rate on each debt.
Additionally, always make all required payments on time.
Furthermore, ensure you have chosen a debt-payoff strategy.
Finally, clearly am prioritising expensive debt.
Specifically, consistently am avoiding unnecessary new borrowing.
Additionally, first, proactively have a plan for the money freed after a debt is cleared.
Key Takeaway
Particularly, notably, debt becomes dangerous when its cost prevents you from moving forward financially. The goal is not simply to become debt-free as quickly as possible at any cost. The goal is to reduce expensive debt while protecting your basic financial stability.
Moreover, know what you owe, understand the interest you are paying, choose a repayment strategy, and prevent unnecessary new debt from replacing the old debt.
Know your debt → Prioritise expensive debt → Pay consistently → Avoid new unnecessary borrowing → Redirect the freed-up money.
Rule 4: Save and Invest for Your Future
Additionally, saving money gives you financial stability today, but saving and investing for the future helps you prepare for tomorrow.
Overall, this is where personal finance starts moving beyond simply “spending less.” Once your basic expenses are under control and expensive debt is being managed, you need a plan for the money you want to keep for future goals.
Additionally, for example, for example, notably, for example, you do not need to become an investing expert overnight. As a beginner, the first goal is to understand why you are saving, when you will need the money, and how much risk you can realistically handle.
Saving and Investing Are Not the Same Thing
Consequently, as a result, saving and investing are connected, but they serve different purposes.
Saving
Investing
Usually for short-term or near-term needs
Usually for longer-term goals
Focuses more on safety and accessibility
Focuses on potential long-term growth
Useful for emergencies and planned expenses
Useful for long-term wealth-building
Generally lower risk
Can involve market risk
Consequently, for example, money you may need next month should not normally be treated the same way as money you do not expect to need for many years.
Additionally, that simple difference can prevent a common beginner mistake: putting short-term money into something that can fluctuate significantly when you actually need it.
Give Every Saving Goal a Purpose
Instead of simply saying, “I want to save more money,” give your savings a specific job.
However, you might have separate goals for:
Specifically, for example, emergency expenses
Furthermore, next, first, upcoming purchases
Consequently, education or skill development
Then, next, travel
However, major household expenses
Then, long-term financial independence
A goal becomes easier to act on when you know how much you need and when you need it.
Furthermore, for example, if you want ₹24,000 for a purchase in 12 months:
₹24,000 ÷ 12 = ₹2,000 per month
In fact, now “save ₹24,000” becomes a simple monthly target of ₹2,000.
Start Investing Only After Understanding the Basics
Specifically, investing can help your money grow over long periods, but it is not a guaranteed way to make money quickly.
Moreover, different investments have different levels of risk. The value of market-linked investments can rise and fall, sometimes significantly.
In addition, for example, that is why beginners should avoid choosing an investment simply because someone online says it will give high returns.
Before investing, understand at least these four things:
What are you investing in?
What risks are involved?
How long can you keep the money invested?
What fees or costs are involved?
SEBI’s investor education resources also emphasize understanding investments and their risks before making investment decisions.
In addition, imagine you need ₹50,000 in six months for an important expense. Consequently, taking substantial market risk with that money may not make sense because you have very little time to recover if the investment falls.
Additionally, now imagine you are investing money for a goal that is decades away. You have much more time to handle short-term market fluctuations.
So instead of asking:
“Which investment gives the highest return?”
However, start with:
“When will I need this money, and how much risk can I afford?”
Therefore, for example, that is a much healthier starting point for a beginner.
Use Compounding to Your Advantage
In fact, one reason people invest for the long term is the potential effect of compounding.
Consequently, compounding means that returns can themselves generate returns over time. The longer money remains invested and the more consistently you contribute, the more important this effect can become.
Particularly, for example, suppose you invest ₹2,000 every month for many years. You are not only contributing your own money; over time, investment growth can also contribute to the value of the portfolio.
However, the exact result will depend on the investment, returns, fees, taxes, and market conditions. However, there is no guaranteed return.
Moreover, the important lesson is simple:
Time can be one of an investor’s biggest advantages.
Do Not Wait for the “Perfect” Time to Start
In fact, many beginners keep waiting.
“I will start when my salary increases.”
“Many believe they will invest after Regularly understand everything.”
“Others assume they will start next year.”
Learning before investing is good. But waiting forever for perfect conditions can become another form of procrastination.
Overall, you do not need to know everything before beginning your financial education. Therefore, start by understanding basic concepts, building good money habits, and making decisions that match your situation.
What If You Can Only Invest a Small Amount?
Moreover, do not compare your beginning with someone else’s portfolio.
If you can invest only ₹500 or ₹1,000 per month right now, that does not make your effort meaningless.
However, notably, your first goal is to build the habit of consistently setting money aside while improving your income and financial knowledge.
Therefore, as a result, notably, as your income grows, your contribution can grow too.
Additionally, the bigger mistake is not starting small. It is believing that small amounts do not matter and therefore never developing the habit at all.
Don’t Invest Money You May Need Soon
Additionally, this is one of the simplest rules beginners can remember.
If money has an important short-term job, keep its risk appropriate to that job.
Furthermore, for example:
Additionally, in fact, emergency money → prioritise safety and accessibility.
Moreover, long-term goal money → consider suitable long-term investments after understanding the risks.
Specifically, for example, this separation makes your financial system much easier to manage because every pool of money has a clear purpose.
A Simple Saving and Investing System
In fact, for example, you do not need a complicated portfolio or dozens of financial products.
Consequently, start with a simple sequence:
Control your monthly spending.
Build an emergency buffer.
Deal with expensive debt.
Define your financial goals.
Decide when you will need each goal’s money.
Choose saving or investing according to the goal and risk.
Contribute consistently and review your plan periodically.
Consequently, the point is not to create the most complicated financial system. The point is to create one you can actually maintain.
Common Mistakes Beginners Make
1. As a result, chasing High Returns
A higher potential return usually comes with higher risk. “High return with no risk” should immediately make you cautious.
2. Particularly, investing Without an Emergency Buffer
If every unexpected expense forces you to sell investments, your long-term plan can become difficult to maintain.
3. Moreover, copying Someone Else’s Portfolio
Another person’s income, goals, age, responsibilities, and risk tolerance may be completely different from yours.
4. Additionally, constantly Switching Investments
However, changing investments every time you hear a new prediction can turn long-term investing into emotional decision-making.
5. In addition, notably, ignoring Fees and Taxes
In addition, returns are not the only thing that matters. As a result, costs and taxes can affect the amount of money you actually keep.
Quick Checklist
Additionally, directly have clear financial goals.
Furthermore, make sure you know when I will need the money for each goal.
Finally, always understand the difference between saving and investing.
Specifically, ensure you understand the basic risks of what Clearly am investing in.
Finally, first, consistently am not investing emergency money unnecessarily.
Specifically, next, proactively am investing according to my time horizon.
Then, regularly am focusing on consistency rather than quick profits.
Additionally, directly review my financial plan when my circumstances change.
Key Takeaway
In fact, saving protects your financial stability, while appropriate long-term investing can help your money work toward future goals.
However, you do not need a huge salary or a complicated investment strategy to begin. Specifically, start with clear goals, understand your risk, keep short-term money appropriately safe, and build the habit of putting money aside consistently.
Save for near-term needs → Protect your emergency fund → Understand risk → Invest for appropriate long-term goals → Stay consistent.
Rule 5: Set Clear Financial Goals
Moreover, saving money without knowing why you are saving can make personal finance feel frustrating. You may put money aside every month, but after a while you may still wonder, “What am I actually working toward?”
Therefore, that is why the fifth rule of personal finance is to set clear financial goals.
A financial goal gives your money a direction. Instead of simply trying to “save more,” you know what the money is for, how much you need, and when you want to reach it.
Turn “I Want to Save Money” Into a Real Goal
In fact, notably, compare these two statements:
Goal A: “I want to save more money.”
Goal B: “I want to save ₹60,000 for an emergency fund within the next 12 months.”
Particularly, goal B is much easier to act on because it gives you three important pieces of information:
What: ₹60,000
Why: Emergency fund
When: 12 months
Additionally, once a goal becomes specific, you can turn it into a monthly plan.
₹60,000 ÷ 12 months = ₹5,000 per month.
Moreover, now you are no longer simply “trying to save.” You have a measurable target.
Use Three Time Horizons
Overall, for example, you do not need dozens of financial goals. A simple way to organise them is to divide them into three time horizons.
Particularly, notably, this separation matters because money needed soon should generally be managed differently from money you do not expect to need for many years.
Consequently, it also prevents a common mistake: treating every financial goal as if it has the same deadline and the same risk requirements.
Give Your Goals a Number and a Deadline
A goal becomes much more useful when you can measure it.
Moreover, as a result, for every important goal, write down:
Target amount
Target date
Current amount
Monthly contribution
Priority
However, for example:
Goal
Target
Deadline
Monthly Amount
Emergency fund
₹60,000
12 months
₹5,000
Education
₹36,000
12 months
₹3,000
Vacation
₹24,000
12 months
₹2,000
Additionally, now your money has a job instead of simply sitting inside a vague “savings” category.
Not Every Goal Should Be a Priority
In fact, this is where real-life personal finance becomes important.
Furthermore, you may want to build an emergency fund, buy a new phone, invest for retirement, repay debt, travel, and save for education—all at the same time.
But your income may not be large enough to fully fund everything simultaneously.
Moreover, that is okay.
Instead of trying to do everything at once, rank your goals.
A simple priority order could be:
Essential financial stability
Emergency protection
Expensive debt reduction
Important short- and medium-term goals
Long-term wealth-building
Optional lifestyle goals
Specifically, your exact order can change depending on your circumstances. Furthermore, someone with expensive debt may need a different priority from someone who has stable income and no significant debt.
Use the “Why” Behind the Goal
A number alone may not keep you motivated.
Overall, for example, notably, knowing why the goal matters to you can make it easier to stay consistent.
Consequently, for example:
“I want ₹50,000” is just a number.
“I want ₹50,000 so that an unexpected expense does not force me to borrow money” has a clear purpose.
Additionally, the second version connects the financial target with a real problem you want to solve.
When you feel tempted to spend the money unnecessarily, that purpose can remind you what you are working toward.
Break Big Goals Into Small Wins
A ₹5 lakh goal can feel overwhelming when you look at the entire number.
However, for example, each milestone gives you something measurable to celebrate.
Therefore, this is particularly useful when the final goal may take several years. You do not need to mentally carry the entire target every day. Specifically, focus on the next milestone.
What If Your Income Is Too Small for Your Goals?
Consequently, this is a situation many beginners face.
In fact, you calculate your goals and realise that the required monthly amount is higher than what you can realistically save.
However, for example:
Required monthly saving = ₹10,000
Affordable monthly saving = ₹4,000
Particularly, that does not mean the goal is impossible.
In fact, you have several options:
Finally, extend the deadline.
Specifically, notably, reduce the target amount.
Furthermore, first, temporarily lower the priority of another goal.
Additionally, reduce unnecessary expenses.
Finally, next, look for ways to increase income.
Then, for example, combine several of these approaches.
A realistic goal that takes longer is usually better than an unrealistic goal that makes you give up after two months.
Keep Planned Goals Separate From Emergency Money
Moreover, suppose you are saving for a vacation and also building an emergency fund.
If you keep both amounts in one mental bucket, it becomes easy to spend emergency money on the vacation—or postpone your emergency savings because the vacation feels more exciting.
Moreover, give different goals different names and, where practical, separate them into different savings categories or accounts.
Overall, this simple separation makes it easier to see what money is actually available for each purpose.
Review Your Goals When Your Life Changes
A financial goal is not a contract that can never change.
Consequently, notably, notably, notably, your income may increase. For example, your expenses may change. You may get married, move to another city, change jobs, start a business, or take on new responsibilities.
When your situation changes, your goals should be reviewed too.
A good habit is to review your major financial goals periodically and ask:
Additionally, is this goal still important?
Consequently, has the target amount changed?
Furthermore, is the deadline still realistic?
However, am I contributing enough?
Finally, has another goal become more important?
In addition, as a result, as a result, changing a goal does not mean you failed. It means your financial plan is adapting to your actual life.
A Simple Goal-Setting System
Additionally, you can turn this entire rule into a simple five-step process:
Choose the goal. Decide exactly what you want your money to accomplish.
Put a number on it. Estimate the amount you will need.
Choose a deadline. Decide when you want to reach it.
Calculate the monthly contribution. Divide the required amount by the available time, while adjusting for your current savings.
Review and adjust. Increase, decrease, or extend the plan when your circumstances change.
Additionally, for example:
Goal: ₹1,20,000
Current savings: ₹20,000
Remaining: ₹1,00,000
Time: 20 months
Required average contribution: ₹5,000 per month
Furthermore, for example, now the goal is no longer abstract. You know exactly what needs to happen.
Quick Goal-Setting Checklist
Specifically, make sure you know what Always am saving or investing for.
Furthermore, first, first, each important goal has a target amount.
Finally, next, next, each goal has a realistic deadline.
Then, ensure you know how much I need to contribute regularly.
Additionally, clearly have prioritised my goals.
Furthermore, consistently have separated emergency money from planned spending.
Finally, proactively review my goals when my circumstances change.
Key Takeaway
Specifically, money becomes easier to manage when it has a clear destination.
Consequently, you do not need twenty different financial goals. Consequently, start with the goals that matter most, give each one a number and a deadline, and turn the large target into smaller monthly actions.
Choose the goal → Give it a number → Set a deadline → Prioritise it → Take small consistent steps → Review and adjust.
Additionally, for example, the next step is to make sure your financial plan does not depend only on your current income. That brings us to Rule 6: Increase Your Income and Protect Your Financial Progress.
Rule 6: Increase Your Income and Protect Your Financial Progress
However, there is a limit to how much you can improve your finances by cutting expenses alone. You can cancel subscriptions, reduce unnecessary spending, and create a strict budget—but if your income stays too low while your responsibilities keep increasing, eventually you may feel stuck.
Consequently, that is why an important part of personal finance for beginners is learning how to increase your earning power while protecting the financial progress you have already made.
In fact, the goal is not simply to earn more money and then spend more money. The real goal is to create a gap between what you earn and what you need, then use that gap to build savings, reduce debt, and invest for the future.
Why Increasing Income Matters
In addition, imagine two people.
Person A earns ₹20,000 per month and spends ₹19,500.
Person B earns ₹40,000 per month and spends ₹25,000.
Moreover, person B has much more room to save, invest, handle emergencies, and work toward financial goals.
However, this does not mean earning more automatically makes someone financially successful. In addition, someone can earn ₹1 lakh and still spend ₹1.1 lakh. The important number is the gap between income and spending.
Income − Essential and controlled spending = Money available for financial progress
Therefore, notably, increasing that gap gives your financial plan more room to breathe.
Do Not Depend on Only One Income Strategy
When people hear “increase your income,” they often immediately think about starting a side hustle.
But there are several ways to improve your earning power:
Increase your main income: improve your skills, take on better responsibilities, negotiate when appropriate, or move toward better-paying work.
Add a second income stream: freelance work, services, digital products, or another legitimate source of income.
Monetise a useful skill: writing, design, programming, editing, research, teaching, or another skill people are willing to pay for.
Reduce income leaks: make sure money is not disappearing through unnecessary fees, poor financial decisions, or repeated avoidable expenses.
In fact, you do not need to pursue all of these at once. Choose the option that fits your current skills, available time, and situation.
Build Skills That Increase Your Earning Power
A useful long-term approach is to treat some of your time and money as an investment in your ability to earn more.
Additionally, for example, learning a skill that helps you qualify for better work can have a much larger long-term effect than saving a few hundred rupees by cutting every small expense.
Particularly, ask yourself:
Specifically, in fact, what skill could make me more valuable in my current work?
Specifically, first, what skill could help me move into a better-paying role?
Moreover, what service could I realistically offer to other people?
Then, first, next, what skill can I practise consistently with the time Regularly have available?
Moreover, for example, the best skill is not necessarily the trendiest one. It is the one you can actually learn, practise, demonstrate, and eventually use to create value.
Turn Extra Income Into Financial Progress
Overall, suppose your income increases by ₹10,000 per month.
Consequently, you now have a choice.
Furthermore, notably, you could increase your lifestyle by the full ₹10,000, or you could use part of the increase to improve your financial position.
However, for example:
₹3,000 → emergency savings
₹3,000 → debt repayment
₹2,000 → long-term investing
₹2,000 → lifestyle improvement
Specifically, as a result, the exact numbers do not matter. The principle does.
When income increases, do not automatically allow spending to increase by the same amount.
In fact, give your extra income a job before it disappears into lifestyle spending.
Watch Out for Lifestyle Inflation
Additionally, lifestyle inflation happens when your spending rises as your income rises.
Moreover, you get a raise, so you upgrade your phone. Then you move to a more expensive apartment. Then you start eating out more often. Soon your salary is higher, but your financial situation has barely improved.
Furthermore, this can create a frustrating situation where someone earns significantly more than before but still says:
“I don’t know where my money goes.”
Specifically, notably, you do not have to live exactly the same way forever. Therefore, enjoying some of your increased income is perfectly reasonable. The problem is allowing every income increase to become a permanent increase in expenses.
A useful rule is:
Let your lifestyle improve slower than your income.
However, for example, for example, that creates room for your savings, investments, and financial security to grow.
What If You Have Very Little Time?
Additionally, you do not need to create a complicated second business after working all day.
If your available time is limited, focus on one realistic improvement instead of trying five different income ideas simultaneously.
Consequently, for example:
Current situation: 1 hour available each evening.
Bad approach: Start freelancing, YouTube, blogging, trading, dropshipping, and five courses at the same time.
Better approach: Choose one skill, practise it consistently, create a few examples of your work, and gradually look for opportunities to earn from it.
In addition, for example, financial progress does not require doing everything. It requires doing the right things consistently.
Protect Your Higher Income
However, earning more is useful only if the additional money actually improves your financial position.
Consequently, once your income rises, protect the progress by keeping a simple system:
Increase your savings rate.
Pay down expensive debt.
Continue building your emergency reserve.
Invest appropriately for long-term goals.
Allow some money for enjoyment.
Therefore, this balance matters. A financial plan that gives you no room to enjoy your money can become so restrictive that you eventually abandon it.
A Simple Income-Growth Experiment
Instead of thinking about increasing your income as a huge life-changing project, try a 90-day experiment.
Initial Phase (Days 1–30): Identify one skill that could increase your earning potential and start learning or improving it.
Action Phase (Days 31–60): Practise the skill and create something that demonstrates what you can do.
Growth Phase (Days 61–90): Look for realistic opportunities to use that skill—additional work, freelance projects, clients, better job opportunities, or another legitimate route.
However, you may not double your income in 90 days. That is not the point.
In fact, the point is to create a repeatable process for increasing your earning ability instead of waiting for your income to magically improve.
When Your Income Increases, Ask These Questions
Before changing your lifestyle after a raise or new income source, stop for a moment and ask:
Then, notably, how much of this additional income will improve my financial security?
Additionally, do Directly have expensive debt that should receive more money?
Additionally, is my emergency fund strong enough?
Furthermore, what long-term goal could this money accelerate?
Finally, for example, how much can I enjoy without damaging my financial plan?
In fact, these questions help you enjoy progress without accidentally spending all of it.
Quick Checklist
Additionally, next, make sure you know how much money I earn each month.
Then, always know how much of my income is actually available after essential expenses.
Additionally, ensure you am working on at least one skill that can improve my earning power.
Furthermore, clearly am not depending entirely on lifestyle cuts to improve my finances.
Finally, consistently avoid automatically increasing my lifestyle whenever my income increases.
Specifically, proactively give extra income a specific purpose.
Finally, next, directly am focusing on one realistic income-growth opportunity at a time.
Key Takeaway
Particularly, cutting unnecessary expenses can help you create financial breathing room, but increasing your earning power can expand that room much further.
Moreover, the goal is not to chase money endlessly. It is to become more valuable, increase your income over time, and make sure that higher income actually improves your financial life.
Increase your skills → Increase your earning potential → Control lifestyle inflation → Give extra income a purpose → Build long-term financial strength.
Moreover, once your income, spending, saving, and investing systems are working together, the final rule is about bringing everything into one simple financial system you can maintain for years.
Rule 7: Create a Simple Financial System and Review It Regularly
Overall, notably, knowing the rules of personal finance is useful, but knowing them is not enough. The real difference comes from turning those rules into a system that works in your everyday life.
Consequently, notably, you can know how to budget, save, invest, manage debt, and increase your income—but if all of these things are happening randomly, your money can still feel difficult to control.
Additionally, the seventh and final rule is therefore simple: create a financial system you can actually follow and review it regularly.
Put Your Money on a Simple Path
In addition, as a result, think of your personal finances as a series of steps rather than seven completely separate rules.
Earn → Plan → Spend → Save → Protect → Invest → Review → Improve
Additionally, for example, each part has a job.
Earn: Bring money into your financial system.
Plan: Decide where your money needs to go.
Spend: Cover your needs without consistently spending more than you earn.
Save: Build money for emergencies and planned goals.
Protect: Reduce the damage unexpected events can cause.
Invest: Put appropriate long-term money to work according to your goals and risk.
Review: Check what is working and what is not.
Improve: Make small changes as your income, expenses, and goals change.
Furthermore, this is much easier to maintain than trying to remember dozens of financial rules every day.
Give Every Part of Your Income a Job
When money comes into your account, you should have a basic idea of where it needs to go before you start spending it.
Consequently, for example, your monthly income might be divided between:
Specifically, essential living expenses
Consequently, debt payments
Then, first, emergency savings
However, financial goals
Additionally, next, long-term investing
Then, in fact, personal and entertainment spending
Specifically, the exact percentages will depend on your income and circumstances. In fact, there is no universal formula that works perfectly for everyone.
However, the important idea is to give your money a purpose before your spending decides its purpose for you.
Automate What You Can
However, for example, one of the easiest ways to make a financial system easier is to remove unnecessary decisions.
If you know that you want to save ₹3,000 every month, you can arrange an automatic transfer when your bank or financial service allows it.
Instead of thinking every month, “Should I save this month?” the system helps make saving part of your normal routine.
In fact, the same principle can apply to recurring bill payments and other predictable financial commitments.
Consequently, automation does not replace financial awareness. You still need to check your accounts and make sure the amounts are appropriate.
Use a Weekly Money Check
Moreover, you do not need to spend hours analysing your finances every day.
A short weekly check can be enough to catch problems before they become bigger.
In addition, once a week, look at:
Additionally, how much money you spent
Whether any unusual expense appeared
Moreover, your upcoming bills
Furthermore, your current account balance
Whether you stayed within your spending plan
However, notably, this is not about judging yourself for every small purchase. It is about staying aware.
If you notice that you spent too much in one category, you can adjust early instead of discovering the problem at the end of the month.
Do a Deeper Monthly Review
Therefore, your weekly check keeps you aware. In addition, your monthly review helps you make decisions.
At the end of each month, ask yourself:
Finally, notably, did Make sure you spend more or less than I earned?
Specifically, did my savings increase?
Additionally, did my debt decrease?
Furthermore, first, did Always invest according to my plan?
Finally, next, for example, did an unexpected expense change my budget?
Then, which spending category needs attention?
Consequently, what worked well this month?
Additionally, what should I change next month?
Additionally, keep the review simple. You are looking for patterns, not trying to create a complicated financial report.
Use a One-Page Personal Finance Dashboard
If you want to make your system even easier, keep your most important numbers in one place.
Metric
What to Track
Monthly income
Money coming in
Essential expenses
Money required for basic living
Debt
Total outstanding balance
Emergency fund
Current emergency savings
Financial goals
Progress toward important targets
Investments
Long-term portfolio value and contributions
Net worth
Assets minus liabilities
In fact, you do not need to check investment values every day. The purpose of a dashboard is to understand your overall direction.
Measure Progress With Net Worth, Not Just Income
A higher salary is useful, but income alone does not tell you whether your financial situation is improving.
Particularly, for example, consider two people who both earn ₹50,000 per month.
Moreover, one has ₹5 lakh in savings and investments with manageable debt. The other has large debt and almost no savings.
Consequently, their incomes are identical, but their financial positions are very different.
Overall, this is why tracking net worth can be useful.
Net worth = Total assets − Total liabilities
However, assets can include savings, investments, and other things of financial value. Moreover, liabilities are amounts you owe.
Therefore, notably, your net worth does not need to increase every single month. Overall, markets fluctuate and life creates unexpected expenses. What matters is the long-term direction and whether your financial decisions are improving your position over time.
Make Your Financial System Flexible
A good financial system should not collapse because one month goes badly.
In fact, maybe your income is lower than expected. However, maybe your phone breaks. As a result, maybe you have an urgent family expense. Additionally, maybe your work situation changes.
In fact, as a result, your plan should have enough flexibility to handle real life.
Moreover, for example, during a difficult month you may temporarily reduce optional spending or investing contributions while protecting essential expenses and required debt payments.
When your situation improves, you can return to your normal plan.
Flexibility is not failure. It is part of a realistic financial system.
Protect the Progress You Have Built
Additionally, as your finances improve, protecting that progress becomes increasingly important.
Furthermore, notably, that can mean maintaining an emergency fund, avoiding unnecessary high-cost debt, using appropriate insurance where relevant, keeping important financial documents organised, and being careful about scams or unrealistic investment promises.
Specifically, investor.gov, the U.S. Therefore, securities and Exchange Commission’s investor education website, also provides resources on avoiding investment fraud and making informed investment decisions.
Additionally, the specific protections you need will depend on your country and personal circumstances, so treat this as a general principle rather than a one-size-fits-all checklist.
Build a Financial Routine You Can Maintain
Particularly, for example, you do not need to think about money constantly.
A simple routine might look like this:
On Every Payday: Check income, move planned savings, and cover important obligations.
During Weekly Reviews: Review spending and upcoming expenses.
At Monthly Check-ins: Review savings, debt, goals, and cash flow.
On Quarterly Audits: Review your financial goals and make adjustments.
Once a year: Take a broader look at your income, expenses, investments, insurance, debt, and long-term goals.
Consequently, for example, this routine turns personal finance from something you constantly worry about into something you manage systematically.
What to Do When You Make a Financial Mistake
In addition, you will probably make some.
Consequently, you may overspend one month. You may buy something you later regret. Specifically, sometimes you might choose an investment that does not work out as expected. Occasionally you could miss a savings target.
However, the important thing is not to turn one mistake into a permanent habit.
Instead, ask:
However, what happened?
Furthermore, why did it happen?
Finally, in fact, was there a weakness in my system?
Specifically, what can I change so it is less likely to happen again?
However, for example, if you repeatedly overspend because you use your main account for both bills and entertainment, the solution may not be “I need more discipline.” A better solution might be to separate spending money from money reserved for important obligations.
Good financial systems reduce the amount of willpower you need.
Put All Seven Rules Together
Therefore, now the seven rules can work as one system:
Spend less than you earn so you create financial breathing room.
Build an emergency fund so unexpected expenses do not immediately destroy your budget.
Pay off high-interest debt so expensive interest does not keep consuming your income.
Save and invest for the future so your money can support long-term goals.
Set clear financial goals so you know what your money is working toward.
Increase your income and protect your progress so your financial capacity can grow.
Create a simple financial system and review it regularly so all the other rules continue working together.
In fact, notice that these rules are connected.
In fact, spending less creates room. That room helps you build an emergency fund. A stronger emergency fund reduces the need for expensive debt. For example, lower debt gives you more money for goals and investing. In fact, increasing your income can accelerate the entire process. In addition, regular reviews keep the system from falling apart when life changes.
Your Complete Personal Finance Routine
If you are a beginner and all of this feels like a lot, do not try to change everything tomorrow.
Moreover, start with the basics:
Moreover, know your monthly income.
Specifically, first, know where your money is going.
Specifically, first, next, notably, spend less than you earn whenever possible.
Then, build an emergency buffer.
Additionally, control expensive debt.
Additionally, set specific financial goals.
Furthermore, for example, learn before investing.
Finally, work on increasing your earning power.
Consequently, review your money regularly.
Then improve one part at a time.
Particularly, your financial life does not need to become perfect. It needs to become more organised, more intentional, and more resilient over time.
Final Checklist: Are You Following the 7 Rules?
Specifically, first, next, ensure you spend less than I earn or have a clear plan to fix the gap.
Then, clearly am building an emergency fund.
Additionally, consistently know what debts I owe and which ones are expensive.
I save and invest according to my goals and risk.
Furthermore, my important financial goals have amounts and deadlines.
Finally, proactively am working on increasing my earning potential.
Specifically, regularly review my finances regularly.
First, next, first, directly adjust my plan when my circumstances change.
Then, next, make sure you focus on progress instead of trying to become financially perfect.
Final Takeaway
Moreover, notably, the seven rules of personal finance are not seven separate tricks for becoming rich. However, they are a framework for making better decisions with the money you have today while building a stronger financial future.
Overall, you do not need a high salary to start. You do not need to understand every investment product. And you do not need to change your entire life overnight.
Additionally, start with one improvement. Then build the next one on top of it.
Earn → Spend intentionally → Save → Protect → Reduce expensive debt → Invest appropriately → Increase your income → Review → Repeat.
Moreover, notably, that is how personal finance becomes a system rather than a collection of random money tips.
Actionable Insights and Smart Advice for 7 rules of personal finance
Overall, as a result, for example, the 7 rules of personal finance are to spend less than you earn, build an emergency fund, manage expensive debt, save and invest for the future, set clear financial goals, increase your income, and create a simple financial system that you review regularly. Particularly, together, these rules help you manage your money and build long-term financial stability.
What is the most important rule of personal finance for beginners?
Additionally, for beginners, one of the most important rules is to spend less than you earn. This creates financial breathing room that you can use to build an emergency fund, reduce expensive debt, save for important goals, and invest appropriately for the future.
Practical Steps & Actionable Tips for 7 rules of personal finance
How can I start managing my money if Always have a low income?
If you have a low income, start by understanding exactly how much you earn and where your money goes. In fact, focus on essential expenses, avoid unnecessary debt, build a small emergency buffer, and set realistic savings goals. At the same time, work on developing skills or finding opportunities that can gradually increase your income.
How can I build good financial habits and become financially stable?
Consequently, build good financial habits by creating a simple system instead of relying only on willpower. Particularly, track your spending, save regularly, set specific financial goals, manage debt, invest according to your goals and risk, and review your finances regularly. In fact, consistent small improvements can gradually strengthen your financial position.
Actionable Advice and Practical Tips for 7 rules of personal finance
conclusion
Furthermore, personal finance does not have to be complicated. The 7 rules of personal finance give you a simple framework to take control of your money: spend less than you earn, build an emergency fund, manage expensive debt, save and invest for the future, set clear financial goals, increase your income, and review your financial system regularly.You do not need a high income or a perfect financial plan to start. Overall, begin with the problem that matters most right now and improve one part of your finances at a time.The goal is not to become financially perfect overnight. It is to build better money habits, protect yourself from financial setbacks, and gradually create more freedom and stability.Start small, stay consistent, and let your financial system improve as your income, goals, and life change.
Hi, Ensure you am Asif Khan, founder and lead research editor at PaisaKmao.de. Overall, notably, over the past 3 to 4 years of active personal finance research and real-money investing in Indian markets, Clearly have navigated the practical realities of building an investment portfolio from scratch—from starting with small student pocket money, learning from early market mistakes (penny stocks, dividend tax surprises, and hidden DP charges), to establishing disciplined SIPs in low-cost index funds and managing risk. My mission with PaisaKmao.de is to provide 100% transparent, math-backed financial guides and practical calculators so young investors can build long-term wealth without falling into common traps.
Written & Researched by Asif Khan
Written & Researched by Asif Khan
Founder & Lead Financial Editor PaisaKmao.de
Furthermore, over 4 years of active personal finance research in Indian markets. Focused on transparent, math-backed guides to help students and young professionals build wealth and manage money smartly.
Learning the essential principles of personal finance for beginners is critical for anyone looking to build healthy money habits, avoid debt traps, and make smart financial decisions in India.
Learning the essential principles of personal finance for beginners is critical for anyone looking to build healthy money habits, avoid debt traps, and make smart financial decisions in India.
Learning the essential principles of personal finance for beginners is critical for anyone looking to build healthy money habits, avoid debt traps, and make smart financial decisions in India.
Learning the essential principles of personal finance for beginners is critical for anyone looking to build healthy money habits, avoid debt traps, and make smart financial decisions in India.
Learning the essential principles of personal finance for beginners is critical for anyone looking to build healthy money habits, avoid debt traps, and make smart financial decisions in India.
Additionally, managing money can feel confusing when you are just starting. You may earn money but still wonder where it goes, struggle to save consistently, or feel unsure about budgeting, debt, emergency funds, and investing.
Additionally, for verified statutory guidelines and official regulatory protections, refer directly to the Reserve Bank of India (RBI).
Essential Overview: Guide to personal finance for beginners
Additionally, the good news is that personal finance does not have to be complicated. You do not need a high income, advanced financial knowledge, or a perfect plan to begin. You only need to understand your current situation, make a few practical decisions, and build better money habits over time.
Furthermore, for example, this Personal Finance for Beginners guide will help you understand the essential steps needed to take control of your money. You will learn how to track your income and expenses, create a realistic budget, build savings, prepare for emergencies, manage debt, and start investing according to your financial goals.
In this guide, we will break everything down into 10 practical steps. Furthermore, each step includes clear explanations, realistic examples, and simple actions you can apply in your daily life. Whether you are a student, a beginner, a salaried employee, or someone trying to improve your financial situation, this guide will help you build a stronger financial foundation and create a clear plan for your money in 2026.
Practical Steps & Actionable Tips for personal finance for beginners
Step 1: Understand Your Current Financial Situation: Complete Guide to personal finance for beginners
Before creating a budget, building an emergency fund, paying off debt, or investing, you need to understand where you currently stand with your money. Furthermore, many people know their monthly salary, but they do not know exactly where that money goes. Moreover, they may feel that they are always short of money, even when their income seems reasonable.
Consequently, for personal finance beginners, understanding your current financial situation is the foundation of good money management. You do not need advanced financial knowledge, expensive software, or complicated calculations. A notebook, a spreadsheet, your bank statements, and your UPI transaction history are enough to begin.
Furthermore, for example, your goal is not to judge yourself or feel guilty about past spending. The goal is to understand your financial reality. Overall, once you know how much you earn, spend, save, and owe, you can create a financial plan that fits your actual life instead of following advice that may not work for your situation.
However, start by reviewing these five areas:
First, first, first, first, your monthly income
Moreover, your regular and flexible expenses
Next, next, next, next, your savings and emergency money
Then, notably, your loans and other debts
Additionally, your monthly cash flow
SEBI explains that documenting income and expenses can help people understand their financial position, control spending, manage debt, save money, and work toward financial goals. You can read its official guide on financial goals and budgeting for additional financial education.
1. Consequently, calculate Your Actual Monthly Income: Complete Guide to personal finance for beginners
Consequently, the first step is to calculate the money you actually receive during a normal month. As a result, include your salary, wages, freelance income, business income, commissions, part-time earnings, rental income, or other regular sources.
If you have a fixed job, use your take-home income, not only the salary written in your employment agreement. Additionally, take-home income is the amount that actually reaches your bank account after deductions.
In fact, for example, if your monthly salary is ₹30,000 but ₹2,000 is deducted before payment, your usable monthly income is ₹28,000. In addition, your budget should be based on ₹28,000 because that is the amount available for expenses, savings, and financial goals.
Income Source
Monthly Amount
Salary
₹25,000
Part-time work
₹3,000
Freelance work
₹2,000
Total Monthly Income
₹30,000
If your income changes every month, do not create your financial plan using your highest-income month. Specifically, review your income from the previous three to six months and calculate a realistic average. You can also use your lowest normal monthly income as a safer starting point for essential expenses.
If your earnings are irregular, read our detailed guide on how to budget with an irregular income. It explains how to calculate a minimum income level, prioritize essential expenses, and manage months when earnings are lower.
2. For example, track Your Monthly Expenses Before Creating a Budget: Complete Guide to personal finance for beginners
⚠️ Must-Read Guide (2026)
16 min read
Flat vs Reducing Interest Rate: Why 10% Flat Rate Is Actually 18%+ Real APR
Before converting any credit card purchase into EMIs or signing a personal loan agreement, learn how flat interest secretly charges interest on money you already paid back. See real ₹2,00,000 calculation proof and RBI rules.
In addition, after calculating your income, review where your money is going. Do not depend only on memory because small expenses are easy to forget. A ₹100 snack, a ₹200 online purchase, or several small UPI payments may not seem important individually, but together they can affect your monthly savings.
Moreover, review your bank statements, UPI history, cash spending, and recurring payments. Specifically, record what you actually spent—not what you think you should have spent. An honest record gives you a useful starting point for improving your financial habits.
A practical way to organize expenses is to divide them into three groups.
Essential Expenses
Additionally, rent or housing
Furthermore, groceries and basic food
Finally, for example, electricity, phone, and internet bills
Specifically, transport
Consequently, healthcare and medicines
Then, first, education expenses
Financial Commitments
However, loan EMIs
Additionally, next, credit-card payments
Then, in fact, insurance premiums
Additionally, other required payments
Flexible Expenses
Moreover, eating out
Furthermore, entertainment
Finally, notably, online shopping
Specifically, subscriptions
Additionally, impulse purchases
Furthermore, first, optional lifestyle spending
However, you do not have to remove every flexible expense. The purpose of expense tracking is to understand your choices and identify spending that does not provide enough value. A good personal budget should be realistic and sustainable, not so restrictive that you abandon it after a few weeks.
SEBI’s official guide on managing income and expenses also recommends listing income sources, categorizing expenses, tracking spending, and allocating money toward savings and investments.
If you receive a regular salary, our Day 1 to Day 30 salary management plan can help you organize your income after payday and divide money between bills, savings, goals, and personal spending.
3. In addition, calculate Your Monthly Cash Flow: Complete Guide to personal finance for beginners
Therefore, notably, your monthly cash flow shows whether you are earning more than you spend. It is one of the simplest ways to understand your current financial health.
Monthly Cash Flow = Total Monthly Income − Total Monthly Expenses
Financial Item
Amount
Total monthly income
₹30,000
Essential expenses
₹17,000
Loan payments
₹4,000
Flexible expenses
₹5,000
Money Remaining
₹4,000
In this example, ₹4,000 remains after all monthly expenses. This amount could be used for savings, an emergency fund, additional debt repayment, investing, or another financial goal.
If your result is negative, it means your expenses are higher than your income. This is not a reason to panic. It is a signal that your current money system needs adjustment. You may need to reduce avoidable expenses, review recurring payments, increase income, or change the order of your financial priorities.
In fact, do not try to fix everything at once. However, first, identify the largest reason for the negative cash flow. A single change—such as reducing an unnecessary recurring expense—may be more useful than making many small changes that are difficult to maintain.
4. Therefore, review Your Savings and Emergency Fund: Complete Guide to personal finance for beginners
Additionally, next, calculate how much money you have saved and how much is available for unexpected expenses. In fact, include money in your savings account, a separate emergency fund, or another easily accessible account.
Particularly, ask yourself:
Finally, next, for example, how much money can I access quickly if an emergency occurs?
Then, could I pay for an urgent medical bill or necessary repair?
Consequently, how many months of essential expenses could my savings cover?
Additionally, is my emergency money separate from my everyday spending money?
Actionable Insights and Smart Advice for personal finance for beginners
Moreover, for example, for example, if your essential monthly expenses are ₹15,000 and you have ₹30,000 in accessible savings, your savings could cover approximately two months of essential expenses.
Overall, an emergency fund is generally meant for unexpected costs, such as urgent repairs, medical expenses, or a temporary loss of income. The amount you need depends on your income stability, responsibilities, expenses, and personal situation. The Consumer Financial Protection Bureau’s emergency-fund guide explains why emergency savings can reduce the need to depend on loans or credit when an unexpected expense occurs.
If you are starting from zero, you do not need to save a large amount immediately. You could begin with ₹500 or ₹1,000 per month and increase the amount when your income allows. Particularly, small, consistent savings can still create a useful financial cushion over time.
Consequently, for practical ideas to create more room in your budget, read our guide on how to save money fast in 30 days. It includes realistic strategies for reducing unnecessary spending without making your daily life unnecessarily difficult.
5. In fact, list Your Debts and Monthly Payments: Complete Guide to personal finance for beginners
If you have a personal loan, education loan, credit-card balance, borrowed money, or another financial obligation, write down the details clearly. Overall, avoiding debt information may temporarily feel easier, but it makes financial planning more difficult.
Specifically, notably, for each debt, record:
However, total amount remaining
Furthermore, interest rate, if known
Finally, in fact, required monthly payment
Specifically, payment due date
Moreover, remaining repayment period
Debt
Amount Remaining
Monthly Payment
Personal loan
₹50,000
₹3,000
Credit-card balance
₹10,000
₹1,000
However, once you can see all your debts in one place, you can compare the balances, interest rates, and payment requirements. Notably, some people prefer paying the smallest debt first to build motivation, while others focus on higher-interest debt to reduce interest costs. The right approach depends on your financial situation and ability to make payments consistently.
Before taking a new loan, understand the total repayment responsibility, interest cost, fees, and repayment period. Moreover, borrowing can create long-term pressure if the monthly payment does not fit your income. For additional investor education, SEBI provides guidance on prioritizing needs, wants, and financial priorities.
6. Additionally, review Your Financial Habits and Spending Patterns: Complete Guide to personal finance for beginners
Additionally, for example, as a result, your financial numbers show what is happening, but your habits often explain why it is happening. Two people with similar incomes may have very different financial results because their spending, saving, and decision-making habits are different.
In fact, ask yourself:
Specifically, first, do I check my account balance before spending?
Then, first, next, notably, do I save at the beginning of the month or only save what is left?
Then, do Always make unplanned purchases because of discounts or social pressure?
Additionally, do Ensure you know how much Clearly spend on subscriptions?
Additionally, do Consistently review my finances regularly?
Furthermore, for example, do I compare prices before making a large purchase?
Additionally, good financial habits are usually built through small actions repeated over time. You do not need to change everything in one day. For example, reviewing your expenses every Sunday may help you notice problems before they become larger.
Moreover, students and young adults can also read our guide on financial habits every college student should develop. Furthermore, many of these habits can help beginners build a stronger relationship with money before taking bigger financial decisions.
7. Use Financial Tools Carefully: Complete Guide to personal finance for beginners
Furthermore, budgeting apps, expense trackers, banking tools, and AI-powered finance tools can help you organize expenses, monitor spending, set reminders, and understand financial information. However, a tool cannot automatically make the right financial decision for you. It should support your judgment, not replace it.
Before connecting an app to your financial accounts, review its privacy policy, permissions, security practices, and data-sharing rules. Overall, avoid entering sensitive banking information into tools that you do not trust.
To explore useful options, read our guide on the best AI tools to manage personal finances. For example, choose a tool based on your actual needs instead of downloading many apps that you may never use.
A Simple Real-Life Example: Complete Guide to personal finance for beginners
Specifically, notably, rahul earns ₹30,000 per month. He believes that he should be able to save ₹8,000, but his bank balance is almost empty before every payday.
Consequently, for example, after reviewing one month of transactions, Rahul discovers that ₹2,000 goes toward food delivery, ₹1,200 goes toward subscriptions he rarely uses, and ₹1,500 goes toward unplanned online purchases. Consequently, none of these expenses seemed very large on their own, but together they were reducing his ability to save.
Additionally, rahul does not remove every enjoyable expense. Instead, he cancels unused subscriptions, sets a monthly limit for food delivery, and waits 24 hours before making non-essential purchases. These changes improve his monthly cash flow without making his budget too restrictive.
Consequently, the lesson is simple: you cannot improve a financial problem until you understand what is causing it.
Common Mistake: Trying to Fix Everything at Once: Complete Guide to personal finance for beginners
A common mistake among personal finance beginners is trying to cut every expense, repay all debt, save a large amount, and start investing at the same time. This can create an unrealistic plan that is difficult to follow.
Instead, understand your current position first. Then choose one or two improvements that can make the biggest difference. For example, you could cancel one unused subscription, save ₹1,000 automatically, or pay an additional ₹500 toward a high-interest debt.
Step 1 Action Plan: Complete Guide to personal finance for beginners
Finally, calculate your actual monthly take-home income.
Consequently, review your bank statements, UPI history, and cash spending.
Specifically, track your expenses for at least 30 days.
However, separate essential expenses from flexible spending.
Additionally, next, first, calculate your monthly cash flow.
Then, next, in fact, write down your savings and available emergency money.
Then, list every debt and monthly payment.
Moreover, choose one financial habit to improve this month.
Quick Takeaway: Complete Guide to personal finance for beginners
In addition, for example, understanding your income, expenses, savings, debt, financial habits, and monthly cash flow gives you a strong foundation for managing money. You do not need to solve every financial problem today. Consequently, first, understand your starting point. However, once your numbers are clear, you can create realistic goals and build a financial plan that fits your actual situation.
However, now that you understand your current financial position, the next step is to create a realistic budget that helps you control spending, protect your priorities, and make steady progress toward your financial goals.
2. Therefore, build an Emergency Fund to Protect Your Financial Future: Complete Guide to personal finance for beginners
Consequently, life does not always follow your monthly budget. A sudden medical bill, phone repair, job loss, family emergency, or unexpected travel expense can create financial pressure without warning. That is why building an emergency fund is one of the most important personal finance tips for beginners in 2026.
FREE INTERACTIVE TOOL
Master Step 3: Automate Your Budget Allocation
Therefore, test your numbers with our 50/30/20 budget framework to balance current living with future wealth creation.
However, an emergency fund is money kept separately for genuine unexpected expenses. It is not money for shopping, entertainment, a planned vacation, or buying something just because it is on sale. Its main purpose is to give you financial breathing room when life becomes expensive unexpectedly.
According to the Consumer Financial Protection Bureau’s emergency fund guide, even a small amount of emergency savings can provide financial security and help people recover from unexpected expenses without immediately depending on credit or loans.
Why an Emergency Fund Matters in Personal Finance: Complete Guide to personal finance for beginners
In fact, imagine that Rahul earns ₹25,000 per month. He spends almost all of his income and keeps no money aside. One day, his phone suddenly stops working, and the repair costs ₹6,000. Because Rahul has no emergency savings, he may need to borrow money, use a credit card, or delay another important payment.
In fact, now imagine that Rahul had saved ₹500 every week. As a result, after several months, he would have built a useful financial cushion. The repair would still be inconvenient, but it would not automatically turn into debt.
Particularly, this is the real value of an emergency fund. It may not make you rich, but it can stop a small financial problem from becoming a much larger one.
How Much Should You Keep in an Emergency Fund?: Complete Guide to personal finance for beginners
Moreover, there is no single emergency-fund amount that is perfect for everyone. Particularly, your target should depend on your income, monthly essential expenses, job stability, family responsibilities, and how predictable your earnings are.
Financial Situation
Possible Emergency-Fund Goal
Student or beginner with limited income
Start with ₹5,000–₹10,000
Person with a stable monthly salary
Build 1–3 months of essential expenses
Freelancer or person with irregular income
Consider 3–6 months of essential expenses
Person supporting a family
Build a larger cushion based on responsibilities
Moreover, for example, if your essential monthly expenses are ₹15,000, you could first aim for ₹15,000. Moreover, after reaching that goal, you could gradually work toward ₹30,000 or more. You do not need to build the entire amount in one month.
If your income changes from month to month, your savings plan should also be flexible. You can learn a practical system for handling changing earnings in our guide on how to budget with an irregular income.
Start Small Instead of Waiting for the “Perfect Time”: Complete Guide to personal finance for beginners
Overall, notably, many people believe they must earn a high salary before they can start saving. In reality, waiting for the perfect income can delay the habit for years. A small and consistent contribution is often more useful than an ambitious plan that you stop after two weeks.
Additionally, save ₹20 or ₹50 whenever you receive money.
Furthermore, notably, set aside ₹100–₹500 every week if your budget allows.
Finally, save a percentage of extra income, bonuses, or freelance payments.
Additionally, increase your contribution when your income grows.
In addition, notably, for example, saving ₹50 per day could build approximately ₹1,500 in one month. Additionally, saving ₹500 per week could create around ₹26,000 in one year, before considering any interest. The amount may look small at first, but consistency creates momentum.
If saving feels difficult even when you earn a reasonable income, first identify where your money is quietly disappearing. Our article on why you can’t save money even with a good salary explains hidden spending patterns and practical ways to improve your savings.
Keep Your Emergency Money Separate: Complete Guide to personal finance for beginners
Additionally, keeping emergency money in the same account you use for daily spending can make it easier to spend accidentally. A separate savings account or another clearly labelled account can help create a mental boundary between everyday money and emergency money.
However, as a result, you could name the account “Emergency Fund” and avoid connecting it to routine shopping payments. The money should remain accessible when a genuine emergency happens, but it should not be so convenient that you spend it on ordinary wants.
Before choosing where to keep your emergency savings, consider three things:
Safety: The money should not be exposed to unnecessary risk.
Accessibility: You should be able to access it when a real emergency occurs.
Stability: The value should not fluctuate heavily when you may need the money soon.
Additionally, for example, emergency money is different from long-term investment money. In addition, notably, investments may rise or fall in value, while an emergency fund is designed primarily for financial stability and quick access.
Use Your Emergency Fund Only for Real Emergencies: Complete Guide to personal finance for beginners
Before withdrawing money, ask yourself:
“Is this expense unexpected, necessary, and difficult to manage without using my emergency savings?”
A sudden medical expense, urgent home repair, essential vehicle repair, or temporary loss of income may qualify. A planned holiday, new gadget, festival shopping, or a discount offer usually does not.
Furthermore, after using the fund, begin rebuilding it gradually. You do not need to replace the entire amount immediately. As a result, return to your normal saving routine and increase contributions when possible.
A Simple 30-Day Emergency-Fund Action Plan: Complete Guide to personal finance for beginners
Week
Action
Week 1
Calculate your essential monthly expenses.
Week 2
Open or choose a separate place for emergency savings.
Week 3
Save your first amount, even if it is only ₹100 or ₹500.
Week 4
Review your spending and choose a realistic monthly saving amount.
Consequently, for a broader step-by-step money system, you can also read our guide on financial planning for beginners. It explains how budgeting, saving, debt management, and long-term goals can work together.
Key Takeaway: Complete Guide to personal finance for beginners
Specifically, building an emergency fund is not about saving a huge amount overnight. It is about creating a financial safety net one small contribution at a time. Specifically, start with a realistic target, keep the money separate, use it only for genuine emergencies, and rebuild it after you use it.
However, among the most practical personal finance tips for beginners, this habit can reduce financial stress and help you avoid unnecessary debt when unexpected expenses appear.
Next: Once you have started building a financial safety net, the next step is to understand how to reduce expensive debt without damaging your monthly budget.
Step 3: Pay Off High-Interest Debt and Avoid Unnecessary Borrowing: Complete Guide to personal finance for beginners
Therefore, for example, debt can help you pay for an important need, such as education, a home, or an emergency. However, debt can become difficult to manage when monthly payments take a large part of your income or when high interest causes the total amount to grow over time.
In fact, for personal finance beginners, learning how to manage debt is an important part of building financial stability. The goal is not always to become debt-free overnight. The goal is to understand what you owe, make payments on time, reduce expensive debt strategically, and avoid borrowing for expenses you may not be able to afford.
Before choosing a repayment strategy, create a clear list of every loan, credit-card balance, EMI, or other amount you owe. When all your debt is visible in one place, it becomes easier to decide what to pay first and how much you can realistically contribute each month.
Understand the True Cost of Your Debt: Complete Guide to personal finance for beginners
Consequently, many people focus only on the monthly EMI. However, the EMI does not always show the complete cost of borrowing. You should also understand the interest rate, repayment period, processing fees, late-payment charges, and total amount you may repay.
Moreover, for example, two loans may have the same monthly payment but different interest rates or repayment periods. The loan with the higher interest rate may cost more over time, even if the monthly payment appears manageable.
Debt Type
Amount Remaining
Interest Rate
Minimum Monthly Payment
Credit-card balance
₹20,000
36% per year
₹2,000
Personal loan
₹50,000
16% per year
₹3,000
Education loan
₹1,50,000
9% per year
₹4,000
In this example, the credit-card balance has the highest interest rate. If all minimum payments are affordable and current, paying extra toward the highest-interest debt may reduce interest costs. However, your repayment plan should consider your complete financial situation.
Before borrowing, review the repayment responsibility carefully. SEBI’s official guide on thinking before you borrow money explains that borrowing creates financial responsibilities and should not be used for avoidable or unnecessary expenses.
Create a Complete Debt List: Complete Guide to personal finance for beginners
In addition, write down every debt in one place. Do not rely only on memory because it is easy to forget due dates, fees, or small balances.
However, notably, your debt list should include:
Specifically, the name of the lender
Additionally, first, the total amount remaining
Furthermore, next, the interest rate
Then, the minimum monthly payment
Additionally, the payment due date
Furthermore, the remaining repayment period
Finally, any late-payment fees or penalties
Therefore, once your list is complete, calculate the total amount you pay toward debt every month. Furthermore, compare that number with your monthly take-home income and essential expenses.
If you have not created a clear monthly spending plan yet, review Step 2: Create a Realistic Budget before increasing your debt payments. A repayment plan should fit your budget so that you can continue paying consistently.
Choose a Debt-Repayment Method: Complete Guide to personal finance for beginners
Additionally, two popular debt-repayment methods are the debt avalanche and the debt snowball. Specifically, both can work, but they focus on different priorities.
Method 1: The Debt Avalanche
In fact, with the debt avalanche method, you continue making the required minimum payments on all debts. Any extra money is directed toward the debt with the highest interest rate.
Particularly, for example, after the highest-interest debt is paid off, you move the extra payment to the debt with the next-highest interest rate.
Moreover, this method may reduce the total interest you pay over time. The Consumer Financial Protection Bureau’s debt-reduction guide describes the highest-interest-rate method as one of the main approaches people can use to reduce debt.
Method 2: The Debt Snowball
Consequently, with the debt snowball method, you continue making the required payments on all debts and direct extra money toward the smallest balance first.
Overall, after paying off the smallest debt, you add that payment amount to the next-smallest debt. This creates a series of small wins that may help some people stay motivated.
However, the debt snowball may not always minimize total interest, but motivation can be valuable if it helps you continue the repayment plan.
Method
Priority
Possible Benefit
Debt avalanche
Highest interest rate first
May reduce total interest costs
Debt snowball
Smallest balance first
May create faster motivational wins
In fact, notably, choose the method that you can follow consistently. A mathematically efficient plan is less useful if it is too difficult to maintain.
Always Pay Required Amounts on Time: Complete Guide to personal finance for beginners
In fact, even when you are focusing extra money on one debt, continue making the required payments on your other debts. For example, missing payments may result in late fees, additional interest, or other financial consequences.
Particularly, as a result, set reminders a few days before each due date. If your income arrives on a predictable schedule, you may also consider automatic payments, provided you keep enough money in your account.
RBI’s Financial Literacy Guide includes responsible borrowing and timely repayment as important financial education topics.
Do Not Borrow More While Paying Off Existing Debt: Complete Guide to personal finance for beginners
Moreover, it is difficult to reduce debt if new borrowing continues to replace the amount you repay. Before taking another loan or using credit for a non-essential purchase, ask yourself:
Specifically, for example, is this expense necessary?
Finally, first, can I wait and save for it instead?
Consequently, can I afford the monthly payment after paying essential expenses?
Specifically, next, what will the total borrowing cost be?
However, will this new payment make my current debt harder to manage?
A new loan may be appropriate for some important needs, but it should not be treated as free money. Consequently, every borrowed amount has a repayment responsibility.
SEBI also advises investors not to borrow money for securities-market investments. You can review its official investment dos and don’ts before making investment decisions.
Use Extra Income Strategically: Complete Guide to personal finance for beginners
If you receive a bonus, freelance payment, tax refund, or other extra income, you do not have to use all of it for debt. However, allocating a planned portion toward high-interest debt may help you reduce the balance faster.
Additionally, for example, imagine that you receive an extra ₹10,000:
Purpose
Amount
Emergency savings
₹3,000
Extra high-interest debt payment
₹5,000
Upcoming essential expense
₹2,000
Furthermore, notably, this is only an example. If you have no emergency savings, keeping some money available may help you avoid borrowing again when an unexpected expense occurs.
A Real-Life Debt Example: Complete Guide to personal finance for beginners
Additionally, arman has three debts: a ₹5,000 credit-card balance, a ₹20,000 personal loan, and a ₹40,000 education loan. He pays the required amount on each debt but has an additional ₹2,000 available every month.
Moreover, for example, using the debt avalanche method, Arman directs the extra ₹2,000 toward the debt with the highest interest rate while continuing the required payments on the other two debts. When the first debt is paid off, he adds its previous payment to the next priority.
Consequently, for example, using the debt snowball method, he would pay the smallest balance first. In addition, both approaches can create progress. The important part is that Arman has a clear plan and avoids adding unnecessary new debt.
Common Debt-Management Mistakes to Avoid: Complete Guide to personal finance for beginners
Then, looking only at the EMI and ignoring the interest rate
Additionally, in fact, taking a new loan to pay for avoidable expenses
Furthermore, missing due dates because payments are not tracked
Moreover, paying extra toward one debt while missing required payments on another
Finally, using new credit while trying to reduce existing debt
Specifically, notably, ignoring fees, penalties, and the total repayment cost
Furthermore, first, first, borrowing money to make high-risk investments
Step 3 Debt-Repayment Action Plan: Complete Guide to personal finance for beginners
Additionally, list every debt, balance, interest rate, and due date.
Finally, next, next, calculate your total required monthly debt payments.
Then, for example, make a realistic budget before increasing repayments.
Additionally, choose the debt avalanche or debt snowball method.
Consequently, continue making required payments on all debts.
Furthermore, direct extra money toward your chosen priority debt.
However, avoid unnecessary new borrowing.
Finally, review your progress once each month.
Quick Takeaway: Complete Guide to personal finance for beginners
In addition, managing debt is not only about paying money faster. It is about understanding interest costs, making payments on time, choosing a realistic strategy, and avoiding unnecessary borrowing.
Consequently, for personal finance beginners, a clear debt plan can reduce financial pressure and create more room for savings and future goals. Progress may be gradual, but consistent payments and better borrowing decisions can make a meaningful difference over time.
However, now that you have started protecting yourself with savings and managing expensive debt, the next step is to automate your savings and build consistent financial habits.
Step 3: Pay Off High-Interest Debt and Avoid Unnecessary Borrowing: Complete Guide to personal finance for beginners
However, debt can help you pay for an important need, such as education, a home, or an emergency. However, debt can become difficult to manage when monthly payments take a large part of your income or when high interest causes the total amount to grow over time.
Therefore, for personal finance beginners, learning how to manage debt is an important part of building financial stability. The goal is not always to become debt-free overnight. The goal is to understand what you owe, make payments on time, reduce expensive debt strategically, and avoid borrowing for expenses you may not be able to afford.
Before choosing a repayment strategy, create a clear list of every loan, credit-card balance, EMI, or other amount you owe. When all your debt is visible in one place, it becomes easier to decide what to pay first and how much you can realistically contribute each month.
Understand the True Cost of Your Debt: Complete Guide to personal finance for beginners
In fact, many people focus only on the monthly EMI. However, the EMI does not always show the complete cost of borrowing. You should also understand the interest rate, repayment period, processing fees, late-payment charges, and total amount you may repay.
In fact, for example, two loans may have the same monthly payment but different interest rates or repayment periods. The loan with the higher interest rate may cost more over time, even if the monthly payment appears manageable.
Debt Type
Amount Remaining
Interest Rate
Minimum Monthly Payment
Credit-card balance
₹20,000
36% per year
₹2,000
Personal loan
₹50,000
16% per year
₹3,000
Education loan
₹1,50,000
9% per year
₹4,000
In this example, the credit-card balance has the highest interest rate. If all minimum payments are affordable and current, paying extra toward the highest-interest debt may reduce interest costs. However, your repayment plan should consider your complete financial situation.
Before borrowing, review the repayment responsibility carefully. SEBI’s official guide on thinking before you borrow money explains that borrowing creates financial responsibilities and should not be used for avoidable or unnecessary expenses.
Create a Complete Debt List: Complete Guide to personal finance for beginners
Moreover, write down every debt in one place. Do not rely only on memory because it is easy to forget due dates, fees, or small balances.
Particularly, your debt list should include:
Specifically, the name of the lender
Then, first, the total amount remaining
Additionally, next, the interest rate
Then, the minimum monthly payment
Additionally, the payment due date
Furthermore, the remaining repayment period
Finally, in fact, any late-payment fees or penalties
Moreover, notably, once your list is complete, calculate the total amount you pay toward debt every month. Therefore, compare that number with your monthly take-home income and essential expenses.
If you have not created a clear monthly spending plan yet, review Step 2: Create a Realistic Budget before increasing your debt payments. A repayment plan should fit your budget so that you can continue paying consistently.
Choose a Debt-Repayment Method: Complete Guide to personal finance for beginners
Overall, two popular debt-repayment methods are the debt avalanche and the debt snowball. In fact, both can work, but they focus on different priorities.
Method 1: The Debt Avalanche
Additionally, with the debt avalanche method, you continue making the required minimum payments on all debts. Any extra money is directed toward the debt with the highest interest rate.
Overall, notably, after the highest-interest debt is paid off, you move the extra payment to the debt with the next-highest interest rate.
Furthermore, notably, as a result, for example, this method may reduce the total interest you pay over time. The Consumer Financial Protection Bureau’s debt-reduction guide describes the highest-interest-rate method as one of the main approaches people can use to reduce debt.
Method 2: The Debt Snowball
Additionally, with the debt snowball method, you continue making the required payments on all debts and direct extra money toward the smallest balance first.
Consequently, after paying off the smallest debt, you add that payment amount to the next-smallest debt. This creates a series of small wins that may help some people stay motivated.
Furthermore, the debt snowball may not always minimize total interest, but motivation can be valuable if it helps you continue the repayment plan.
Method
Priority
Possible Benefit
Debt avalanche
Highest interest rate first
May reduce total interest costs
Debt snowball
Smallest balance first
May create faster motivational wins
However, choose the method that you can follow consistently. A mathematically efficient plan is less useful if it is too difficult to maintain.
Always Pay Required Amounts on Time: Complete Guide to personal finance for beginners
Specifically, even when you are focusing extra money on one debt, continue making the required payments on your other debts. In addition, missing payments may result in late fees, additional interest, or other financial consequences.
In fact, set reminders a few days before each due date. If your income arrives on a predictable schedule, you may also consider automatic payments, provided you keep enough money in your account.
RBI’s Financial Literacy Guide includes responsible borrowing and timely repayment as important financial education topics.
Do Not Borrow More While Paying Off Existing Debt: Complete Guide to personal finance for beginners
Specifically, as a result, for example, it is difficult to reduce debt if new borrowing continues to replace the amount you repay. Before taking another loan or using credit for a non-essential purchase, ask yourself:
Specifically, is this expense necessary?
Moreover, can I wait and save for it instead?
Furthermore, first, can I afford the monthly payment after paying essential expenses?
Finally, next, notably, what will the total borrowing cost be?
Then, will this new payment make my current debt harder to manage?
A new loan may be appropriate for some important needs, but it should not be treated as free money. Moreover, every borrowed amount has a repayment responsibility.
SEBI also advises investors not to borrow money for securities-market investments. You can review its official investment dos and don’ts before making investment decisions.
Use Extra Income Strategically: Complete Guide to personal finance for beginners
If you receive a bonus, freelance payment, tax refund, or other extra income, you do not have to use all of it for debt. However, allocating a planned portion toward high-interest debt may help you reduce the balance faster.
Moreover, for example, imagine that you receive an extra ₹10,000:
Purpose
Amount
Emergency savings
₹3,000
Extra high-interest debt payment
₹5,000
Upcoming essential expense
₹2,000
Consequently, this is only an example. If you have no emergency savings, keeping some money available may help you avoid borrowing again when an unexpected expense occurs.
However, arman has three debts: a ₹5,000 credit-card balance, a ₹20,000 personal loan, and a ₹40,000 education loan. He pays the required amount on each debt but has an additional ₹2,000 available every month.
Additionally, using the debt avalanche method, Arman directs the extra ₹2,000 toward the debt with the highest interest rate while continuing the required payments on the other two debts. When the first debt is paid off, he adds its previous payment to the next priority.
Therefore, using the debt snowball method, he would pay the smallest balance first. Overall, both approaches can create progress. The important part is that Arman has a clear plan and avoids adding unnecessary new debt.
Common Debt-Management Mistakes to Avoid
Additionally, looking only at the EMI and ignoring the interest rate
Additionally, taking a new loan to pay for avoidable expenses
Furthermore, for example, missing due dates because payments are not tracked
Finally, paying extra toward one debt while missing required payments on another
Consequently, using new credit while trying to reduce existing debt
Specifically, ignoring fees, penalties, and the total repayment cost
However, borrowing money to make high-risk investments
Step 3 Debt-Repayment Action Plan
Specifically, first, list every debt, balance, interest rate, and due date.
Specifically, first, next, in fact, calculate your total required monthly debt payments.
Then, make a realistic budget before increasing repayments.
Moreover, choose the debt avalanche or debt snowball method.
Additionally, continue making required payments on all debts.
Furthermore, notably, direct extra money toward your chosen priority debt.
Finally, avoid unnecessary new borrowing.
Additionally, review your progress once each month.
Quick Takeaway
In fact, for example, managing debt is not only about paying money faster. It is about understanding interest costs, making payments on time, choosing a realistic strategy, and avoiding unnecessary borrowing.
Particularly, for personal finance beginners, a clear debt plan can reduce financial pressure and create more room for savings and future goals. However, progress may be gradual, but consistent payments and better borrowing decisions can make a meaningful difference over time.
Consequently, now that you have started protecting yourself with savings and managing expensive debt, the next step is to automate your savings and build consistent financial habits.
Step 4: Automate Your Savings and Investments for Consistent Growth
Moreover, creating a budget and building an emergency fund are important, but consistency is what turns good financial intentions into long-term progress. As a result, many people plan to save money every month, yet they wait until the end of the month and discover that very little is left. Additionally, automating your money can help solve this problem.
However, for personal finance beginners, automation means setting up a planned transfer so that a portion of your income moves toward savings or investments automatically. Instead of depending only on memory, motivation, or willpower, you create a system that supports your financial goals every time you receive money.
Overall, automation does not guarantee investment returns, and it does not replace financial planning. However, it can make saving more consistent and reduce the temptation to spend money that was intended for your future.
What Does Automating Your Finances Mean?
In fact, financial automation means using your bank, investment platform, or payment system to complete selected money tasks automatically on a fixed date.
Additionally, notably, for example, if you receive your salary on the 5th of every month, you could arrange:
₹1,000 to move into your emergency savings account on the 6th
₹2,000 to be invested through a planned investment contribution on the 7th
Specifically, your regular EMI or bill payment to be scheduled before its due date
Moreover, this approach follows a simple principle: save first and spend the remaining amount according to your budget. It is often easier than trying to save whatever remains after a month of spending.
Why Automation Can Improve Your Money Habits
Furthermore, as a result, people are busy, and financial tasks are easy to postpone. You may tell yourself that you will transfer money tomorrow, but an unexpected expense or an attractive purchase can change the plan.
Additionally, notably, automation reduces the number of decisions you need to make each month. Therefore, once the system is set up correctly, your planned contribution can happen without requiring repeated effort.
Manual Saving
Automated Saving
You must remember to transfer money
The transfer follows a scheduled date
Saving may be delayed
Saving can happen soon after income arrives
Spending may happen before saving
Money is assigned to goals earlier
Progress may depend heavily on motivation
A system supports consistency
Furthermore, automation is useful because it creates a repeatable process. However, you should still review your account balance and financial plan regularly. An automatic payment is helpful only when the amount and timing are appropriate for your income.
Start With a Small Automatic Savings Amount
Additionally, you do not need to automate a large amount immediately. Specifically, start with an amount that fits your current budget and does not make it difficult to pay essential expenses.
Specifically, for example, if your monthly income is ₹20,000, your first automated plan could look like this:
Financial Purpose
Monthly Amount
Transfer Date
Emergency fund
₹1,000
One day after income arrives
Long-term investment
₹2,000
Two days after income arrives
Future annual expenses
₹500
One day after income arrives
In this example, ₹3,500 is assigned to future goals. The remaining income can then be used for essential expenses, debt payments, and personal spending according to the budget.
If ₹3,500 is not affordable, start with ₹500 or ₹1,000. The purpose is to build a sustainable habit. You can increase the amount after reviewing your income and expenses.
Automate Savings Before Automating Investments
If you have no emergency savings and your financial situation is unstable, building a basic emergency fund may be more important than increasing investment contributions. For example, investment values can rise or fall, while emergency money is intended to remain available for unexpected essential expenses.
A practical order may be:
Then, first, next, first, for example, pay essential bills and required debt payments.
Then, next, build a basic emergency fund.
Consequently, automate regular savings.
Then, begin long-term investing according to your goals and risk tolerance.
However, increase contributions gradually as your financial position improves.
Specifically, for example, for example, for a complete beginner-friendly system, you can connect this section with your article on financial planning for beginners.
How Automatic Investment Contributions Work
In India, many investors use a Systematic Investment Plan, commonly called a SIP, to invest a fixed amount at regular intervals in a mutual fund. A SIP is a method of investing regularly; it does not guarantee profits or protect against market losses.
According to the Association of Mutual Funds in India (AMFI), a SIP allows investors to invest a fixed amount periodically. Before investing, understand the fund’s objective, risk level, costs, and whether it matches your financial goals.
Consequently, for example, someone may invest ₹2,000 per month through a SIP for a long-term goal. The investment amount remains fixed, but the value of the investment can move up or down depending on market performance.
If you are new to mutual funds, your article on best-performing FlexiCap funds can be linked here only if that is the exact working URL. Otherwise, search for the article inside WordPress and select the correct page before publishing.
Choose the Right Date for Automatic Transfers
Consequently, the timing of automation matters. In fact, setting a transfer date before your income arrives may cause a failed transaction or create pressure on your account balance.
A simple approach is to schedule savings one or two days after your salary, business income, or regular payment usually arrives.
In addition, for example:
Additionally, income arrives: 5th of the month
Furthermore, in fact, emergency-fund transfer: 6th
Finally, investment contribution: 7th
Moreover, bill and EMI payments: According to their due dates
Specifically, budget review: Last day of the month
If your income is irregular, avoid setting an automatic amount that could leave you short of money. You may prefer to transfer a percentage of each payment manually or automate a small base amount.
A Simple Automation Example
However, meera earns ₹30,000 per month. She wants to save and invest but usually spends most of her money before the month ends.
However, she creates the following system:
Purpose
Amount
Emergency savings
₹2,000
Long-term investment
₹3,000
Future expenses
₹1,000
In fact, every month, ₹6,000 is assigned automatically after she receives her income. She then manages the remaining ₹24,000 using her monthly budget.
Therefore, after three months, Meera reviews the plan. Because her essential expenses are under control, she increases her savings contribution by ₹500. She does not make a large change all at once; she improves the system gradually.
Review Automated Payments Regularly
Moreover, automation should not become “set it and forget it.” Your income, expenses, goals, and financial responsibilities may change.
In fact, review your automated transfers at least every three to six months and ask:
Additionally, first, notably, is the savings amount still affordable?
Furthermore, next, have my essential expenses increased?
Additionally, is my emergency fund progressing toward its target?
Then, does my investment still match my financial goal and risk tolerance?
Additionally, for example, have any automatic payments become unnecessary?
Furthermore, is there enough money in my account before each payment date?
Particularly, notably, the SEBI Investor Education portal provides educational information about investing and investor awareness. Before investing, understand the product instead of choosing it only because it is popular or has performed well recently.
Common Automation Mistakes to Avoid
Consequently, automating an amount that is too large for your budget
Finally, scheduling transfers before income usually arrives
However, ignoring account balances and payment failures
Specifically, investing emergency money in volatile assets
Finally, first, in fact, increasing investment contributions while high-interest debt remains unmanaged
Specifically, next, choosing an investment without understanding its risks
Moreover, never reviewing old automatic payments or subscriptions
Step 4: 15-Minute Automation Action Plan
Then, review your monthly income and essential expenses.
Additionally, notably, choose a realistic savings amount.
Furthermore, select a separate account for emergency savings.
Additionally, schedule the transfer one or two days after income arrives.
Finally, decide whether you are financially ready for long-term investing.
Specifically, for example, set up investment contributions only after understanding the risks and product.
Additionally, next, first, first, turn on transaction alerts and check that payments are successful.
Consequently, review the entire system every three to six months.
Key Takeaway
Moreover, automating savings and investments can make financial progress more consistent because it turns a good intention into a repeatable system. In addition, start with an affordable amount, protect your emergency savings, understand investment risks, and review your automatic payments regularly.
Additionally, for personal finance beginners, the goal is not to automate the largest possible amount. The goal is to create a sustainable financial system that supports your needs today while helping you prepare for future goals.
Next: After creating a consistent savings system, the next step is to diversify your investments and manage risk instead of depending too heavily on a single asset or investment.
Step 5: Diversify Your Investments and Manage Risk Wisely
Overall, after building an emergency fund, managing expensive debt, and creating a regular saving habit, you may begin thinking about long-term investing. However, investing all your money in one company, one sector, one fund, or one type of asset can create unnecessary risk.
Additionally, for example, for example, notably, for example, for personal finance beginners, diversification means spreading your investments instead of depending too heavily on a single investment. However, diversification cannot guarantee profits or prevent all losses, but it may reduce the damage if one investment performs poorly.
A strong investment plan is not only about finding the investment with the highest recent return. It should also consider your financial goals, time horizon, risk tolerance, emergency savings, existing debt, and the purpose of the money you are investing.
What Does Investment Diversification Mean?
Consequently, as a result, diversification is often explained with the phrase, “Do not put all your eggs in one basket.” In personal finance, this means avoiding excessive dependence on one company, industry, asset class, or investment idea.
Consequently, for example, imagine that Ravi invests his entire ₹1,00,000 in shares of only one company. If that company faces financial problems, the value of a large part of his investment may fall.
Additionally, now imagine that another investor spreads money across different investments based on their goals and risk capacity. If one investment performs poorly, the other investments may reduce the overall impact. This does not remove risk, but it can reduce concentration risk.
Highly Concentrated Portfolio
More Diversified Portfolio
Most money is invested in one company or asset
Money is spread across multiple investments
One poor investment may have a large impact
The effect of one investment may be reduced
Higher concentration risk
Risk may be spread across different areas
Returns depend heavily on one outcome
The portfolio is less dependent on one investment
However, the Investor.gov guide to diversification explains that diversification involves spreading investments among different assets to reduce the impact of a single investment on an overall portfolio.
Understand the Main Types of Investment Risk
Furthermore, investment risk is not only the possibility that prices may fall. Particularly, different investments can involve different risks, and understanding them can help you make more informed decisions.
Market risk: Investment values may rise or fall because of economic conditions, interest rates, company performance, or market sentiment.
Concentration risk: Too much money is invested in one company, sector, asset, or investment theme.
Liquidity risk: You may not be able to access your money quickly without selling at an unfavorable price.
Inflation risk: Your money may lose purchasing power if its growth does not keep up with rising prices.
Credit risk: A borrower or issuer may fail to make expected payments.
In fact, understanding these risks does not mean avoiding every investment. It means knowing what could happen before you commit your money.
Match Your Investments With Your Financial Goals
Before choosing an investment, decide what the money is for and when you may need it. In fact, money needed next year may require a different approach from money intended for a goal that is ten or twenty years away.
Financial Goal
Possible Time Horizon
Important Consideration
Emergency expense
Any time
Safety and quick access may be more important than growth
Course fee or planned purchase
1–2 years
Avoid taking unnecessary market risk with money needed soon
Buying a home
5–10 years
Consider the target date and your ability to handle investment changes
Long-term financial independence
10+ years
Long-term growth, risk, and diversification may become more relevant
Specifically, emergency savings should remain separate from long-term investments because you may need emergency money quickly. If you have not built an emergency fund yet, return to Step 2: Build an Emergency Fund and create a basic financial safety net first.
Moreover, for a broader money-management framework, you can also read our guide on Financial Planning for Beginners: 10 Simple Steps. It explains how budgeting, saving, debt management, financial goals, and investing can work together.
Understand Asset Allocation
In addition, for example, asset allocation means deciding how your investment money is divided among different investment categories. Particularly, there is no single allocation that is suitable for everyone.
Consequently, notably, your financial goals, income, responsibilities, time horizon, and ability to handle losses can affect the type of allocation that may be appropriate for you.
In addition, for educational purposes, a sample portfolio could look like this:
Investment Category
Example Allocation
Possible Purpose
Equity-oriented investments
50%
Long-term growth potential
Debt or fixed-income investments
30%
Potential stability and income
Cash or short-term savings
20%
Liquidity and near-term needs
Additionally, this is only an example for understanding asset allocation. It is not a recommended portfolio. In fact, your own allocation should be based on your financial goals, risk capacity, and time horizon.
Diversification Does Not Mean Buying Everything
However, some beginners believe that buying many investments automatically creates diversification. However, owning a large number of products does not always reduce risk.
Therefore, for example, for example, buying shares of ten companies from the same industry may still create concentration risk. Similarly, investing in several funds that hold many of the same companies may create more overlap than you expect.
Before adding a new investment, ask:
Then, next, next, what does this investment add to my portfolio?
However, does it hold many of the same assets I already own?
Then, does it support one of my financial goals?
Additionally, in fact, do Proactively understand its risks and costs?
Furthermore, am I buying it because of a clear plan or only because it recently performed well?
In fact, the goal is not to own the largest number of investments. The goal is to avoid unnecessary concentration while keeping your financial plan understandable.
Understand Mutual Funds Before Investing
Consequently, mutual funds may provide exposure to multiple securities through a single investment product. However, different funds have different objectives, risks, costs, investment styles, and portfolio holdings.
Before investing, read the scheme information, understand the investment objective, review the risk level, and check whether the fund matches your financial goal.
Particularly, the AMFI Investor Knowledge Centre provides educational information about mutual funds, investor awareness, and important investment concepts.
If you want to learn more about one mutual-fund category, read our detailed guide on Best Performing FlexiCap Funds. The article can help you understand what to examine beyond past returns, including investment strategy, risk, consistency, and long-term suitability.
A Practical Diversification Example
However, suppose Sana has ₹1,20,000 available. Before investing, she checks whether she has enough emergency savings, whether she has expensive debt, and when she may need the money.
Moreover, she realizes that she may need ₹20,000 within the next year and wants to keep ₹30,000 available for emergencies. Instead of investing the entire ₹1,20,000 in one company, she separates the money according to its purpose.
Financial Purpose
Example Amount
Emergency savings
₹30,000
Near-term planned expense
₹20,000
Long-term investment goal
₹70,000
In fact, this example shows that diversification is not only about dividing investments. It also includes separating emergency money, short-term goal money, and long-term investment money.
Review Your Investments Without Reacting Emotionally
Overall, investment prices may change every day. Overall, checking your portfolio constantly can increase stress and may encourage emotional decisions.
Instead, review your investments on a planned schedule, such as every six or twelve months, or when your financial goals change.
During a review, ask:
Moreover, does this investment still support my financial goal?
Finally, has my time horizon changed?
Specifically, notably, has my income or financial responsibility changed?
Then, first, has one investment become too large a part of my portfolio?
Additionally, do Regularly understand what I own?
Additionally, next, are the risks and costs still acceptable?
A review does not always mean buying or selling. Overall, notably, sometimes the correct action is to continue following a suitable long-term plan.
Use Reliable Investment Information
Moreover, investment decisions should not be based only on social-media trends, advertisements, or promises of guaranteed returns. Notably, check official information and understand the product before investing.
However, notably, the SEBI Investor Education portal provides investor-awareness information and educational resources. It can help beginners understand important investment concepts and recognize the need for informed decision-making.
If you are using digital tools to organize your financial information, read our guide on 10 Best AI Tools to Manage Your Personal Finances in 2026. These tools may help with budgeting, expense tracking, planning, and research, but important financial information should always be verified.
Common Diversification Mistakes to Avoid
Then, for example, investing all your money in one company or sector
Additionally, choosing investments only because of recent high returns
Consequently, copying another person’s portfolio without understanding it
Furthermore, investing emergency money in volatile assets
However, buying many funds without checking portfolio overlap
Finally, ignoring investment costs and risk information
Specifically, in fact, making decisions because of short-term market fear or excitement
Furthermore, first, assuming diversification guarantees profit or eliminates all losses
Step 5: Investment Diversification Action Plan
Moreover, write down your financial goals and target dates.
Finally, next, keep emergency savings separate from long-term investments.
Then, notably, review your current investments and identify concentration risk.
Additionally, check whether multiple investments hold similar assets.
Additionally, understand the purpose, risk, and cost of every investment.
Furthermore, choose an allocation based on your goals and risk capacity.
Finally, for example, avoid investing only because of recent returns or online trends.
Specifically, review your portfolio periodically instead of reacting to daily price changes.
Key Takeaway
Therefore, as a result, notably, diversification is a risk-management strategy, not a guarantee of profit. By spreading investments thoughtfully, matching them with your financial goals, and avoiding excessive dependence on one asset, you can build a more balanced financial plan.
Additionally, for personal finance beginners, the most important rule is to understand what you own and why you own it. Additionally, keep emergency money separate, invest according to your time horizon, and avoid making decisions based only on recent performance.
Next: After building a diversified investment approach, the next step is to improve your financial knowledge and stay informed without becoming overwhelmed by financial news, trends, or social-media advice.
Step 6: Improve Your Financial Knowledge and Stay Informed
Additionally, managing money is not only about earning, budgeting, saving, or investing. Furthermore, good financial decisions also depend on understanding how money works. Moreover, financial products, interest rates, investment options, technology, and economic conditions can change over time. That is why improving your financial knowledge can help you make more informed decisions and avoid costly mistakes.
Furthermore, for personal finance beginners, financial education does not mean becoming an accountant, economist, or investment expert. It means learning enough to understand your financial choices, compare options, recognize risks, ask useful questions, and avoid making decisions only because something is popular on social media.
Specifically, for example, you do not need to study finance for several hours every day. For example, even 20 to 30 minutes of focused learning each week can improve your understanding when you apply what you learn to your own income, expenses, savings, debt, investments, and financial goals.
Why Financial Knowledge Is Important
In fact, for example, many financial problems happen because people do not fully understand interest rates, loan terms, investment risks, fees, inflation, or the long-term effect of their decisions.
Consequently, for example, imagine that two people want to invest ₹2,000 every month. The first person invests because a social-media creator says that a particular investment will provide very high returns. The second person spends time learning about risk, diversification, investment time horizons, fees, and how the investment actually works.
Consequently, neither person can predict future returns. However, the second person is more likely to understand the possible benefits and risks before investing.
Learn the Most Important Personal Finance Topics First
In addition, there is a huge amount of financial information online. Consequently, trying to learn everything at once can create confusion. A better approach is to begin with the topics that directly affect your financial life.
Financial Topic
What You Should Learn
Why It Matters
Budgeting
Income, expenses, spending limits, and monthly planning
Helps you understand where your money goes
Saving
Emergency funds, savings goals, and consistent saving habits
Helps create financial security
Debt
Interest rates, EMIs, repayment periods, and borrowing costs
Helps you manage debt responsibly
Investing
Risk, return, diversification, time horizon, and fees
Helps you make informed long-term decisions
Financial Goals
Target amounts, deadlines, and monthly contributions
Gives your money a clear purpose
Credit
Payment history and responsible borrowing
Can affect future borrowing opportunities
In fact, start with the topic that is most important to your current situation. If you are struggling to save money, first learn about spending habits and budgeting. If you have expensive debt, understand interest costs and repayment strategies before focusing heavily on investing.
If you earn regularly but still struggle to save, read our detailed guide on why you can’t save money even with a good salary. It explains hidden spending patterns and practical ways to improve your saving habits.
Use Reliable Financial Sources Instead of Following Every Trend
However, social media can help you discover financial ideas, but short videos and viral posts often leave out important details. A person may show high investment returns without explaining the risks, fees, losses, taxes, or time involved.
Before acting on financial information, check whether the source is reliable and whether the information applies to your situation.
Moreover, ask these questions:
Consequently, who published this information?
Specifically, first, is the source a government agency, financial regulator, recognized institution, or qualified professional?
However, does the content explain risks as well as possible benefits?
Additionally, first, next, is the information current?
Then, in fact, is someone trying to sell a financial product?
Additionally, can the information be verified through another reliable source?
Therefore, for beginner investment education, Investor.gov’s introduction to investing explains important topics such as financial goals, risk, diversification, long-term investing, and the difference between saving and investing.
Use Financial Technology to Learn and Manage Money
In fact, notably, technology can make financial learning easier. Additionally, budgeting apps, expense trackers, calculators, banking tools, and AI-powered financial tools can help you organize information and understand your financial habits.
However, a tool should support your decisions rather than replace your judgment. Before sharing financial information with an app or AI tool, check its privacy policy, security practices, and the type of information it collects.
To explore useful tools in more detail, read our guide on 10 Best AI Tools to Manage Your Personal Finances in 2026. The article explains how different tools may help with budgeting, expense tracking, financial planning, and money management.
Particularly, financial tools can help you organize information, but they may not understand your complete financial situation. However, verify important information before making a major financial decision.
Understand an Investment Before You Put Money Into It
Additionally, one of the most useful financial habits is refusing to invest in something you do not understand. A product may have a professional-looking website, a popular name, or strong past returns, but those factors do not automatically make it suitable for your goals.
Before investing, try to answer these questions in simple language:
Moreover, what does this investment actually do?
Furthermore, how can it make or lose money?
Finally, notably, what are its main risks?
Specifically, how long may I need to keep my money invested?
Additionally, can I access the money quickly if necessary?
Furthermore, next, first, what fees or charges may apply?
Then, next, for example, does this investment match my financial goal and risk tolerance?
Moreover, the Investor.gov guide to investment options explains that different investments have different risks, potential returns, and characteristics. Therefore, understanding these factors can help investors make more informed decisions.
If you want to understand one mutual-fund category in greater detail, read our guide on Best Performing FlexiCap Funds. It explains important factors to evaluate beyond past returns, including investment strategy, risk, consistency, and long-term suitability.
Create a Simple Weekly Financial Learning Routine
Overall, for example, you do not need a complicated study plan. A small routine is easier to follow and becomes more valuable when you apply the lessons to your own finances.
Day
Learning Activity
Suggested Time
Monday
Read one reliable article about budgeting or saving
10 minutes
Wednesday
Learn one financial term, such as inflation or interest
10 minutes
Friday
Study one investment concept or financial risk
15 minutes
Sunday
Apply one lesson to your own financial plan
15 minutes
Particularly, notably, the most important part is application. Furthermore, reading about budgeting is useful, but reviewing your own spending is more practical. Particularly, learning about emergency funds is useful, but saving your first ₹100 or ₹500 turns knowledge into action.
Keep a Personal Finance Learning Notebook
Consequently, create a notebook, document, or digital note where you explain financial concepts in your own words. Moreover, avoid copying complicated definitions without understanding them.
Financial Concept
Simple Meaning
Personal Action
Emergency Fund
Money reserved for unexpected essential expenses
I will begin by saving ₹5,000
Interest Rate
The cost of borrowing or the return offered by some savings products
I will compare rates before borrowing
Diversification
Spreading investments to reduce dependence on one investment
I will avoid putting all my money into one company
Moreover, as a result, writing financial ideas in your own words can help you identify what you understand and what you need to learn further.
Learn From Your Own Financial Decisions
However, your monthly financial activity is also a learning opportunity. At the end of each month, review your decisions and look for useful patterns.
Additionally, ask yourself:
Then, where did Directly spend more than expected?
Consequently, did I save the amount I planned?
Additionally, did I borrow money? If yes, why?
However, which expense gave me real value?
Furthermore, which expense could I reduce next month?
Finally, in fact, did Make sure you make a financial decision without enough information?
In fact, for example, suppose you planned to spend ₹3,000 on food but spent ₹4,500. Instead of only saying that your budget failed, find the reason. Did prices increase? Did you order food more often? Did you forget to include an important expense?
Furthermore, the answer can help you create a more realistic financial plan next month.
A Practical Financial Learning Example
Moreover, arif wants to invest ₹3,000 every month. Before investing, he spends one week learning about risk, diversification, investment time horizons, and fees.
Specifically, he discovers that he may need part of the money within one year. Instead of investing the complete ₹3,000 without a plan, he separates his short-term needs from his long-term goals.
Financial Purpose
Monthly Amount
Short-term savings goal
₹1,000
Emergency savings
₹1,000
Long-term investment goal
₹1,000
Overall, for example, notably, the amounts are only examples. The important lesson is that financial knowledge helped Arif create a plan based on his own needs instead of copying someone else’s investment decision.
Common Financial Learning Mistakes to Avoid
Specifically, believing every viral financial video
Following investment tips without checking the source
Moreover, focusing only on returns and ignoring risk
Additionally, first, learning advanced investing before understanding budgeting
Furthermore, next, notably, buying a financial product without reading important information
Then, assuming past performance guarantees future results
Additionally, copying another person’s financial plan without considering your own goals
Additionally, reading financial content without applying anything to your own situation
Step 6: Financial Learning Action Plan
Furthermore, for example, choose one personal finance topic to study this week.
Finally, use an official or reliable educational source.
Consequently, learn the concept in simple language.
Specifically, write the main lesson in your own words.
However, check how the concept applies to your income, expenses, savings, or goals.
Finally, first, take one small action based on what you learned.
Specifically, next, in fact, review the result at the end of the month.
Then, continue learning without rushing into financial products.
Key Takeaway
Consequently, financial knowledge is not about memorizing complicated terms. It is about understanding how your money decisions affect your present and future.
Additionally, for personal finance beginners, learning the basics of budgeting, saving, debt, investing, risk, and financial goals can improve decision-making over time. Use reliable sources, question unrealistic promises, apply what you learn, and continue improving your financial knowledge step by step.
Next: After improving your financial knowledge, the next step is to use financial technology and digital money tools wisely while protecting your personal and financial information.
Step 7: Use Financial Technology and Money Tools Wisely
In addition, financial technology has made managing money faster and more convenient. Overall, today, you can check your bank balance, track expenses, pay bills, create a budget, invest, and monitor financial goals using a smartphone. However, technology is only useful when it helps you make better decisions instead of encouraging unnecessary spending or creating security risks.
However, for example, for personal finance beginners, financial tools can simplify money management by organizing financial information in one place. A budgeting app may show where your money goes, an expense tracker may help identify unnecessary spending, and an automated transfer can make saving more consistent.
However, no app can automatically create good financial habits. A tool can show that you spent too much, but you still need to decide what to change. Use technology as a support system—not as a replacement for financial knowledge and personal responsibility.
How Financial Technology Can Help You Manage Money
Therefore, different financial tools are designed for different purposes. You do not need to install every app. For example, notably, choose tools that solve a specific problem in your financial life.
Financial Tool
How It Can Help
What to Check
Banking App
Check balances, review transactions, transfer money, and pay bills
Security settings and transaction alerts
Budgeting App
Plan monthly income and expenses
Privacy policy and data access
Expense Tracker
Identify spending patterns
Accuracy and account permissions
Goal Tracker
Monitor progress toward savings goals
Whether the goals are realistic
Investment Platform
View investments and research products
Fees, risks, and regulatory information
AI Financial Tool
Organize information and explain financial concepts
Accuracy, privacy, and limitations
Consequently, the best financial tool is not always the one with the most features. It is the one you can understand, use consistently, and trust with your information.
Use Budgeting and Expense-Tracking Tools to Understand Your Spending
In fact, many people know their monthly income but cannot clearly explain where all their money goes. As a result, small expenses can become difficult to notice when they happen through digital payments.
However, an expense tracker can help you categorize spending, such as:
Moreover, rent or housing
Additionally, food and groceries
Furthermore, notably, transportation
Finally, mobile and internet bills
Additionally, entertainment
Specifically, shopping
Finally, first, first, for example, loan or EMI payments
Specifically, next, next, savings and investments
Particularly, for example, suppose your monthly income is ₹25,000. You believe that you spend only ₹2,000 on online shopping and food delivery. Consequently, after tracking your expenses for one month, you discover that the actual amount is ₹4,500.
In fact, the tool did not create the problem. It simply made the spending pattern visible. You can now decide whether reducing that category would help you save more.
If you are earning regularly but still struggle to save, read our guide on why you can’t save money even with a good salary. It explains hidden spending habits and practical ways to improve your savings.
Use Automation to Make Saving More Consistent
Moreover, automation can reduce the need to make the same financial decision every month. For example, you may schedule an automatic transfer to a savings account shortly after receiving your income.
Moreover, suppose you earn ₹30,000 per month and want to save ₹3,000. Instead of waiting until the end of the month to see what remains, you may automatically move ₹3,000 into savings after your income arrives.
Without Automation
With Automation
Save whatever remains at the end of the month
Move a planned amount soon after receiving income
Saving may be affected by unnecessary spending
Savings become part of the monthly system
Requires a new decision every month
Reduces repeated manual effort
Overall, automation should still be reviewed regularly. If your income changes or you have an unexpected expense, you may need to adjust the amount.
Use AI Tools as Financial Assistants, Not Financial Decision-Makers
AI tools can help explain financial terms, summarize information, create a basic budget template, organize expenses, compare general financial concepts, and generate questions for research.
Consequently, notably, notably, notably, for example, you can ask an AI tool:
“Help me create a monthly budget using an income of ₹25,000.”
“Explain the difference between saving and investing in simple language.”
“Create a checklist for comparing two financial products.”
“Help me identify possible unnecessary expenses from this spending list.”
However, AI-generated information can be incomplete, outdated, or incorrect. Do not treat an AI response as personalized financial advice. Furthermore, verify important information using official sources before making major decisions.
In addition, as a result, as a result, for a detailed overview, read our guide on 10 Best AI Tools to Manage Your Personal Finances in 2026. It explains how AI tools may support budgeting, expense tracking, financial planning, and money management.
Protect Your Financial Information
Additionally, convenience should not come at the cost of security. Specifically, financial apps may contain sensitive information, including account details, transaction history, personal information, and spending patterns.
Before installing or connecting a financial app, check what information it requests and why it needs that access.
Additionally, follow these basic security practices:
Consequently, use a strong and unique password for important financial accounts.
Then, enable two-factor authentication when available.
However, keep your phone and financial apps updated.
Additionally, do not share OTPs, passwords, PINs, or security codes.
Furthermore, in fact, avoid entering financial information on suspicious websites.
Finally, review app permissions before connecting bank accounts.
Moreover, turn on transaction alerts when available.
Specifically, log out of financial accounts on shared devices.
Check Privacy Before Connecting Your Financial Accounts
Specifically, some financial tools request permission to access account information or transaction data. Before approving access, read the privacy policy and understand what data the company collects, stores, shares, or uses.
Consequently, ask these questions:
Then, first, notably, what financial information will the app access?
Additionally, next, why does the app need this information?
Additionally, does the company explain how it protects user data?
Then, can you delete your data or close your account?
Additionally, for example, does the company share information with third parties?
Furthermore, can you use the tool without connecting your bank account?
Additionally, for example, do not connect an account only because an app promises convenience. The benefit should be worth the information you are sharing.
Use Investment Apps Carefully
However, investment apps can make buying and selling easier, but convenience may also encourage frequent decisions. Seeing prices change every minute can create fear or excitement and lead to emotional actions.
Before using an investment platform, understand:
Consequently, what investment products are available?
Finally, what fees or charges may apply?
However, what risks are involved?
Specifically, how quickly can you access your money?
Furthermore, first, in fact, is the platform regulated where required?
Finally, next, does the investment match your financial goal?
Consequently, the SEBI Investor Education portal provides educational information to help investors understand financial markets, investment risks, and informed decision-making.
Before selecting a mutual fund or investment category, you can also read our guide on Best Performing FlexiCap Funds. Consequently, past performance alone should not be the only factor in an investment decision.
A Practical Example: Creating a Simple Digital Money System
In fact, suppose Sameer earns ₹30,000 per month. He wants to improve his money management but does not want to use many different apps.
In addition, he creates a simple system:
Financial Activity
Tool or Method
Monthly Action
Track spending
Expense tracker
Review expenses every Sunday
Save money
Automatic bank transfer
Move ₹3,000 after receiving income
Pay bills
Banking app reminder
Check due dates before payment
Monitor goals
Simple spreadsheet
Update savings progress monthly
Learn about finance
Reliable educational websites
Study one topic each week
Moreover, sameer does not need ten financial apps. He uses a small number of tools with clear purposes and reviews them regularly.
Common Financial Technology Mistakes to Avoid
Moreover, installing many financial apps without using them consistently
Then, giving unnecessary permissions to an app
Additionally, notably, sharing OTPs, PINs, passwords, or security codes
Furthermore, trusting AI-generated financial information without verification
Additionally, making investment decisions because an app makes trading easy
Finally, ignoring privacy policies and data-sharing practices
Specifically, for example, using the same password for multiple financial accounts
Following notifications that encourage unnecessary spending
Specifically, first, connecting financial accounts to unknown or unverified apps
Step 7: Financial Technology Action Plan
Consequently, choose one financial problem you want technology to help solve.
Furthermore, first, first, next, select one simple and reliable tool instead of downloading many apps.
However, use an expense tracker for at least 30 days.
Then, turn on useful transaction and payment alerts.
Additionally, in fact, automate a realistic savings amount if your cash flow allows it.
Furthermore, review app permissions and privacy settings.
Moreover, enable strong security and two-factor authentication.
Finally, verify important financial information before acting on it.
Specifically, notably, review your tools every three to six months.
Key Takeaway
However, financial technology can make money management easier, but it cannot replace financial knowledge, discipline, or careful decision-making.
Therefore, notably, for personal finance beginners, the best approach is to use a small number of reliable tools for clear purposes—such as tracking expenses, automating savings, monitoring goals, and learning financial concepts. In addition, protect your information, review permissions, and verify important financial details before taking action.
Next: After creating a simple financial system, the next step is to set clear financial goals and track your progress so that your income, savings, and investments have a defined purpose.
Step 8: Set Clear Financial Goals and Track Your Progress
In fact, saving money without a clear purpose can feel difficult. When you do not know what you are saving or investing for, it becomes easier to spend the money on short-term wants. However, financial goals give your money a direction and help you make decisions based on what matters most to you.
Additionally, for personal finance beginners, setting financial goals does not mean creating an unrealistic plan to become wealthy quickly. It means deciding what you want your money to help you achieve, estimating how much you may need, choosing a realistic timeline, and taking small, consistent steps.
Particularly, your goals may include building an emergency fund, paying off debt, buying a phone, funding education, starting a business, purchasing a home, or preparing for retirement. The goal can be different for every person because income, responsibilities, priorities, and financial situations are different.
Why Financial Goals Are Important
A financial goal turns a general wish into a measurable plan.
Moreover, for example, for example, saying, “I want to save more money,” is a good intention, but it does not explain how much you want to save or when you want to achieve it.
A clearer goal would be:
“I want to save ₹30,000 for my emergency fund within 12 months by saving ₹2,500 every month.”
Overall, this goal has a target amount, a timeline, and a monthly action. You can measure your progress and adjust the plan if your income or expenses change.
Understand the Three Main Types of Financial Goals
Furthermore, notably, dividing your goals by time can help you decide how much money you need and when you may need it.
Goal Type
Typical Time Frame
Examples
Short-Term Goals
Less than 1–2 years
Emergency savings, a course fee, a phone, or paying a small debt
Medium-Term Goals
Approximately 2–5 years
Starting a business, buying a vehicle, or funding higher education
Long-Term Goals
More than 5 years
Buying a home, retirement, or long-term financial independence
However, the time frame is not fixed. A goal that is short-term for one person may take longer for another person. Therefore, your income, responsibilities, and available savings will affect the timeline.
Turn a Financial Wish Into a SMART Goal
A useful financial goal should be clear enough that you can measure and review it. You can use the SMART framework:
SMART Element
Meaning
Example
Specific
Clearly define the goal
Build an emergency fund
Measurable
Choose a target amount
Save ₹30,000
Achievable
Keep the plan realistic
Save ₹2,500 per month
Relevant
Connect the goal to your needs
Prepare for unexpected expenses
Time-Bound
Set a target date
Complete the goal in 12 months
A SMART goal may look like this:
“I will save ₹24,000 in 12 months by transferring ₹2,000 into my savings account every month.”
Specifically, as a result, this is easier to follow than saying, “I will try to save more.”
Calculate How Much You Need to Save Each Month
In fact, once you know your target amount and deadline, calculate the approximate monthly amount required.
Simple formula:
Monthly Savings Needed = Total Goal Amount ÷ Number of Months
In this example, you would need to save approximately ₹3,000 each month if your income and expenses remain stable.
However, do not create a savings target that forces you to miss essential expenses or rely on expensive borrowing. If ₹3,000 is not realistic, extend the timeline or reduce the target amount.
Prioritize Your Financial Goals
Moreover, you may have several goals at the same time, but your income may not be enough to fund all of them equally. In fact, prioritization helps you decide where your money should go first.
Priority Level
Example Goal
Reason
High Priority
Emergency fund or high-interest debt
May protect financial stability and reduce expensive costs
Medium Priority
Education, skill development, or a planned purchase
Important but may have a flexible timeline
Long-Term Priority
Retirement or long-term investing
May require consistent contributions over many years
Furthermore, for example, if you have high-interest debt and no emergency savings, it may be more practical to improve those areas before putting a large amount into a long-term investment.
Specifically, notably, financial priorities can change. A new job, family responsibility, income reduction, or unexpected expense may require you to adjust your plan.
Create a Goal-Based Money Plan
Instead of keeping all your money in one general savings category, assign each amount a purpose. This can make your progress easier to understand.
However, for example, for example, suppose Ayaan has ₹5,000 available each month after essential expenses:
Financial Goal
Monthly Amount
Purpose
Emergency fund
₹2,000
Prepare for unexpected essential expenses
Debt repayment
₹1,500
Reduce an existing financial obligation
Education or skill fund
₹1,000
Support future learning
Personal goal
₹500
Save for a planned purchase
Additionally, this is only an example. Therefore, your own plan should depend on your income, essential expenses, debt, emergency needs, and priorities.
Track Your Financial Progress Regularly
Consequently, setting a goal is only the first step. Moreover, tracking helps you see whether your actions are moving you closer to the target.
In addition, for example, you can track progress using:
A notebook
A spreadsheet
A budgeting app
A savings tracker
Then, next, your banking app
A simple monthly checklist
However, for example:
Month
Target Savings
Actual Savings
Total Progress
January
₹2,500
₹2,500
₹2,500
February
₹2,500
₹2,000
₹4,500
March
₹2,500
₹3,000
₹7,500
Consequently, progress does not need to be perfect every month. If you save less during one month because of an important expense, review the reason and adjust the next month instead of abandoning the goal.
Use Financial Tools to Track Goals More Easily
Therefore, digital tools can make goal tracking faster. A budgeting app, spreadsheet, expense tracker, or AI-powered financial tool may help you organize your income, expenses, savings targets, and progress.
However, technology should support your plan rather than create unnecessary complexity. You do not need ten different apps to track one financial goal.
To explore useful digital tools, read our detailed guide on 10 Best AI Tools to Manage Your Personal Finances in 2026. It explains how different tools may support budgeting, expense tracking, financial planning, and money management.
Review Goals Without Feeling Discouraged
However, your financial plan should be flexible. If your income changes, an emergency occurs, or your expenses increase, you may need to change the amount or timeline.
In fact, for example, suppose your goal is to save ₹30,000 in one year, but you can save only ₹15,000 after six months. Instead of giving up, review your situation:
Then, for example, can you reduce one unnecessary expense?
Additionally, can you increase your income?
Consequently, can you extend the deadline?
Furthermore, can you reduce the target amount?
However, was there an unexpected expense that affected your progress?
In fact, adjusting a financial goal is not the same as failing. A realistic plan should be able to adapt to changes in your life.
If you are earning a reasonable income but still cannot save consistently, our guide on why you can’t save money even with a good salary may help you identify hidden spending patterns and improve your savings system.
Use Long-Term Goals to Guide Investment Decisions
Particularly, long-term financial goals can help you decide why you are investing and how much risk may be appropriate. Before choosing an investment, consider when you may need the money and whether you can handle changes in its value.
Moreover, the Investor.gov investing basics explain that financial goals, time horizon, risk tolerance, and investment choices are connected.
If you are researching mutual funds, you can also read our guide on Best Performing FlexiCap Funds. Overall, past returns should not be the only factor; the investment strategy, risk, costs, and suitability for your goal are also important.
A Practical Financial Goal Example
Moreover, suppose Sana wants to build a ₹50,000 emergency fund within 20 months.
Overall, notably, she calculates:
₹50,000 ÷ 20 months = ₹2,500 per month
Consequently, notably, her plan looks like this:
Action
Plan
Monthly savings target
₹2,500
Transfer date
Within two days of receiving income
Tracking method
Simple spreadsheet
Review schedule
Last Sunday of every month
Adjustment plan
Extend the timeline if income falls
Additionally, after four months, Sana has saved ₹9,000 instead of the planned ₹10,000 because of an unexpected expense. She reviews her budget and decides to add ₹500 during the next two months. Her goal remains flexible and realistic.
Common Financial Goal Mistakes to Avoid
Finally, setting a goal without choosing a target amount
Specifically, in fact, creating an unrealistic deadline
Additionally, first, trying to fund too many goals at the same time
Moreover, ignoring emergency savings
Furthermore, next, saving without tracking progress
Then, notably, using borrowed money to meet a savings target
Additionally, comparing your financial progress with other people
Additionally, giving up after one difficult month
Furthermore, never reviewing or updating your goals
Step 8: Financial Goal Action Plan
Finally, for example, write down your three most important financial goals.
Specifically, choose a target amount for each goal.
Consequently, set a realistic deadline.
Finally, first, calculate the approximate monthly amount required.
However, rank your goals by priority.
Specifically, next, choose a simple tracking method.
Then, in fact, review your progress once every month.
Additionally, adjust the amount or timeline when your financial situation changes.
Moreover, celebrate progress without creating unnecessary spending.
Key Takeaway
In addition, as a result, financial goals give your money a purpose. A clear target, realistic timeline, regular contribution, and simple tracking system can make a large financial goal feel more manageable.
Additionally, for example, for personal finance beginners, the best approach is to start with one important goal, take small and consistent actions, and review your progress regularly. As a result, your financial plan does not need to be perfect—it needs to be realistic enough to continue.
Next: After setting clear financial goals, the next step is to build and protect a healthy credit profile by understanding responsible borrowing, timely payments, and credit-report monitoring.
What is personal finance for beginners?
Furthermore, personal finance for beginners means learning how to manage income, expenses, savings, debt, insurance, and investments. The goal is to make informed money decisions, build financial security, and work toward short-term and long-term financial goals.
How should a beginner start managing money?
A beginner can start by tracking monthly income and expenses, creating a simple budget, saving a small amount regularly, building an emergency fund, and avoiding unnecessary debt. As a result, start with a simple system that you can follow consistently.
How much money should a beginner save each month?
Consequently, there is no single amount that works for everyone. Additionally, start with an amount that fits your income and essential expenses, even if it is small. Particularly, saving consistently is usually more sustainable than setting an unrealistic target and stopping after a few months.
Conclusion:
Specifically, personal finance does not require a high income, complicated calculations, or perfect money habits. It starts with understanding where your money comes from, where it goes, and what you want it to achieve.
By following these 10 steps, you can create a realistic budget, control unnecessary expenses, build an emergency fund, manage debt responsibly, set clear financial goals, and make better decisions about saving and investing. You do not need to complete everything at once. Specifically, start with one small action, such as tracking your expenses for a week or saving a fixed amount every month.
However, your financial plan should also change as your income, responsibilities, and goals change. For example, review your progress regularly, learn from mistakes, and adjust your plan when necessary. A missed savings target or an unexpected expense does not mean your plan has failed—it simply shows that something may need to be improved.
However, for example, for personal finance beginners, consistency is usually more valuable than trying to follow a perfect system. Moreover, small habits, repeated over time, can help you build greater financial confidence and move closer to long-term financial stability.
Actionable Advice and Practical Tips for personal finance for beginners
In fact, start today: review your income and expenses, choose one financial goal, and take the first practical step toward managing your money better.
Personal Finance for Beginners: Quick Summary Personal finance for beginners starts with understanding your income, tracking expenses, and making a realistic plan for your money. You do not need a high income or a complicated system to begin. In addition, small and consistent financial decisions can help you build better money habits over time. Understand your income, expenses, savings, and debts. Create a realistic monthly budget. Track spending and reduce unnecessary expenses. Build an emergency fund gradually. Manage debt responsibly and pay bills on time. Set clear short-term and long-term financial goals. Protect your finances with suitable insurance and basic security practices. Learn the basics before investing and understand the risks involved. Develop consistent financial habits instead of looking for quick results. Review your financial plan regularly and adjust it when your income, expenses, or goals change. The most important lesson is that financial progress does not usually happen through one big decision. It is built through small actions repeated consistently. However, start with one practical step today, improve your system over time, and make decisions that support your financial goals.
Furthermore, over 4 years of active personal finance research in Indian markets. Additionally, focused on transparent, math-backed guides to help students and young professionals build wealth and manage money smartly.
Learning the essential principles of financial planning for beginners is critical for anyone looking to build healthy money habits, avoid debt traps, and make smart financial decisions in India.
Learning the essential principles of financial planning for beginners is critical for anyone looking to build healthy money habits, avoid debt traps, and make smart financial decisions in India.
Learning the essential principles of financial planning for beginners is critical for anyone looking to build healthy money habits, avoid debt traps, and make smart financial decisions in India.
Learning the essential principles of financial planning for beginners is critical for anyone looking to build healthy money habits, avoid debt traps, and make smart financial decisions in India.
Learning about financial planning for beginners is essential for anyone looking to build healthy money habits. Furthermore, table of Contents
Actionable Advice and Practical Tips for financial planning for beginners
Essential Overview: Guide to financial planning for beginners
Practical Steps & Actionable Tips for financial planning for beginners
Essential Overview: Guide to financial planning for beginners
Introduction: Complete Guide to financial planning for beginners
Additionally, managing money isn’t just about earning more—it’s about making smart financial decisions that help you build a secure future. Therefore, unfortunately, many people struggle with budgeting, saving, investing, and managing debt because they don’t have a clear financial plan. That’s why Financial Planning for Beginners is one of the most important skills anyone can learn, regardless of their income or financial background.
Whether you’re a student, a young professional, a freelancer, or simply looking to take control of your finances, financial planning provides a clear roadmap for managing your money with confidence. It helps you set realistic financial goals, create a practical budget, build an emergency fund, reduce financial stress, and make informed investment decisions that support long-term wealth.
In this complete guide, you’ll learn the 10 simple steps of Financial Planning for Beginners, along with practical strategies, real-world examples, and actionable tips that you can apply immediately. By the end of this article, you’ll have a step-by-step financial roadmap to make smarter money decisions, avoid common financial mistakes, and build a stronger financial future.
What Is Financial Planning?: Complete Guide to financial planning for beginners
Financial planning is the strategic process of managing your income, expenses, savings, investments, insurance, taxes, and future financial goals to achieve long-term financial security. Instead of making random money decisions, it provides a structured roadmap that helps you spend wisely, save consistently, invest intelligently, and prepare for life’s expected and unexpected financial challenges.
FREE INTERACTIVE TOOL
Visualize the Power of Compound Interest
Furthermore, for example, see how small, consistent monthly contributions grow exponentially through compounding over time.
Specifically, for beginners, financial planning is not about becoming rich overnight or making complicated investments. It starts with understanding your current financial situation, setting realistic goals, creating a budget, building an emergency fund, managing debt, and investing consistently. Whether you’re a student, a salaried employee, a freelancer, or a business owner, having a financial plan gives every dollar a purpose and helps you make smarter financial decisions.
Consequently, think of financial planning as a GPS for your financial journey. As a result, just as you wouldn’t start a long road trip without knowing your destination, you shouldn’t make important money decisions without a clear financial plan. A proper plan keeps you focused on your goals while reducing financial stress and avoiding costly mistakes.
Why Is Financial Planning Important?: Complete Guide to financial planning for beginners
Additionally, for example, financial planning helps you stay in control of your money instead of letting your money control you. It creates a balance between your current lifestyle and your future financial goals while protecting you from unexpected financial emergencies.
First, first, first, first, helps you understand your complete financial situation.
Consequently, creates a realistic monthly budget.
Next, next, next, next, builds an emergency fund for unexpected expenses.
However, reduces unnecessary debt and financial stress.
Then, improves your saving habits.
Additionally, in fact, helps you invest according to your goals.
Furthermore, protects your family with proper insurance planning.
Moreover, builds long-term wealth through disciplined investing.
Finally, prepares you for retirement and major life events.
Key Components of Financial Planning: Complete Guide to financial planning for beginners
A successful financial plan consists of several interconnected areas. Particularly, ignoring even one of them can affect your overall financial health.
1. Moreover, income Management
However, the first step is understanding your income sources and managing them efficiently. Additionally, knowing exactly how much money you earn each month allows you to create realistic financial goals and spending plans.
2. In addition, notably, budgeting and Expense Management
In fact, managing debt wisely allows more of your income to be used for saving and investing instead of paying interest. Specifically, paying off high-interest debt should always be a priority.
5. For example, investment Planning
In addition, investing helps your money grow over time and protects it against inflation. If you’re just getting started, our explains the basics in simple language.
6. Consequently, insurance and Risk Management
Moreover, insurance protects your financial future from unexpected events. In addition, health, life, and disability insurance reduce financial risk and protect your long-term wealth.
7. Retirement Planning
However, retirement planning ensures financial independence later in life. Therefore, starting early allows compound growth to work in your favor, making it easier to build long-term wealth.
Financial Planning vs Budgeting vs Investing: Complete Guide to financial planning for beginners
⚠️ Must-Read Guide (2026)
16 min read
Flat vs Reducing Interest Rate: Why 10% Flat Rate Is Actually 18%+ Real APR
Before converting any credit card purchase into EMIs or signing a personal loan agreement, learn how flat interest secretly charges interest on money you already paid back. See real ₹2,00,000 calculation proof and RBI rules.
Includes budgeting, saving, insurance, debt, and investing.
Focuses mainly on spending and saving.
Focuses on stocks, mutual funds, ETFs, bonds, and other investments.
Real-Life Example: Complete Guide to financial planning for beginners
Therefore, notably, imagine two friends earning the same salary. The first spends money without tracking expenses, saves only when money is left over, and invests randomly. The second creates a budget, builds an emergency fund, pays off high-interest debt, invests every month, and reviews financial goals regularly. In fact, after several years, the second person is far more likely to achieve financial stability and long-term wealth—not because they earned more, but because they followed a financial plan.
Common Myths About Financial Planning: Complete Guide to financial planning for beginners
Specifically, notably, financial planning is only for wealthy people.
Then, first, you need a high income before creating a financial plan.
Additionally, financial planning only means investing in the stock market.
Additionally, next, budgeting alone is enough to achieve financial success.
Then, for example, financial planning is something you only do once.
In reality, financial planning is a continuous process that evolves as your income, expenses, responsibilities, and financial goals change over time.
Expert Tips for Beginners: Complete Guide to financial planning for beginners
Additionally, pay yourself first by saving before spending.
Consequently, review your budget every month.
Furthermore, build an emergency fund before making risky investments.
However, invest consistently instead of trying to time the market.
Finally, review your financial plan at least once every six months.
Quick Checklist: Complete Guide to financial planning for beginners
Specifically, know your monthly income.
Furthermore, first, track your expenses.
Finally, next, create a realistic budget.
Then, build an emergency fund.
Additionally, eliminate high-interest debt.
Furthermore, start investing consistently.
Finally, protect yourself with insurance.
Specifically, review your financial plan regularly.
Key Takeaways: Complete Guide to financial planning for beginners
Specifically, first, in fact, financial planning is a complete strategy for managing money effectively.
Then, first, next, it combines budgeting, saving, investing, insurance, debt management, and retirement planning.
Moreover, anyone can start financial planning regardless of income.
Then, small, consistent financial decisions often produce significant long-term results.
Additionally, notably, reviewing and improving your financial plan regularly is essential for achieving financial success.
Now that you understand what financial planning is, let’s explore why financial planning is important and how it can transform your financial future.
Why Is Financial Planning Important?: Complete Guide to financial planning for beginners
In fact, financial planning is more than just saving money—it is about creating a roadmap for your financial future. Moreover, without a proper plan, even people with high incomes can struggle to achieve financial freedom because they spend without clear priorities. A well-designed financial plan helps you manage your income wisely, prepare for emergencies, reduce debt, build wealth, and achieve long-term financial goals with confidence.
Whether you are a student, salaried employee, freelancer, or business owner, financial planning gives every dollar a purpose. Instead of wondering where your money disappeared each month, you gain complete control over your finances and make decisions that support your future.
If you’re finding it difficult to control your monthly expenses, read our How to Manage Your Salary guide to build a stronger financial foundation.
1. Overall, gives You Complete Control Over Your Money: Complete Guide to financial planning for beginners
Additionally, financial planning allows you to understand exactly how much money you earn, spend, save, and invest. This awareness helps eliminate unnecessary expenses and improves your financial discipline.
Furthermore, track monthly income and expenses.
Additionally, reduce impulse spending.
Finally, create better money habits.
Specifically, for example, increase monthly savings.
2. However, helps You Achieve Financial Goals Faster: Complete Guide to financial planning for beginners
Whether your goal is buying a house, starting a business, traveling the world, or retiring early, financial planning breaks large goals into smaller, achievable milestones.
Examples of Financial Goals
Additionally, next, first, build a $1,000 emergency fund.
Consequently, save for higher education.
Then, next, buy your first home.
However, become debt-free.
Then, create passive income.
Additionally, in fact, retire comfortably.
3. As a result, protects You During Financial Emergencies: Complete Guide to financial planning for beginners
Particularly, unexpected events such as medical bills, job loss, or major repairs can disrupt your finances. A financial plan includes an emergency fund that helps you handle these situations without relying on high-interest debt.
4. Additionally, reduces Financial Stress: Complete Guide to financial planning for beginners
Overall, money is one of the biggest causes of stress. When you know your financial position and have a clear action plan, you feel more confident and make better financial decisions.
5. Therefore, helps You Build Long-Term Wealth: Complete Guide to financial planning for beginners
Consequently, saving alone is not enough. Specifically, financial planning combines budgeting, saving, investing, insurance, and tax planning to help your money grow over time through compound growth.
Common Mistakes Beginners Make: Complete Guide to financial planning for beginners
Furthermore, living without a monthly budget.
Moreover, ignoring emergency savings.
Finally, using credit cards for unnecessary purchases.
Specifically, notably, investing without clear goals.
Additionally, first, not reviewing finances regularly.
Expert Tips: Complete Guide to financial planning for beginners
Additionally, review your financial plan every month.
Furthermore, next, automate your savings.
Then, for example, invest consistently for the long term.
Additionally, avoid lifestyle inflation as your income grows.
Consequently, track your net worth every year.
Key Takeaways: Complete Guide to financial planning for beginners
Furthermore, financial planning gives your money a clear direction.
However, it helps you achieve goals while reducing financial stress.
Finally, emergency savings and investing are equally important.
Specifically, in fact, consistent planning leads to long-term financial security.
According to the Consumer Financial Protection Bureau (CFPB), creating a financial plan and reviewing it regularly helps individuals make informed financial decisions and prepare for future financial needs.
Next, let’s understand the 10 simple steps you can follow to create your own financial plan from scratch.
Step 3: Build an Emergency Fund Before You Invest: Complete Guide to financial planning for beginners
Furthermore, notably, one of the biggest financial mistakes beginners make is investing before creating an emergency fund. While investing helps grow your wealth, it cannot replace cash that is immediately available during unexpected situations.
However, an emergency fund acts as your financial safety net. It protects you from debt, high-interest loans, and financial stress when life takes an unexpected turn.
What Is an Emergency Fund?: Complete Guide to financial planning for beginners
Specifically, as a result, an emergency fund is money set aside only for unexpected expenses such as:
Finally, first, medical emergencies
Moreover, job loss
Specifically, next, car or bike repairs
Then, notably, home maintenance
Additionally, family emergencies
Additionally, urgent travel expenses
In fact, never use this money for shopping, vacations, or entertainment.
How Much Should You Save?: Complete Guide to financial planning for beginners
A good rule is to save enough to cover 3–6 months of essential living expenses.
Additionally, for example:
Furthermore, monthly expenses: $800
Finally, for example, emergency fund goal:
Specifically, minimum: $2,400
Consequently, ideal: $4,800
If you’re just starting, don’t wait until you can save the full amount.
Moreover, start with your first milestone:
$100
$250
$500
$1,000
Furthermore, small wins create long-term financial discipline.
Where Should You Keep Your Emergency Fund?: Complete Guide to financial planning for beginners
Specifically, notably, keep your emergency money somewhere safe and easily accessible.
Additionally, for example, for example, good options include:
Additionally, avoid keeping emergency funds in stocks or other volatile investments because their value can fall when you need the money most.
Common Mistakes Beginners Make: Complete Guide to financial planning for beginners
Then, in fact, investing without any emergency savings
Additionally, using credit cards for emergencies
Moreover, spending emergency money on non-essential purchases
Furthermore, keeping all savings in risky investments
Finally, notably, never replenishing the emergency fund after using it
Quick Action Plan: Complete Guide to financial planning for beginners
Consequently, calculate your monthly essential expenses.
In addition, set a realistic emergency savings goal.
However, automate a fixed amount every month.
Therefore, use the fund only for real emergencies.
In fact, rebuild the fund immediately after withdrawing money.
Pro Tip: Build your emergency fund first. For example, once you have a strong financial safety net, you can invest with greater confidence and avoid selling investments during difficult times.
A budget is the foundation of every successful financial plan. No matter how much you earn, if you don’t know where your money goes each month, building wealth becomes extremely difficult. A realistic monthly budget gives every dollar a purpose, helping you spend intentionally instead of emotionally.
Moreover, for example, many people think budgeting is about restricting their lifestyle, but that’s a common misconception. In reality, a budget gives you more financial freedom because it allows you to spend confidently while ensuring your essential expenses, savings, and investments remain on track.
If you’ve ever wondered where your salary disappears before the end of the month, it’s time to create a budget that works for your lifestyle—not against it.
Overall, need help managing your monthly income? In fact, read our How to Manage Your Salary guide for practical strategies.
Why Budgeting Is Important
A monthly budget acts as a financial blueprint. Instead of reacting to expenses, you plan them in advance and stay in control of your money.
Specifically, track every dollar you earn.
Additionally, reduce unnecessary spending.
Then, first, increase monthly savings.
Additionally, next, for example, avoid overspending.
Then, achieve financial goals faster.
Consequently, reduce money-related stress.
How to Create a Budget in 5 Simple Steps
1. In addition, calculate Your Monthly Income
Consequently, start by adding all reliable sources of income, including salary, freelance work, side hustles, rental income, or business earnings.
2. However, list Every Monthly Expense
Consequently, notably, separate your expenses into fixed and variable categories.
Additionally, housing
However, utilities
Furthermore, transportation
Finally, in fact, groceries
Specifically, insurance
Moreover, entertainment
Furthermore, first, shopping
Finally, next, notably, subscriptions
3. Particularly, follow the 50/30/20 Budget Rule
Category
Percentage
Purpose
Needs
50%
Housing, food, bills, transportation
Wants
30%
Entertainment, shopping, dining out
Savings & Investing
20%
Emergency fund, investments, retirement
However, the 50/30/20 rule is a helpful starting point, but you can adjust the percentages based on your income, financial goals, and living expenses.
4. In fact, track Your Spending Every Week
In addition, as a result, review your expenses weekly instead of waiting until the end of the month. This helps you identify unnecessary spending before it becomes a habit.
5. Particularly, adjust and Improve Every Month
A budget isn’t permanent. As your income, expenses, and financial goals change, your budget should evolve too.
Real-Life Example
In fact, imagine David earns $3,000 every month. Before budgeting, he often ran out of money before payday. In fact, after following a monthly budget, he reduced unnecessary subscriptions and impulse purchases, increased his monthly savings, and started investing consistently. Overall, within a year, he had built a healthy emergency fund and significantly improved his financial confidence.
Common Budgeting Mistakes
Then, not tracking daily expenses.
Additionally, ignoring small purchases.
Additionally, creating an unrealistic budget.
Furthermore, for example, forgetting irregular yearly expenses.
Finally, never reviewing the budget.
Expert Tips
Consequently, automate your savings first.
Specifically, review your budget every Sunday.
However, keep entertainment spending within limits.
Specifically, first, increase savings whenever your income grows.
Specifically, first, next, in fact, use budgeting apps or spreadsheets to monitor expenses.
According to the Consumer Financial Protection Bureau (CFPB), maintaining a monthly budget is one of the most effective ways to improve financial well-being and achieve long-term financial goals.
Key Takeaways
A budget gives every dollar a purpose.
Then, track your spending consistently.
Moreover, review and improve your budget every month.
Additionally, small budgeting habits create long-term financial success.
Next Step: Now that you’ve created a realistic budget, it’s time to build a strong emergency fund that protects your financial future.
Manage and Eliminate Debt Wisely
Moreover, managing debt is one of the most important parts of financial planning for beginners. Notably, many people focus only on earning more money, but building wealth becomes difficult if a large part of your income goes toward loan payments, credit card bills, or other debts. A smart financial plan helps you reduce debt strategically so you can save, invest, and achieve your financial goals faster.
Why Debt Management Matters
Furthermore, not all debt is bad. A home loan or education loan can help build your future, but high-interest debt such as credit card balances and personal loans can slow your financial growth. Additionally, paying these off early gives you more financial freedom and reduces stress.
Types of Debt You Should Know
Good Debt
Furthermore, notably, education loans
Finally, home loans
Additionally, business loans used for growth
Bad Debt
Specifically, high-interest credit cards
Specifically, first, for example, personal loans for unnecessary expenses
Additionally, next, first, next, buy Now Pay Later (BNPL) purchases without a repayment plan
How to Eliminate Debt Faster
1. Furthermore, list Every Debt
Specifically, notably, write down each loan with its total balance, interest rate, and minimum monthly payment. This helps you see the complete picture.
2. Pay High-Interest Debt First
However, for example, use the Debt Avalanche Method by paying extra toward the loan with the highest interest rate while making minimum payments on the others. This saves the most money over time.
3. Moreover, avoid Taking New Debt
Additionally, reduce unnecessary spending and avoid borrowing for non-essential purchases until your existing debt is under control.
4. For example, make Extra Payments Whenever Possible
Consequently, use bonuses, tax refunds, freelance income, or any extra earnings to reduce your loan principal faster.
Real-Life Example
In addition, for example, imagine you have a credit card balance with a high interest rate and a small education loan. By paying extra toward the credit card first while continuing minimum payments on the education loan, you reduce interest costs and become debt-free sooner.
Common Debt Management Mistakes
Consequently, paying only the minimum amount every month
Then, ignoring high-interest debt
However, borrowing to repay another loan
Additionally, using credit cards for everyday expenses without a repayment plan
Furthermore, in fact, not tracking loan balances regularly
Expert Tips
Finally, keep your monthly debt payments below 35% of your income whenever possible.
Moreover, set up automatic payments to avoid late fees.
Specifically, review your debt every month and celebrate small milestones to stay motivated.
However, saving money protects your finances, but investing helps your money grow over time. If you want to build long-term wealth, beat inflation, and achieve major financial goals, investing should become an essential part of your financial planning. The earlier you start, the more time your money has to benefit from compound growth.
Why Investing Is Important
Consequently, many beginners keep all their money in a savings account. While savings are important for emergencies, they usually don’t generate enough returns to build significant wealth. Consequently, investing allows your money to work for you instead of sitting idle.
Where Should Beginners Invest?
1. Additionally, mutual Funds
Therefore, mutual funds are one of the easiest investment options for beginners. You can start with a small monthly SIP and let professional fund managers handle your investments.
2. However, index Funds
However, index funds track the overall market and usually have lower fees. Therefore, they are ideal for beginners who want long-term growth with minimal effort.
3. Furthermore, stocks
In fact, buying individual company shares can offer higher returns, but it also involves higher risk. Particularly, beginners should learn the basics before investing directly in stocks.
4. Moreover, fixed-Income Investments
In fact, fixed deposits and government-backed savings schemes provide stable returns and are suitable for short-term or low-risk financial goals.
Investment Mistakes Beginners Should Avoid
Then, investing without clear financial goals.
Additionally, for example, trying to become rich overnight.
Following social media tips without research.
Furthermore, investing money needed for emergencies.
Consequently, selling investments during short-term market declines.
Real-Life Example
Particularly, suppose you invest a fixed amount every month through a SIP instead of waiting for the “perfect time.” Over several years, consistent investing and compound growth can build significantly more wealth than keeping the same money in a regular savings account.
Expert Tips
Finally, start investing as early as possible.
However, invest regularly instead of timing the market.
Specifically, diversify your investments across different assets.
Additionally, first, in fact, review your portfolio once or twice a year.
Furthermore, next, stay invested for the long term.
Key Takeaways
Moreover, investing is essential for long-term wealth creation.
Then, start with beginner-friendly investment options.
Additionally, notably, invest consistently and think long term.
Protect Your Financial Future with the Right Insurance
A complete financial planning for beginners guide is not only about saving and investing. It is also about protecting everything you have built. A single medical emergency, accident, or unexpected event can destroy years of savings if you are not properly insured. That’s why insurance is an essential part of every financial planning process.
Why Is Insurance Important in Financial Planning?
Moreover, insurance protects your income, savings, investments, and family from unexpected financial risks. Instead of paying huge expenses from your own pocket, insurance helps reduce the financial burden and keeps your long-term financial goals on track.
Types of Insurance Every Beginner Should Consider
1. For example, notably, health Insurance for Financial Security
Moreover, health insurance is one of the first policies every beginner should have. As a result, medical costs continue to rise every year, and a good health insurance plan protects your savings from unexpected hospital bills.
2. Consequently, life Insurance for Family Protection
If your family depends on your income, life insurance provides financial support to your loved ones if something unexpected happens to you. A term life insurance plan is often the most affordable option for beginners.
3. Furthermore, vehicle Insurance to Avoid Financial Losses
If you own a bike or car, vehicle insurance protects you from repair costs, accidents, and legal liabilities. It is also mandatory in many countries.
4. Specifically, property and Home Insurance
Overall, notably, home insurance protects your house and valuable belongings from fire, theft, natural disasters, and other unexpected events.
How Much Insurance Do You Need?
Therefore, notably, the right insurance coverage depends on your income, financial responsibilities, existing savings, debts, and family needs. Review your insurance requirements regularly as your financial situation changes.
Common Insurance Mistakes Beginners Make
Additionally, buying insurance only to save tax.
Finally, delaying health insurance until later in life.
Specifically, for example, choosing the cheapest policy without comparing coverage.
Finally, first, ignoring policy exclusions and claim conditions.
Consequently, never reviewing insurance after major life changes.
Expert Tips for Choosing the Right Insurance
Specifically, next, buy insurance before investing aggressively.
However, compare multiple insurance providers before purchasing.
Then, read the policy terms carefully.
Additionally, in fact, review your coverage every year.
Furthermore, keep all insurance documents organized and updated.
Key Takeaways
Moreover, insurance protects your financial future from unexpected risks.
Finally, health insurance should usually be your first priority.
Specifically, notably, life insurance is important if your family depends on your income.
Additionally, first, first, review your insurance coverage regularly as your financial goals change.
Additionally, creating a financial plan is only the beginning. To achieve long-term success, you must review and improve your plan regularly. Consequently, your income, expenses, financial goals, investments, and responsibilities will change over time, so your financial plan should evolve as well.
In fact, as a result, many beginners create a budget or investment plan once and never look at it again. This is one of the biggest mistakes in financial planning for beginners. In addition, regular reviews help you identify problems early, adjust your strategy, and stay on track toward your financial goals.
Why Is Reviewing Your Financial Plan Important?
A financial plan is not a one-time document—it is a living strategy. However, reviewing it regularly helps you adapt to life’s changes and make smarter financial decisions.
Additionally, for example, benefits of reviewing your financial plan include:
Additionally, stay focused on your financial goals.
Furthermore, next, next, adjust your budget as your income changes.
Then, for example, track your savings and investment progress.
Additionally, identify unnecessary expenses.
Consequently, improve your long-term financial security.
Furthermore, reduce financial mistakes before they become costly.
What Should You Review Every Month?
1. Therefore, review Your Monthly Budget
Furthermore, compare your planned budget with your actual spending. In fact, look for areas where you consistently overspend and make adjustments for the next month.
2. Therefore, review Your Savings Progress
Consequently, check whether you’re consistently contributing to your emergency fund, retirement savings, and other financial goals.
3. Moreover, review Your Investments
Specifically, monitor your portfolio’s performance without reacting to short-term market movements. Overall, focus on whether your investments still match your goals and risk tolerance.
4. As a result, review Your Debt
However, track your outstanding balances, interest rates, and repayment progress. If possible, increase your monthly payments to become debt-free faster.
5. As a result, review Your Financial Goals
Particularly, for example, as your career, family, or lifestyle changes, update your short-term and long-term financial goals to reflect your current priorities.
Annual Financial Planning Checklist
At least once a year, ask yourself:
However, have I increased my savings rate?
Finally, is my emergency fund still adequate?
Specifically, in fact, do Always have the right insurance coverage?
Then, first, am I investing enough for retirement?
Moreover, have I reduced unnecessary debt?
Additionally, next, do my financial goals still reflect my priorities?
Common Financial Planning Mistakes
Then, notably, never reviewing your budget.
Additionally, ignoring lifestyle inflation after salary increases.
Additionally, making emotional investment decisions.
Furthermore, forgetting to update financial goals.
Finally, for example, delaying important financial decisions.
Expert Tips
Specifically, schedule a monthly “Money Review Day.”
Consequently, review your net worth every six months.
Furthermore, first, increase your investments whenever your income grows.
However, rebalance your investment portfolio once a year.
Finally, next, keep learning about personal finance to improve your financial decisions.
Key Takeaways
Then, in fact, financial planning is an ongoing process, not a one-time task.
Additionally, small monthly improvements lead to significant long-term results.
Moreover, regular reviews help you stay aligned with your financial goals.
Furthermore, continuous learning and disciplined habits are the foundation of financial success.
External Resource: The Consumer Financial Protection Bureau (CFPB) recommends reviewing your financial goals, spending, savings, and debt regularly to maintain long-term financial well-being.
Step 10: Take Action and Stay Consistent with Your Financial Plan
In fact, creating a financial plan is an important achievement, but taking consistent action is what turns your plan into real financial success. Additionally, many people spend weeks learning about budgeting, investing, and saving, yet never implement what they learn. Particularly, knowledge alone doesn’t build wealth—consistent action does.
Consequently, the most successful people in personal finance aren’t always those with the highest incomes. Specifically, they’re the ones who follow good financial habits month after month, year after year. For example, small, consistent improvements often produce far better results than occasional large efforts.
Why Consistency Is the Key to Financial Success
Moreover, financial planning isn’t about making one perfect decision. It’s about making hundreds of small, smart decisions over time.
When you stay consistent, you can:
Finally, notably, build wealth steadily.
Specifically, develop strong financial habits.
Additionally, reduce financial stress.
Specifically, first, reach your financial goals faster.
Finally, first, next, for example, stay motivated during market ups and downs.
Build Daily and Monthly Financial Habits
Daily Financial Habits
Then, avoid impulse purchases.
Consequently, track your daily spending.
Additionally, spend intentionally instead of emotionally.
Weekly Financial Habits
However, review your expenses.
Furthermore, check your budget progress.
Finally, in fact, identify unnecessary spending.
Monthly Financial Habits
Specifically, save before spending.
Moreover, invest consistently.
Specifically, next, first, pay bills on time.
Then, next, notably, review your financial goals.
Then, update your budget if needed.
Continue Learning About Personal Finance
In addition, financial planning is a lifelong journey. As markets, technology, and your personal circumstances change, continue improving your financial knowledge.
However, notably, consider learning about:
Additionally, investing
Additionally, tax planning
Furthermore, for example, insurance
Finally, retirement planning
Consequently, passive income
Specifically, wealth management
Therefore, the more you learn, the better financial decisions you’ll make.
Financial planning for beginners doesn’t have to be complicated. By following the simple steps in this guide—understanding your current financial situation, setting SMART goals, tracking your income and expenses, creating a realistic budget, managing debt, investing for the future, protecting yourself with insurance, planning for retirement, and reviewing your progress regularly—you can build a strong financial foundation.
In fact, remember, financial success is not about earning the highest income. It’s about making smart financial decisions consistently over time. Moreover, even small actions, such as saving a little more each month or investing regularly, can create significant results through discipline and the power of compound growth.
Particularly, for example, the best time to start your financial planning journey is today. In addition, stay committed to your goals, continue learning, and review your financial plan regularly. However, with patience and consistency, you’ll be well on your way to achieving long-term financial security and financial freedom.
What Is Financial Planning for Beginners? Financial planning for beginners is the process of managing your income, expenses, savings, investments, insurance, and financial goals to build long-term financial security. It helps you create a budget, save consistently, reduce debt, invest wisely, and make better financial decisions for the future.
Actionable Advice and Practical Tips for financial planning for beginners
Why Is Financial Planning Important Financial planning is important because it helps you take control of your money, prepare for unexpected expenses, achieve your financial goals, and build long-term wealth. A solid financial plan also reduces financial stress and gives you confidence in your financial future.
How Do I Start Financial Planning with a Low Income You can start financial planning with a low income by tracking your expenses, creating a realistic budget, building an emergency fund, paying off high-interest debt, and investing small amounts consistently. Additionally, good financial habits matter more than a high income.
Practical Steps & Actionable Tips for financial planning for beginners
What Are the Five Steps of Financial Planning The five basic steps of financial planning are assessing your current financial situation, setting clear financial goals, creating a budget, saving and investing regularly, and reviewing your financial plan periodically. Following these steps helps you achieve long-term financial success.
How Often Should You Review Your Financial Plan You should review your financial plan every three to six months or whenever a major life event occurs, such as changing jobs, getting married, buying a home, or starting a family. In fact, regular reviews help keep your budget, savings, investments, and financial goals on track.
Actionable Advice and Practical Tips for financial planning for beginners
Actionable Insights and Smart Advice for financial planning for beginners
Detailed Summary Financial planning for beginners is the foundation of long-term financial success. It is not just about creating a budget or saving money—it’s a complete process that helps you manage your income, control expenses, reduce debt, invest wisely, protect your finances, and achieve your short-term and long-term financial goals. In this guide, you first learned what financial planning is and why it is essential for building financial security. You then discovered how to assess your current financial situation by evaluating your income, expenses, savings, debts, and overall financial health. Particularly, understanding your current position is the first step toward making smarter financial decisions. Next, you explored how to set SMART financial goals that are specific, measurable, achievable, relevant, and time-bound. Notably, clear goals give your money a purpose and help you stay focused on what matters most. You also learned the importance of tracking your income and expenses, creating a realistic monthly budget, and managing debt effectively. These habits help you improve cash flow, reduce unnecessary spending, and create more opportunities to save and invest. The guide also explained why investing is essential for long-term wealth creation, how insurance protects your financial future from unexpected risks, and why starting retirement planning early allows your investments to benefit from compound growth over time. Finally, you learned that financial planning is an ongoing process. Overall, reviewing your financial plan regularly, adjusting it as your life changes, and staying consistent with good financial habits are the keys to achieving lasting financial success. Whether you’re starting with a small income or beginning your financial journey from scratch, following these practical steps can help you build a stronger financial future. As a result, notably, remember, successful financial planning is not about being perfect—it’s about making consistent, informed decisions that move you closer to financial freedom, one step at a time.
Hi, Ensure you am Asif Khan, founder and lead research editor at PaisaKmao.de. Specifically, over the past 3 to 4 years of active personal finance research and real-money investing in Indian markets, Clearly have navigated the practical realities of building an investment portfolio from scratch—from starting with small student pocket money, learning from early market mistakes (penny stocks, dividend tax surprises, and hidden DP charges), to establishing disciplined SIPs in low-cost index funds and managing risk. My mission with PaisaKmao.de is to provide 100% transparent, math-backed financial guides and practical calculators so young investors can build long-term wealth without falling into common traps.
Written & Researched by Asif Khan
Written & Researched by Asif Khan
Founder & Lead Financial Editor PaisaKmao.de
Additionally, over 4 years of active personal finance research in Indian markets. For example, focused on transparent, math-backed guides to help students and young professionals build wealth and manage money smartly.
Learning the essential principles of budget with an irregular income is critical for anyone looking to build healthy money habits, avoid debt traps, and make smart financial decisions in India.
Learning the essential principles of budget with an irregular income is critical for anyone looking to build healthy money habits, avoid debt traps, and make smart financial decisions in India.
Learning the essential principles of budget with an irregular income is critical for anyone looking to build healthy money habits, avoid debt traps, and make smart financial decisions in India.
Learning the essential principles of budget with an irregular income is critical for anyone looking to build healthy money habits, avoid debt traps, and make smart financial decisions in India.
Learning about budget with an irregular income is essential for anyone looking to build healthy money habits. introduction
How to Budget with Managing money becomes difficult when your income is not the same every month. Unlike salaried employees who receive a fixed paycheck, people with irregular income often face uncertainty — one month can bring high earnings, while the next month may be much lower.
Essential Overview: Guide to budget with an irregular income
Additionally, the biggest challenge is not only earning money; it is creating a system that works when your income changes.
Additionally, many people with irregular income make the mistake of spending more during good months and struggling during slow months. Furthermore, without a proper budgeting system, even a good income can disappear quickly.
Furthermore, for example, this is where irregular income budgeting becomes important.
Instead of creating a budget based on your highest earning month, you need a flexible system that helps you manage expenses, save money, and prepare for unpredictable income.
In this guide, you will learn a practical step-by-step method to create a budget for irregular income, including how to calculate your minimum monthly expenses, manage variable spending, build an income buffer, and create a stable financial plan.
Whether you are a freelancer, self-employed professional, business owner, content creator, or anyone with changing income, this guide will help you take control of your money.
Practical Steps & Actionable Tips for budget with an irregular income
Additionally, for example, for verified statutory guidelines and official consumer protections, refer to the Reserve Bank of India (RBI).
What You Will Learn in This Guide: Complete Guide to budget with an irregular income
In this complete guide to budgeting with irregular income, you will learn:
First, first, first, first, how to calculate your minimum monthly expenses.
Moreover, how to create a Survival Budget that works during low-income months.
Next, next, next, next, how to separate essential expenses from unnecessary spending.
Then, notably, how to manage variable income without financial stress.
Additionally, how to build an income buffer for unpredictable months.
Additionally, how to create a long-term money management system.
However, this guide focuses on practical strategies that you can apply immediately, not just general budgeting advice.
Whether your income changes every week, every month, or seasonally, these methods will help you create a flexible financial system.
Consequently, now let’s start with the first step: calculating your Minimum Monthly Expenses (Survival Budget).
Step 1: Calculate Your Minimum Monthly Expenses (Survival Budget): Complete Guide to budget with an irregular income
When your income changes every month, the first step is not deciding how much you should spend — it is understanding the minimum amount of money you actually need to run your life.
FREE INTERACTIVE TOOL
Freelancers & Gig Workers: Build Your Income Buffer
In fact, protect against dry months by calculating your exact lean-month survival fund and monthly baseline costs.
In addition, this amount is called your Survival Budget.
Moreover, your Survival Budget is the foundation of an effective irregular income budgeting system. It tells you the minimum money required to cover your essential expenses before you spend on lifestyle choices, entertainment, or other non-essential things.
However, for freelancers, self-employed professionals, business owners, and anyone with variable income, this system creates financial stability because you stop depending on your best earning months.
Why Your Survival Budget Is Important: Complete Guide to budget with an irregular income
Therefore, notably, many people with irregular income follow an unstable money pattern:
In fact, high-income month → Spend more → Low-income month → Financial stress
Additionally, the problem is not always income. The problem is not knowing your minimum financial requirement.
A Survival Budget helps you understand:
Furthermore, the minimum income you need every month.
Finally, which expenses must be protected first.
Specifically, for example, how much extra money you can save or invest.
Then, first, how to prepare for months when income is lower.
Particularly, for example, if your minimum monthly expenses are $1,800, then your first financial target is not buying luxury items or increasing your lifestyle — it is securing that $1,800 amount first.
Fixed Expenses: Complete Guide to budget with an irregular income
Overall, these expenses usually remain the same every month:
Consequently, rent or mortgage
Additionally, next, insurance
However, phone and internet bills
Then, loan payments
Essential Variable Expenses: Complete Guide to budget with an irregular income
Consequently, these expenses change but are necessary:
Additionally, in fact, groceries
Furthermore, transportation
Moreover, electricity
Finally, healthcare
Specifically, notably, household needs
Minimum Financial Payments: Complete Guide to budget with an irregular income
Furthermore, notably, include all payments you cannot skip:
Furthermore, first, credit card minimum payments
Additionally, loan installments
Finally, next, other required payments
How to Calculate Your Minimum Monthly Expenses: Complete Guide to budget with an irregular income
1. Overall, review Your Last 3–6 Months Spending: Complete Guide to budget with an irregular income
However, the first step is understanding your real spending pattern.
Specifically, as a result, check:
Then, for example, bank statements
Additionally, payment apps
Consequently, credit card history
Furthermore, expense tracking records
In fact, write down every expense, including small purchases.
Additionally, many people underestimate small expenses because they seem insignificant. However, repeated small spending can reduce your savings significantly over time.
2. Notably, separate Needs From Wants: Complete Guide to budget with an irregular income
Moreover, after collecting your expenses, divide them into two categories.
Essential Expenses (Needs): Complete Guide to budget with an irregular income
Furthermore, these are expenses required for your basic lifestyle:
However, housing
Finally, food
Specifically, in fact, utilities
Specifically, first, transportation
Moreover, healthcare
Then, first, next, insurance
Non-Essential Expenses (Wants): Complete Guide to budget with an irregular income
Specifically, notably, these expenses are optional:
Then, notably, eating outside
Additionally, entertainment
Additionally, shopping
Furthermore, premium subscriptions
Finally, for example, luxury purchases
Additionally, for example, for example, reducing unnecessary expenses does not mean removing all enjoyment. It means creating space for your important financial goals.
Example: Calculating Your Survival Budget: Complete Guide to budget with an irregular income
Additionally, imagine your monthly essential expenses are:
Category
Amount
Rent
$800
Food
$300
Utilities
$150
Transportation
$150
Insurance
$100
Debt Payment
$200
Total Survival Budget
$1,700
Consequently, your Survival Budget is $1,700 per month.
In addition, for example, this means you need at least $1,700 before spending money on optional things.
However, any income above this amount you can use for:
Specifically, emergency savings
Consequently, investments
Additionally, next, first, debt reduction
However, future low-income months
Common Mistakes To Avoid: Complete Guide to budget with an irregular income
Consequently, avoid these mistakes while creating your Survival Budget:
Then, next, planning your lifestyle around your highest income month.
Then, in fact, ignoring small recurring expenses.
Additionally, spending extra income immediately.
Moreover, not tracking your monthly cash flow.
Furthermore, mixing business and personal expenses.
A proper Survival Budget protects you from financial uncertainty and gives you more control over your money.
Action Plan: Create Your Survival Budget Today: Complete Guide to budget with an irregular income
Therefore, follow these steps:
Consequently, review your last 3–6 months of expenses. Write down every monthly cost. Separate needs and wants. Add only essential expenses. Calculate your Survival Budget number. Use this number as the base of your irregular income budget.
However, once you know your Survival Budget, the next step is to calculate your Baseline Income — the income level you should target to create a stable financial system even when your earnings change every month.
Step 2: Calculate Your Baseline Income: Complete Guide to budget with an irregular income
In fact, once you know your Survival Budget, the next step is to calculate your Baseline Income. This is one of the most important parts of budgeting with irregular income because it gives you a realistic income target instead of relying on your best earning month.
In fact, many people make the mistake of planning their budget around the highest amount they have ever earned. For example, if you earned $5,000 last month, it’s easy to assume you’ll earn the same again. But irregular income rarely works that way. Moreover, some months are excellent, while others are much slower.
Particularly, your Baseline Income is the amount you can reasonably expect to earn on a consistent basis. It becomes the foundation for your monthly budget, savings plan, and financial decisions. Instead of chasing unpredictable numbers, you build your budget around a realistic average that keeps your finances stable throughout the year.
Why Your Baseline Income Matters: Complete Guide to budget with an irregular income
A Baseline Income helps you answer one simple question:
“How much money can I safely plan to spend every month?”
Moreover, without knowing this number, it becomes easy to overspend during good months and struggle during slow months.
A realistic Baseline Income helps you:
Finally, notably, create a stable monthly budget.
Specifically, avoid lifestyle inflation.
Additionally, plan savings with confidence.
Additionally, first, reduce financial stress during low-income months.
Furthermore, next, for example, make better long-term financial decisions.
How to Calculate Your Baseline Income: Complete Guide to budget with an irregular income
1. Additionally, collect Your Income Records
Moreover, start by gathering your income from the last 6–12 months.
Overall, notably, this may include:
Then, client payments
Consequently, freelance income
Additionally, business revenue
However, commission earnings
Furthermore, side hustle income
Finally, in fact, part-time work
In addition, notably, the longer the time period you review, the more accurate your Baseline Income will be.
2. Furthermore, calculate Your Average Monthly Income
Additionally, add all your income from the past 6–12 months and divide it by the number of months.
Formula:
Baseline Income = Total Income ÷ Number of Months
However, as a result, example:
Month
Income
January
$3,500
February
$2,400
March
$4,100
April
$2,800
May
$3,200
June
$3,000
Total Income = $19,000
Baseline Income = $19,000 ÷ 6 = $3,166
Instead of budgeting as if you’ll earn $4,100 every month, you should build your budget around $3,166, because it reflects your average earning pattern.
Don’t Budget Using Your Best Month: Complete Guide to budget with an irregular income
Additionally, for example, one of the biggest financial mistakes is treating your highest-income month as your normal income.
A better strategy is:
Specifically, budget using your Baseline Income.
Moreover, save extra income during high-earning months.
Finally, first, use those savings to support low-income months.
Furthermore, this simple system creates consistency, even when your income is unpredictable.
Action Plan: Complete Guide to budget with an irregular income
Before moving to the next step, complete these tasks:
Specifically, review your last 6–12 months of income.
Furthermore, first, add every income source.
Finally, next, calculate your average monthly income.
Then, use this number as your Baseline Income.
Additionally, ignore unusually high-income months when creating your budget.
Next Step: Now that you know your Baseline Income, the next step is to prioritize your expenses using a flexible budgeting system that works even when your income changes every month.
Step 3: Prioritize Essential Expenses First: Complete Guide to budget with an irregular income
Consequently, now that you know your Survival Budget and Baseline Income, it’s time to decide where your money should go first.
Specifically, one of the biggest reasons people with irregular income struggle financially is not because they earn too little—but because they spend money in the wrong order.
However, many people pay for shopping, entertainment, subscriptions, or lifestyle upgrades as soon as they receive income. Later, when rent, groceries, or utility bills are due, they find themselves short of cash.
A better approach is to prioritize your expenses based on importance, not urgency.
Therefore, for example, this simple habit ensures that even during a low-income month, your essential needs are always covered before you spend money on anything optional.
Why Prioritizing Expenses Is So Important: Complete Guide to budget with an irregular income
When your income changes every month, you cannot afford to treat every expense equally.
In fact, some expenses keep your life running, while others simply make life more enjoyable.
If you pay for optional expenses before covering your basic needs, you’ll constantly feel financial pressure.
By prioritizing your expenses, you can:
Furthermore, next, notably, always pay your essential bills first.
Then, reduce financial stress during slow months.
Additionally, avoid relying on credit cards or loans.
Additionally, build better money habits.
Furthermore, for example, create a stable financial system even with unpredictable income.
Next Step: Now that your expenses are organized by priority, the next step is to build an Income Buffer that protects you during slow-income months and gives you greater financial confidence.
Step 4: Build an Income Buffer for Low-Income Months: Complete Guide to budget with an irregular income
By now, you’ve calculated your Survival Budget, estimated your Baseline Income, and learned how to prioritize essential expenses. The next step is creating an Income Buffer—a financial cushion that helps you stay stable during months when your income is lower than expected.
Particularly, as a result, for people with irregular income, earning less in some months is completely normal. The real problem begins when there is no money set aside to cover essential expenses. That’s where an Income Buffer becomes one of the most powerful tools in your budgeting system.
Instead of worrying about whether next month’s income will be enough, you can use the money you’ve saved during high-income months to cover the gap. This creates peace of mind and helps you avoid borrowing money or using credit cards for everyday expenses.
Why an Income Buffer Is Important
Moreover, an Income Buffer protects your monthly budget from unexpected income fluctuations.
Whether you’re a freelancer, self-employed professional, content creator, consultant, or seasonal worker, your income can change for many reasons—fewer clients, seasonal demand, delayed payments, or economic changes.
Additionally, without an Income Buffer, even a small drop in income can affect your ability to pay rent, buy groceries, or cover utility bills.
Furthermore, notably, with an Income Buffer, your financial life becomes much more predictable because you already have money reserved for slower months.
According to the Consumer Financial Protection Bureau (CFPB), setting aside money for unexpected situations helps reduce financial stress and improves long-term financial stability.
How to Build an Income Buffer
1. Set a Clear Savings Target
Specifically, start with a realistic goal.
If you’re just beginning, aim to save enough money to cover one month of your Survival Budget.
Additionally, once you reach that goal, gradually increase it to cover:
Moreover, one month of essential expenses.
Specifically, three months of essential expenses.
Additionally, next, first, first, notably, six months of essential expenses for greater financial security.
Moreover, for example, don’t try to save everything at once. Overall, building an Income Buffer is a gradual process.
2. For example, save Extra Income During High-Earning Months
Consequently, for example, one of the biggest advantages of irregular income is that some months can be much better than others.
Instead of increasing your lifestyle during those months, save a portion of the extra income.
In addition, for example:
Then, next, next, survival Budget: $2,000
Additionally, monthly Income: $3,500
Instead of spending the extra $1,500, move part of it into your Income Buffer.
Consequently, over time, these small contributions create a strong financial cushion.
3. Consequently, keep Your Income Buffer Separate
However, avoid keeping your Income Buffer in the same account you use for daily spending.
A separate high-yield savings account or dedicated savings account makes it less tempting to spend the money on non-essential purchases.
However, the FDIC Money Smart Program also encourages building healthy saving habits and keeping emergency savings separate from everyday spending.
4. Consequently, rebuild Your Buffer After Using It
Therefore, an Income Buffer is meant to be used when income falls—not for shopping, vacations, or impulse purchases.
If you use part of your buffer during a slow month, make rebuilding it your priority during the next high-income month.
In fact, this keeps your financial safety net ready for future income fluctuations.
Real-Life Example
In fact, imagine David is a freelance photographer.
Moreover, his average monthly income is around $3,200, but some months he earns only $1,800.
Particularly, his Survival Budget is $2,000.
During a busy wedding season, David saves an extra $600 every month into his Income Buffer.
A few months later, when business slows down, he uses the buffer to cover the difference instead of borrowing money or missing bill payments.
Because he planned ahead, his lifestyle remains stable even when his income changes.
Common Mistakes to Avoid
Moreover, notably, avoid these mistakes when building your Income Buffer:
Then, spending all extra income during good months.
Additionally, for example, keeping your buffer in your daily spending account.
Furthermore, using the buffer for luxury purchases.
Consequently, stopping contributions after reaching your first savings goal.
Finally, waiting for a financial emergency before starting to save.
Action Plan
Before moving to the next step, complete these tasks:
Then, calculate your first Income Buffer target.
Additionally, open a separate savings account if possible.
Furthermore, save a portion of every high-income month.
Finally, use the buffer only when your income falls below your normal level.
Specifically, rebuild your buffer immediately after using it.
Overall, for more practical guidance on building emergency savings and financial resilience, you can also explore: MyMoney.gov – Emergency Funds.
Next Step: Once you have an Income Buffer in place, the next step is to create a Zero-Based Budget so every dollar you earn has a clear purpose and nothing is wasted.
Step 5: Use the Zero-Based Budgeting Method
Additionally, now that you have a Survival Budget, a realistic Baseline Income, prioritized your expenses, and built an Income Buffer, it’s time to give every dollar a specific purpose.
Overall, notably, this is where the Zero-Based Budgeting Method becomes one of the most effective budgeting strategies for people with irregular income.
Despite its name, Zero-Based Budgeting does not mean your bank account should reach zero. It simply means every dollar you earn is assigned a job before you spend it.
Instead of wondering where your money went at the end of the month, you decide in advance where every dollar will go. This gives you complete control over your finances and reduces unnecessary spending.
Why Zero-Based Budgeting Works for Irregular Income
When your income changes every month, spending money without a plan can quickly create financial problems.
Furthermore, notably, as a result, for example, zero-Based Budgeting helps you:
However, give every dollar a clear purpose.
Specifically, avoid impulse spending.
Additionally, first, first, in fact, control lifestyle inflation.
Furthermore, next, next, save consistently during high-income months.
Moreover, stay organized even when your income fluctuates.
Unlike traditional budgeting, this method is flexible. However, each month, you create a new budget based on the income you actually expect to receive instead of using the same budget every month.
Consequently, this doesn’t mean you’ve spent all your money.
Furthermore, it means every dollar has already been assigned to a category before you begin spending.
However, for example:
Monthly Baseline Income: $3,200
Then, housing: $900
Additionally, notably, groceries: $350
Furthermore, utilities: $180
Additionally, transportation: $170
Finally, insurance: $120
Specifically, for example, debt Payments: $200
Then, first, emergency Savings: $300
Consequently, investments: $400
Additionally, next, personal Spending: $280
However, miscellaneous: $300
Money Remaining = $0
Specifically, every dollar now has a purpose.
How to Apply Zero-Based Budgeting
1. Therefore, start With Your Baseline Income
In fact, never create your budget using your highest earning month.
Instead, use the Baseline Income you calculated in Step 2.
Specifically, as a result, for example, this makes your budget realistic and easier to follow.
2. As a result, fund Essential Expenses First
Moreover, your first responsibility is covering your Survival Budget.
Consequently, always fund:
Then, housing
Additionally, in fact, food
Furthermore, utilities
Moreover, transportation
Finally, insurance
Specifically, notably, minimum debt payments
In addition, notably, only after these expenses are covered should you move to savings, investing, and lifestyle spending.
3. Particularly, give Every Remaining Dollar a Job
However, extra income should never remain “unplanned.”
Additionally, assign every remaining dollar to one of these categories:
Furthermore, first, income Buffer
Additionally, emergency Fund
Finally, next, investments
Then, for example, debt repayment
Additionally, business growth
Consequently, personal goals
A clear plan prevents unnecessary spending and keeps your financial priorities on track.
Real-Life Example
Therefore, sarah is a freelance graphic designer.
In fact, for example, her Baseline Income is $2,800 per month.
Instead of spending money as clients pay her, she creates a Zero-Based Budget before the month begins.
Particularly, she first funds her essential expenses, then adds money to her Income Buffer, contributes to her investments, and finally sets aside a small amount for entertainment.
When unexpected expenses arise, she already knows where her money is allocated, so she avoids using credit cards unnecessarily.
Common Mistakes to Avoid
Consequently, avoid these common mistakes:
Furthermore, creating a budget after spending your money.
However, forgetting to budget for savings.
Finally, leaving extra income without a purpose.
Specifically, in fact, budgeting based on your highest-income month.
Specifically, first, not reviewing your budget when your income changes.
Next Step: Now that every dollar has a purpose, the next step is learning how to manage separate bank accounts for spending, savings, and taxes, making your irregular income even easier to control.
Step 6: Create Separate Accounts for Spending, Savings, and Taxes
Overall, one of the smartest habits of people who successfully manage irregular income is keeping their money organized. Instead of using one bank account for everything, they divide their money into separate accounts with a specific purpose.
When all of your income stays in one account, it’s easy to lose track of how much money is actually available to spend. You may accidentally use money meant for taxes, emergency savings, or future bills.
In fact, creating separate accounts gives every part of your money a clear destination. This simple system reduces financial mistakes, improves cash flow, and makes budgeting much easier.
Why Separate Bank Accounts Matter
Additionally, notably, people with fixed salaries usually know exactly when and how much money they will receive. However, freelancers, self-employed professionals, creators, consultants, and small business owners often receive payments at different times and in different amounts.
Moreover, without a clear system, all your income mixes together, making it difficult to know:
Moreover, how much you can safely spend.
Specifically, next, how much should be saved.
Then, notably, how much belongs to future taxes.
Additionally, how much is available for investing.
Furthermore, as a result, separating your money creates financial discipline and reduces the temptation to spend savings on everyday purchases.
According to the Consumer Financial Protection Bureau (CFPB), organizing your finances and planning ahead can make budgeting easier and help you stay on track with your financial goals.
The 4-Account Money Management System
Additionally, notably, you don’t need dozens of accounts. For most people with irregular income, four accounts are enough.
1. Moreover, spending Account
Furthermore, this is your everyday account.
Additionally, use it only for:
Additionally, rent
Furthermore, groceries
Finally, for example, utilities
Specifically, transportation
Consequently, healthcare
Furthermore, first, first, first, daily living expenses
Specifically, transfer only your planned monthly spending amount into this account.
Specifically, for example, for example, once the money is used, avoid moving extra money from your savings unless it’s absolutely necessary.
2. Additionally, emergency Savings Account
Consequently, this account is for unexpected situations, not everyday spending.
Consequently, examples include:
However, medical emergencies
Finally, next, next, next, emergency home repairs
Then, in fact, temporary income loss
Additionally, unexpected travel
In addition, keep this money separate so you’re less likely to spend it impulsively.
3. Tax Account
If you’re self-employed, a freelancer, or a business owner, taxes should never be treated as spending money.
However, every time you receive a payment, move a percentage into a dedicated tax account.
However, this simple habit prevents financial stress when tax payments become due.
Next Step: Once your money is organized into separate accounts, the next step is learning how to save more during high-income months so you can stay financially secure when income slows down.
Step 7: Save Extra Income During High-Earning Months
Furthermore, one of the biggest advantages of having an irregular income is that some months can bring significantly higher earnings than others. However, this advantage can quickly become a financial problem if you spend the extra money instead of preparing for future slow months.
In fact, many freelancers, business owners, creators, and self-employed professionals celebrate a high-income month by upgrading their lifestyle. As a result, they buy expensive gadgets, eat out more often, or increase their monthly spending. When the next month brings lower income, they struggle to pay even their essential bills.
A smarter strategy is to treat every high-income month as an opportunity to strengthen your financial future—not your lifestyle.
Why Saving Extra Income Is So Important
Specifically, irregular income is unpredictable by nature. You cannot always control when clients pay you, how much business you’ll receive, or whether demand will slow down.
Moreover, what you can control is what you do with the extra money you earn during good months.
In addition, for example, saving part of your extra income helps you:
Additionally, prepare for low-income months.
Additionally, reduce financial stress.
Furthermore, for example, avoid unnecessary debt.
Finally, build long-term financial security.
Consequently, reach your financial goals faster.
According to the Consumer Financial Protection Bureau (CFPB), consistently setting aside money improves financial resilience and helps people handle unexpected financial challenges.
Follow the “Save First, Spend Later” Rule
Consequently, notably, many people save whatever money is left at the end of the month.
In addition, successful money management works the opposite way.
Additionally, as soon as you receive a larger-than-normal payment:
Specifically, cover your essential expenses.
However, add money to your Income Buffer.
Furthermore, first, increase your emergency savings.
Finally, next, in fact, invest toward your long-term goals.
Then, spend only the remaining amount.
However, this approach ensures that your future is funded before your lifestyle.
How Much Should You Save?
Therefore, for example, there isn’t one percentage that works for everyone, but having a target makes saving easier.
In fact, for example:
Moreover, save 20–30% of extra income if you’re still building an Income Buffer.
Additionally, save 30–50% if your emergency savings are not yet complete.
Furthermore, notably, invest a portion after your essential savings goals are covered.
Consequently, the exact percentage depends on your financial situation, but consistency matters more than perfection.
Real-Life Example
Particularly, imagine Alex owns a small online business.
However, his average monthly income is $3,000, but during a holiday season he earns $5,500.
Instead of increasing his spending, Alex follows a simple plan:
Finally, pays all essential expenses.
Additionally, adds money to his Income Buffer.
Specifically, increases his emergency savings.
Specifically, first, for example, invests part of the remaining income.
Furthermore, first, next, keeps a small amount for personal enjoyment.
A few months later, when sales slow down, he continues paying his bills without financial stress because he planned ahead.
Common Mistakes to Avoid
Moreover, avoid these common mistakes during high-income months:
Consequently, assuming every month will be equally profitable.
Then, increasing your lifestyle too quickly.
However, spending bonuses immediately.
Additionally, ignoring future slow seasons.
Furthermore, in fact, saving only when it’s convenient.
In fact, small, consistent decisions during good months often determine your financial stability during difficult months.
Action Plan
Overall, complete these steps whenever you earn more than usual:
Finally, next, cover your Survival Budget first.
Then, add money to your Income Buffer.
Additionally, increase your emergency savings.
Furthermore, invest toward your long-term goals.
Finally, spend only what remains after your priorities are funded.
Moreover, for additional guidance on building healthy saving habits, you can also explore: MyMoney.gov – Save Money.
Next Step: Now that you’ve learned how to use high-income months wisely, the next step is to track your income and expenses regularly so you can identify spending patterns and improve your budget over time.
Step 8: Track Your Income and Expenses Every Week
However, notably, creating a budget is only the beginning. The real difference comes from tracking your income and expenses consistently.
Therefore, as a result, notably, for people with irregular income, waiting until the end of the month to review finances is often too late. By then, you may have already overspent or missed opportunities to save.
A simple weekly money review helps you stay in control of your cash flow, spot spending problems early, and make better financial decisions before small mistakes become expensive ones.
Instead of asking, “Where did all my money go?”, you’ll know exactly where every dollar was earned and spent.
Why Weekly Tracking Is Better Than Monthly Tracking
When your income changes every month, your financial situation can change quickly.
Additionally, you might receive several client payments in one week and nothing in the next. If you only check your finances once a month, it’s easy to lose control of your spending.
A weekly review helps you:
Finally, monitor your cash flow.
Moreover, stay within your budget.
Specifically, identify unnecessary expenses.
Specifically, first, notably, track progress toward your savings goals.
Specifically, first, next, adjust your budget before problems grow.
According to the Consumer Financial Protection Bureau (CFPB), regularly reviewing your income and expenses helps you make informed financial decisions and stay on track with your budget.
What Should You Track Every Week?
Additionally, you don’t need complicated software. A simple spreadsheet, budgeting app, or notebook is enough.
Furthermore, focus on these four areas:
1. Specifically, income Received
Specifically, for example, record every payment you receive, including:
Additionally, freelance payments
Then, business income
Additionally, for example, salary
Furthermore, side hustle earnings
Consequently, commissions
Finally, passive income
In fact, for example, tracking income helps you compare your actual earnings with your expected Baseline Income.
2. Furthermore, essential Expenses
Consequently, review all necessary spending, such as:
However, rent
Specifically, groceries
Specifically, first, next, first, in fact, utilities
Then, next, transportation
Moreover, insurance
Then, healthcare
Consequently, this ensures your Survival Budget stays under control.
3. Non-Essential Spending
However, track optional expenses like:
Additionally, notably, dining out
Furthermore, shopping
Additionally, entertainment
Finally, subscriptions
Specifically, for example, online purchases
In addition, small purchases may seem harmless individually, but together they can significantly reduce your savings.
4. Specifically, savings and Investments
In fact, every week, ask yourself:
Additionally, first, did I add money to my Income Buffer?
Consequently, did Always contribute to my emergency savings?
Furthermore, next, did Ensure you invest toward my long-term goals?
However, tracking progress keeps your financial goals visible and motivates you to stay consistent.
Create a Simple Weekly Money Review
Moreover, choose one day each week—such as Sunday evening—and spend 15 to 20 minutes reviewing your finances.
Therefore, ask yourself these questions:
However, how much money did I earn this week?
Then, where did Clearly spend the most?
Additionally, in fact, were all my expenses necessary?
Furthermore, did I follow my budget?
Moreover, what should I improve next week?
A short review every week is much easier than trying to fix an entire month’s financial mistakes.
Real-Life Example
In fact, notably, sophia is a freelance writer whose income changes every month.
Before tracking her finances weekly, she often forgot about small subscriptions and online purchases.
Particularly, after creating a 20-minute weekly review, she discovered she was spending over $150 every month on services she rarely used.
By canceling unnecessary subscriptions, she redirected that money into her Income Buffer and emergency savings.
Common Mistakes to Avoid
Additionally, avoid these common mistakes:
Finally, reviewing finances only at the end of the month.
Specifically, notably, ignoring small daily expenses.
Finally, first, forgetting to record cash payments.
Additionally, tracking expenses but never reviewing them.
Specifically, next, giving up after missing one week.
Moreover, remember, consistency is more valuable than perfection.
Action Plan
Overall, for example, complete these steps every week:
First, next, first, record every source of income.
Then, next, review essential and non-essential expenses.
Then, compare your spending with your budget.
Additionally, update your savings and investment progress.
Furthermore, make one small improvement for the following week.
Next Step: After tracking your finances consistently, the final step is to review and adjust your budget every month so it continues to work as your income and financial goals change.
Step 9: Review and Adjust Your Budget Every Month
A budget is not something you create once and forget. It should evolve as your income, expenses, and financial goals change. This is especially important if you have an irregular income, where no two months are exactly the same.
A monthly budget review helps you identify what worked, what didn’t, and what needs to change. Instead of repeating the same financial mistakes, you improve your budgeting system every month.
Consequently, think of your budget as a living financial plan—not a fixed document.
Why You Should Review Your Budget Every Month
Moreover, as a result, even if you followed your budget perfectly this month, your financial situation may be different next month.
However, for example:
Then, for example, you may earn more or less than expected.
Additionally, your rent or utility bills may increase.
Consequently, you may have unexpected medical expenses.
Furthermore, you may reach a savings goal and set a new one.
Additionally, reviewing your budget regularly allows you to adapt instead of reacting.
According to the Consumer Financial Protection Bureau (CFPB), reviewing your spending plan regularly helps you make better financial decisions and stay aligned with your goals.
How to Review Your Budget
1. For example, compare Your Planned Budget With Actual Spending
In fact, start by comparing what you planned to spend with what you actually spent.
Furthermore, ask yourself:
However, which categories stayed within budget?
Finally, which categories exceeded the budget?
Specifically, in fact, why did those differences happen?
Moreover, the goal is not perfection—it is learning from your spending habits.
2. Consequently, review Your Income
Specifically, compare your actual monthly income with your Baseline Income.
Then, notably, use your Income Buffer if necessary.
Additionally, avoid unnecessary debt.
3. In addition, update Your Financial Goals
Overall, for example, notably, your goals will change over time.
Consequently, for example, after completing your emergency fund, you may decide to focus on:
Additionally, investing.
Furthermore, paying off debt.
Finally, for example, saving for a home.
Specifically, growing your business.
Consequently, learning new skills.
Additionally, your budget should always support your current priorities.
Questions to Ask Every Month
At the end of each month, answer these questions honestly:
Additionally, first, first, did I follow my budget?
However, which expenses were unnecessary?
Furthermore, next, next, did I save enough?
Then, in fact, did Consistently invest consistently?
Additionally, what financial habit should I improve next month?
In addition, these simple questions help you improve your budgeting system month after month.
Real-Life Example
However, for example, michael is a self-employed photographer.
At the end of every month, he spends 30 minutes reviewing his finances.
Therefore, one month, he notices that transportation costs are much higher than expected because of extra client visits.
Instead of ignoring the problem, he increases that category in next month’s budget while reducing entertainment expenses.
Consequently, this small adjustment keeps his overall budget balanced without affecting his savings goals.
Common Mistakes to Avoid
In fact, avoid these common mistakes:
Moreover, never reviewing your budget.
Furthermore, ignoring overspending.
Finally, notably, making unrealistic budget changes.
Specifically, forgetting to adjust for income changes.
Additionally, giving up after one difficult month.
However, remember, a budget should improve over time. Small monthly adjustments often produce better long-term results than making major changes once a year.
Action Plan
At the end of every month:
Then, compare planned spending with actual spending.
Additionally, review your monthly income.
Furthermore, identify unnecessary expenses.
Finally, update your savings and investment goals.
Specifically, adjust next month’s budget based on what you learned.
Next Step: After building a budgeting system that adapts to changing income, the final step is to focus on long-term financial stability through emergency savings, investing, and continuous financial planning.
Step 10: Build Long-Term Financial Stability
In fact, creating a budget for irregular income is not just about paying this month’s bills—it’s about building a financial system that continues to support you for years to come. Therefore, once you’ve learned how to calculate your Survival Budget, estimate your Baseline Income, prioritize expenses, build an Income Buffer, and track your spending, the final step is turning these habits into long-term financial stability.
Moreover, financial stability doesn’t mean earning a huge income. It means having enough control over your money that unexpected events don’t completely disrupt your life. Whether you earn $2,000 or $10,000 a month, consistent financial habits will always matter more than occasional high-income months.
Why Long-Term Financial Planning Matters
Moreover, people with irregular income often focus only on the next payment. While this is understandable, constantly thinking short-term makes it difficult to build wealth.
A long-term financial plan helps you:
Finally, first, first, stay financially secure during income fluctuations.
Specifically, next, next, for example, reduce money-related stress.
Then, build wealth gradually.
Consequently, achieve important life goals.
Additionally, become financially independent over time.
According to the Investor.gov, investing consistently over time is one of the most effective ways to build long-term wealth.
Build Your Long-Term Financial System
Instead of relying only on budgeting, combine budgeting with saving, investing, and goal planning.
1. In fact, maintain Your Emergency Fund
Overall, your emergency fund is your first line of financial protection.
Consequently, notably, notably, notably, aim to keep enough money to cover at least three to six months of essential living expenses.
In addition, as a result, as a result, use this money only for genuine emergencies, such as:
However, medical expenses
Furthermore, temporary income loss
Finally, in fact, major home or vehicle repairs
Specifically, unexpected family emergencies
Additionally, continue rebuilding the fund whenever you need to use it.
2. In addition, invest Consistently
Additionally, once your emergency savings are in place, start investing regularly.
Furthermore, for example, you don’t need to invest a large amount.
Specifically, the most important habit is consistency.
Consequently, depending on your financial goals, you may choose investments such as:
Moreover, index funds
Then, first, mutual funds
Additionally, next, notably, retirement accounts
Then, other diversified long-term investments
If you’re new to investing, begin with research and invest according to your risk tolerance and financial objectives.
3. Moreover, continue Learning About Personal Finance
Additionally, for example, financial success is a continuous learning process.
However, make time to improve your knowledge about:
Additionally, budgeting
Additionally, saving
Furthermore, for example, investing
Finally, taxes
Consequently, debt management
Specifically, retirement planning
Consequently, the more you understand money, the better financial decisions you’ll make throughout your life.
4. Overall, review Your Financial Goals Every Year
In fact, your priorities will change over time.
In addition, once a year, review your goals and ask yourself:
However, have my financial priorities changed?
Furthermore, first, am I saving enough?
Finally, next, in fact, am I investing consistently?
Then, do I need to increase my Income Buffer?
Moreover, what is my next financial milestone?
Moreover, regular reviews help ensure your money continues working toward your future goals.
Real-Life Example
However, emma is a self-employed photographer whose income changes throughout the year.
A few years ago, she lived from one payment to the next.
Therefore, notably, today, she follows a complete financial system.
In fact, she maintains an emergency fund, invests a portion of every profitable month, reviews her budget monthly, and adjusts her financial goals every year.
Although her income is still irregular, her financial life is far more stable because her habits—not her income—create consistency.
Common Mistakes to Avoid
Additionally, avoid these long-term financial mistakes:
Additionally, stopping your budget after reaching one savings goal.
Furthermore, notably, ignoring investing.
Finally, depending entirely on one source of income.
Additionally, never reviewing your financial goals.
Specifically, assuming high income automatically leads to wealth.
Particularly, financial stability is built through consistent decisions, not occasional success.
Action Plan
Moreover, for example, complete these long-term financial habits:
Specifically, maintain an emergency fund covering 3–6 months of essential expenses.
Next, first, first, invest consistently, even if you start with a small amount.
Then, next, next, continue improving your financial knowledge.
Then, review your financial goals every year.
Additionally, keep updating your budgeting system as your income and lifestyle change.
Overall, for trusted financial education and long-term investing guidance, you can explore: Investor.gov and MyMoney.gov.
Final Thoughts
Consequently, budgeting with irregular income may seem challenging at first, but it becomes much easier when you follow a proven system. By calculating your Survival Budget, estimating your Baseline Income, prioritizing essential expenses, building an Income Buffer, using Zero-Based Budgeting, organizing your accounts, saving during high-income months, tracking your finances, and reviewing your budget regularly, you can take control of your money with confidence.
Furthermore, notably, remember, financial success isn’t determined by earning the same income every month—it’s determined by how consistently you manage the income you have. However, start with one step today, stay disciplined, and improve your system over time. As a result, small actions repeated consistently can lead to lasting financial freedom.
Practical Steps & Actionable Tips for budget with an irregular income
What is the best budgeting method for irregular income
What is the best budgeting method for irregular income? The best budgeting method for irregular income is to combine a Survival Budget, Baseline Income, Income Buffer, and Zero-Based Budgeting. This system helps you cover essential expenses first, save during high-income months, and stay financially stable even when your income changes. FAQ 2 How much emergency savings should Proactively have if my income is irregular? A good goal is to save at least three to six months of essential living expenses. If you're just starting, aim to build one month of expenses first and gradually increase your emergency fund over time. FAQ 3 Should I budget based on my highest-income month? No. Additionally, budgeting based on your highest-income month can lead to overspending during slower months. Instead, calculate your Baseline Income using your average earnings from the last 6–12 months and build your budget around that amount. FAQ 4 How often should Regularly review my budget if Directly have irregular income? Therefore, review your budget every week to track income and expenses, and complete a full budget review at the end of each month. Specifically, regular reviews help you adjust your spending, improve savings, and stay on track with your financial goals. Key Takeaway 1 Know your Survival Budget before making any spending decisions. Key Takeaway 2 Save extra income during high-earning months instead of increasing your lifestyle. Key Takeaway 3 Track your income and expenses consistently because what gets measured gets managed. Key Takeaway 4 Review and improve your budget every month to keep it aligned with your changing income and financial goals.
Actionable Insights and Smart Advice for budget with an irregular income
Actionable Insights and Smart Advice for budget with an irregular income
Actionable Insights and Smart Advice for budget with an irregular income
Conclusion
However, budgeting with irregular income may seem difficult at first, but it becomes much easier when you follow a proven system instead of relying on guesswork. The goal isn’t to predict exactly how much you’ll earn every month—it’s to build a financial plan that works whether your income is high or low.
By calculating your Survival Budget, estimating your Baseline Income, prioritizing essential expenses, building an Income Buffer, using Zero-Based Budgeting, organizing separate accounts, saving more during high-income months, tracking your finances weekly, and reviewing your budget regularly, you can create a stable financial system that grows with you.
Specifically, as a result, remember, financial success doesn’t depend on having a fixed salary. It depends on making consistent, smart decisions with the money you earn. For example, even small improvements, repeated every month, can lead to greater financial security, less stress, and long-term wealth.
Practical Steps & Actionable Tips for budget with an irregular income
In fact, start with the first step today. You don’t need a perfect budget—you just need a system that you can follow consistently. In fact, over time, those small habits will help you take full control of your finances, no matter how unpredictable your income may be.
Article Summary If your income changes every month, creating a traditional budget may not work. Instead, you need a flexible budgeting system designed specifically for irregular income. In this guide, you learned how to calculate your Survival Budget, estimate your Baseline Income, prioritize essential expenses, build an Income Buffer, use the Zero-Based Budgeting Method, organize separate bank accounts, save more during high-income months, track your finances every week, review your budget every month, and build long-term financial stability. By following these 10 practical steps, you can reduce financial stress, avoid overspending, prepare for low-income months, and make smarter financial decisions. The key is not earning the same amount every month—it’s creating a money management system that adapts to changing income while helping you save, invest, and achieve your long-term financial goals. Whether you’re a freelancer, self-employed professional, small business owner, content creator, or anyone with variable income, this budgeting method can help you stay in control of your money and build lasting financial confidence.
Actionable Advice and Practical Tips for budget with an irregular income
Hi, Make sure you am Asif Khan, founder and lead research editor at PaisaKmao.de. In addition, over the past 3 to 4 years of active personal finance research and real-money investing in Indian markets, Always have navigated the practical realities of building an investment portfolio from scratch—from starting with small student pocket money, learning from early market mistakes (penny stocks, dividend tax surprises, and hidden DP charges), to establishing disciplined SIPs in low-cost index funds and managing risk. My mission with PaisaKmao.de is to provide 100% transparent, math-backed financial guides and practical calculators so young investors can build long-term wealth without falling into common traps.
Written & Researched by Asif Khan
Written & Researched by Asif Khan
Founder & Lead Financial Editor PaisaKmao.de
Furthermore, over 4 years of active personal finance research in Indian markets. In fact, focused on transparent, math-backed guides to help students and young professionals build wealth and manage money smartly.