Financial Planning for Beginners (2026): 10 Simple Steps

Financial Planning for Beginners (2026): 10 Simple Steps to Build Wealth infographic

Introduction

Managing money isn’t just about earning more—it’s about making smart financial decisions that help you build a secure future. Unfortunately, many people struggle with budgeting, saving, investing, and managing debt because they don’t have a clear financial plan. That’s why Financial Planning for Beginners is one of the most important skills anyone can learn, regardless of their income or financial background.

Whether you’re a student, a young professional, a freelancer, or simply looking to take control of your finances, financial planning provides a clear roadmap for managing your money with confidence. It helps you set realistic financial goals, create a practical budget, build an emergency fund, reduce financial stress, and make informed investment decisions that support long-term wealth.

In this complete guide, you’ll learn the 10 simple steps of Financial Planning for Beginners, along with practical strategies, real-world examples, and actionable tips that you can apply immediately. By the end of this article, you’ll have a step-by-step financial roadmap to make smarter money decisions, avoid common financial mistakes, and build a stronger financial future.

What Is Financial Planning?

Financial planning is the strategic process of managing your income, expenses, savings, investments, insurance, taxes, and future financial goals to achieve long-term financial security. Instead of making random money decisions, it provides a structured roadmap that helps you spend wisely, save consistently, invest intelligently, and prepare for life’s expected and unexpected financial challenges.

For beginners, financial planning is not about becoming rich overnight or making complicated investments. It starts with understanding your current financial situation, setting realistic goals, creating a budget, building an emergency fund, managing debt, and investing consistently. Whether you’re a student, a salaried employee, a freelancer, or a business owner, having a financial plan gives every dollar a purpose and helps you make smarter financial decisions.

Think of financial planning as a GPS for your financial journey. Just as you wouldn’t start a long road trip without knowing your destination, you shouldn’t make important money decisions without a clear financial plan. A proper plan keeps you focused on your goals while reducing financial stress and avoiding costly mistakes.

Why Is Financial Planning Important?
Financial planning helps you stay in control of your money instead of letting your money control you. It creates a balance between your current lifestyle and your future financial goals while protecting you from unexpected financial emergencies.

  • Helps you understand your complete financial situation.
  • Creates a realistic monthly budget.
  • Builds an emergency fund for unexpected expenses.
  • Reduces unnecessary debt and financial stress.
  • Improves your saving habits.
  • Helps you invest according to your goals.
  • Protects your family with proper insurance planning.
  • Builds long-term wealth through disciplined investing.
  • Prepares you for retirement and major life events.

Key Components of Financial Planning

A successful financial plan consists of several interconnected areas. Ignoring even one of them can affect your overall financial health.

1. Income Management

The first step is understanding your income sources and managing them efficiently. Knowing exactly how much money you earn each month allows you to create realistic financial goals and spending plans.

2. Budgeting and Expense Management

A monthly budget helps you track every expense, eliminate unnecessary spending, and ensure your money is being used according to your priorities. If you’re new to budgeting, read our How to Budget with an Irregular Income: Step-by-Step Guide (2026)

3. Saving and Emergency Fund

Saving money regularly creates financial stability. Building an Save Money Fast in 30 Days (2026): 15 Proven Strategies That Actually Workprotects you from unexpected situations such as medical emergencies, job loss, or major repairs without relying on debt.

4. Debt Management

Managing debt wisely allows more of your income to be used for saving and investing instead of paying interest. Paying off high-interest debt should always be a priority.

5. Investment Planning

Investing helps your money grow over time and protects it against inflation. If you’re just getting started, our explains the basics in simple language.

6. Insurance and Risk Management

Insurance protects your financial future from unexpected events. Health, life, and disability insurance reduce financial risk and protect your long-term wealth.

7. Retirement Planning

Retirement planning ensures financial independence later in life. Starting early allows compound growth to work in your favor, making it easier to build long-term wealth.

Financial Planning vs Budgeting vs Investing

Financial PlanningBudgetingInvesting
Creates an overall financial roadmap.Controls monthly income and expenses.Grows your wealth over time.
Focuses on long-term financial goals.Focuses on short-term cash flow.Focuses on increasing asset value.
Includes budgeting, saving, insurance, debt, and investing.Focuses mainly on spending and saving.Focuses on stocks, mutual funds, ETFs, bonds, and other investments.

Real-Life Example

Imagine two friends earning the same salary. The first spends money without tracking expenses, saves only when money is left over, and invests randomly. The second creates a budget, builds an emergency fund, pays off high-interest debt, invests every month, and reviews financial goals regularly. After several years, the second person is far more likely to achieve financial stability and long-term wealth—not because they earned more, but because they followed a financial plan.

Common Myths About Financial Planning

  • Financial planning is only for wealthy people.
  • You need a high income before creating a financial plan.
  • Financial planning only means investing in the stock market.
  • Budgeting alone is enough to achieve financial success.
  • Financial planning is something you only do once.

In reality, financial planning is a continuous process that evolves as your income, expenses, responsibilities, and financial goals change over time.

Expert Tips for Beginners

  • Pay yourself first by saving before spending.
  • Review your budget every month.
  • Build an emergency fund before making risky investments.
  • Invest consistently instead of trying to time the market.
  • Review your financial plan at least once every six months.

Quick Checklist

  • ✔ Know your monthly income.
  • ✔ Track your expenses.
  • ✔ Create a realistic budget.
  • ✔ Build an emergency fund.
  • ✔ Eliminate high-interest debt.
  • ✔ Start investing consistently.
  • ✔ Protect yourself with insurance.
  • ✔ Review your financial plan regularly.

Key Takeaways

  • Financial planning is a complete strategy for managing money effectively.
  • It combines budgeting, saving, investing, insurance, debt management, and retirement planning.
  • Anyone can start financial planning regardless of income.
  • Small, consistent financial decisions often produce significant long-term results.
  • Reviewing and improving your financial plan regularly is essential for achieving financial success.

According to the Consumer Financial Protection Bureau (CFPB), creating a financial plan and maintaining healthy financial habits can help individuals make informed financial decisions and prepare for future financial needs. For investor education, the U.S. Securities and Exchange Commission’s Investor.gov provides reliable educational resources on investing and financial planning.

Now that you understand what financial planning is, let’s explore why financial planning is important and how it can transform your financial future.

Why Is Financial Planning Important?
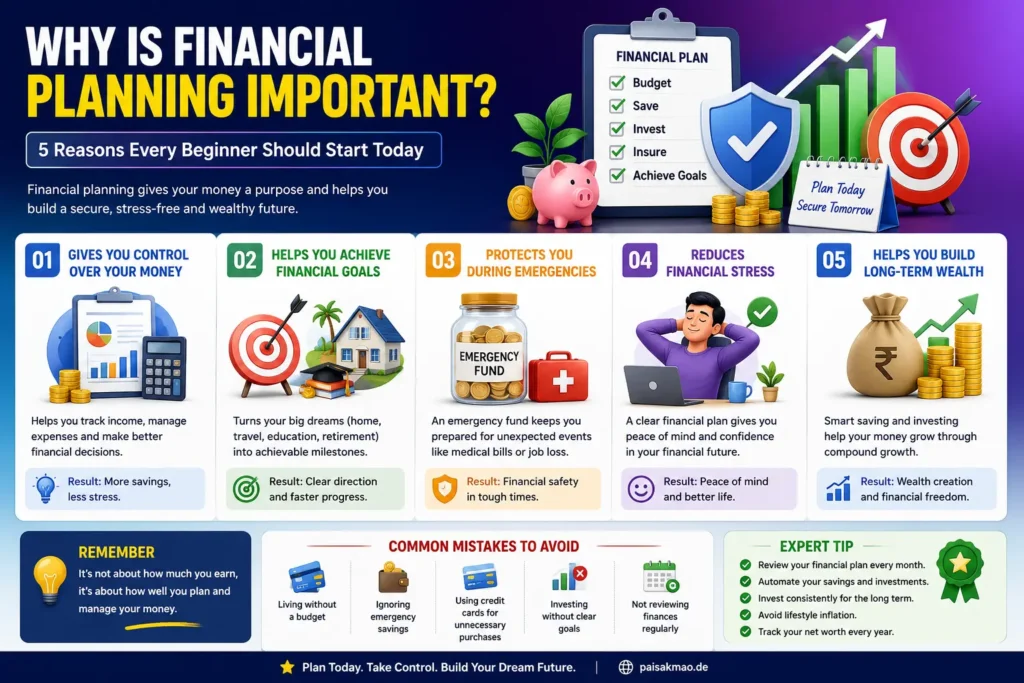
Financial planning is more than just saving money—it is about creating a roadmap for your financial future. Without a proper plan, even people with high incomes can struggle to achieve financial freedom because they spend without clear priorities. A well-designed financial plan helps you manage your income wisely, prepare for emergencies, reduce debt, build wealth, and achieve long-term financial goals with confidence.

Whether you are a student, salaried employee, freelancer, or business owner, financial planning gives every dollar a purpose. Instead of wondering where your money disappeared each month, you gain complete control over your finances and make decisions that support your future.

If you’re finding it difficult to control your monthly expenses, read our How to Manage Your Salary guide to build a stronger financial foundation.

1. Gives You Complete Control Over Your Money

Financial planning allows you to understand exactly how much money you earn, spend, save, and invest. This awareness helps eliminate unnecessary expenses and improves your financial discipline.

  • Track monthly income and expenses.
  • Reduce impulse spending.
  • Create better money habits.
  • Increase monthly savings.

2. Helps You Achieve Financial Goals Faster

Whether your goal is buying a house, starting a business, traveling the world, or retiring early, financial planning breaks large goals into smaller, achievable milestones.

Examples of Financial Goals

  • Build a $1,000 emergency fund.
  • Save for higher education.
  • Buy your first home.
  • Become debt-free.
  • Create passive income.
  • Retire comfortably.

3. Protects You During Financial Emergencies

Unexpected events such as medical bills, job loss, or major repairs can disrupt your finances. A financial plan includes an emergency fund that helps you handle these situations without relying on high-interest debt.

Learn practical saving strategies in our How to Save Money Fast in 30 Days guide.

4. Reduces Financial Stress

Money is one of the biggest causes of stress. When you know your financial position and have a clear action plan, you feel more confident and make better financial decisions.

5. Helps You Build Long-Term Wealth

Saving alone is not enough. Financial planning combines budgeting, saving, investing, insurance, and tax planning to help your money grow over time through compound growth.

If you’re ready to start investing, read our Best Investments for College Students with $100 guide.

Common Mistakes Beginners Make

  • Living without a monthly budget.
  • Ignoring emergency savings.
  • Using credit cards for unnecessary purchases.
  • Investing without clear goals.
  • Not reviewing finances regularly.

Expert Tips

  • Review your financial plan every month.
  • Automate your savings.
  • Invest consistently for the long term.
  • Avoid lifestyle inflation as your income grows.
  • Track your net worth every year.

Key Takeaways

  • Financial planning gives your money a clear direction.
  • It helps you achieve goals while reducing financial stress.
  • Emergency savings and investing are equally important.
  • Consistent planning leads to long-term financial security.

According to the Consumer Financial Protection Bureau (CFPB), creating a financial plan and reviewing it regularly helps individuals make informed financial decisions and prepare for future financial needs.

Next, let’s understand the 10 simple steps you can follow to create your own financial plan from scratch.

Step 3: Build an Emergency Fund Before You Invest

One of the biggest financial mistakes beginners make is investing before creating an emergency fund. While investing helps grow your wealth, it cannot replace cash that is immediately available during unexpected situations.

An emergency fund acts as your financial safety net. It protects you from debt, high-interest loans, and financial stress when life takes an unexpected turn.

What Is an Emergency Fund?

An emergency fund is money set aside only for unexpected expenses such as:

  • Medical emergencies
  • Job loss
  • Car or bike repairs
  • Home maintenance
  • Family emergencies
  • Urgent travel expenses

Never use this money for shopping, vacations, or entertainment.

How Much Should You Save?

A good rule is to save enough to cover 3–6 months of essential living expenses.

For example:

  • Monthly expenses: $800
  • Emergency fund goal:
  • Minimum: $2,400
  • Ideal: $4,800

If you’re just starting, don’t wait until you can save the full amount.

Start with your first milestone:

  • $100
  • $250
  • $500
  • $1,000

Small wins create long-term financial discipline.

Where Should You Keep Your Emergency Fund?

Keep your emergency money somewhere safe and easily accessible.

Good options include:

  • High-yield savings account
  • Cash management account
  • Money market account

Avoid keeping emergency funds in stocks or other volatile investments because their value can fall when you need the money most.

Common Mistakes Beginners Make

  • Investing without any emergency savings
  • Using credit cards for emergencies
  • Spending emergency money on non-essential purchases
  • Keeping all savings in risky investments
  • Never replenishing the emergency fund after using it

Quick Action Plan

✔ Calculate your monthly essential expenses.

✔ Set a realistic emergency savings goal.

✔ Automate a fixed amount every month.

✔ Use the fund only for real emergencies.

✔ Rebuild the fund immediately after withdrawing money.

Pro Tip: Build your emergency fund first. Once you have a strong financial safety net, you can invest with greater confidence and avoid selling investments during difficult times.

External Resource

For emergency savings recommendations, visit the Consumer Financial Protection Bureau (CFPB).

Create a Realistic Monthly Budget

A budget is the foundation of every successful financial plan. No matter how much you earn, if you don’t know where your money goes each month, building wealth becomes extremely difficult. A realistic monthly budget gives every dollar a purpose, helping you spend intentionally instead of emotionally.

Many people think budgeting is about restricting their lifestyle, but that’s a common misconception. In reality, a budget gives you more financial freedom because it allows you to spend confidently while ensuring your essential expenses, savings, and investments remain on track.

If you’ve ever wondered where your salary disappears before the end of the month, it’s time to create a budget that works for your lifestyle—not against it.

Need help managing your monthly income? Read our How to Manage Your Salary guide for practical strategies.

Why Budgeting Is Important

A monthly budget acts as a financial blueprint. Instead of reacting to expenses, you plan them in advance and stay in control of your money.

  • Track every dollar you earn.
  • Reduce unnecessary spending.
  • Increase monthly savings.
  • Avoid overspending.
  • Achieve financial goals faster.
  • Reduce money-related stress.

How to Create a Budget in 5 Simple Steps

1. Calculate Your Monthly Income

Start by adding all reliable sources of income, including salary, freelance work, side hustles, rental income, or business earnings.

2. List Every Monthly Expense

Separate your expenses into fixed and variable categories.

  • Housing
  • Utilities
  • Transportation
  • Groceries
  • Insurance
  • Entertainment
  • Shopping
  • Subscriptions

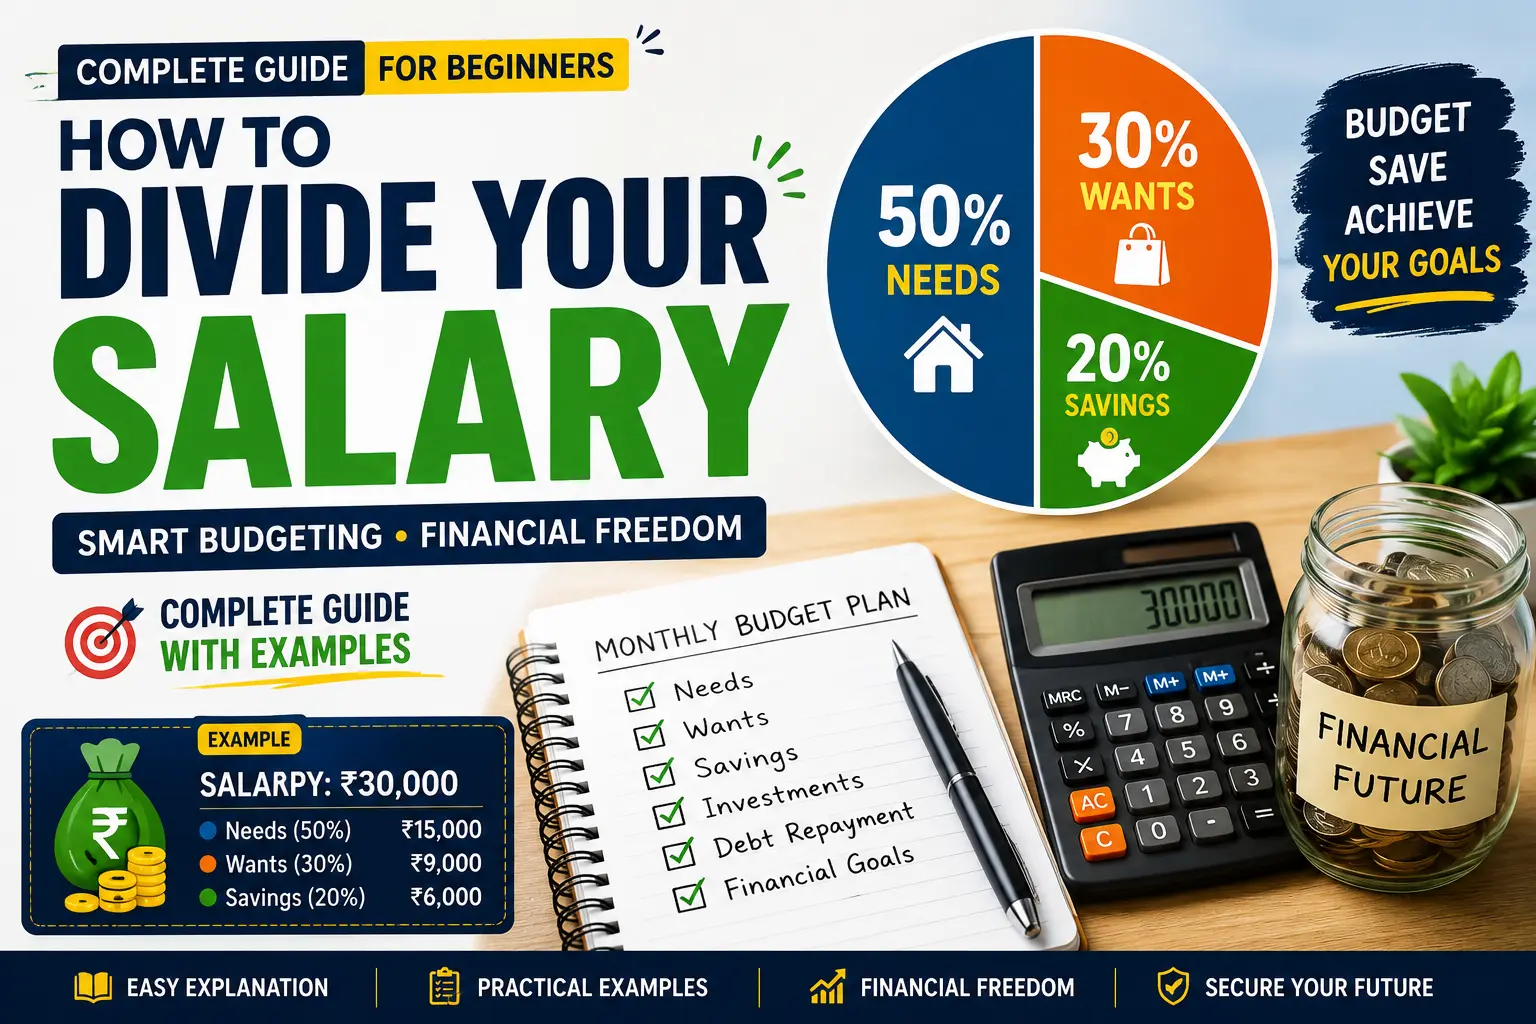
3. Follow the 50/30/20 Budget Rule

CategoryPercentagePurpose
Needs50%Housing, food, bills, transportation
Wants30%Entertainment, shopping, dining out
Savings & Investing20%Emergency fund, investments, retirement

The 50/30/20 rule is a helpful starting point, but you can adjust the percentages based on your income, financial goals, and living expenses.

4. Track Your Spending Every Week

Review your expenses weekly instead of waiting until the end of the month. This helps you identify unnecessary spending before it becomes a habit.

5. Adjust and Improve Every Month

A budget isn’t permanent. As your income, expenses, and financial goals change, your budget should evolve too.

Real-Life Example

Imagine David earns $3,000 every month. Before budgeting, he often ran out of money before payday. After following a monthly budget, he reduced unnecessary subscriptions and impulse purchases, increased his monthly savings, and started investing consistently. Within a year, he had built a healthy emergency fund and significantly improved his financial confidence.

Common Budgeting Mistakes

  • Not tracking daily expenses.
  • Ignoring small purchases.
  • Creating an unrealistic budget.
  • Forgetting irregular yearly expenses.
  • Never reviewing the budget.

Expert Tips

  • Automate your savings first.
  • Review your budget every Sunday.
  • Keep entertainment spending within limits.
  • Increase savings whenever your income grows.
  • Use budgeting apps or spreadsheets to monitor expenses.

Quick Budget Checklist

  • ✅ Calculate monthly income.
  • ✅ List every expense.
  • ✅ Follow a budgeting rule.
  • ✅ Track spending weekly.
  • ✅ Review your budget every month.

Need a flexible budgeting strategy? Read our How to Budget with an Irregular Income guide.

If saving money feels difficult, explore our How to Save Money Fast in 30 Days guide.

According to the Consumer Financial Protection Bureau (CFPB), maintaining a monthly budget is one of the most effective ways to improve financial well-being and achieve long-term financial goals.

Key Takeaways

  • A budget gives every dollar a purpose.
  • Track your spending consistently.
  • Review and improve your budget every month.
  • Small budgeting habits create long-term financial success.

Next Step: Now that you’ve created a realistic budget, it’s time to build a strong emergency fund that protects your financial future.

Manage and Eliminate Debt Wisely

Managing debt is one of the most important parts of financial planning for beginners. Many people focus only on earning more money, but building wealth becomes difficult if a large part of your income goes toward loan payments, credit card bills, or other debts. A smart financial plan helps you reduce debt strategically so you can save, invest, and achieve your financial goals faster.

Why Debt Management Matters

Not all debt is bad. A home loan or education loan can help build your future, but high-interest debt such as credit card balances and personal loans can slow your financial growth. Paying these off early gives you more financial freedom and reduces stress.

Types of Debt You Should Know

Good Debt

  • Education loans
  • Home loans
  • Business loans used for growth

Bad Debt

  • High-interest credit cards
  • Personal loans for unnecessary expenses
  • Buy Now Pay Later (BNPL) purchases without a repayment plan

How to Eliminate Debt Faster

1. List Every Debt

Write down each loan with its total balance, interest rate, and minimum monthly payment. This helps you see the complete picture.

2. Pay High-Interest Debt First

Use the Debt Avalanche Method by paying extra toward the loan with the highest interest rate while making minimum payments on the others. This saves the most money over time.

3. Avoid Taking New Debt

Reduce unnecessary spending and avoid borrowing for non-essential purchases until your existing debt is under control.

4. Make Extra Payments Whenever Possible

Use bonuses, tax refunds, freelance income, or any extra earnings to reduce your loan principal faster.

Real-Life Example

Imagine you have a credit card balance with a high interest rate and a small education loan. By paying extra toward the credit card first while continuing minimum payments on the education loan, you reduce interest costs and become debt-free sooner.

Common Debt Management Mistakes

  • Paying only the minimum amount every month
  • Ignoring high-interest debt
  • Borrowing to repay another loan
  • Using credit cards for everyday expenses without a repayment plan
  • Not tracking loan balances regularly

Expert Tips

  • Keep your monthly debt payments below 35% of your income whenever possible.
  • Set up automatic payments to avoid late fees.
  • Review your debt every month and celebrate small milestones to stay motivated.

Key Takeaways

  • Eliminate high-interest debt first.
  • Avoid unnecessary borrowing.
  • Make extra payments whenever you can.
  • A strong debt management strategy creates more room for saving and investing.

Related Guide: Read our complete guide on How to Manage Your Salary to improve your monthly cash flow.

Related Guide: Learn practical saving techniques in How to Save Money Fast in 30 Days.

External Resource: Learn more about responsible borrowing from the Consumer Financial Protection Bureau (CFPB).

Step 6: Start Investing for Long-Term Wealth

Saving money protects your finances, but investing helps your money grow over time. If you want to build long-term wealth, beat inflation, and achieve major financial goals, investing should become an essential part of your financial planning. The earlier you start, the more time your money has to benefit from compound growth.

Why Investing Is Important

Many beginners keep all their money in a savings account. While savings are important for emergencies, they usually don’t generate enough returns to build significant wealth. Investing allows your money to work for you instead of sitting idle.

Where Should Beginners Invest?

1. Mutual Funds

Mutual funds are one of the easiest investment options for beginners. You can start with a small monthly SIP and let professional fund managers handle your investments.

2. Index Funds

Index funds track the overall market and usually have lower fees. They are ideal for beginners who want long-term growth with minimal effort.

3. Stocks

Buying individual company shares can offer higher returns, but it also involves higher risk. Beginners should learn the basics before investing directly in stocks.

4. Fixed-Income Investments

Fixed deposits and government-backed savings schemes provide stable returns and are suitable for short-term or low-risk financial goals.

Investment Mistakes Beginners Should Avoid

  • Investing without clear financial goals.
  • Trying to become rich overnight.
  • Following social media tips without research.
  • Investing money needed for emergencies.
  • Selling investments during short-term market declines.

Real-Life Example

Suppose you invest a fixed amount every month through a SIP instead of waiting for the “perfect time.” Over several years, consistent investing and compound growth can build significantly more wealth than keeping the same money in a regular savings account.

Expert Tips

  • Start investing as early as possible.
  • Invest regularly instead of timing the market.
  • Diversify your investments across different assets.
  • Review your portfolio once or twice a year.
  • Stay invested for the long term.

Key Takeaways

  • Investing is essential for long-term wealth creation.
  • Start with beginner-friendly investment options.
  • Invest consistently and think long term.
  • Never invest your emergency fund.

Related Guide: Learn practical investing basics in Best Investments for College Students with $100: A Complete Beginner’s Guide (2026).

Related Guide: Understand budgeting before investing in How to Manage Your Salary: A Complete Day 1 to Day 30 Money Plan (2026).

External Resource: Learn the basics of investing and mutual funds from the U.S. Securities and Exchange Commission – Investor.gov.

Protect Your Financial Future with the Right Insurance

A complete financial planning for beginners guide is not only about saving and investing. It is also about protecting everything you have built. A single medical emergency, accident, or unexpected event can destroy years of savings if you are not properly insured. That’s why insurance is an essential part of every financial planning process.

Why Is Insurance Important in Financial Planning?

Insurance protects your income, savings, investments, and family from unexpected financial risks. Instead of paying huge expenses from your own pocket, insurance helps reduce the financial burden and keeps your long-term financial goals on track.

Types of Insurance Every Beginner Should Consider

1. Health Insurance for Financial Security

Health insurance is one of the first policies every beginner should have. Medical costs continue to rise every year, and a good health insurance plan protects your savings from unexpected hospital bills.

2. Life Insurance for Family Protection

If your family depends on your income, life insurance provides financial support to your loved ones if something unexpected happens to you. A term life insurance plan is often the most affordable option for beginners.

3. Vehicle Insurance to Avoid Financial Losses

If you own a bike or car, vehicle insurance protects you from repair costs, accidents, and legal liabilities. It is also mandatory in many countries.

4. Property and Home Insurance

Home insurance protects your house and valuable belongings from fire, theft, natural disasters, and other unexpected events.

How Much Insurance Do You Need?

The right insurance coverage depends on your income, financial responsibilities, existing savings, debts, and family needs. Review your insurance requirements regularly as your financial situation changes.

Common Insurance Mistakes Beginners Make

  • Buying insurance only to save tax.
  • Delaying health insurance until later in life.
  • Choosing the cheapest policy without comparing coverage.
  • Ignoring policy exclusions and claim conditions.
  • Never reviewing insurance after major life changes.

Expert Tips for Choosing the Right Insurance

  • Buy insurance before investing aggressively.
  • Compare multiple insurance providers before purchasing.
  • Read the policy terms carefully.
  • Review your coverage every year.
  • Keep all insurance documents organized and updated.

Key Takeaways

  • Insurance protects your financial future from unexpected risks.
  • Health insurance should usually be your first priority.
  • Life insurance is important if your family depends on your income.
  • Review your insurance coverage regularly as your financial goals change.

Related Guide: Before buying insurance, learn how to build a solid financial foundation in How to Manage Your Salary: A Complete Day 1 to Day 30 Money Plan (2026).

Related Guide: Strengthen your money habits with 10 Best Financial Habits Every College Student Should Develop (2026).

External Resource: Learn how insurance protects your financial future from the National Association of Insurance Commissioners (NAIC).

Review and Improve Your Financial Plan Regularly

Creating a financial plan is only the beginning. To achieve long-term success, you must review and improve your plan regularly. Your income, expenses, financial goals, investments, and responsibilities will change over time, so your financial plan should evolve as well.

Many beginners create a budget or investment plan once and never look at it again. This is one of the biggest mistakes in financial planning for beginners. Regular reviews help you identify problems early, adjust your strategy, and stay on track toward your financial goals.

Why Is Reviewing Your Financial Plan Important?

A financial plan is not a one-time document—it is a living strategy. Reviewing it regularly helps you adapt to life’s changes and make smarter financial decisions.

Benefits of reviewing your financial plan include:

  • Stay focused on your financial goals.
  • Adjust your budget as your income changes.
  • Track your savings and investment progress.
  • Identify unnecessary expenses.
  • Improve your long-term financial security.
  • Reduce financial mistakes before they become costly.

What Should You Review Every Month?

1. Review Your Monthly Budget

Compare your planned budget with your actual spending. Look for areas where you consistently overspend and make adjustments for the next month.

2. Review Your Savings Progress

Check whether you’re consistently contributing to your emergency fund, retirement savings, and other financial goals.

3. Review Your Investments

Monitor your portfolio’s performance without reacting to short-term market movements. Focus on whether your investments still match your goals and risk tolerance.

4. Review Your Debt

Track your outstanding balances, interest rates, and repayment progress. If possible, increase your monthly payments to become debt-free faster.

5. Review Your Financial Goals

As your career, family, or lifestyle changes, update your short-term and long-term financial goals to reflect your current priorities.

Annual Financial Planning Checklist

At least once a year, ask yourself:

  • Have I increased my savings rate?
  • Is my emergency fund still adequate?
  • Do I have the right insurance coverage?
  • Am I investing enough for retirement?
  • Have I reduced unnecessary debt?
  • Do my financial goals still reflect my priorities?

Common Financial Planning Mistakes

  • Never reviewing your budget.
  • Ignoring lifestyle inflation after salary increases.
  • Making emotional investment decisions.
  • Forgetting to update financial goals.
  • Delaying important financial decisions.

Expert Tips

  • Schedule a monthly “Money Review Day.”
  • Review your net worth every six months.
  • Increase your investments whenever your income grows.
  • Rebalance your investment portfolio once a year.
  • Keep learning about personal finance to improve your financial decisions.

Key Takeaways

  • Financial planning is an ongoing process, not a one-time task.
  • Small monthly improvements lead to significant long-term results.
  • Regular reviews help you stay aligned with your financial goals.
  • Continuous learning and disciplined habits are the foundation of financial success.

Related Guide: Learn how to control your income more effectively in How to Manage Your Salary.

Related Guide: Build better money habits by reading 10 Best Financial Habits Every College Student Should Develop.

External Resource: The Consumer Financial Protection Bureau (CFPB) recommends reviewing your financial goals, spending, savings, and debt regularly to maintain long-term financial well-being.

Step 10: Take Action and Stay Consistent with Your Financial Plan

Creating a financial plan is an important achievement, but taking consistent action is what turns your plan into real financial success. Many people spend weeks learning about budgeting, investing, and saving, yet never implement what they learn. Knowledge alone doesn’t build wealth—consistent action does.

The most successful people in personal finance aren’t always those with the highest incomes. They’re the ones who follow good financial habits month after month, year after year. Small, consistent improvements often produce far better results than occasional large efforts.

Why Consistency Is the Key to Financial Success

Financial planning isn’t about making one perfect decision. It’s about making hundreds of small, smart decisions over time.

When you stay consistent, you can:

  • Build wealth steadily.
  • Develop strong financial habits.
  • Reduce financial stress.
  • Reach your financial goals faster.
  • Stay motivated during market ups and downs.

Build Daily and Monthly Financial Habits

Daily Financial Habits

  • Avoid impulse purchases.
  • Track your daily spending.
  • Spend intentionally instead of emotionally.

Weekly Financial Habits

  • Review your expenses.
  • Check your budget progress.
  • Identify unnecessary spending.

Monthly Financial Habits

  • Save before spending.
  • Invest consistently.
  • Pay bills on time.
  • Review your financial goals.
  • Update your budget if needed.

Continue Learning About Personal Finance

Financial planning is a lifelong journey. As markets, technology, and your personal circumstances change, continue improving your financial knowledge.

Consider learning about:

  • Investing
  • Tax planning
  • Insurance
  • Retirement planning
  • Passive income
  • Wealth management

The more you learn, the better financial decisions you’ll make.

Common Mistakes That Prevent Long-Term Success

  • Giving up after one bad month.
  • Frequently changing financial strategies.
  • Trying to get rich quickly.
  • Ignoring long-term goals.
  • Not reviewing financial progress regularly.

Expert Tips

  • Focus on progress, not perfection.
  • Automate your savings and investments.
  • Increase your investment amount whenever your income grows.
  • Celebrate small financial milestones.
  • Stay patient—wealth takes time to build.

Your 30-Day Financial Planning Challenge

Complete these actions over the next month:

✅ Create a monthly budget.

✅ Track every expense.

✅ Build or increase your emergency fund.

✅ Invest your first monthly contribution.

✅ Review your financial goals.

✅ Read one personal finance book or article each week.

Key Takeaways

  • Financial planning is a lifelong process.
  • Consistency beats perfection.
  • Small financial habits create long-term wealth.
  • Keep learning and improving your financial knowledge.
  • Take action today instead of waiting for the perfect time.

Related Guide: Improve your money management skills by reading How to Manage Your Salary.

Related Guide: Build stronger money habits with 10 Best Financial Habits Every College Student Should Develop.

Related Guide: Learn practical investing strategies in Best Investments for College Students with $100.

External Resource: For trusted personal finance education and practical money management resources, visit the Consumer Financial Protection Bureau (CFPB).

Final Thoughts

Financial planning for beginners doesn’t have to be complicated. By following the simple steps in this guide—understanding your current financial situation, setting SMART goals, tracking your income and expenses, creating a realistic budget, managing debt, investing for the future, protecting yourself with insurance, planning for retirement, and reviewing your progress regularly—you can build a strong financial foundation.

Remember, financial success is not about earning the highest income. It’s about making smart financial decisions consistently over time. Even small actions, such as saving a little more each month or investing regularly, can create significant results through discipline and the power of compound growth.

The best time to start your financial planning journey is today. Stay committed to your goals, continue learning, and review your financial plan regularly. With patience and consistency, you’ll be well on your way to achieving long-term financial security and financial freedom.

What Is Financial Planning for Beginners?
Financial planning for beginners is the process of managing your income, expenses, savings, investments, insurance, and financial goals to build long-term financial security. It helps you create a budget, save consistently, reduce debt, invest wisely, and make better financial decisions for the future.

Why Is Financial Planning Important Financial planning is important because it helps you take control of your money, prepare for unexpected expenses, achieve your financial goals, and build long-term wealth. A solid financial plan also reduces financial stress and gives you confidence in your financial future.

How Do I Start Financial Planning with a Low Income You can start financial planning with a low income by tracking your expenses, creating a realistic budget, building an emergency fund, paying off high-interest debt, and investing small amounts consistently. Good financial habits matter more than a high income.

What Are the Five Steps of Financial Planning The five basic steps of financial planning are assessing your current financial situation, setting clear financial goals, creating a budget, saving and investing regularly, and reviewing your financial plan periodically. Following these steps helps you achieve long-term financial success.

How Often Should You Review Your Financial Plan You should review your financial plan every three to six months or whenever a major life event occurs, such as changing jobs, getting married, buying a home, or starting a family. Regular reviews help keep your budget, savings, investments, and financial goals on track.

Detailed Summary
Financial planning for beginners is the foundation of long-term financial success. It is not just about creating a budget or saving money—it’s a complete process that helps you manage your income, control expenses, reduce debt, invest wisely, protect your finances, and achieve your short-term and long-term financial goals.
In this guide, you first learned what financial planning is and why it is essential for building financial security. You then discovered how to assess your current financial situation by evaluating your income, expenses, savings, debts, and overall financial health. Understanding your current position is the first step toward making smarter financial decisions.
Next, you explored how to set SMART financial goals that are specific, measurable, achievable, relevant, and time-bound. Clear goals give your money a purpose and help you stay focused on what matters most.
You also learned the importance of tracking your income and expenses, creating a realistic monthly budget, and managing debt effectively. These habits help you improve cash flow, reduce unnecessary spending, and create more opportunities to save and invest.
The guide also explained why investing is essential for long-term wealth creation, how insurance protects your financial future from unexpected risks, and why starting retirement planning early allows your investments to benefit from compound growth over time.
Finally, you learned that financial planning is an ongoing process. Reviewing your financial plan regularly, adjusting it as your life changes, and staying consistent with good financial habits are the keys to achieving lasting financial success.
Whether you’re starting with a small income or beginning your financial journey from scratch, following these practical steps can help you build a stronger financial future. Remember, successful financial planning is not about being perfect—it’s about making consistent, informed decisions that move you closer to financial freedom, one step at a time.

Best 5 Mutual Funds for College Students in India (2026)

Best 5 mutual funds for college students in India in 2026

Starting an investment journey during college can completely transform your long-term financial future. While most college students assume that investing in the stock market requires huge capital, financial degrees, or full-time corporate salaries, the Indian mutual fund ecosystem has evolved dramatically. Today, any student with an active smartphone and just ₹100 to ₹500 from their monthly pocket money can build a high-compounding investment portfolio.

In this comprehensive guide, we will break down the top five beginner-friendly mutual funds for Indian college students in 2026. You will learn the exact expense ratios, portfolio holdings, how to complete paperless KYC without income proof, and how to automate your monthly SIP on Zerodha Coin, Groww, or Angel One.

Disclaimer: The financial insights shared in this article are solely for educational, academic, and informational purposes. We are not SEBI-registered investment advisors. Mutual fund investments are subject to market risks; past performance does not guarantee future returns. Always review the Scheme Information Document (SID) on official AMC portals before investing.

Why College Students Should Start a Mutual Fund SIP Early

When you are 18 to 22 years old, your biggest financial superpower is not the amount of money in your wallet, but the time you have ahead of you. Compounding works like a rolling snowball: the longer your money stays invested in quality companies, the faster your returns begin to generate their own returns.

To see the real power of time, consider two college students investing ₹500 every month at an average historical return of 14% CAGR:

  • Student A (Starts at Age 18): Invests ₹500 every month from pocket money or freelance stipends. Over 35 years until age 53, the total money deposited is just ₹2.10 Lakhs. At 14% CAGR, the final portfolio grows to over ₹35,40,000!
  • Student B (Waits until Age 25): Decides to wait for a full-time corporate job. By delaying by just 7 years, their portfolio reaches only ₹13,80,000.

A short 7-year delay costs Student B over ₹21 Lakhs in compounding gains. That is why starting early with whatever small amount you can save from canteen expenses is the single smartest money decision you can make in college.

Mutual Fund SIP Compounding Calculator Sheet for College Students Starting at Age 18
Calculation Sheet: Month-by-month ₹500 SIP compounding calculation at 14% CAGR demonstrating how time beats capital.

Quick Comparison: Top 5 Mutual Funds for Students at a Glance

The table below provides a quick side-by-side comparison of the five premier student-friendly equity schemes based on their category, entry requirements, ongoing costs, and long-term risk profiles:

Fund SchemeCategoryMinimum SIPDirect Expense RatioRisk LevelIdeal For
Parag Parikh Flexi CapFlexi Cap₹1,000~0.65%Moderate to HighAll-round wealth (5+ yrs)
Nippon India Small CapSmall Cap₹100~0.70%Very HighAggressive growth (7+ yrs)
HDFC Index S&P BSE SensexIndex (Passive)₹100~0.20%ModerateSafe beginner entry (3+ yrs)
Quant Multi AssetMulti Asset₹500~0.75%ModerateEquity + Gold balance
ICICI Prudential BluechipLarge Cap₹100~0.85%Low to ModerateCapital stability & low swings

Detailed Review of the 5 Best Mutual Funds for Students

1. Parag Parikh Flexi Cap Fund (Direct - Growth)

The Ultimate Foundation Fund: If you only want to invest in a single equity mutual fund throughout your entire college degree, Parag Parikh Flexi Cap is arguably the most disciplined option in India. Because it is a flexi-cap fund, the fund managers have complete freedom to invest across large-cap, mid-cap, and small-cap companies depending on where the best value lies.

  • Assets Under Management (AUM): ₹75,000+ Crores
  • Direct Expense Ratio: ~0.65% (Very competitive for an actively managed fund)
  • Benchmark: NIFTY 500 TRI
  • Top Indian Holdings: HDFC Bank, Bajaj Holdings, ITC, Power Grid, ICICI Bank
  • International Advantage: The fund holds global tech giants like Alphabet (Google) and Microsoft. This gives students automatic foreign currency diversification, protecting your portfolio if the Indian rupee depreciates against the US dollar.
  • Minimum SIP: ₹1,000 per month (Ideal if you earn stipends or receive consistent pocket money).

2. Nippon India Small Cap Fund (Direct - Growth)

Highest Growth Potential for Patient Students: Small-cap funds invest in emerging, fast-growing companies ranked 251st and below in Indian stock exchanges. Nippon India Small Cap is one of the largest and most consistently managed small-cap schemes in India.

  • Assets Under Management (AUM): ₹55,000+ Crores
  • Direct Expense Ratio: ~0.70%
  • Benchmark: NIFTY Smallcap 250 TRI
  • Top Holdings: Tube Investments of India, Apar Industries, HDFC Bank, Voltamp Transformers
  • Why It Suits College Students: Because students have 10 to 15 years before retirement or major adult liabilities, you can easily ride out short-term market crashes. Historically, small caps offer the highest wealth multiplier over 7 to 10-year horizons.
  • Minimum SIP: Just ₹100 per month, making it accessible to any student with basic pocket money.

3. HDFC Index S&P BSE Sensex Fund (Direct - Growth)

The Safest, Lowest-Cost Passive Entry: An index fund does not rely on a human fund manager picking individual stocks. Instead, it mechanically mirrors India's premier benchmark index—the S&P BSE Sensex—which tracks the country's top 30 corporate giants like Reliance Industries, TCS, Infosys, and Larsen & Toubro.

  • Assets Under Management (AUM): ₹8,000+ Crores
  • Direct Expense Ratio: ~0.20% (Ultra-low cost; almost zero fees deducted)
  • Tracking Error: Less than 0.05% (Extremely accurate index replication)
  • Zero Fund Manager Risk: You never have to worry about a manager making bad bets. As long as India's overall economy and top industries expand, your investment grows steadily with it.
  • Minimum SIP: ₹100 per month.

4. Quant Multi Asset Fund (Direct - Growth)

All-Weather Protection During Market Dips: Most college beginners get panicked when the stock market drops 10% during exam season. A Multi Asset Allocation Fund solves this by automatically diversifying your money across three different asset classes: Equities (Stocks), Gold, and Debt (Bonds).

  • Assets Under Management (AUM): ₹3,500+ Crores
  • Direct Expense Ratio: ~0.75%
  • Portfolio Asset Allocation: ~55% Indian Equities, ~15% Gold ETFs, ~15% Debt instruments, ~15% Cash/Derivatives
  • Why It Works: When the equity market experiences sharp corrections, gold prices frequently surge. This dynamic hedge cushions your portfolio, giving you peace of mind while still delivering equity-like returns over the long run.
  • Minimum SIP: ₹500 per month.

5. ICICI Prudential Bluechip Fund (Direct - Growth)

Steady Compounding with India's Market Leaders: If your risk tolerance is low and you want maximum stability, ICICI Prudential Bluechip Fund is a premier large-cap scheme that invests primarily in India's top 100 established market leaders.

  • Assets Under Management (AUM): ₹58,000+ Crores
  • Direct Expense Ratio: ~0.85%
  • Benchmark: NIFTY 100 TRI
  • Top Holdings: ICICI Bank, Reliance Industries, Infosys, Bharti Airtel, Larsen & Toubro, Maruti Suzuki
  • Defensive Character: Bluechip companies possess massive cash reserves and pricing power. During economic slowdowns, these funds experience far lower drawdowns than small-cap schemes.
  • Minimum SIP: ₹100 per month.

How College Students Can Complete 100% Paperless Video-KYC (No Salary Slip Needed)

One of the biggest hurdles that stops students from starting is the fear of paperwork: "I don't have a corporate job, salary slip, or ITR. Will investment apps reject me?"

Under official SEBI and AMFI guidelines, no income proof is required for mutual fund investments. Any Indian citizen who is 18 years or older can complete verification in under five minutes using three basic documents:

  • 1. PAN Card: Required by law for all Indian capital market investments.
  • 2. Aadhaar Card: Must be linked to an active mobile number to receive an instant OTP via DigiLocker.
  • 3. Student Savings Bank Account: Any active savings bank account in your own name (such as SBI, Kotak 811, HDFC, or Paytm Payments Bank) with UPI or net banking enabled.

When you sign up on an investment app, it connects to government records via DigiLocker. You verify your details, record a 5-second video selfie on your phone to confirm in-person verification (IPV), and your KYC is officially approved within 2 to 24 hours without stepping into a physical bank branch.

Direct Plan vs. Regular Plan: Why Students Must Never Choose Regular Plans

Every single mutual fund in India is offered in two distinct formats: Direct Plan and Regular Plan. Understanding this distinction is crucial for protecting your wealth:

  • Regular Plans: Sold by traditional bank relationship managers, local agents, and commission brokers. The mutual fund company secretly deducts 1% to 1.5% from your portfolio every year to pay ongoing commissions to the broker.
  • Direct Plans: You invest directly through SEBI-registered discount platforms like Zerodha Coin or Groww. Zero middleman commission is deducted, meaning 100% of your earnings stay in your account.

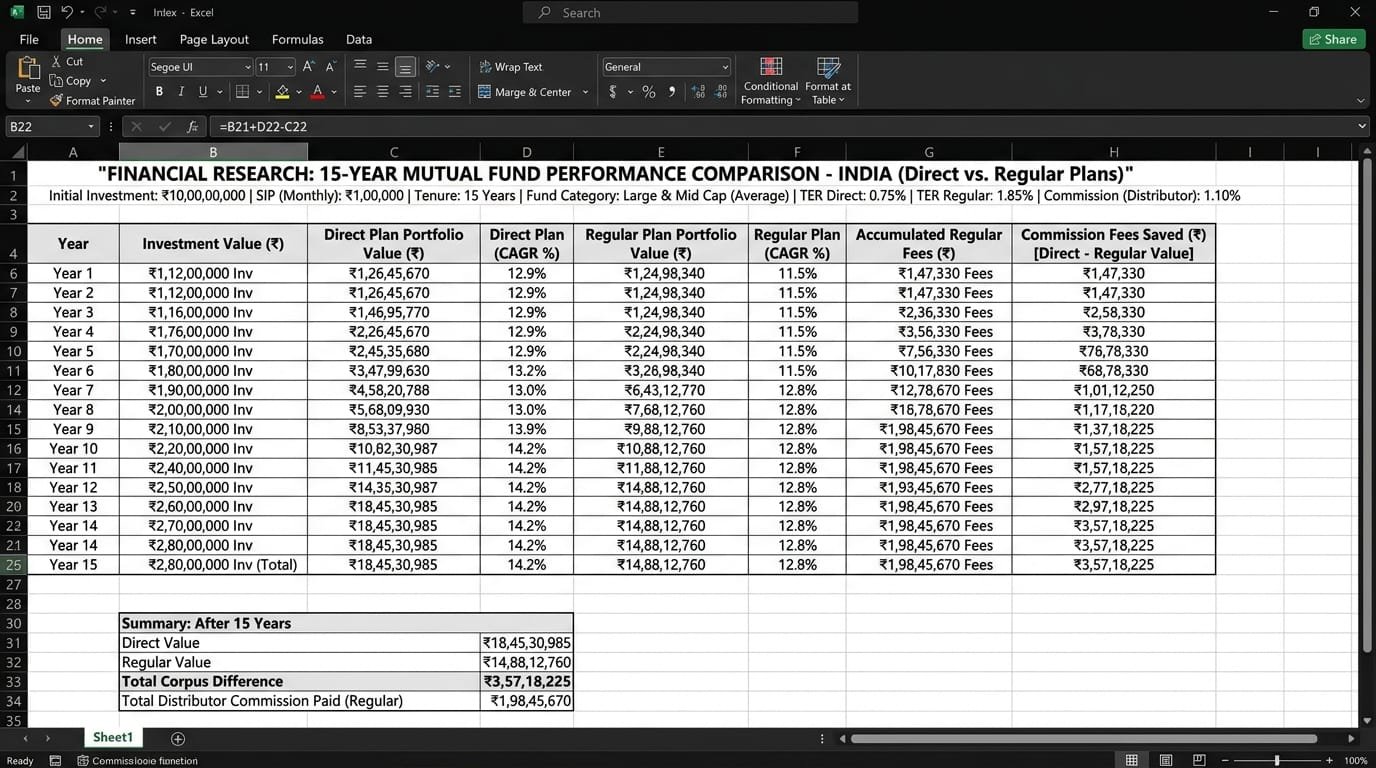
The Real Impact: On a 15-year SIP of ₹1,000 per month, that small 1.5% commission difference cuts your final wealth by over ₹2,40,000 in lost returns. Always make sure the word "Direct" is explicitly written in the fund title before confirming your purchase.

Direct Plan vs Regular Plan 1.5% Broker Commission Fee Comparison Data Sheet
Research Data Sheet: How a 1.5% annual distributor commission in Regular Plans erodes over ₹1,04,000 from a 15-year student portfolio.

How to Set Up Your Monthly SIP on Groww, Zerodha Coin, and Angel One

Automating your monthly SIP takes under three minutes on your smartphone. Here is how the top three platforms compare for college students:

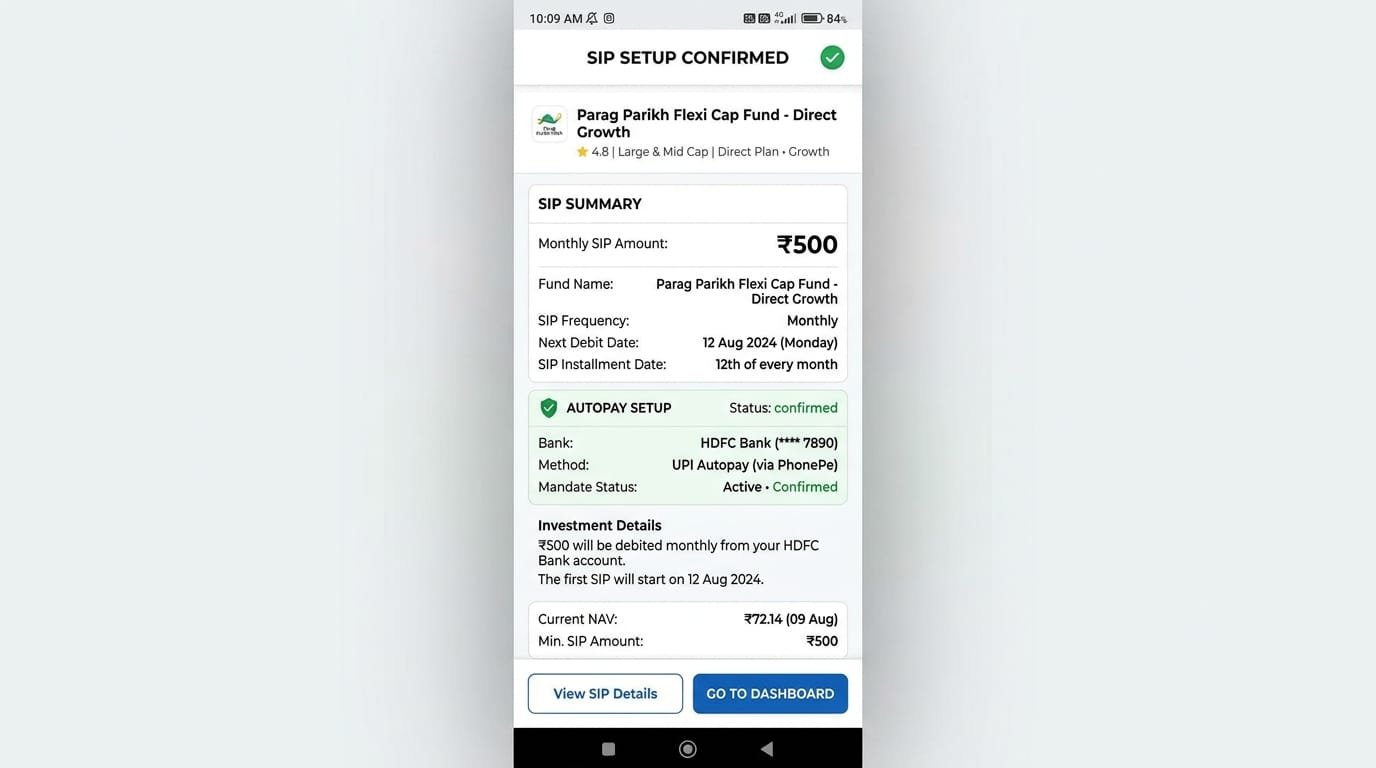
Mobile Investment App SIP Setup Screen on Groww and Zerodha Coin for College Students
Mobile App Screen: Setting up a ₹100 or ₹500 automated monthly SIP with UPI Autopay on a verified Direct Growth plan.
PlatformPlans AvailableMinimum SIPKey Advantage for Students
Groww100% Direct Plans₹100Cleanest interface for beginners, 1-click UPI Autopay setup
Zerodha Coin100% Direct Plans₹100Zero distributor fees, Demat holding, and Step-Up SIP option
Angel One100% Direct Plans₹100Advanced research tools, smart advisory, easy e-mandate

1. Setting Up SIP on Groww (Step-by-Step)

  1. Download Groww & Complete DigiLocker Verification: Log in with your mobile number, verify Aadhaar OTP via DigiLocker, and enter your PAN details.
  2. Search for Your Fund: Type the scheme name in the search bar (for example: Nippon India Small Cap Fund Direct Growth). Always verify that it says Direct Plan.
  3. Tap "Start SIP": Select the Start SIP button at the bottom of the screen.
  4. Enter Amount and Pick Date: Enter your monthly budget (₹100 or ₹500). Pick a date 2-3 days after your pocket money or allowance usually arrives.
  5. Authorize UPI Autopay: Select Google Pay, PhonePe, or Paytm. Enter your UPI PIN to approve the recurring mandate. Your automated monthly SIP is now live!

2. Setting Up SIP on Zerodha Coin (Step-by-Step)

  1. Log into Coin: Open the Coin app or visit coin.zerodha.com using your Zerodha user ID.
  2. Search for Direct Scheme: Search for your fund (such as HDFC Index S&P BSE Sensex Fund Direct Growth). Coin exclusively lists 100% Direct Plans with zero commission.
  3. Click "SIP" & Choose Frequency: Tap SIP and set the frequency to Monthly. You can also turn on the Step-Up SIP feature to raise your monthly investment by 10% each year as your internship stipend grows.
  4. Authorize Mandate: Link your student savings bank account using Net Banking or Debit Card to approve the recurring auto-debit.

3. Setting Up SIP on Angel One (Step-by-Step)

  1. Go to Mutual Funds: Open the Angel One mobile app and tap on the Mutual Funds tab from the home dashboard.
  2. Discover Scheme: Search for Parag Parikh Flexi Cap Direct Plan and check the NAV performance chart.
  3. Confirm SIP: Tap Start SIP, choose your monthly date, enter your amount, and approve the auto-debit via UPI or Net Banking.

Mutual Fund Tax Rules for College Students (2026 Simplified)

Students often worry that investing in mutual funds will lead to tax notices. Here is how Indian taxation legally applies to college students:

  • Zero Tax for Non-Earning Students: Under Indian tax laws, if your total annual income (including pocket money stipends and mutual fund profits) is below the basic tax exemption limit (₹3,00,000 per year under the New Tax Regime), you pay zero tax.
  • Long-Term Capital Gains (LTCG): For equity mutual funds held for more than 12 months, profits up to ₹1.25 Lakh every financial year are completely tax-exempt.
  • Short-Term Gains (STCG): If you redeem equity funds within 12 months, gains are taxed at 20%, but basic exemption thresholds continue to protect college students who do not have other taxable salaries.

How to Allocate Your Student Pocket Money for Monthly SIPs

To invest consistently without running out of money before the end of the month, follow the 50/30/20 Student Budgeting Framework:

  • 50% for Essentials: Semester books, bus/metro transit, mobile recharges, hostel canteen meals.
  • 30% for Fun & Social Life: Outings with friends, movies, weekend snacks.
  • 20% for Automated SIP: Transfer ₹100, ₹500, or ₹1,000 directly into your mutual fund SIP on the day your allowance arrives before you have a chance to spend it.

Regulatory & Editorial Standards (AMFI & SEBI Disclosure):
paisakmao.de is an independent financial education initiative founded by Asif Khan. We are not SEBI-registered investment advisers (RIA) or portfolio managers. Mutual fund investments are subject to market risks; please read all scheme-related documents (SID / KIM) carefully on official AMC portals before investing. Past performance figures reflect historical data up to 2026 and do not guarantee future returns.

Frequently Asked Questions (FAQs)

Can a college student invest in mutual funds without a job or income proof?

Yes, absolutely. SEBI and AMFI guidelines do not require salary slips or income tax returns (ITR) to invest in mutual funds. As long as you are 18+ years old with a valid PAN card, Aadhaar card, and a student bank account, you can complete paperless Video-KYC in under 5 minutes on apps like Groww or Zerodha Coin.

What is the minimum monthly SIP amount a student can start with?

You can start with as little as ₹100 per month. Popular student-friendly funds like Nippon India Small Cap Fund, HDFC Index S&P BSE Sensex Fund, and ICICI Prudential Bluechip Fund all allow ₹100 micro-SIPs, making investing accessible on any college budget.

What happens if I don't have enough pocket money in my bank on SIP date?

The mutual fund company simply skips the installment for that month with zero penalties. To avoid bank auto-debit bounce fees, you can easily tap "Pause SIP" on your app 2-3 days before the scheduled date for 1 to 3 months without any charge.

Is a Fixed Deposit (FD) better or a Mutual Fund SIP for students?

Bank FDs offer guaranteed 6.5% to 7% returns, which barely beats inflation. Equity mutual funds have historically delivered 14% to 18%+ CAGR over 5-7 year horizons. If you need money within a year for semester fees, use a Bank FD; for long-term wealth creation, a Mutual Fund SIP is far superior.

Which is the best and safest app for college students to invest in mutual funds?

Groww and Zerodha Coin are the top two choices. Both are SEBI-regulated, offer paperless DigiLocker KYC, charge zero account opening fees, and strictly sell Direct Plans with zero middleman commissions.

Best 5 Lifetime Free Credit Cards for College Students in India (No Income Proof) in 2026

5 lifetime free credit cards for college students in India 2026

Choosing the best 5 lifetime free credit cards for college students in India can completely transform how you manage your money, especially when you don’t have a salary slip or income proof. Many students need instant credit options to purchase necessary gadgets, pay for online certification courses, or handle sudden educational expenses, but traditional banking rules often lead to immediate rejections. Fortunately, secured or FD-backed options provide a guaranteed route to bypass these strict requirements. In this comprehensive guide, we will break down the top student-friendly cards that charge zero annual fees, helping you secure instant buying power and build a rock-solid 750+ CIBIL score during your college years.

Disclaimer: The information provided in this article is for educational and informational purposes only. We are not SEBI-registered financial advisors or banking experts. Credit cards require high financial discipline and timely repayments. Late payments or defaulting on dues can severely damage your CIBIL score and attract heavy penalties. Please read all terms, conditions, and fee structures carefully on the official bank website before applying for any financial product.

How Can College Students Get a Credit Card Without Income Proof?

Most traditional credit cards require you to submit salary slips or Income Tax Returns (ITR) to prove your monthly income. Since college students usually do not have a steady job or formal income documents, banks routinely reject their regular card applications.

However, you can easily bypass this barrier through a financial asset known as a secured credit card. Instead of looking at your monthly salary, banks issue these cards against a small Fixed Deposit (FD) that you open with them. You can read this detailed secured credit cards guide on Paisabazaar to understand the eligibility parameters deeply. The bank keeps this FD as collateral security and grants you a credit limit equivalent to 80% to 100% of your deposit amount.

The biggest benefit of this method is that your money is never locked away uselessly. You continue to earn regular interest on your fixed deposit—often between 6.5% to 7.5% depending on the bank—while simultaneously enjoying the spending power of a credit card. It is a 100% guaranteed way for students to build a high credit history from scratch.

Quick Comparison: Best Student Credit Cards in India (2026)

Card NameMinimum FD AmountAnnual / Joining FeePrimary Superpower
IDFC FIRST WOW!₹20,000₹0 (Lifetime Free)Zero Forex Markup Fee
OneCard Lite (SBM)₹5,000₹0 (Lifetime Free)5X Rewards & Metal Design
Kotak 811 #DreamDifferent₹10,000₹0 (Lifetime Free)2X Reward Points Online
AU Small Finance Bank LITNo FD Required₹0 (Lifetime Free)Customizable Feature Slabs
ICICI Coral Secured Card₹10,000₹0 (Lifetime Free)Movie & Lounge Discounts

Before reading the detailed analysis, look at this quick comparison table. It highlights the baseline entry barriers, annual fees, and core purposes of the top student credit cards available in the market.

Important Note: Before you apply for any card and swipe it, managing your cash flow is critical. Scroll down to the bottom of this article to download our free budgeting tracker tool to secure your payment cycles.

Detailed Review of the Best Lifetime Free Student Credit Cards

Choosing your first credit card can be confusing because each bank offers different benefits. To make your decision easier, here is a detailed, transparent review of the top lifetime free credit cards available for college students in India, along with their pros and cons.

1. IDFC FIRST WOW! Credit Card

The IDFC FIRST WOW! is an excellent secured card that requires zero documentation or income verification. You can check the complete application criteria on the official IDFC FIRST Bank WOW Credit Card page. This card is highly popular among students because it charges a 0% foreign markup fee, making it the cheapest option for making international transactions, such as buying foreign courses, paying for GRE/IELTS exams, or ordering global software subscriptions.

  • Pros: Earns regular FD interest up to 7.5% per annum; 100% cash withdrawal limit; absolutely zero joining and annual fees.
  • Cons: Requires a high minimum fixed deposit of ₹20,000 to get started.

2. SBM OneCard Lite

If you want a highly modern, digital-first credit card experience, the SBM OneCard Lite is a fantastic choice. Managed entirely via a smooth mobile application, it is issued against a very affordable deposit. You can read more about the digital features and reward slabs directly on the official OneCard platform. It offers 5X reward points on your top two spending categories every month, making it perfect for online shopping.

  • Pros: Very low minimum fixed deposit entry barrier of just ₹5,000; instant virtual card activation; sleek metal card options for higher deposit amounts.
  • Cons: Rewards point redemption has complex fractional slabs that take time to accumulate.

3. Kotak 811 #DreamDifferent Credit Card

The Kotak 811 #DreamDifferent Credit Card is tailored for students who already hold a Kotak 811 digital savings account. It requires a moderate fixed deposit and can be activated instantly directly through the Kotak mobile banking app. For full details on interest calculations, visit the official Kotak Mahindra Bank 811 Card portal. It gives you 2X reward points for every ₹100 spent online.

  • Pros: Quick in-app approval process; 100% interest-free cash withdrawal for up to 48 days; zero documentation required.
  • Cons: Reward points cannot be redeemed directly for cash statement credit; they must be used against specific vouchers.

How to Build a 750+ CIBIL Score in College Without Falling Into Debt Trap

Getting your first credit card is easy, but managing it responsibly is the real test for a college student. If you swipe your card recklessly and fail to pay the bills on time, you will damage your CIBIL score before your career even begins. On the other hand, if you clear your total dues before the due date, you can easily build a solid 750+ credit history within 12 months.

Credit card debt traps usually happen when you do not follow a strict money management system. To prevent overspending on your new card, read our comprehensive guide on how to divide your salary for beginners with examples to learn how to allocate your funds correctly.

Additionally, using a credit card requires serious self-control. You must develop healthy spending boundaries early in life. To help you master this mindset, check out our expert blueprint on the 10 best financial habits every college student should develop. By combining the right habits with your new card, you will secure a powerful financial future.

Download Our Free College Student Budgeting and Credit Card Expense Tracker Tool

To make your financial journey completely stress-free, we have designed a customized, easy-to-use student budgeting and credit card expense tracker tool. This free spreadsheet helps you log your monthly pocket money, divide your expenses automatically, and monitor your credit card bill cycles so that you never miss a payment deadline.

To track your monthly budget and expenses easily, you can use a ready-made professional template. Click the official reference link below to save a free tracking sheet directly:

👉 Click Here to Download the Alternate Excel Personal Budget Template

Additionally, if you want to quick-check your monthly financial math right now, you can try our interactive budget-calculator to plan your monthly income allocation in seconds.

Please Note: If you do not have a fixed monthly stipend or work as a student freelancer, tracking your expenses can be slightly tricky. If that is your current situation, make sure to read our highly detailed blueprint on how to budget with an irregular income step-by-step guide to sync your fluctuating money flows with these calculators perfectly.

Can a college student get a credit card without an income proof or salary slip?

Yes, college students can absolutely get a credit card without any income proof by choosing a secured credit card. Instead of validating your monthly salary, banks issue these cards against a small Fixed Deposit (FD) that acts as collateral security.

What is the minimum FD amount required for a student credit card?

The minimum deposit required varies depending on the bank you choose. For instance, you can get started with as little as ₹5,000 for an SBM OneCard Lite, while cards like the IDFC FIRST WOW! require a minimum fixed deposit of ₹20,000 to trigger activation.

Does using a student credit card really improve your CIBIL score?

Yes, as long as you pay your credit card bills on time and in full every single month. By clearing your dues before the payment deadline, the bank reports your positive repayment behavior to credit bureaus, helping you build a solid credit history.

What happens if a student fails to pay their credit card bill?

Failing to clear your credit card dues will severely damage your credit history and drop your score instantly. To understand how utilization patterns affect your overall credit standing, you can read the official CIBIL score management guide on TransUnion CIBIL. Additionally, banks will levy heavy annual interest penalties ranging from 36% to 42% on your outstanding balance.

Conclusion: Which Student Credit Card Should You Choose?

Building a solid financial foundation while studying is one of the smartest moves a college student can make. By picking a lifetime free secured credit card, you eliminate the need for any formal income proof or salary slips while unlocking a guaranteed path to a high CIBIL score.

If your primary goal is to pay for international exams, foreign subscriptions, or online global courses without losing money on conversion fees, the IDFC FIRST WOW! Credit Card is your best option due to its zero forex markup feature. However, if you are looking for an affordable entry point with minimal deposit requirements and a sleek design, starting with the SBM OneCard Lite at just ₹5,000 is highly recommended.

No matter which card you select, ensure you clear your monthly statements on time, keep your credit utilization low, and utilize our free tracking spreadsheet to manage your student budget safely.

How to Organize Multiple Savings Goals Before 2027: A Simple Money Plan

How to Organize Multiple Savings Goals: A Simple Money Plan
Home » All Guides & Articles

Planning for multiple financial goals can feel overwhelming. This simple guide shows you how to prioritize your goals, set realistic targets, calculate monthly savings, and stay on track for 2027.

Saving for one goal is simple. But when you have several goals at the same time—such as an emergency fund, annual expenses, a new laptop, a trip, or future needs—it can become difficult to know where your money should go first.

The key is not to save for everything equally. You need to organize multiple savings goals, set priorities, and decide how much to save for each goal based on its deadline and importance.

In this guide, you’ll learn how to organize your savings goals, set realistic targets, calculate your monthly savings, and create a simple plan you can follow before 2027.

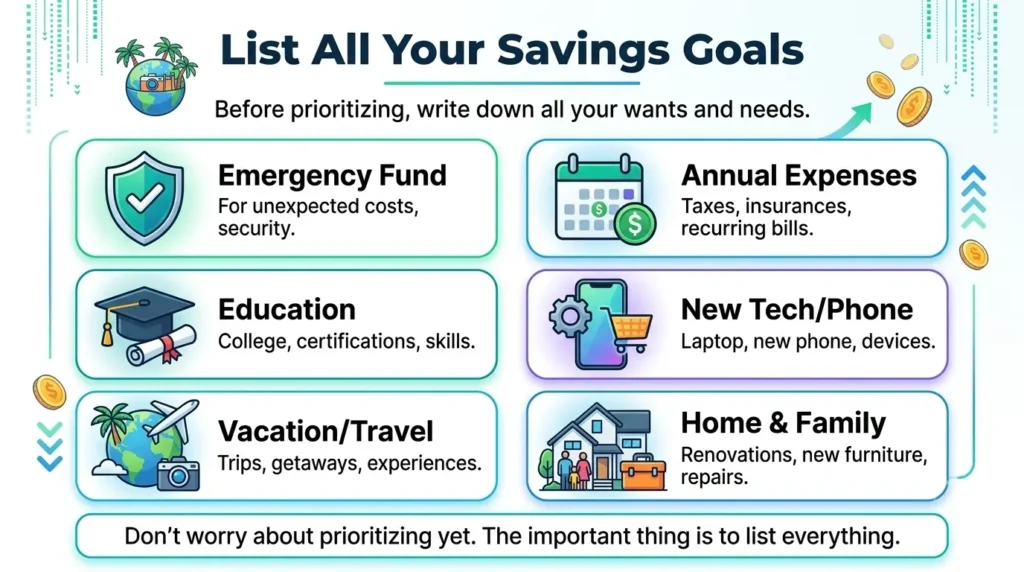
Step 1: List All Your Savings Goals

Before deciding how much to save for each goal, write down everything you want or need to save for.

Include both important financial goals and upcoming expenses, such as:

  • Emergency fund
  • Annual bills or expenses
  • Education
  • New phone or laptop
  • Vacation or travel
  • Home or family expenses
  • Other planned purchases

Don’t worry about prioritizing them yet. The first goal is simply to get a clear picture of where your money may need to go.

Once you have listed everything, you can group the goals by time frame, importance, and deadline. This makes it much easier to decide which goals should receive more attention first.

Step 2: Separate Short-Term, Medium-Term, and Long-Term Savings Goals

Not every savings goal has the same deadline. A bill due next month needs a different approach from a car you want to buy in three years or a future financial goal that may take much longer.

That is why one of the easiest ways to organize multiple savings goals is to separate them by time frame.

Short-Term Savings Goals

Short-term goals are goals you expect to reach relatively soon, such as annual bills, emergency expenses, a phone, or a planned purchase.

These goals usually need more immediate attention because their deadlines are closer.

Medium-Term Savings Goals

Medium-term savings goals sit between immediate expenses and long-term financial goals. They may take several months or a few years to complete, depending on the size and deadline of the goal.

Common examples include:

  • Buying a car
  • Saving for education or training
  • A major home expense
  • Starting a small business
  • Saving for a wedding or major event
  • Preparing for a large planned purchase

The advantage of a medium-term goal is that you have more time to build the money. Instead of trying to save a large amount at once, you can break the target into smaller monthly savings contributions.

How to Calculate a Medium-Term Savings Target

Use this simple formula:

Target Amount ÷ Months Remaining = Monthly Savings Needed

For example, suppose your goal is to save $3,000 in 30 months.

$3,000 ÷ 30 = $100 per month

So your basic monthly savings target would be $100.

GoalTargetTime RemainingMonthly TargetPriority
Education$3,00030 months$100High
Car fund$6,00036 months$167Medium
Major purchase$1,50024 months$63Low

This gives you a clearer picture of how much each goal requires instead of simply saving money without knowing whether you are on track.

What If the Monthly Amount Is Too High?

This is where a realistic savings plan matters.

If your calculated monthly contribution does not fit your budget, you have several options:

  • Extend the deadline if possible.
  • Reduce the target amount.
  • Give the goal a lower priority.
  • Temporarily focus on a more important goal.
  • Look for ways to reduce expenses or increase available savings.

You do not have to abandon a goal just because the first calculation does not fit your current cash flow.

The Consumer Financial Protection Bureau recommends breaking savings goals into manageable targets and considering the amount needed and the time available when creating a savings plan.

For a broader reference, you can also review the CFPB’s savings and goal-setting tools, which include tools for setting goals, planning savings, tracking money, and preparing for large purchases.

For your own numbers, you can use our budget calculator to see how your income and expenses affect the amount available for different savings goals.

The important point is simple: medium-term goals should have a target, deadline, and monthly contribution. Once those three numbers are clear, a large future expense becomes much easier to manage.

Step 3: Prioritize Your Savings Goals

Once you have separated your goals by time frame, the next step is to decide which savings goals should come first.

When you have multiple savings goals, you do not always need to divide your money equally. Some goals are more important because they protect your financial stability, have a fixed deadline, or could create a bigger problem if you do not prepare for them.

A simple priority system can help you decide where your monthly savings should go first.

Start With Financial Safety

Before putting a large amount toward optional goals, consider whether you have enough money set aside for unexpected expenses.

An emergency fund can help cover unexpected costs such as an urgent repair, medical expense, or temporary loss of income without forcing you to depend on debt.

Your financial priorities will depend on your situation, but building a basic financial safety net is often an important starting point.

For a broader overview, read our guide to the 7 rules of personal finance, which explains the role of budgeting, emergency savings, debt management, and long-term financial goals.

Consider the Deadline and Consequences

Not every savings goal has the same level of urgency. A goal with a fixed deadline may need more attention than a goal that can be delayed.

Before deciding how to divide your savings, ask yourself:

  • Does this expense have a fixed deadline?
  • What happens if I do not save enough by that date?
  • Is the goal essential or optional?
  • Can I delay the goal without creating a financial problem?
  • Could failing to prepare lead to debt or another financial cost?
  • Does this goal protect my basic financial needs?

For example, an annual insurance payment due in three months may deserve more attention than a vacation planned for next year.

The vacation can still be an important savings goal, but its deadline and consequences are different.

Use a High, Medium, and Low Priority System

A simple three-level priority system makes it easier to manage multiple savings goals without feeling overwhelmed.

PriorityType of GoalExample
HighFinancial safety or essential deadlineEmergency fund, essential annual expense
MediumImportant planned expenseEducation, major repair, vehicle
LowOptional or flexible goalVacation, new gadget, entertainment

This does not mean low-priority goals should never receive money. It simply means they should not take money away from a more important financial need when your available savings are limited.

How to Divide Money Between Savings Goals

If your monthly savings amount is limited, a useful starting order is:

  1. Financial safety
  2. Essential upcoming expenses
  3. Important planned goals
  4. Optional goals

For example, suppose you can save $300 per month and you have three goals:

  • Emergency fund — High priority
  • Education — Medium priority
  • Vacation — Low priority

Instead of automatically giving each goal $100, you could direct more of your available savings toward the emergency fund and education while making a smaller contribution toward the vacation.

The exact amounts depend on your income, essential expenses, current savings, and the deadlines of your goals.

If you want to connect your savings goals with your income and expenses, see our guide to financial planning for beginners.

Do Not Try to Fund Every Goal Equally

One common mistake when managing multiple savings goals is assuming that every goal should receive the same amount of money.

For example, imagine you have $500 available for savings and the following goals:

GoalAmount NeededDeadlinePriority
Emergency fund$1,500FlexibleHigh
Annual bill$6004 monthsHigh
Laptop$1,00010 monthsMedium
Vacation$1,20012 monthsLow

An equal split would give each goal $125. But the annual bill has a much closer deadline, while the vacation may be more flexible.

Your savings plan should reflect importance and urgency, not simply equality.

What If Two Savings Goals Have the Same Priority?

When two goals are equally important, use their deadlines to decide which one should receive more attention.

As a simple rule, consider the goal that:

  1. Has the earlier deadline.
  2. Requires a larger monthly contribution.
  3. Has greater consequences if you miss the target.

You can also change the priority later. Your income, expenses, deadlines, and financial goals may change, so your savings plan should be flexible enough to change with them.

Keep Your Savings Priorities Simple

You do not need a complicated financial planning system to organize multiple savings goals.

For each goal, know these four things:

  • What you are saving for
  • How much you need
  • When you need it
  • How important it is compared with your other goals

Once these details are clear, it becomes much easier to decide where your money should go each month.

The goal is not to create a perfect plan that never changes. The goal is to build a practical savings plan that gives every dollar a purpose while keeping your most important financial goals on track.

Step 4: Set a Target Amount and Deadline for Every Savings Goal

Once you know which savings goals are most important, give each goal a specific target amount and deadline.

“I want to save more money” is a good intention, but it is difficult to follow because there is no clear finish line. A better savings plan tells you exactly how much you need, when you need it, and how much you should save each month.

This approach can make multiple savings goals much easier to organize and track.

Give Every Financial Goal a Specific Target

Start by deciding the approximate amount you need for each goal.

For example, instead of writing:

  • Save for a laptop
  • Save for a trip
  • Save for education

Turn them into measurable goals:

  • Laptop — $1,000
  • Trip — $1,500
  • Education — $3,000

A specific target gives you something you can calculate against. It also makes it easier to see whether your current monthly savings are enough.

Set a Realistic Savings Deadline

After deciding the target amount, choose when you want or need to reach it.

Your deadline can be based on:

  • A fixed bill or payment date
  • A planned purchase
  • A school or education deadline
  • A planned trip or event
  • A personal financial milestone
  • A timeframe that is realistic for your income

Try not to choose a deadline simply because it sounds good. A deadline should be realistic enough that you can continue making the required monthly contribution without putting your essential expenses under pressure.

Calculate the Time You Have Left

Once you know the target and deadline, calculate how many months you have remaining.

For example:

GoalTargetTime AvailableApprox. Monthly Saving
Laptop$1,00010 months$100
Trip$1,50012 months$125
Education$3,00024 months$125

These numbers give you a starting point for building your monthly savings plan. In the next step, we will use the same information to calculate the required monthly contribution more precisely.

Use the SMART Approach for Savings Goals

A useful way to make a savings goal clearer is to make it specific and measurable, with a realistic timeframe.

For example:

Vague goal: “I want to save for a laptop.”

Clear goal: “I want to save $1,000 for a laptop within 10 months.”

The second goal gives you three important pieces of information:

  • What: Laptop
  • Target: $1,000
  • Deadline: 10 months

The Consumer Financial Protection Bureau’s SMART savings goal worksheet also uses a structured approach to help people turn a general savings intention into a clearer goal.

Use the Same Method in USD, GBP, or INR

The currency does not change the basic method. Whether you are saving in US dollars, British pounds, or Indian rupees, the process is the same:

Target amount → Deadline → Months remaining → Monthly savings requirement

For example:

CurrencyGoalTargetTime
USDLaptop$1,00010 months
GBPHoliday£1,20012 months
INREducation₹120,00024 months

You do not need to convert these amounts into one currency. Keep each goal in the currency you will actually spend.

What If the Target Is Too High for Your Income?

This is where your savings plan becomes practical.

Suppose you calculate that you need to save $400 per month for several goals, but after essential expenses you can realistically save only $250.

Do not simply assume you have failed. Rework the plan.

You could:

  • Extend the deadline
  • Reduce the target amount
  • Give higher priority to the most important goal
  • Temporarily pause a lower-priority goal
  • Reduce unnecessary expenses
  • Increase your savings contribution when your income rises

A realistic savings target that you can consistently follow is usually more useful than an aggressive target that makes your monthly budget impossible to maintain.

Keep Your Savings Goals in One Simple Table

Once you have several goals, put the important numbers in one place. This makes it easier to see the complete picture instead of keeping separate notes in your head.

GoalTargetSavedRemainingDeadlinePriority
Emergency fund$1,500$600$900FlexibleHigh
Laptop$1,000$250$75010 monthsMedium
Vacation$1,200$300$90012 monthsLow

This simple savings tracker gives you a quick view of what you are saving for, how much you have already saved, what remains, and which goals deserve the most attention.

Once every goal has a target and deadline, the next step is to calculate exactly how much you need to save each month.

Step 5: Calculate Your Monthly Savings for Each Goal

Now that every savings goal has a target amount and deadline, you can calculate how much you need to save each month.

This is the point where a list of financial goals becomes an actual savings plan. Instead of guessing how much to put aside, you can work backward from the amount you need and the time available.

Use the Monthly Savings Formula

The basic calculation is simple:

Monthly Savings Needed = Amount Remaining ÷ Months Remaining

For example, suppose you want to save $1,200 for a planned purchase and you have 12 months remaining.

$1,200 ÷ 12 = $100 per month

So, you would need to set aside approximately $100 each month to reach the target, assuming the money you save does not earn additional returns and there are no extra costs.

Calculate Each Savings Goal Separately

When you have multiple savings goals, calculate the monthly contribution for each one instead of combining all the targets into one number.

GoalAmount RemainingMonths RemainingMonthly Savings
Emergency fund$1,00010$100
Laptop$9009$100
Vacation$1,20012$100

In this example, the total monthly requirement would be:

$100 + $100 + $100 = $300 per month

Now you can compare that $300 requirement with the amount your monthly budget can realistically provide.

Check Your Monthly Savings Capacity

Before committing to a savings target, look at your actual cash flow.

A simple starting calculation is:

Monthly Income − Essential Expenses − Required Payments = Potential Savings

For example:

Monthly BudgetAmount
Income$2,500
Essential expenses$1,700
Required payments and regular spending$400
Potential savings$400

If your savings goals require $300 per month and you can realistically save $400, the plan has some room for unexpected expenses or faster progress.

If your goals require $550 but your realistic savings capacity is only $400, you need to adjust the goals rather than forcing an unrealistic budget.

Use a Budget Calculator to Find Your Available Savings

Working out your income and expenses manually can become difficult when you have several financial goals.

You can use our Budget Calculator to organize your income and spending and get a clearer idea of how much money may be available for savings each month.

Once you know your available savings amount, you can compare it with the monthly contribution required for each goal.

What If Your Monthly Savings Requirement Is Too High?

This is one of the most important parts of creating a realistic savings plan.

If the numbers do not fit your budget, do not simply cut essential expenses or put yourself under unnecessary financial pressure. Rework the plan.

You can:

  • Extend the deadline: Give yourself more months to reach the target.
  • Reduce the target: Look for a lower-cost version of the planned purchase.
  • Prioritize: Put more money toward essential or time-sensitive goals.
  • Pause a lower-priority goal: Temporarily stop funding a flexible goal.
  • Increase your savings capacity: Reduce unnecessary spending or direct future extra income toward the goal.
  • Review the target: Make sure the original amount is still realistic.

A savings plan should fit your real financial situation. A target that looks impressive on paper but cannot be maintained every month is not a useful target.

Use the Deadline to Adjust Your Monthly Contribution

Your monthly savings requirement can change when the deadline changes.

TargetDeadlineMonthly Savings
$1,2006 months$200
$1,20012 months$100
$1,20018 monthsAbout $67

This shows why the deadline matters. The same savings goal can require very different monthly contributions depending on how much time you have.

Do Not Forget the Amount You Have Already Saved

If you have already saved part of the money, calculate the monthly requirement using the remaining amount, not the original target.

For example:

Target: $2,000
Already saved: $500
Remaining: $1,500
Time remaining: 10 months

$1,500 ÷ 10 = $150 per month

This makes your savings target more accurate and prevents you from saving more than necessary for the same goal.

Keep a Small Buffer for Real Life

Monthly budgets do not always go exactly as planned. An unexpected expense can temporarily reduce the amount you are able to save.

For that reason, avoid building a savings plan that uses every available dollar with no flexibility.

If your calculations show that you can save $400 per month, but your goals require exactly $400, consider whether you need some breathing room for irregular expenses before committing to the full amount.

This is especially important when your income changes from month to month.

The Consumer Financial Protection Bureau’s Your Money, Your Goals toolkit also provides tools and guidance for setting goals, planning spending, and managing savings.

A Simple Rule for Multiple Savings Goals

Once you calculate the monthly requirement for every goal, add them together and compare the total with your realistic monthly savings capacity.

If required savings ≤ available savings: Your plan may be realistic.

If required savings > available savings: Prioritize the goals and adjust the deadlines, targets, or contributions.

This simple comparison can prevent a common problem: creating too many savings goals without checking whether your income can actually support them.

In the next step, we will look at how to divide your available money between multiple savings goals when you cannot fully fund every goal at the same time.

Step 6: How to Divide Money Between Multiple Savings Goals

Knowing how much you need to save each month is only half the job. When you have several financial goals, you also need to decide how to divide your available savings between them.

You do not have to give every goal the same amount. The right approach depends on each goal’s priority, deadline, target amount, and how much you can realistically save after your regular expenses.

The aim is to create a savings plan that is realistic enough to follow every month while still moving your most important financial goals forward.

First, Know How Much You Can Save Each Month

Before deciding how much goes into each goal, calculate your available monthly savings.

A simple starting point is:

Monthly Income − Essential Expenses − Required Payments = Potential Savings

For example, if your monthly income is $2,500, essential expenses are $1,700, and other required payments and regular spending total $400, you may have around $400 available for savings.

You can use our Budget Calculator to organize your income and expenses and get a clearer picture of how much you may be able to save each month.

If you want a broader approach to dividing your income between spending, savings, and financial priorities, you can also read our guide on how to divide your salary for beginners.

Method 1: Equal Contribution for Multiple Savings Goals

The simplest approach is to divide your available savings equally between your goals.

For example, if you can save $300 per month and have three goals, you could contribute:

  • Goal 1 — $100 per month
  • Goal 2 — $100 per month
  • Goal 3 — $100 per month

This method is easy to understand and can work well when the goals have similar importance and similar deadlines.

However, equal contributions are not always the best option. If one goal has a much earlier deadline or greater financial importance, it may need a larger share of your monthly savings.

Method 2: Priority-Based Savings

With a priority-based savings plan, you give more of your available money to goals that are more important and reduce contributions to goals that can wait.

A simple order could be:

  1. Financial safety
  2. Essential upcoming expenses
  3. Important planned goals
  4. Optional goals

For example, if you are building an emergency fund while also saving for a vacation, you may decide that the emergency fund deserves a larger contribution because it provides greater financial protection.

This method can be especially useful when your monthly savings are limited and you cannot fully fund every goal at the same time.

Method 3: Deadline-Based Savings

Another practical method is to divide your savings according to how soon each goal needs to be funded.

Suppose you have the following goals:

GoalAmount RemainingTime RemainingPriority
Annual bill$6004 monthsHigh
Laptop$1,00010 monthsMedium
Vacation$1,20012 monthsLow

The annual bill has the closest deadline, so it may need more immediate attention. The laptop and vacation goals have more time, which gives you greater flexibility with their contributions.

This method is particularly useful for short-term and medium-term savings goals where missing a deadline could create a financial problem.

Which Savings Method Should You Choose?

There is no single method that works for every person or every savings goal. You can choose one method or combine several.

MethodBest ForMain Advantage
Equal contributionGoals with similar importanceSimple and easy to maintain
Priority-basedLimited monthly savingsFocuses money on important goals
Deadline-basedGoals with different due datesHelps prevent missed deadlines

For example, you could use a priority-based approach for your emergency fund and essential expenses, then divide whatever remains between flexible goals.

Example: Dividing $500 Between Multiple Savings Goals

Suppose you have $500 available for savings each month and four goals:

GoalPriorityMonthly Contribution
Emergency fundHigh$200
Annual expensesHigh$150
LaptopMedium$100
VacationLow$50
Total$500

This is only an illustrative example, not a universal rule. Your own allocation should be based on your income, expenses, current savings, deadlines, and priorities.

The important idea is that you do not need to divide your money equally just because you have multiple goals.

Match Your Savings Allocation With Your Financial Plan

Your savings goals should not exist separately from the rest of your budget. They should fit into your overall financial plan.

Consider:

  • Your monthly income
  • Essential living expenses
  • Existing debt or required payments
  • Emergency savings
  • Upcoming annual expenses
  • Short-term financial goals
  • Longer-term goals

Our guide to financial planning for beginners explains how different money priorities can be organized into a broader financial plan.

For additional guidance on setting savings goals and creating a savings plan, you can also refer to the Consumer Financial Protection Bureau’s savings plan tool.

What If You Cannot Fund Every Goal?

This is completely normal. Having several savings goals does not mean you have to make progress on all of them at the same speed.

If your required monthly contributions are higher than your available savings, you can:

  • Focus on the highest-priority goal first.
  • Give more time to a flexible goal.
  • Reduce the target amount if appropriate.
  • Temporarily pause a lower-priority goal.
  • Redirect money to another goal after completing one target.
  • Increase contributions later when your financial situation improves.

A realistic savings plan is better than a complicated plan that consistently leaves you short of money.

Review and Rebalance Your Savings Goals

Your savings allocation does not need to remain unchanged throughout the year.

Review your plan at least once a month and consider whether:

  • Your income has changed.
  • Your regular expenses have increased or decreased.
  • A deadline is getting closer.
  • You have already reached one of your targets.
  • A new essential expense has appeared.
  • One goal has become more or less important.

For example, once you finish saving for an annual expense, you can redirect that monthly contribution toward your next priority instead of leaving the money unassigned.

A Simple Rule for Dividing Your Savings

If you are unsure where your money should go, ask yourself three questions every month:

  • What is most important right now?
  • Which goal has the nearest deadline?
  • How much can I realistically save this month?

Your answers can help you decide how to divide money between multiple savings goals without making your budget unnecessarily complicated.

The goal is not to save the same amount for everything. The goal is to give your available money a clear purpose while keeping your most important financial goals on track.

How many savings goals should I have at one time?

There is no fixed number of savings goals you should have. Start with the goals that are most important and realistic for your current income. Too many goals can make it harder to stay consistent, so focus on your priorities first.

Should I save for multiple goals at the same time?

Yes. If your budget allows, you can save for several goals at the same time. Give more money to urgent or essential goals and smaller amounts to flexible goals.

What should I do if I cannot save enough for all my goals?

Prioritize your most important goals instead of trying to fund everything equally. You can reduce optional targets, extend deadlines, or increase your monthly savings later when your income improves.

How often should I review my savings goals?

Review your savings plan at least once a month. Check your progress, remaining amount, deadlines, and monthly contributions. Adjust the plan whenever your income, expenses, or priorities change

Final Thoughts: How to Organize Multiple Savings Goals

Managing multiple savings goals becomes much easier when every goal has a clear target, deadline, and priority. Instead of trying to save for everything equally, focus your money on what matters most and adjust your plan as your situation changes.

Start small, stay consistent, and review your progress each month. A simple plan you can follow is more valuable than a complicated plan you cannot maintain.

Cash Stuffing Method for Beginners: A Simple Step-by-Step Guide

Cash stuffing method for beginners with labeled budgeting envelopes
Home » All Guides & Articles

Managing money can feel difficult when small purchases keep adding up throughout the month. The cash stuffing method offers a simple way to give each spending category a clear limit and make your budget easier to see and follow.Instead of keeping your entire spending budget in one place, you divide cash into separate categories such as groceries, transportation, eating out, or personal spending. When an envelope gets low, you know exactly how much is left for that category.In this guide, you’ll learn how cash stuffing works, how to set up your first envelopes, how much to allocate to each category, and how to adapt the method for different budgets and payment habits.

What Is the Cash Stuffing Method for Beginners?

The cash stuffing method for beginners is a simple way to organize your spending by separating money into different categories. Instead of keeping all your spending money together, you decide how much you want to use for groceries, transportation, eating out, entertainment, or other everyday expenses.

The basic idea is simple: give your money a purpose before you spend it.

For example, if you have $500 available for flexible spending, you might divide it between several categories instead of treating the entire $500 as available for anything. In India, the same idea could be applied to ₹40,000 of monthly income or spending money. The actual amounts depend on your income, bills, and personal circumstances.

How Does Cash Stuffing Work

Traditional cash stuffing uses physical envelopes. Each envelope represents a spending category, and you place the amount you’ve budgeted for that category inside it.

A simple setup might include:

  • Groceries
  • Transportation
  • Eating out
  • Entertainment
  • Personal spending
  • Miscellaneous

When you spend money, you take it from the relevant category. If your grocery envelope has $150 left, for example, you know that $150 is what remains for groceries under that budget.

The system is closely related to the cash envelope system and traditional envelope budgeting. The Consumer Financial Protection Bureau (CFPB) has also discussed the envelope approach as a way of separating money for different spending categories.

Why Do People Use Cash Stuffing?

The main attraction is visibility.

When your spending money is separated into categories, it can be easier to notice how much you have left before making another purchase.

That doesn’t mean cash stuffing will automatically stop overspending. It simply gives you a clear spending boundary to work with.

For someone who regularly wonders, “Where did my money go this month?”, seeing separate amounts for different categories can make budgeting feel more concrete.

Does Cash Stuffing Mean Using Only Physical Cash?

Not necessarily.

Physical envelopes are the traditional version, but the underlying idea can also work with digital budgeting.

Someone in the US might use cash envelopes for groceries and entertainment while keeping rent and online bills in a bank account.

A UK reader might use digital “pots” for some categories.

In India, where UPI and digital payments are widely used, someone may prefer a hybrid approach—keeping some categories in cash while tracking other spending digitally.

The important principle is separating money by purpose, not carrying every expense in your wallet.

Cash Stuffing at a Glance

ElementWhat it means
IncomeMoney available for your budget
CategoriesDifferent types of spending
EnvelopesSeparate places for each category
Spending limitAmount assigned to a category
TrackingRecording what you spend
ReviewChecking what worked and what needs adjusting

This is only the basic idea. The next step is understanding how to actually set up a cash stuffing budget, choose the right categories, and decide how much money should go into each one.

How Much Money Should You Put in Each Cash Stuffing Envelope?

Once you know your income and regular expenses, the next step is deciding how much money to put into each envelope.

There is no single amount that works for everyone. Your cash stuffing budget should reflect your income, essential expenses, family situation, location, and normal spending habits.

A good starting point is to look at what you actually spend rather than copying someone else’s envelope amounts.

Start With Your Real Spending

Before setting your limits, look at your recent bank statements, receipts, or budgeting records.

You might notice that groceries regularly cost more than you expected, while entertainment spending is much smaller.

That information is useful.

Try to identify the categories where your spending is both variable and controllable.

Common examples include:

  • Groceries
  • Eating out
  • Transportation
  • Entertainment
  • Clothing
  • Personal spending
  • Household purchases
  • Miscellaneous expenses

If you don’t know your spending patterns yet, track them for a few weeks before creating strict limits.

This makes the cash envelope system more realistic and easier to maintain.

Separate Fixed Bills From Flexible Spending

Cash stuffing doesn’t require you to put every expense into a physical envelope.

Some expenses are already predictable or automatically paid from your bank account.

For example:

  • Rent or mortgage
  • Insurance
  • Loan payments
  • Subscriptions
  • Internet and phone bills
  • Other recurring payments

Cash envelopes are usually more useful for spending that can change from week to week.

The goal is not to make your finances complicated. It’s to create a clear boundary around the spending you can control.

A Simple Cash Stuffing Example

Imagine someone in the US takes home $2,500 a month.

After accounting for essential bills, savings, and other financial commitments, they have $600 available for selected flexible expenses.

They might start with:

CategoryExample Amount
Groceries$300
Transportation$100
Eating out$75
Personal spending$75
Miscellaneous$50
Total$600

These numbers are only an example. They are not recommended spending limits.

A person in the UK might work with £500, while someone in India might have ₹10,000 available for similar variable categories.

The currency and cost of living change, but the basic idea remains the same: divide the money according to your own spending needs.

Don’t Set Unrealistic Envelope Limits

One common beginner mistake is trying to make the budget look perfect on paper.

Suppose you normally spend around $350 on groceries but decide to put only $200 into your grocery envelope because you want to save more.

If you run out of money halfway through the month, the problem may not be the cash stuffing method. Your original limit may simply have been unrealistic.

A better approach is to start with your actual spending and make gradual adjustments

What If Your Income Changes?

The cash stuffing method for beginners can also be adapted for irregular income.

If you receive money weekly, work freelance, or have changing monthly income, you don’t necessarily need to decide your entire month’s envelope amounts at once.

Instead, you can allocate money when you actually receive it.

For example:

Paycheck arrives → cover priorities → allocate flexible spending → stuff envelopes → track spending

This approach can be easier when your income isn’t the same every month.

For UK readers, MoneyHelper’s budgeting guidance provides practical information on understanding income, expenses, and household budgeting.

For Indian readers, the Reserve Bank of India’s financial education resources also emphasize planning income and expenses and comparing planned spending with actual expenditure.

Use a Budget Calculator Before You Decide

If you’re not sure how much money is actually available after your regular expenses, you can first use our Budget Calculator to organise your numbers.

Think of the process like this:

Income → Essential expenses → Savings/debt goals → Flexible spending → Cash stuffing categories

This helps prevent a common mistake: filling your envelopes first and discovering later that you don’t have enough money for an important bill.

Start Small

You don’t need ten or twenty envelopes on your first attempt.

Start with three to five categories that are genuinely useful for your spending habits.

For example:

  • Groceries
  • Transportation
  • Eating out
  • Personal spending
  • Miscellaneous

After a month, review what happened.

If one envelope consistently has money left over, you can reconsider its limit.

If another runs out too quickly, look at your actual spending before simply adding more money.

Your first cash stuffing budget doesn’t need to be perfect. It needs to be realistic enough to help you understand and control your spending.

What Categories Should You Use for Cash Stuffing?

You don’t need a separate envelope for every expense. Start with the spending categories where you are most likely to overspend.

Best Cash Stuffing Categories for Beginners

Common categories include:

  • Groceries — food and household shopping
  • Transportation — fuel, bus, train, or local travel
  • Eating Out — restaurants, snacks, and coffee
  • Personal Spending — small personal purchases
  • Entertainment — movies, games, and hobbies
  • Gifts — birthdays, festivals, and special occasions
CategoryExample
Groceries$250 / £200 / ₹8,000
Transportation$100 / £80 / ₹3,000
Eating Out$75 / £60 / ₹2,500
Personal$75 / £60 / ₹2,500

These amounts are only examples. Your actual budget should depend on your income and regular spending.

Don’t Put Every Expense in an Envelope

Fixed expenses such as rent, mortgage payments, electricity bills, and subscriptions usually don’t need physical cash envelopes. You can continue paying them digitally or through your bank account.

For irregular expenses like gifts, clothing, or annual costs, a sinking fund can be useful. MoneyHelper explains sinking funds as a way to prepare for expenses that don’t happen every month.

If you are unsure how much you can actually afford for each category, first use the Budget Calculator.

Start small: 3–5 useful categories are usually easier to manage than 15–20 envelopes. Once the system becomes a habit, you can add more categories if needed.

How to Start Cash Stuffing: A Step-by-Step Setup

Starting the cash stuffing method is easier when you follow a simple routine instead of trying to change all your spending habits at once. The basic idea is to decide your limits, separate the money into categories, and track what you spend.

1. Choose Your Budget Period

First, decide how often you want to organize your envelopes.

You can use a:

  • Weekly system if you prefer tighter spending control
  • Biweekly system if you get paid every two weeks
  • Monthly system if you receive a monthly salary

Your choice should match your income schedule and spending pattern.

If you want to understand how to divide your income before creating envelopes, read our How to Divide Your Salary for Beginners guide.

2. Prepare and Label Your Envelopes

Choose a few categories that you actually use.

For example:

  • Groceries
  • Transportation
  • Eating out
  • Personal spending
  • Entertainment

Write the category name clearly on each envelope. Starting with 3–5 categories can make the system easier to maintain.

3. Decide How Much Goes Into Each Envelope

Use the spending limits from your budget rather than guessing.

For example, a monthly flexible-spending budget might look like this:

CategoryExample Amount
Groceries$250
Transportation$100
Eating out$75
Personal$75

These amounts are only examples. Your actual limits should depend on your income, essential expenses, and normal spending.

You can first use our Budget Calculator to organize your numbers.

4. Track Every Purchase

This is one of the most important parts of cash stuffing.

Suppose your grocery envelope contains $250. You spend $35 at the supermarket, so your remaining amount is $215.

Writing down each purchase helps you know exactly how much is available instead of relying on memory.

MoneyHelper also recommends keeping track of income and spending when creating a workable budget. You can learn more from its budgeting guidance.

5. Review and Adjust

At the end of your budget period, check what happened.

Ask yourself:

  • Which envelope ran out first?
  • Which category had money left?
  • Were any limits unrealistic?
  • Should money be moved between categories next time?

Don’t treat going over one category as failure. It can simply show that your original estimate needs adjusting.

For readers in India, the RBI financial education material also provides guidance on budgeting and managing personal finances.

If your income is very tight and covering basic expenses is already difficult, see our paycheck-to-paycheck budgeting guide for a more focused approach.

The goal is not to follow a perfect envelope system. The goal is to create a spending system that you can realistically follow every pay period.

What Happens When a Cash Stuffing Envelope Runs Out?

One of the biggest questions beginners have is: What should you do when an envelope reaches $0 before the end of the month?

It doesn’t automatically mean your budget has failed. It may simply mean that your spending limit needs to be reviewed.

Check Before Moving Money

First, ask whether the expense is actually necessary.

For example, if your entertainment envelope is empty, you may decide to wait until the next budget period. But if your grocery budget is short because food prices were higher than expected, the situation may be different.

A simple rule is:

Needs first, wants second.

SituationWhat You Can Do
Non-essential spendingWait until the next period
Essential expenseConsider moving money from a lower-priority category
Unexpected expenseUse an appropriate emergency/savings fund
Budget repeatedly runs shortRecalculate your category limits

Can You Move Money Between Envelopes?

Yes. Your budget doesn’t have to be completely rigid.

Suppose your Eating Out envelope has $40 left, while your Groceries envelope needs another $25. If groceries are the priority, you could move $25 from Eating Out to Groceries.

The important part is to record the transfer so you know where your money went.

What If This Happens Every Month?

If the same envelope runs out repeatedly, don’t simply keep adding money to it.

Look at your actual spending and adjust the budget.

For example, if you regularly spend $300 on groceries but your budget allows only $250, your original limit may not reflect your real situation.

Our salary division guide can help you review how your income is being allocated across different priorities.

What About Leftover Money?

If an envelope still has money at the end of the period, you have several options:

  • Carry it into the next period
  • Move it toward a planned expense
  • Add it to savings
  • Keep a small buffer for future spending

For irregular expenses, a sinking-fund approach can make budgeting easier. MoneyHelper’s sinking-fund guidance explains how setting money aside over time can help prepare for expenses that don’t happen every month.

The goal of cash stuffing isn’t to punish yourself for spending. It’s to make your spending choices visible and intentional. If you’re already struggling to cover essential expenses, our paycheck-to-paycheck budgeting guide covers a more focused approach for tight budgets.

Cash Stuffing vs. Digital Budgeting: Which Is Better?

Cash stuffing works by making your spending limits visible through separate cash envelopes. Digital budgeting uses bank accounts, budgeting apps, spreadsheets, or digital savings pots to organize the same idea electronically.

Neither method is automatically better. The right choice depends on how you normally spend and how often you use cash.

FeatureCash StuffingDigital Budgeting
Spending visibilityVery highHigh
Physical cash neededYesNo
Card/UPI paymentsLimited unless hybridEasy
TrackingManualOften automatic
Best forControlling flexible spendingDigital-first spending

When Cash Stuffing Can Work Well

Physical cash can make a spending limit feel more concrete. Once the envelope is nearly empty, you can immediately see that you’re approaching your limit.

This can be particularly useful for categories such as groceries, eating out, entertainment, or personal spending.

When Digital Budgeting Makes More Sense

Cash isn’t practical for every expense. Rent, subscriptions, online shopping, bills, and many everyday transactions are normally paid digitally.

That’s why a hybrid cash stuffing system can be useful. You might use cash for flexible spending while keeping fixed bills and other payments in your bank account.

For readers in the UK, MoneyHelper’s jam jar approach shows how separating money into different pots can also be done digitally.

In India, where digital payments are widely used, you can combine cash envelopes with separate bank-account or savings categories rather than forcing every expense into physical cash.

Which Should Beginners Choose?

Start with the method you are most likely to follow consistently.

If you often overspend on small purchases, physical envelopes may give you stronger spending awareness. If you rarely use cash, a digital or hybrid approach may be more practical.

You can also combine this method with the broader budgeting principles in our Personal Finance for Beginners guide.

The goal isn’t to use cash simply because it’s called “cash stuffing.” The goal is to give every spending category a clear limit and make your money easier to manage.

Common Cash Stuffing Mistakes Beginners Should Avoid

Cash stuffing looks simple, but a few common mistakes can make the system difficult to maintain. The good news is that most of them are easy to fix.

1. Creating Too Many Envelopes

You don’t need an envelope for every small expense.

Starting with 15–20 categories can make your budget feel like another chore. Begin with 3–5 important spending categories and add more only when necessary.

2. Setting Unrealistic Limits

A budget shouldn’t be based on what you wish you spent. It should reflect your actual situation.

If you normally spend $300 on groceries but set a $150 limit without a realistic plan to reduce costs, the envelope may run out quickly.

Review your real spending before changing your limits. Our Budget Calculator can help you organize your numbers.

3. Trying to Use Cash for Everything

Not every expense needs a physical envelope.

Rent, subscriptions, online payments, and many bills can remain digital. A hybrid budgeting system can be more practical than forcing every payment into cash.

4. Forgetting to Track Spending

Cash can disappear quickly when you make several small purchases.

Write down each transaction or keep a simple note on your phone. This makes it easier to understand where your money is actually going.

5. Taking Money From Other Envelopes Without Recording It

Moving money between categories is sometimes reasonable. But repeatedly doing it without tracking the changes can hide the real problem.

If you keep taking money from groceries to cover entertainment, for example, your category limits may need to be reviewed.

6. Ignoring Irregular Expenses

Some expenses don’t appear every month but still need planning.

Gifts, annual subscriptions, clothing, repairs, and seasonal expenses can be handled through a sinking fund rather than pretending they don’t exist.

MoneyHelper’s guide to sinking funds explains how setting aside smaller amounts over time can help prepare for less frequent expenses.

7. Giving Up After One Bad Month

One difficult month doesn’t mean cash stuffing doesn’t work for you.

Your first budget is an estimate. After a few weeks, you’ll have better information about your actual spending habits.

If you’re managing a very tight income, our How to Budget When Living Paycheck to Paycheck guide can help you build a more realistic spending plan.
For broader money-management principles, you can also explore our 7 Rules of Personal Finance guide.

The Simple Rule to Remember

Don’t try to make your cash stuffing system perfect. Make it sustainable.

Start with a few categories, use realistic limits, track your spending, and adjust the system when your circumstances change. That’s what turns cash stuffing from a budgeting experiment into a habit you can actually maintain.


Is cash stuffing good for beginners?

Yes. Cash stuffing can be beginner-friendly because it gives each spending category a clear limit and makes it easier to see how much money is available.

How much money should I put in cash stuffing envelopes?

Use an amount that fits your actual budget. After essential expenses, divide your flexible spending money between categories such as groceries, transportation, personal spending, and entertainment.

What happens if I run out of money in an envelope?

Check whether the expense is essential. If it is, you can move money from a lower-priority category and record the transfer. For non-essential spending, waiting until the next budget period may be the better option.

Can I do cash stuffing without using physical cash?

Yes. You can use a digital or hybrid system with bank accounts, savings pots, spreadsheets, or budgeting apps. The principle remains the same: separate your money into spending categories with clear limits

Conclusion

The cash stuffing method can be a simple way to make everyday spending easier to understand and control. Instead of treating your entire budget as one amount, you give different spending categories clear limits.

You don’t need to start with a complicated system. Choose a few categories, set realistic amounts, track your spending, and adjust your envelopes when your real spending doesn’t match your original plan.

And remember, cash stuffing doesn’t have to mean using physical cash for everything. A digital or hybrid approach can work too, especially for bills and online payments.

The best budgeting system is the one you can understand, follow, and maintain consistently. Start small, learn from each budget period, and improve your system over time.

How to Budget When Living Paycheck to Paycheck
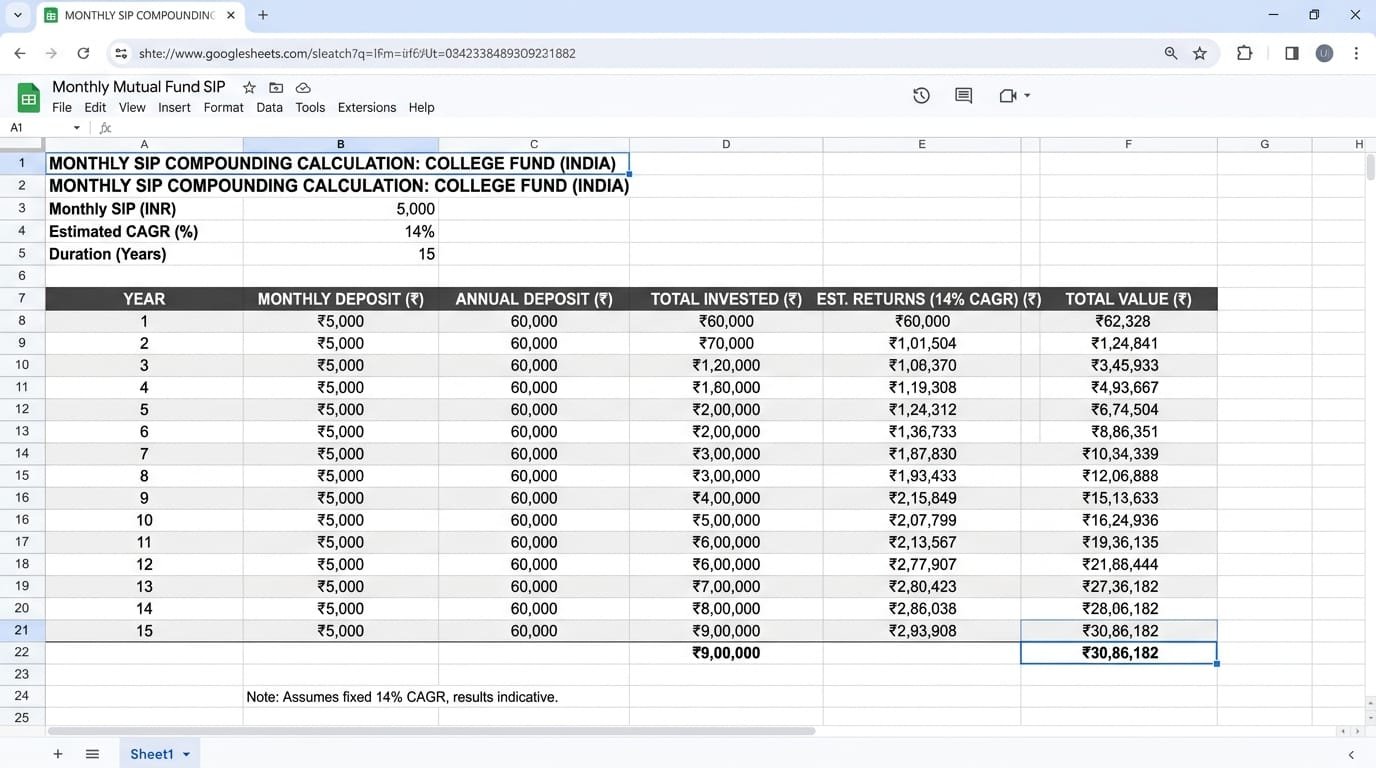
7 ways to make your salary last longer

If your paycheck runs out before your next payday, budgeting can feel almost impossible—especially when your income is already low. The problem may not be unnecessary spending; your essential expenses may simply leave too little room.This guide explains how to budget when living paycheck to paycheck on a low income, find where your money is actually going, and create a practical plan to make each paycheck last longer.

Find Out Why Your Paycheck Runs Out Before Payday

Before changing your budget, first find out why your money is running out. If you don’t know where the shortage is coming from, cutting random expenses may not solve the problem.

Start with your take-home income for one pay period. Then list the expenses that must be paid before your next paycheck, such as housing, food, transportation, utilities, and required payments.

For example, if you receive ₹10,000 and need ₹4,000 for housing, ₹2,000 for food, ₹1,000 for transportation, and ₹1,500 for essential bills, you have ₹1,500 left.

Now ask yourself: Can that ₹1,500 realistically cover everything until your next payday?

If yes, the problem may be how the remaining money is being spent or when certain expenses occur. If no, your essential costs may already be leaving too little income available.

The same calculation works whether your paycheck is ₹10,000, $1,000, or £900. The amounts will differ, but the question stays the same: how much income is left after the expenses you cannot avoid?

This simple check helps you identify whether your main problem is spending, payment timing, or an income that is not enough to cover essential costs. Once you know the actual problem, you can build a budget around it instead of guessing where your money is going.

Calculate Your Minimum Amount Needed Until the Next Paycheck

Once you know why your paycheck is disappearing, calculate the minimum amount you actually need before the next payday. This gives you a clear spending limit instead of treating your whole paycheck as available money.

Start with the expenses that cannot reasonably be postponed until later. For example, if your next paycheck is 10 days away, include the food, transportation, bills, and other essential payments you need during those 10 days.

Suppose you receive ₹10,000 and your next paycheck is 10 days away:

  • Essential food: ₹2,000
  • Transportation: ₹1,000
  • Upcoming bill: ₹2,500
  • Other required expense: ₹1,000

Your minimum amount needed is ₹6,500.

That means the remaining ₹3,500 should not automatically be treated as spending money. It can become a buffer, cover an upcoming expense, or help reduce the pressure on your next paycheck.

The same method works with $1,000 or £900. The numbers will change depending on your location and expenses, but the principle remains the same: separate money you must use from money you can safely leave untouched.

This small calculation can change the way you look at each paycheck. Instead of asking, “How much money do I have?” you start asking, “How much of this money is actually available?”

Build a Paycheck Plan Around Your Essential Expenses

When you are living paycheck to paycheck, a budget should do more than divide your income into categories. It should help you control the timing of your money so that an expense due next week does not compete with today’s spending.

After calculating what you need until your next paycheck, give each important amount a specific job. This creates a simple cash-flow plan without forcing every household into the same percentage-based budget.

Reserve Money for Bills Before They Are Due

Start with bills that will need to be paid before your next paycheck arrives. These might include rent, utilities, phone bills, transportation payments, or other unavoidable commitments.

For example, suppose you receive ₹10,000 today and ₹3,500 of bills are due before your next payday. That ₹3,500 should be treated as committed money even though it is still sitting in your account.

The same idea applies to a $1,000 or £900 paycheck. The currency changes, but the problem is the same: money can look available simply because the bill has not arrived yet.

A bill calendar from the Consumer Financial Protection Bureau can help you track what you owe and when each payment is due. This is particularly useful when the timing of income and expenses is causing the cash shortage.

Turn the Remaining Days Into a Spending Limit

Once upcoming bills are protected, calculate what you need for essential day-to-day spending until payday.

Imagine you have 10 days remaining and expect to spend about ₹200 per day on necessary food and transportation:

₹200 × 10 days = ₹2,000

Instead of treating your whole account balance as spendable, ₹2,000 becomes the working amount for those essentials.

You can use the same calculation with dollars or pounds. For example, if your essential daily spending is $12 and you have 8 days until payday, your basic requirement would be $96.

This creates a useful distinction: your account balance shows what you have, while your spending limit shows what you can safely use.

Leave Room for Small Unplanned Expenses

A budget that leaves no flexibility can be difficult to follow. A small unexpected expense can force you to take money from a bill or another essential category.

After covering your required expenses, keep a modest flexible amount that fits your situation.

  • ₹500 for a ₹10,000 example paycheck
  • $30 for a $1,000 example paycheck
  • £25 for a £900 example paycheck

These numbers are examples, not recommended percentages. Your flexible amount should depend on your actual income and expenses.

The important rule is simple: once this amount is used, do not automatically increase it by taking money reserved for essential expenses.

Give the Remaining Money a Specific Job

After protecting bills, essential daily spending, and a small flexible amount, look at what remains. Do not automatically label it as “extra money.” Decide what that money is supposed to do.

₹10,000 PaycheckAmountPurpose
Upcoming bills₹3,500Protect until due date
Food + transportation₹2,00010-day essentials
Flexible spending₹500Small unexpected needs
Remaining amount₹4,000Protect for the next financial need

The ₹4,000 remaining in this example should not automatically become shopping or entertainment money. It could help cover an upcoming expense, provide breathing room for the next pay period, or be directed toward another priority once your immediate needs are secure.

This is similar to the basic idea behind MoneyHelper’s jam-jar budgeting approach, where money is separated into different pots for different purposes so that spending money is less likely to interfere with money reserved for bills.

When Money Is UnassignedWhen Money Has a Job
The full balance feels availableOnly the appropriate amount feels available
Upcoming bills are easy to forgetUpcoming bills are protected
Daily spending can consume future moneyDaily spending has a defined limit
Payday feels like a resetEach paycheck is planned around the next one

If you want to understand broader salary allocation, you can also read your existing guide to dividing your salary. That article covers percentage-based allocation and salary budgeting; this section focuses specifically on protecting cash between paychecks, so the two articles serve different purposes.

The goal is not to make every paycheck fit a perfect formula. It is to make sure money needed for the next few days and weeks is protected before you decide what you can actually spend.

Create a Survival Budget for the Lowest-Income Weeks

When you live paycheck to paycheck, your budget cannot depend on every paycheck being the same. A week with fewer working hours, lower overtime, or an unexpected expense can leave you with much less money than usual.

Instead of rebuilding your entire budget whenever income falls, create a survival budget based on the minimum amount you need to keep your essential expenses covered.

Find Your Bare-Minimum Monthly Cost

Start by identifying the expenses you cannot reasonably stop or postpone when your income is lower.

  • Housing and essential household costs
  • Basic food
  • Necessary transportation
  • Essential utilities and communication
  • Required debt or other unavoidable payments

For example, if your normal monthly income is ₹20,000 but your essential expenses are ₹13,000, then ₹13,000 is much more important for your survival budget than your usual spending level.

A person earning $2,500 or £2,000 would use the same method: first identify the minimum cost of keeping essential needs covered, rather than copying someone else’s budget percentages.

Separate Fixed Costs From Expenses You Can Adjust

Not every expense has the same level of flexibility. When income falls, knowing which costs can actually be reduced is more useful than simply cutting everything by the same percentage.

Type of ExpenseUsually Harder to Change QuicklyOften More Flexible
HousingRent or essential housing paymentSome optional housing-related spending
FoodBasic groceriesTakeaways and non-essential purchases
TransportationNecessary travel to workOptional trips
SubscriptionsEssential communication servicesEntertainment subscriptions

This gives you a priority order. You are not trying to make every category smaller. You are protecting the expenses that keep your household functioning and adjusting the areas where you have genuine control.

What to Cut First When Your Paycheck Is Smaller

When a paycheck comes in lower than expected, make the adjustment based on priority rather than emotion.

For example, suppose your usual income is ₹20,000 but this month you receive only ₹15,000. If essential expenses remain around ₹12,000, you have only ₹3,000 available for everything else.

Monthly SituationIncomeEssential CostsAmount Left
Normal month₹20,000₹12,000₹8,000
Lower-income month₹15,000₹12,000₹3,000

The lesson is not to spend the extra ₹8,000 simply because it was available in the normal month. Your flexible spending has to respond when your income changes.

The same principle applies if income falls from $2,500 to $2,000 or from £2,000 to £1,600. The actual figures differ by country and household, but the budgeting decision is the same: protect essential costs first, then reduce flexible spending.

What to Do When the Budget Still Doesn’t Balance

Sometimes cutting flexible spending is not enough. If your essential expenses are already higher than your income, the problem is no longer simply about better budgeting.

At that point, look at the gap itself.

  • Check whether any payment can be moved to a more suitable date.
  • Look for temporary reductions in non-essential commitments.
  • Review recurring expenses that are no longer necessary.
  • Consider realistic ways to increase income if the shortfall continues.
  • Contact the relevant provider early if you are struggling with an important payment rather than waiting until it becomes overdue.

Do not treat every low-income month as a failure. A temporary income drop requires a different spending plan. If the gap continues for several months, however, it is a signal that the underlying income-versus-expense problem needs to be addresse provide practical information for managing income and expenses. UK readers can also use MoneyHelper’s budgeting guidance for country-specific budgeting information.

If you already have a broader article about dividing your salary, use it as a supporting internal link for the normal-income budgeting side. This section has a different purpose: it explains how to adapt when your income falls below normal.

A survival budget is not meant to be your permanent lifestyle. It is a practical fallback system that helps you protect essential expenses during a low-income period without pretending that every month will look the same.

Build a Small Buffer Between Your Paychecks

When you are living paycheck to paycheck, even a small unexpected expense can create a problem because most of your income is already committed before the next payday arrives.

The solution is not to suddenly save a large amount. A more realistic approach is to create a small buffer between paychecks and increase it gradually as your cash flow improves.

Why Every Paycheck Should Not Be Fully Spent

If your entire paycheck is allocated before the next one arrives, there is no room for a small surprise expense. A transport problem, higher grocery bill, or unexpected household purchase can force you to reduce something else or depend on borrowing.

For example, if you receive ₹20,000 and normally spend almost all of it before the next payday, try leaving a small amount untouched instead of treating the full balance as available spending money.

The same idea applies to someone earning $2,000 or £1,600. The amount of the buffer will depend on local costs and income, but the purpose is the same: create a little space between what you earn and what you immediately spend.

Start With a Buffer You Can Actually Keep

Your first target does not need to be a large emergency fund. If money is already tight, setting an unrealistic target can make the system impossible to maintain.

Start with an amount that would make one small unexpected expense easier to handle.

StageIllustrative BufferMain Purpose
Starting point₹300 / $5 / £5Creates the first small cushion
Small cushion₹1,000 / $25 / £20Handles minor unexpected costs
Several days of essentialsBased on your actual costsProvides more breathing room
Larger bufferBased on your income and expensesReduces pressure between paychecks

These are illustrative examples, not recommended savings targets for every country or household. Your starting point should match what you can realistically leave untouched.

Turn Leftover Money Into Next-Paycheck Protection

One useful habit is to stop treating every leftover amount as permission to spend more.

Suppose you planned to spend ₹2,000 during a week but actually spent ₹1,750. Instead of automatically using the remaining ₹250, you can leave it available for the next pay period.

Over time, several small amounts can create a useful cushion without requiring one large contribution from a low income.

If you want a separate collection of practical saving strategies, you can read how to save money fast in 30 days. That article covers broader saving techniques; this section is specifically about creating protection between paychecks.

How a Buffer Changes Your Next Paycheck

SituationWithout a BufferWith a Small Buffer
Small unexpected expenseMay reduce money available for essentialsCan be covered from the cushion
Lower-than-usual paycheckImmediate pressure on spendingPrevious buffer provides some breathing room
Money left at the end of the weekMay be spent automaticallyCan remain available for the next period
Next paydayStarts with little or no flexibilityStarts with some money already protected

The goal is not to make your bank balance look bigger. The goal is to make your next payday less fragile.

Increase the Buffer Gradually

Once your first small cushion becomes easy to maintain, increase it only when your budget can support the change.

  • Keep the first small amount untouched.
  • Add a little more when you genuinely have money left over.
  • Use part of the buffer only for situations that actually need it.
  • Rebuild the buffer after using it.
  • Increase the target when your income becomes more stable.

This creates a simple cycle:

Paycheck → essential spending → controlled flexible spending → small amount protected → next paycheck starts with a cushion.

If you are still struggling to keep any money aside despite earning a reasonable income, the problem may be different from simply needing a larger buffer. In that situation, why you can’t save money despite earning a good salary is a more relevant supporting guide.

When a Buffer Is Not Enough

A small buffer can help with timing problems and minor unexpected expenses, but it cannot solve a permanent gap between income and essential costs.

If your essential expenses are consistently higher than your reliable income, calculate the shortfall instead of simply trying to save more.

Essential expenses − reliable income = monthly shortfall

For example, if essential expenses are ₹16,000 and reliable income is ₹14,000, there is a ₹2,000 monthly gap. A buffer can temporarily reduce pressure, but the underlying gap still needs to be addressed.

For broader personal-finance fundamentals, you can also use this beginner’s personal finance guide to review the wider system without repeating those topics here.

For additional official guidance, the consumerfinance.gov/an-essential-guide-to-building-an-emergency-fund/?utm_source=chatgpt.com explain ways to approach saving and financial resilience. UK readers can also refer to MoneyHelper’s guidance on budgeting with irregular income when income varies from one period to another.

A buffer is not about becoming wealthy overnight. It is about creating a small gap between your income and your immediate spending so that one minor problem does not automatically become a next-paycheck problem.

Start small, protect the amount, rebuild it when you use it, and increase it only when your actual budget allows.

Handle a Shortfall Before It Becomes a Bigger Problem

Sometimes a low-income budget does not fail because of unnecessary spending. The real problem can be that your essential expenses are already close to, or higher than, your reliable income.

When that happens, the first step is not to cut random expenses. Find the exact size of the gap and determine whether it is temporary or happening repeatedly.

Calculate Your Exact Monthly Shortfall

Start with your reliable take-home income and subtract only the expenses you genuinely need to keep covered.

Reliable income − essential expenses = money available for everything else

For example, if your reliable income is ₹15,000 and essential expenses are ₹13,500, you have ₹1,500 available for flexible spending and other priorities.

But if essential expenses are ₹16,000, you already have a ₹1,000 shortfall before discretionary spending begins.

SituationIncomeEssential ExpensesResult
Expenses fit income₹15,000₹13,500₹1,500 remaining
Small shortfall₹15,000₹16,000₹1,000 gap
Larger shortfall₹15,000₹18,000₹3,000 gap

The same calculation works for other currencies. Someone earning $2,000 with $2,200 of essential expenses has a $200 gap. Someone earning £1,600 with £1,750 of essential expenses has a £150 gap.

Separate a Temporary Gap From a Recurring Problem

Not every shortfall requires the same response.

Temporary ShortfallRecurring Shortfall
Income was unusually low for one periodIncome is regularly below essential costs
An unusual expense caused the problemBasic monthly costs are structurally too high
Normal income may solve it next paydayThe underlying income-expense gap needs attention
Small adjustments may be enoughBoth expenses and income may need to change

This distinction matters because repeatedly using a credit card, borrowing money, or taking from your next paycheck can hide a recurring shortfall instead of solving it.

Decide What Can Be Delayed or Reduced

If the gap is temporary, review your expenses according to priority rather than cutting everything equally.

  • Protect: housing, basic food, necessary transportation, essential utilities, and required payments.
  • Reduce: flexible food spending, entertainment, shopping, and other non-essential categories.
  • Delay: purchases or goals that are useful but not urgent.
  • Review: recurring subscriptions and commitments that may no longer provide enough value.

The purpose is to create enough breathing room to get through the weaker income period without sacrificing expenses that keep your basic needs covered.

If the issue is connected to inconsistent income rather than a single low paycheck, your guide on budgeting with an irregular income is the more relevant supporting resource. It covers a different situation, so this section does not need to repeat that system.

When Cutting Expenses Is No Longer Enough

There is a point where reducing discretionary spending cannot solve the problem. If your essential expenses are already higher than your reliable income, the budget needs to address the gap itself.

For example, if your essential expenses are ₹18,000 and your reliable income is ₹15,000, cutting ₹500 of entertainment does not remove the entire ₹3,000 shortfall.

At that stage, consider both sides of the equation:

  • Can an essential cost be reduced or changed?
  • Can a payment date be adjusted where appropriate?
  • Is there a temporary expense that can be postponed?
  • Can reliable working hours or income be increased?
  • Is the shortfall temporary or likely to continue?

If debt payments are part of the problem, avoid treating new borrowing as income. A recurring gap financed by new debt can make future paychecks even harder to manage.

Know When Your Budget Needs a Structural Change

A budget is useful when it reflects reality. If your income repeatedly cannot cover your essential expenses, changing the spreadsheet without changing the underlying situation will not fix the problem.

Track the shortfall for several pay periods and look for a pattern. If the same gap keeps appearing, you have identified a structural problem rather than a one-time budgeting mistake.

For broader financial planning, you can refer to your financial planning guide for beginners. Keep this article focused on the paycheck-to-paycheck problem instead of repeating the full financial-planning framework.

official guidance on managing income and expenses. UK readers can use MoneyHelper’s budgeting guidance for additional country-specific information.

The key is to identify the problem early. A one-time ₹1,000, $100, or £100 shortfall can be handled differently from a gap that appears every month. Once you know which situation you have, you can choose the appropriate next step instead of repeatedly starting over on payday.

Create a Simple Weekly System That Keeps You Ahead of Payday

A budget only works when you can follow it after the planning is finished. If you are living paycheck to paycheck, you do not need to check your finances every hour. A short weekly routine can be enough to see what has been spent, what is still available, and what needs attention before the next payday.

The goal of this system is simple: make your money decisions before your balance becomes a problem.

Check Your Available Money Once a Week

Choose one fixed day each week to check your bank balance and recent spending. Sunday can work well, but the best day is the one you can repeat consistently.

Do not look only at your total balance. Separate the money that is already committed from the money you can actually use during the next few days.

  • Check your current balance.
  • Check essential payments due before the next review.
  • Check what you spent during the previous week.
  • Check how much flexible money remains.
  • Move any genuine leftover amount into your protected buffer when appropriate.

This five-minute check can reveal a problem while it is still small instead of waiting until the final days before payday.

Set a Spending Limit for the Next Seven Days

Once you know what money is already committed, give yourself a realistic limit for the coming week.

For example, if you have ₹2,800 available for flexible spending and four weeks remain in your planning period, you might initially work with a limit of around ₹700 per week. Your actual number should come from your own expenses rather than a fixed budgeting rule.

A US reader might work with a $150 weekly limit, while a UK reader might use £100. The currency does not matter as much as giving the remaining money a clear time period.

Weekly CheckQuestion to AskAction
BalanceHow much money is available?Record the amount
Upcoming billsWhat must be paid before next week?Protect that money
Recent spendingWhere did last week’s money go?Identify unusual spending
Flexible moneyHow much can I safely spend?Set the week’s limit
BufferDid any money genuinely remain?Keep it protected when possible

Check Upcoming Bills Before You Spend

A weekly spending limit is not enough if a large payment is due in the same week.

Before using your available balance, look at the next few days and check whether rent, utilities, transportation, insurance, debt payments, or another essential expense is approaching.

The Consumer Financial Protection Bureau’s bill-calendar guidance recommends putting income and bill dates together so you can see when money comes in and when payments leave your account. That cash-flow view is especially useful when the timing of your income creates pressure before payday. 1

This is different from simply asking, “How much money is in my bank account?” The better question is, “How much of that balance is actually available after the money I already need to protect?”

Adjust the Next Week Instead of Giving Up on the Budget

Suppose you planned to spend ₹700 during the week but ended up spending ₹900. Do not treat the entire monthly budget as failed.

First, identify why the extra ₹200 was spent. Was it a necessary expense, a one-time purchase, or something you could have avoided?

If the expense was genuinely necessary, adjust the following week’s flexible spending if your overall cash flow allows it. If it was avoidable, use the information to prevent the same pattern from repeating.

What HappenedBetter Response
Necessary expense was higherAdjust the next week’s flexible amount
One-time unexpected costUse the buffer if appropriate and rebuild it later
Repeated unnecessary spendingIdentify the category and reduce it
Essential costs exceed incomeRecalculate the shortfall instead of cutting random expenses

This makes the budget a feedback system rather than a punishment system.

Use a Simple Payday-to-Payday Checklist

At the beginning of each pay period, run through the same short checklist:

  • ☐ Confirm your actual take-home income.
  • ☐ Protect bills due before the next paycheck.
  • ☐ Set aside the amount needed for essential daily spending.
  • ☐ Decide your flexible spending limit.
  • ☐ Keep your existing buffer protected.
  • ☐ Check your finances once during each week.
  • ☐ Review what changed before the next payday.

If your income changes from one pay period to another, use the lower reliable income as the safer starting point rather than assuming your best paycheck will arrive every time.

For a broader system covering salary management across the month, your Day 1 to Day 30 salary management guide can support the reader after this article. This article has a narrower purpose: keeping a low-income paycheck under control between paydays. 2

Make the System Easier Every Payday

You do not need a complicated spreadsheet or a new financial rule every week. The system becomes useful when the same few decisions become automatic.

Each payday, protect essential money. Each week, check your actual spending. When income falls, reduce flexible spending before essential needs. When money remains, protect part of it instead of automatically spending it.

Over time, this changes the way you experience payday. Instead of starting every pay period wondering how long your money will last, you start with a clear picture of what is committed, what is available, and what needs to happen next.

That is the real purpose of a paycheck-to-paycheck budget: not perfection, but enough control to make the next payday less stressful than the last one.

Can you budget if you

Yes. When your income baseline is low, structural percentage allocations become even more critical to safeguard your primary needs and prevent cascading high-interest debt cycles.

What is the 70/20/10 rule for low income?

This alternate budgeting blueprint allocates 70% of total funds for essential living needs, 20% to clear debts or build savings, and exactly 10% for variable personal lifestyle choices.

How do I start an emergency fund on a tight budget

Begin by automating microscopic milestones. Setting aside just $5 or ₹500 immediately on Day 1 establishes consistent behavioral habits without fracturing your day-to-day liquidity.

What is the fastest way to break the paycheck cycle

The fastest way is shifting to physical cash tracking via the envelope system for variable costs and performing a immediate subscription audit to reclaim lost margins.

How to Divide Your Salary for Beginners: Complete Guide With Examples

How to divide your salary for beginners

introduction

Getting a salary every month feels good, but managing that money wisely can be challenging, especially when you are just starting to manage your finances. Bills, daily expenses, savings, debt, and personal spending can quickly compete for the same income.

Learning how to divide your salary for beginners can make this much easier. Instead of spending first and trying to save whatever is left, you can give each part of your income a clear purpose from the beginning.

In this guide, you’ll learn practical ways to divide your salary, how the 50/30/20 rule works, when other budgeting methods may be better, and how to adjust your plan based on your income and expenses. You’ll also see real salary examples and simple steps you can use every month.

The goal is not to follow a percentage blindly, but to build a salary plan that works in your real life.

How Should a Beginner Divide Their Salary?

Getting started with salary budgeting does not mean following one fixed percentage. A beginner should first understand how much money comes in, what must be paid, what should be saved, and how much can be used for personal spending.

A simple starting order is:

Take-home salary → Essential expenses → Savings → Debt and financial goals → Personal spending → Monthly review

Start With Your Take-Home Salary

Use the amount you actually receive in your bank account each month, not your gross salary. This gives you a realistic starting point for your monthly budget.

Separate Needs From Wants

Start by identifying essential expenses such as rent, food, utilities, transportation, insurance, and necessary family expenses. Then separate them from wants such as shopping, entertainment, eating out, and hobbies.

This helps you see where your salary is actually going before deciding how much you can spend or save.

Set Aside Savings Before Extra Spending

Instead of waiting until the end of the month to see what is left, decide on a savings amount in advance. This makes saving a planned part of your salary rather than something you do only when extra money remains.

You can divide this money between short-term goals, emergency savings, and other financial goals based on your situation.

Include Debt and Financial Goals

If you have debt, loan payments should be included in your monthly salary allocation. You may also need to set aside money for goals such as education, a major purchase, or long-term financial plans.

Your allocation should change when your priorities change.

Keep a Realistic Amount for Personal Spending

A good budget should still leave room for reasonable personal spending. Giving yourself a clear limit for wants can make your plan easier to follow without feeling unnecessarily restrictive.

Use Percentages as a Starting Point

Percentage-based budgeting can make salary allocation simpler for beginners. However, percentages are not strict rules. Your ideal allocation may be different because of your income, living costs, debt, family responsibilities, and financial goals.

For example, a person with high rent may need to spend more on essential expenses, while someone with lower fixed costs may be able to save more.

Example: Dividing a ₹30,000 Monthly Salary

A simple starting example could look like this:

CategoryPercentageAmount
Essential expenses50%₹15,000
Wants and personal spending30%₹9,000
Savings and financial goals20%₹6,000

This is only a starting example. If your essential expenses are higher, you can adjust the percentages instead of forcing your budget to fit a rule.

The 50/30/20 rule is one of the most popular ways beginners can structure their salary, so let’s look at how it works in detail.

What is the 50/30/20 rule for splitting your salary?

The 50/30/20 rule is a simple way to budget your take-home pay by splitting it into 50% for needs, 30% for wants, and 20% for savings or financial goals. The Consumer Financial Protection Bureau (CFPB) describes it as an easy method to help you organize your spending and saving.

If you’re just getting started with money management, this rule helps you give every rupee a job instead of spending first and saving whatever is left. If you’re new to this, our Personal Finance for Beginners guide covers the basics of budgeting and saving.

50% for Needs

Needs are the things you can’t really avoid in daily life, like:

  • Rent or housing
  • Groceries
  • Utilities
  • Transportation
  • Phone and internet
  • Insurance
  • Minimum debt payments

For a ₹30,000 salary, 50% comes to ₹15,000. If your actual essential expenses are lower, you can put the extra into savings or investments.

30% for Wants

Wants are the fun or optional things you spend on, like:

  • Eating out
  • Entertainment
  • Shopping
  • Subscriptions
  • Travel
  • Hobbies

For a ₹30,000 salary, 30% is ₹9,000. If you don’t use it all, you can move the leftover into savings or use it to pay off debt.

20% for Savings and Goals

This part is for your future and financial security, such as:

  • Emergency fund
  • Debt repayment
  • Investments
  • Retirement savings
  • Big planned purchases

For a ₹30,000 salary, 20% is ₹6,000. It’s usually a good idea to start with an emergency fund or high-interest debt first. The SEC’s Investor.gov also talks about why saving and investing regularly matters.

50/30/20 Salary Breakdown

Monthly SalaryNeeds (50%)Wants (30%)Savings (20%)
₹20,000₹10,000₹6,000₹4,000
₹30,000₹15,000₹9,000₹6,000
₹50,000₹25,000₹15,000₹10,000

These are just examples, not strict rules.

What If It Doesn’t Fit?

The 50/30/20 rule isn’t fixed—you can tweak it based on your situation. If your needs take up more of your income, you could try something like:

60% needs + 15% wants + 25% savings/debt repayment

You can adjust it as your income and expenses change. The main idea is just to give every rupee a clear purpose.

For a more detailed approach, check out our Financial Planning for Beginners guide.

How to Allocate Your Salary Based on Actual Expenses

The 50/30/20 rule is a good starting point, but your budget should really match your actual income and spending habits. Fixed percentages don’t always work well when rent, EMIs, and basic living costs vary a lot from person to person.

A better way is to build a salary plan based on what you actually spend.

Start With Your Take-Home Salary

Start with your net (in-hand) salary after taxes and deductions.

For example, if you earn ₹30,000 a month, use that amount for planning instead of your gross salary.

Identify Fixed Expenses

Fixed expenses are the things you pay every month, such as:

  • Rent
  • Loan EMIs
  • Insurance
  • Internet and mobile bills
  • Subscriptions

Adding these up helps you see how much of your income is already committed.

Assess Variable Expenses

Variable expenses change from month to month, such as:

  • Groceries
  • Transportation
  • Eating out
  • Shopping
  • Entertainment

Looking at your past spending can help you figure out a realistic average and spot where you might cut back if needed.

Distinguish Between Needs and Wants

Needs are the essentials like rent, food, and utilities.
Wants are things like dining out, shopping, and entertainment.

This makes it easier to see whether your lifestyle spending is affecting your savings.

Define Savings and Financial Goals

After covering expenses, decide how much you can put toward savings and goals like:

  • Emergency fund
  • Loan repayment
  • Investments
  • Retirement savings

For example, with a ₹30,000 salary:
₹16,000 needs + ₹6,000 wants = ₹8,000 savings

That comes out to roughly a 53% / 20% / 27% split, which is often more realistic than sticking to a fixed rule.

The main idea is to build a budget that actually fits your life and adjust it as your income or expenses change.

How to Create a Monthly Salary Budget That Actually Works

A good monthly salary budget is not about tracking every rupee perfectly. It is about knowing where your money should go before you start spending it.

Start With Your Take-Home Salary

Start with your take-home salary—the amount that actually reaches your bank account after taxes and other deductions.

For example, if you take home ₹30,000 per month, use ₹30,000 as the starting point for your budget instead of your gross salary.

Then list your regular expenses, such as:

  • Rent or housing
  • Groceries
  • Utilities and phone bills
  • Transportation
  • Loan EMIs
  • Subscriptions
  • Other regular spending

This gives you a clear picture of where your income is going.

If you are still learning the basics, our Personal Finance for Beginners guide can help you understand how budgeting fits into your overall financial plan.

Set Realistic Spending Limits

Once you know your regular expenses, set a realistic spending limit for each major category.

Instead of simply telling yourself to “spend less,” decide how much you can reasonably spend on groceries, eating out, shopping, entertainment, and other flexible expenses.

For example, you might set limits for:

  • Groceries: ₹4,000
  • Eating out: ₹1,500
  • Entertainment: ₹1,000
  • Shopping: ₹1,500

The exact numbers will depend on your income and lifestyle.

A good budget should feel manageable. If your limits are too strict, you may find it difficult to follow them consistently.

Prioritize Savings and Financial Goals

Do not wait until the end of the month to see whether you have money left to save.

Decide in advance how much you want to put toward important financial goals, such as:

  • Emergency savings
  • Debt repayment
  • Investments
  • Retirement
  • A planned purchase

If possible, move your planned savings soon after receiving your salary. This makes saving a regular habit instead of something you do only when extra money is available.

The Consumer Financial Protection Bureau (CFPB) recommends getting a clear picture of your income and spending, creating a realistic working budget, and updating it when your income or spending habits change.

Review What You Actually Spent

A monthly budget becomes more useful when you compare what you planned to spend with what you actually spent.

For example, suppose you planned to spend ₹4,000 on groceries but ended the month at ₹5,000.

Instead of simply calling it overspending, ask why it happened. Maybe prices increased, you made extra purchases, or you underestimated your normal grocery costs.

Then use that information to make next month’s budget more realistic.

Adjust Your Budget When Your Life Changes

Your salary budget should not remain fixed forever.

A salary increase, new EMI, higher rent, family responsibility, or change in daily expenses can affect how you should divide your money.

If your income increases, you do not necessarily need to increase your lifestyle spending by the same amount. You could direct part of the extra income toward savings, debt repayment, or long-term financial goals.

The same applies when your expenses increase. Instead of abandoning your budget, review your categories and adjust them based on your new situation.

The goal is not to create a perfect budget. It is to build a simple monthly spending plan that fits your real life, gives every rupee a purpose, and is realistic enough to follow consistently.

How Much Should You Save From Your Salary?

There is no single savings amount that works for everyone. The right amount depends on your income, essential expenses, debt, and financial goals.

The 20% in the 50/30/20 rule can be a useful starting point, but you do not have to force yourself to save exactly 20% if your current situation does not allow it.

Start With an Amount You Can Maintain

If you cannot save 20% of your salary right now, start with an amount you can consistently set aside.

For example, if you earn ₹25,000 and can comfortably save ₹2,500 each month, that is still a good starting point. As your income increases or your expenses decrease, you can gradually increase the amount.

The important part is to make saving a regular habit rather than waiting for a month when you have extra money.

Build an Emergency Fund First

Before focusing heavily on long-term goals, build money that can help you handle unexpected expenses.

An emergency fund can be useful for situations such as:

  • Unexpected medical or household expenses
  • Temporary loss of income
  • Urgent repairs
  • Other necessary costs you did not plan for

The Consumer Financial Protection Bureau (CFPB) explains that an emergency fund is money set aside for unplanned expenses and that even a small amount can provide some financial security.

Keep this money separate from your normal spending account so you are less likely to use it for everyday purchases.

Save for Short-Term and Long-Term Goals

Not every savings goal has the same time frame.

Short-term goals might include a planned purchase, travel, education, or an upcoming expense. Long-term goals may include retirement or building long-term wealth.

The U.S. Securities and Exchange Commission’s Investor.gov recommends defining your financial goals and considering your time horizon when deciding how to save or invest.

Giving each goal a purpose makes it easier to decide where your savings should go instead of treating all saved money as one large amount.

If you are building your broader financial plan, our Financial Planning for Beginners guide can help you connect saving with other financial priorities.

Increase Your Savings When Your Income Grows

You do not have to keep the same savings amount forever.

If you receive a raise, bonus, or additional income, consider directing part of the increase toward savings before increasing your lifestyle spending.

For example, if your salary rises from ₹30,000 to ₹35,000, you could increase your monthly savings by ₹2,000 and use the remaining increase for other priorities.

This allows your savings rate to grow without making your monthly budget feel dramatically tighter.

The goal is not to save the highest possible percentage of your salary. It is to build a savings habit that is realistic today and can grow with your income over time.

How to Divide Your Salary Between Bills, Spending, and Savings

Once you know your income and your financial priorities, the next step is to decide how much of your salary should go toward bills, everyday spending, savings, and other financial goals.

The exact percentages do not have to match the 50/30/20 rule. Your rent, debt, family responsibilities, and income may require a different balance.

Cover Essential Bills First

Start by separating the expenses you need to pay every month from the expenses you can control or reduce.

Essential expenses may include:

  • Rent or housing
  • Electricity, water, and other utilities
  • Groceries and basic food
  • Transportation
  • Insurance
  • Minimum debt or EMI payments

These expenses should come first because missing essential bills or debt payments can create bigger financial problems later.

If your essential expenses already consume more than 50% of your salary, do not force yourself to follow the 50/30/20 rule. Instead, look for areas where you can gradually reduce costs while keeping your basic needs covered.

The FDIC explains that budgeting can help you track income, expenses, and savings while making better decisions about needs and wants.

Set a Limit for Everyday Spending

After covering essential bills, decide how much you can reasonably spend on things that are not necessary for basic living.

This may include:

  • Eating out
  • Entertainment
  • Shopping
  • Hobbies
  • Subscriptions
  • Social activities

Giving these expenses a limit does not mean you have to remove all enjoyment from your budget. It simply prevents optional spending from taking money away from important financial goals.

For example, instead of spending whenever you feel like it, you might give yourself a fixed monthly amount for eating out and entertainment. Once that amount is used, you can wait until the next month.

Give Savings a Fixed Place in Your Salary

Savings should not depend entirely on whatever money is left after spending.

Choose an amount that you can realistically save every month and treat it as one of your regular financial commitments.

You can divide your savings between different goals, such as:

  • Emergency fund
  • Short-term purchases
  • Debt repayment
  • Investments
  • Retirement

If you are still building your overall financial plan, our Financial Planning for Beginners guide can help you connect your monthly budget with longer-term goals.

Use a Realistic Salary Example

Suppose your monthly take-home salary is ₹40,000.

You might create a starting allocation like this:

  • ₹20,000 for essential bills and needs
  • ₹5,000 for flexible spending
  • ₹15,000 for savings, debt repayment, and financial goals

That gives you a 50% / 12.5% / 37.5% split. It is very different from a strict 50/30/20 allocation, but it may work well if your lifestyle allows you to save more.

The numbers are only an example. Someone with higher rent or family responsibilities may need to allocate much more toward essential expenses.

Keep Your Salary Budget Flexible

Your salary allocation does not have to remain exactly the same every month.

You may have a higher electricity bill one month, a medical expense the next, or an unexpected repair. These changes are part of real life.

Instead of abandoning your budget when something unexpected happens, adjust your flexible spending first and protect your essential bills and important financial goals as much as possible.

As your income changes, review the whole allocation again. A salary increase can create an opportunity to increase savings, while a new EMI may require you to reduce discretionary spending.

The goal is not to divide your salary perfectly. It is to create a system where your bills are covered, your spending stays under control, and your money continues moving toward your financial goals.

How to Adjust Your Salary Budget When Your Income or Expenses Change

Your salary budget should not be treated as a fixed formula. Your income and expenses can change over time, so your budget should change with them.

A raise, new EMI, higher rent, unexpected expense, or change in your family responsibilities can all affect how much money you have available each month.

Review Your Budget After a Salary Increase

When your income increases, it can be tempting to immediately increase your lifestyle spending.

Instead, give the extra income a purpose before you start spending it. You could divide the increase between savings, debt repayment, investments, and a reasonable increase in your lifestyle spending.

For example, if your salary increases from ₹30,000 to ₹35,000, you do not have to spend the entire ₹5,000 increase. You might put ₹2,500 toward savings or investments and use the remaining ₹2,500 for other priorities.

This helps prevent lifestyle inflation, where spending rises every time your income rises.

Adjust When Your Expenses Increase

Sometimes your income stays the same while your expenses increase. Rent may go up, an EMI may start, or household costs may become more expensive.

When this happens, review your flexible spending before cutting important financial goals completely.

For example, you might temporarily reduce eating out, shopping, entertainment, or unused subscriptions to make room for a necessary increase in expenses.

Plan for Irregular Expenses

Not every expense arrives every month. Insurance renewals, repairs, annual subscriptions, travel, and other occasional costs can catch you off guard if you only budget for regular monthly bills.

A simple solution is to estimate these expenses in advance and set aside a small amount each month.

For example, if you expect an annual expense of ₹12,000, setting aside around ₹1,000 per month can make the eventual payment much easier to handle.

Review Your Budget Regularly

You do not need to rebuild your entire budget every week. A monthly review is usually enough for most people.

At the end of each month, check three things:

  • What did I actually spend?
  • Which category went over budget?
  • Did I save the amount I planned to save?

Use the answers to make small adjustments for the following month. If you are struggling to save despite having a reasonable income, our guide to why you can’t save money can help you identify common spending and saving problems.

Do Not Abandon Your Budget After One Bad Month

One expensive month does not mean your entire financial plan has failed.

Unexpected expenses happen. The important thing is to understand what caused the overspending and adjust your next month’s plan instead of giving up completely.

A useful salary budget is a flexible system that changes as your financial situation changes. The goal is to keep your spending under control while continuing to make progress toward your savings and financial goals.

Common Salary Budgeting Mistakes to Avoid

Even with a basic salary budget, it is easy to make mistakes that slowly affect your savings and financial progress. The problem is usually not the budgeting rule itself, but how the budget is used in real life.

1. Budgeting With Your Gross Salary

One common mistake is creating a budget using your gross salary instead of the amount you actually receive.

Your budget should start with your take-home salary because that is the money available for your monthly expenses, savings, and financial goals.

2. Saving Only What Is Left

If you spend first and plan to save whatever remains at the end of the month, there may be very little left.

A better approach is to decide your savings amount in advance and treat it as part of your monthly financial plan.

3. Following a Percentage Too Strictly

The 50/30/20 rule is a useful framework, but it is not a requirement that every person must follow exactly.

Someone paying high rent or supporting a family may need a different allocation. The goal is to create a budget that fits your actual circumstances rather than forcing your expenses into fixed percentages.

4. Ignoring Small and Irregular Expenses

Small purchases can look harmless individually but become significant when they happen repeatedly.

Subscriptions, frequent food deliveries, small online purchases, and convenience spending can quietly reduce the money available for savings.

Irregular expenses can cause another problem. Annual insurance payments, repairs, travel, or other occasional costs should be considered before they arrive.

5. Forgetting to Build an Emergency Fund

A budget that only covers normal monthly expenses can still leave you vulnerable when something unexpected happens.

Building an emergency fund gives you a separate pool of money for necessary unplanned expenses instead of forcing you to rely on credit or new debt.

6. Increasing Lifestyle Spending Too Quickly

When your salary increases, it is natural to want a better lifestyle. But increasing every expense at the same time can prevent your savings from growing.

Instead, consider putting part of every raise or bonus toward savings, investments, or debt repayment before increasing discretionary spending.

If you want to understand why income increases do not always lead to higher savings, our guide on why you can’t save money even with a good salary explores some common reasons.

7. Never Reviewing the Budget

A budget is not something you create once and forget about.

Your income, bills, priorities, and spending habits can change. Review your actual spending regularly and make small adjustments when necessary.

If you notice that a particular category repeatedly goes over budget, do not simply keep setting the same unrealistic limit. Find the reason and change the plan.

8. Giving Up After One Bad Month

Unexpected expenses can make one month look completely different from your original plan. That does not mean your entire budget has failed.

Look at what caused the difference, make the necessary adjustment, and start again the following month.

The best salary budget is not the one that looks perfect on paper. It is the one you can actually follow, review, and adjust as your financial life changes.

What is the 50/30/20 rule for salary?

The 50/30/20 rule suggests using 50% of your take-home income for needs, 30% for wants, and 20% for savings and financial goals. It is a flexible starting point rather than a strict rule.

How much of my salary should I save each month?

A 20% savings target can be a useful starting point if your budget allows it. If 20% is not realistic, start with an amount you can consistently save and increase it over time.

How should I budget a ₹30,000 monthly salary?

Start by calculating essential expenses such as rent, food, transportation, utilities, and EMIs. Then control flexible spending and allocate the remaining amount toward savings and financial goals.

Is the 50/30/20 rule realistic for a low salary?

Not always. If essential expenses consume most of your income, focus on covering your needs, controlling flexible expenses, and saving whatever amount you can consistently.

Conclusion: Build a Salary Budget That Fits Your Life

Dividing your salary is not about following one perfect formula. The 50/30/20 rule can give you a useful starting point, but your actual budget should reflect your income, essential expenses, debt, lifestyle, and financial goals.

Start with your take-home salary, cover your essential needs, set a realistic limit for flexible spending, and give your savings a clear place in your monthly plan. Then review your actual spending and adjust the budget whenever your income or expenses change.

Most importantly, do not worry if your numbers do not perfectly match a standard percentage. A simple budget that you can follow consistently, review regularly, and improve over time is more useful than a perfect-looking budget that does not work in real life.

Start with what you can manage today, and let your salary budget grow with your income and financial goals.

Post Summary
Learn how to divide your salary effectively with this beginner-friendly guide. Discover the 50/30/20 rule, practical salary allocation examples, savings strategies, budgeting tips, common mistakes, and simple ways to build a monthly budget that fits your real income and expenses.