Why Can’t I Save Money? 5 Hidden Reasons You’re Still Broke Even With a Good Salary

Person struggling to save money even with a good salary due to poor money habits and lifestyle inflation.

introduction

Have you ever wondered, **”Why can’t I save money even with a good salary?”** You are not alone. Many people earn a decent income but still struggle with **saving money, managing expenses, and building wealth**.The truth is, **a high salary does not guarantee financial freedom**. Your financial success depends on how well you manage, save, and grow your money. Hidden problems like **lifestyle inflation, emotional spending, poor budgeting, and bad money habits** can quietly stop you from achieving your financial goals.In this guide, we will uncover the **5 hidden reasons you’re still broke even with a good salary**, explain why these mistakes happen, and share practical strategies to improve your **personal finance habits** and build long-term wealth.

Why People With Good Salaries Still Struggle to Save Money

A good salary does not always mean financial success. Many people earn well but still struggle with saving money, managing expenses, and building wealth.

The reason is that earning money and managing money are two different skills. A higher income gives you more opportunities, but without smart money management habits, your salary can disappear quickly.

Many people focus only on increasing their income but ignore important things like spending control, saving habits, budgeting, and investing. This is why some people with high salaries still live paycheck to paycheck.

The truth is:

Income helps you earn money, but your financial habits decide whether you become wealthy.

Income Is Not the Same as Wealth

Your income is the money you earn every month, while wealth is the money and assets you build over time.

For example:

Person A:

  • Salary: ₹1,00,000/month
  • Expenses: ₹95,000/month
  • Savings: ₹5,000/month

Person B:

  • Salary: ₹50,000/month
  • Expenses: ₹35,000/month
  • Savings: ₹15,000/month

Even though Person A earns more, Person B is building wealth faster because of better saving habits and financial discipline.

This proves that salary alone cannot create wealth. Your spending decisions, saving rate, and investment choices decide your long-term financial future.

Now let’s understand the first hidden reason why many people can’t save money even with a good salary.

1. Lifestyle Inflation: The Silent Wealth Killer
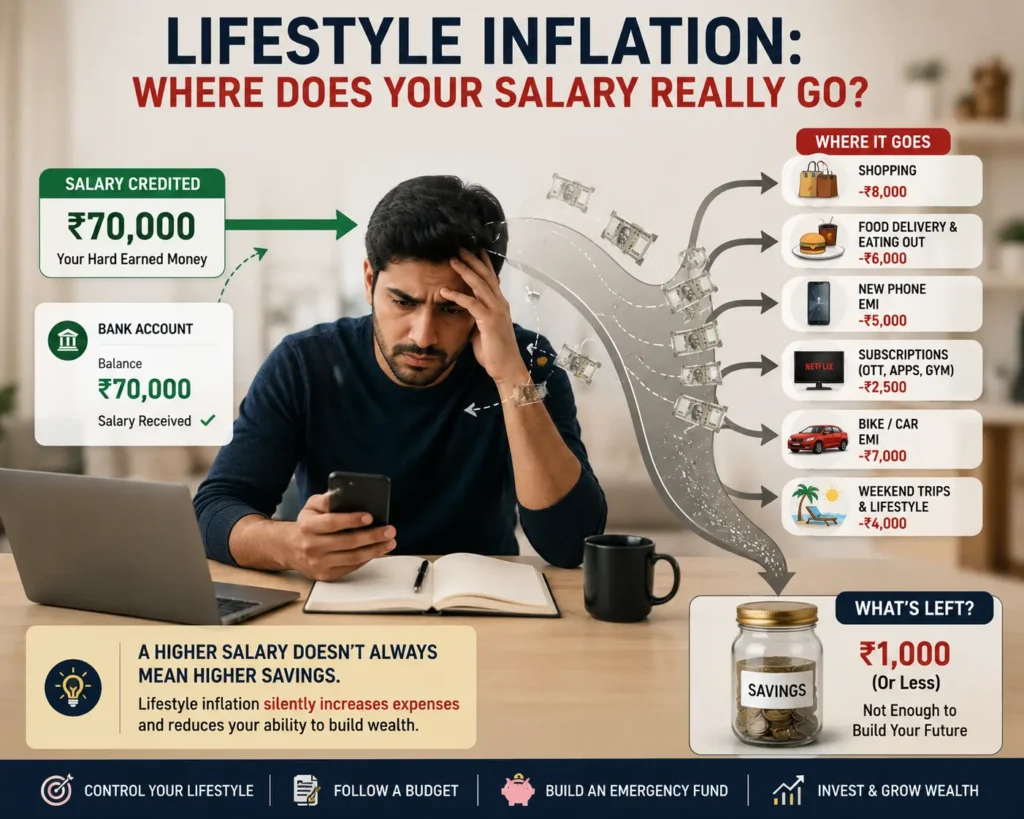
One of the biggest reasons why people can’t save money even with a good salary is lifestyle inflation. It is a hidden financial problem where your expenses increase as your income increases.

Many people think that earning more money will automatically solve their financial problems. But when their salary rises, they also start spending more on expensive things, bigger lifestyles, and unnecessary upgrades.

For example, someone earning ₹40,000 per month may manage their expenses carefully and save ₹5,000. After getting a salary increase to ₹70,000, instead of increasing savings, they may start spending more on:

  • Expensive smartphones
  • Frequent restaurant visits
  • Luxury shopping
  • Bigger EMIs
  • Unnecessary subscriptions
  • More online purchases

After some time, their income increases, but their savings remain almost the same.

This is the trap of lifestyle inflation.


What Is Lifestyle Inflation?

Lifestyle inflation means increasing your spending habits whenever your income increases.

A salary hike should improve your financial future, but many people use extra income only to improve their current lifestyle.

The cycle usually looks like this:

More Income → More Spending → Higher Expenses → Less Savings

Instead of:

More Income → More Savings → More Investments → More Wealth

The first cycle keeps people dependent on their salary, while the second cycle helps them build financial freedom.


Why Does Lifestyle Inflation Happen?

Lifestyle inflation is not only a money problem; it is also connected with human psychology.

When people earn more, they naturally want more comfort and better experiences. This is normal, but the problem starts when every income increase is converted into higher spending.

Some common psychological reasons are:

1. Social Comparison

People often compare their lifestyle with friends, colleagues, or social media influencers. They feel pressure to buy expensive things to appear successful.

2. Reward Mentality

After working hard, people feel they deserve to spend more money as a reward.

Example:

“I worked hard this month, so I should buy something expensive.”

Small rewards are fine, but frequent unnecessary spending can damage your financial goals.

3. Hedonic Adaptation

Humans quickly adapt to new comforts. Something that feels luxurious today becomes normal tomorrow, and then you want something even better.


Real-Life Example of Lifestyle Inflation

Imagine Rahul earns ₹60,000 per month.

His old lifestyle:

  • Rent: ₹15,000
  • Food: ₹10,000
  • Transport: ₹5,000
  • Other expenses: ₹20,000
  • Savings: ₹10,000

After a promotion, his salary increases to ₹90,000.

Instead of saving the extra ₹30,000, he:

  • Upgrades his phone
  • Starts expensive shopping
  • Takes a bigger loan
  • Eats out more often

Now his expenses increase to ₹80,000.

His salary increased, but his financial situation did not improve.

This is why many people with good salaries still struggle to save money.


How To Avoid Lifestyle Inflation

You don’t need to stop enjoying life. The goal is to create a balance between enjoying today and securing your future.

Follow these strategies:

1. Increase Savings Before Increasing Spending

Whenever your income increases, first increase your savings and investments.

Example:

Salary increase: ₹20,000

Better approach:

  • ₹10,000 → Investment
  • ₹5,000 → Savings
  • ₹5,000 → Lifestyle improvement

2. Maintain Your Old Lifestyle for Some Time

When you get a salary hike, avoid immediately upgrading everything.

Give yourself time to adjust and use the extra income to strengthen your financial foundation.


3. Focus on Buying Assets, Not Just Status Items

Many people spend money on things that show wealth but do not create wealth.

Instead of only buying expensive products, focus on:

  • Building an emergency fund
  • Investing regularly
  • Learning valuable skills
  • Creating additional income sources

Common Mistake Box

⚠️ Common Mistake:

“I earn more now, so I can afford more expenses.”

This mindset can keep you trapped forever. The goal of increasing income should not only be a better lifestyle but also a stronger financial future.


Pro Tip Box

💡 Pro Tip:

Whenever your salary increases, try to save at least 50% of the extra income. This simple habit can help you build wealth faster without feeling like you are sacrificing your lifestyle.


Key Takeaway

Lifestyle inflation is one of the biggest hidden reasons people remain broke despite earning a good salary.

Remember:

A higher income can make you comfortable, but controlled spending and smart investing can make you wealthy.

2. You Save Whatever Is Left Instead of Paying Yourself First

One of the most common reasons people struggle to save money even with a good salary is their saving strategy. Many people follow the habit of spending their entire income first and saving whatever remains at the end of the month.

The problem is that this approach makes savings optional. When savings become something you do “if money is left,” it often gets ignored because daily expenses, lifestyle choices, and unexpected costs always take priority.

A better approach is to make saving money a priority, not a leftover activity.

This financial principle is known as “Pay Yourself First”.

Instead of:

Income → Expenses → Savings

Follow:

Income → Savings → Expenses

This small change can completely transform the way you manage money.


What Does Paying Yourself First Mean?

Paying yourself first means saving or investing a fixed portion of your income immediately after receiving it, before spending on other things.

Think of savings as a bill that you must pay every month — just like rent, electricity, or other essential expenses.

For example:

Suppose your monthly salary is ₹60,000.

Traditional method:

  • Salary received: ₹60,000
  • Monthly expenses: ₹55,000
  • Savings: ₹5,000

Pay Yourself First method:

  • Salary received: ₹60,000
  • Savings and investments: ₹15,000
  • Remaining expenses: ₹45,000

The difference is not necessarily your income. The difference is your financial system and priorities.


Why Saving Whatever Is Left Usually Fails

Many people genuinely want to save money, but they fail because they depend only on discipline and motivation.

Human behavior makes this difficult.

When extra money is available in your bank account, your brain often treats it as money that can be spent.

This leads to:

  • Unplanned online shopping
  • Frequent dining out
  • Lifestyle upgrades
  • Unnecessary subscriptions
  • Impulse purchases

Over time, these small decisions silently reduce your ability to build savings.

According to behavioral finance principles, people often prefer immediate rewards over future benefits. Spending today feels more satisfying than saving for a goal that may happen years later.


The Psychology Behind Paying Yourself First

The biggest advantage of this method is that it removes decision-making from the process.

Every month, you don’t have to ask yourself:

“Should I save this month or spend this money?”

The decision is already made.

Automatic saving creates a system where your financial goals progress without depending on your mood, discipline, or motivation.

This is why successful investors and financially disciplined people focus more on creating systems rather than relying on willpower.


Real-Life Example: Same Salary, Different Results

Let’s compare two employees.

Employee A: Saves After Spending

Monthly income: ₹70,000

Expenses:

  • Rent: ₹20,000
  • Food: ₹12,000
  • Transport: ₹5,000
  • Shopping: ₹10,000
  • Entertainment: ₹8,000
  • Other expenses: ₹12,000

Total expenses: ₹67,000

Monthly savings: ₹3,000


Employee B: Saves Before Spending

Monthly income: ₹70,000

First step:

  • Investment and savings: ₹15,000

Remaining amount:

  • Expenses: ₹55,000

Monthly savings: ₹15,000

After one year:

Employee A saves:
₹36,000

Employee B saves:
₹1,80,000

Both earn the same salary. The difference is their money management habit.


How To Build a Pay Yourself First System

1. Automate Your Savings

The easiest way to develop a saving habit is automation.

Set automatic transfers on salary day for:

  • Emergency fund
  • Investments
  • Retirement savings
  • Future goals

Automation reduces the chance of spending money before saving.


2. Decide Your Saving Percentage

Don’t wait until you earn more money.

Start with a percentage that is realistic.

Example:

  • Beginner: Save 5–10% of income
  • Intermediate: Save 15–20%
  • Advanced: Save 30% or more

The most important thing is consistency.


3. Create Separate Money Accounts

Keeping all money in one account makes spending easier.

A simple system:

Income Account

  • Salary comes here

Savings Account

  • Emergency fund and short-term goals

Investment Account

  • Long-term wealth creation

This separation creates a psychological barrier against unnecessary spending.


Common Mistakes While Trying To Save Money

Mistake 1: Waiting for the Perfect Time

Many people say:

“I will start saving when my salary increases.”

But when income increases, expenses usually increase too.

The best time to start saving is now.


Mistake 2: Saving Without a Goal

Saving becomes difficult when you don’t know why you are saving.

Create clear goals:

  • Emergency fund
  • Buying a home
  • Education
  • Retirement
  • Financial freedom

A strong goal creates stronger motivation.


Mistake 3: Keeping Savings Too Easy to Access

If your saved money is sitting in your daily spending account, you may use it unnecessarily.

Create a system where your savings are protected from impulsive decisions.


Pro Tip

Treat savings as a payment to your future self.

Every rupee you save today gives your future more security, freedom, and opportunities.


Key Takeaway

The biggest mistake people make is trying to save money from what remains after spending.

The smarter approach is:

Save first. Spend second.

When you make saving automatic and prioritize your future goals, you can escape the paycheck-to-paycheck cycle and start building real financial stability.

3. Small Invisible Expenses Are Quietly Destroying Your Savings

Many people think they are unable to save money because of big expenses, but in reality, small and unnoticed expenses often create the biggest financial damage over time.

These small costs may look harmless individually, but when they happen repeatedly, they can consume a significant part of your income.

A coffee here, a food delivery there, unnecessary subscriptions, impulse shopping, and frequent online purchases may not feel expensive in the moment, but together they can become a major reason why you can’t save money even with a good salary.

This problem is known as invisible spending — money that leaves your account without creating real value for your financial future.


What Are Invisible Expenses?

Invisible expenses are small, regular payments that people often ignore because they don’t feel like major financial decisions.

Examples include:

  • Daily snacks and beverages
  • Food delivery charges
  • Unused app subscriptions
  • Small online purchases
  • Frequent cab rides
  • Impulse buying
  • Convenience fees

The problem is not one single expense. The problem is the repeated habit.

For example:

Spending ₹200 daily on unnecessary purchases may feel small.

But:

₹200 × 30 days = ₹6,000 per month

₹6,000 × 12 months = ₹72,000 per year

A small daily habit can quietly become a large yearly expense.


Why Small Expenses Are Difficult To Notice

Human psychology plays a major role in spending behavior.

People usually pay more attention to big financial decisions like buying a car, taking a loan, or purchasing expensive products.

But small expenses often escape attention because the brain considers them insignificant.

This is called the small purchase effect — where repeated low-cost decisions create a large financial impact over time.

A person may carefully compare prices before buying a phone but spend thousands every month on small unnecessary purchases without tracking them.


Real-Life Example: How Small Expenses Reduce Savings

Imagine Aman earns ₹50,000 per month.

His small expenses:

  • Coffee/snacks: ₹2,000
  • Food delivery: ₹3,000
  • Unused subscriptions: ₹1,000
  • Online impulse shopping: ₹4,000

Total unnecessary spending:

₹10,000 per month

Yearly impact:

₹1,20,000

If Aman invests this amount regularly instead of spending it, it could become a valuable long-term asset.

The issue is not that Aman earns less. The issue is that his money is leaking through small financial habits.


The Psychology Behind Impulse Spending

Modern businesses are designed to make spending easier.

Apps, advertisements, discounts, and one-click payments encourage quick decisions.

Common triggers include:

1. Discounts and Offers

People often buy things they don’t need because they feel they are saving money.

Example:

“I saved ₹500 because there was a discount.”

But actually, they spent money they never planned to spend.


2. Emotional Spending

Many people spend money when they feel:

  • Stressed
  • Bored
  • Sad
  • Tired

Shopping becomes a temporary source of happiness, but it can damage long-term financial goals.


3. Digital Payment Convenience

Digital payments make spending feel less painful because you don’t physically see money leaving your hands.

This is why tracking expenses becomes important.


How To Find Your Hidden Expenses

1. Track Every Expense for 30 Days

The first step to controlling money is understanding where it goes.

Write down:

  • Every purchase
  • Every subscription
  • Every small payment

After 30 days, you will clearly see your spending patterns.

You can also use budgeting methods explained by https://www.consumerfinance.gov/understand how tracking expenses helps in managing money.


2. Review Your Bank Statements

Your bank statement can reveal spending patterns you don’t notice daily.

Look for:

  • Repeated small payments
  • Forgotten subscriptions
  • Frequent unnecessary purchases

3. Use the 24-Hour Rule

Before buying something unnecessary, wait 24 hours.

Ask yourself:

  • Do I really need this?
  • Will this improve my life?
  • Is this helping my financial goals?

Many impulse purchases disappear after waiting.


Practical Ways To Reduce Invisible Spending

Cancel Unused Subscriptions

Review your monthly subscriptions and remove services you rarely use.

Create a Weekly Spending Limit

Instead of controlling every small purchase, create a weekly limit for flexible expenses.

Cook More Often

Reducing food delivery can save thousands every month.

Avoid Shopping When Emotional

Make purchasing decisions when you are calm, not when emotions are high.


Common Mistake Box

⚠️ Common Mistake:

“I only spend a small amount, so it doesn’t matter.”

This thinking is dangerous because wealth is not destroyed by one big mistake only. Repeated small mistakes can create long-term financial problems.


Pro Tip Box

💡 Pro Tip:

Review your expenses once every month and identify your top three unnecessary spending areas. Cutting even

4. You Don’t Have a Budget That Actually Works

One of the biggest reasons people can’t save money even with a good salary is not because they don’t earn enough—it’s because they don’t have a budgeting system that works in real life.

Many people think budgeting means restricting yourself or tracking every rupee you spend. As a result, they either avoid creating a budget or give up after a few weeks.

The truth is, a budget is not about limiting your life—it’s about giving every rupee a purpose. Without a clear plan, your salary disappears on bills, shopping, food delivery, entertainment, and impulse purchases before you even realize where the money went.


Why Most Budgets Fail

Creating a budget is easy. Following it consistently is the real challenge.

Most budgets fail because they are:

  • Too complicated
  • Unrealistic
  • Difficult to maintain
  • Based on guesswork instead of actual spending

For example, someone earning ₹60,000 may decide to spend only ₹2,000 on entertainment without checking their past spending habits. Within a week, they exceed the limit and feel frustrated.

A budget should match your lifestyle—not someone else’s.


What Happens When You Don’t Budget?

Without a budget, it’s easy to lose control of your finances.

Common problems include:

  • Spending more than planned
  • Forgetting monthly bills
  • Depending on credit cards
  • Having no emergency savings
  • Living paycheck to paycheck
  • Feeling stressed about money every month

Over time, these habits make it difficult to build wealth, no matter how much you earn.


A Simple Example

Imagine Priya earns ₹70,000 per month.

Since she doesn’t follow a budget:

  • Rent: ₹18,000
  • Food & Dining: ₹14,000
  • Shopping: ₹12,000
  • Entertainment: ₹8,000
  • Online subscriptions: ₹3,000
  • Miscellaneous expenses: ₹12,000

At the end of the month, she has almost nothing left to save.

Now imagine she creates a realistic budget.

She identifies unnecessary expenses, reduces impulse purchases, and automatically saves ₹12,000 every month.

Her income didn’t change—only her financial plan did.


How to Create a Budget That Works

1. Track Your Income and Expenses

Before creating a budget, understand exactly where your money goes.

Record:

  • Salary
  • Fixed expenses
  • Variable expenses
  • Savings
  • Investments

The Consumer Financial Protection Bureau provides practical guidance on creating and managing a budget. Learn more from the official resource:
Consumer Financial Protection Bureau – Budgeting Tools
https://www.consumerfinance.gov/consumer-tools/budgeting/


2. Use the 50/30/20 Budget Rule

One of the easiest budgeting methods is the 50/30/20 Rule.

  • 50% → Needs (Rent, food, bills)
  • 30% → Wants (Entertainment, shopping)
  • 20% → Savings and investments

This rule helps create a healthy balance between enjoying life today and preparing for the future.


3. Review Your Budget Every Month

A budget is not something you create once and forget.

Every month, ask yourself:

  • Did I overspend?
  • Which expenses were unnecessary?
  • Can I increase my savings next month?
  • Am I getting closer to my financial goals?

Small monthly improvements can create significant long-term results.


Common Budgeting Mistakes

Avoid these common mistakes:

  • Creating an unrealistic budget
  • Ignoring small daily expenses
  • Forgetting annual or unexpected costs
  • Not reviewing your budget regularly
  • Saving only if money is left

Pro Tip

💡 Pay yourself first.

As soon as your salary is credited, transfer a fixed amount to your savings or investment account. Whatever remains is your spending budget.

This simple habit makes saving automatic and reduces unnecessary spending.


Key Takeaway

A budget is one of the most powerful personal finance tools you can use.

Without a budget, your money controls you.

With a budget, you control your money.

Remember:

You don’t need a bigger salary to save more money. You need a better plan for the salary you already earn.

5. Emotional Spending Is Secretly Emptying Your Wallet

Have you ever bought something you didn’t really need just because you were stressed, bored, sad, or excited?

If your answer is yes, you’re not alone.

Emotional spending is one of the biggest hidden reasons why many people can’t save money even with a good salary. Instead of making logical financial decisions, people often let their emotions control how they spend money.

The problem is that emotional purchases provide only temporary happiness, while the financial consequences can last for months or even years.


What Is Emotional Spending?

Emotional spending is the habit of buying products or services based on your feelings rather than your actual needs.

People often spend money to:

  • Reduce stress
  • Celebrate achievements
  • Feel better after a bad day
  • Escape boredom
  • Impress others
  • Reward themselves

Although these purchases may feel satisfying in the moment, they rarely provide long-term happiness.


Why Does Emotional Spending Happen?

Human emotions strongly influence financial decisions.

When you feel stressed or emotionally overwhelmed, your brain looks for something that provides instant pleasure.

Shopping, ordering food, or buying something online temporarily increases dopamine—the brain chemical associated with pleasure and reward.

However, this feeling usually disappears quickly, leading many people to repeat the same spending behavior again.


Common Emotional Spending Triggers

You may be spending emotionally without even realizing it.

Some of the most common triggers include:

Stress

After a difficult day at work, many people reward themselves with unnecessary shopping or expensive food.

Boredom

Scrolling through shopping apps without needing anything often results in impulse purchases.

Happiness

Many people celebrate promotions, bonuses, or achievements by buying expensive items they never planned to purchase.

Social Pressure

Seeing friends or influencers buy luxury products can create the feeling that you also need those things.


Real-Life Example

Imagine Neha earns ₹75,000 per month.

Whenever she feels stressed after work, she orders food online and shops during weekend sales.

Monthly emotional spending:

  • Food delivery: ₹4,000
  • Online shopping: ₹6,000
  • Beauty products: ₹3,000

Total:

₹13,000 every month

Yearly emotional spending:

₹1,56,000

Instead of investing this money, it quietly disappears through emotional decisions.


How To Stop Emotional Spending

1. Identify Your Spending Triggers

Ask yourself before every non-essential purchase:

  • Am I buying this because I need it?
  • Or because I’m feeling emotional?

Simply recognizing the trigger can prevent unnecessary spending.


2. Follow the 24-Hour Rule

Before buying anything expensive, wait at least 24 hours.

Most impulse purchases lose their appeal after a short waiting period.


3. Find Healthier Alternatives

Instead of shopping to improve your mood, try:

  • Going for a walk
  • Reading a book
  • Exercising
  • Talking to a friend
  • Listening to music

These activities improve your mood without affecting your finances.


4. Set a Monthly Fun Budget

You don’t need to stop enjoying life.

Instead, allocate a fixed amount every month for entertainment and personal rewards.

This allows you to enjoy spending without damaging your financial goals.


Expert Resource

Learning how emotions influence money decisions is an important part of behavioral economics.

To understand this concept better, explore the educational resources from the Behavioral Insights Team:

Behavioral Insights Team
https://www.bi.team/


Common Mistake Box

⚠️ Common Mistake

Many people believe:

“I’m only spending a little to feel better.”

The problem is that small emotional purchases repeated every week can quietly cost thousands every year.


Pro Tip

💡 Before completing any online purchase, ask yourself one simple question:

“Will this purchase still matter to me one month from now?”

If the answer is No, consider saving or investing that money instead.


Key Takeaway

Emotional spending doesn’t just reduce your bank balance—it also delays your financial goals.

Learning to separate emotions from financial decisions is one of the most powerful habits you can develop if you want to save more money, build wealth, and achieve long-term financial freedoml etest post10 Best AI Tools to Manage Your Personal Finances in 2026: The Ultimate Guide

### Frequently Asked Question #1**Q. Why can’t I save money even with a good salary?**

**Answer:**Many people **can’t save money even with a good salary** because of **lifestyle inflation, emotional spending, poor budgeting, unnecessary expenses, and weak money management habits**. In most cases, the problem isn’t how much you earn—it’s how you manage, save, and invest your income.

### Frequently Asked Question #2**Q. What is the best way to start saving money?**

**Answer:**The best way to start saving is to **pay yourself first**. As soon as you receive your salary, transfer a fixed percentage to your savings or investment account. Automating your savings and following a realistic budget can help you build wealth consistently.

### Frequently Asked Question #3**Q. How much of my salary should I save every month?**

**Answer:**A good goal is to save **at least 20% of your monthly income**. If that isn’t possible, start with **5–10%** and gradually increase your savings as your income grows. The key is consistency, not perfection.

Conclusion

If you’ve ever asked yourself, “Why can’t I save money even with a good salary?”, the answer is now clear. The biggest obstacles to saving money are often not your income but your financial habits, spending behavior, and money management system.

From lifestyle inflation and saving whatever is left to invisible expenses, poor budgeting, and emotional spending, these hidden mistakes can quietly prevent you from building wealth. The good news is that every one of these habits can be changed with consistent effort and a clear financial plan.

Start with one simple step today: pay yourself first, track your expenses, create a realistic budget, and review your finances every month. Small improvements made consistently can lead to significant financial growth over time.

Remember, financial freedom is not determined by how much you earn—it is determined by how much you save, invest, and grow. The decisions you make today will shape your financial future tomorrow.

Now it’s your turn. Which of these hidden reasons is stopping you from saving money? Share your thoughts or experiences in the comments, and don’t forget to share this guide with someone who wants to take control of their finances.

10 Best AI Tools to Manage Your Personal Finances in 2026: The Ultimate Guide

Alt Text: 10 Best AI Tools to Manage Your Personal Finances in 2026 infographic showing AI budgeting, expense tracking, financial planning, and money management apps.

introduction

10 Best AI Tools for Personal Finance Managing your finances has never been more important—or more challenging. With the rapid advancement of artificial intelligence, managing your money is no longer limited to spreadsheets or traditional budgeting apps. The 10 Best AI Tools to Manage Your Personal Finances in 2026 can help you automate budgeting, track expenses, monitor subscriptions, build better saving habits, and make smarter financial decisions with personalized insights. Whether you’re a student, a working professional, a freelancer, or simply looking to take control of your finances, choosing the right AI tool can save you time, reduce financial stress, and improve the way you manage your money. In this comprehensive guide, we’ll compare the top AI-powered personal finance tools based on their features, pricing, ease of use, security, and overall value, helping you confidently choose the best solution for your financial goals.

1.What Are AI Tools for Personal Finance?

Managing money is no longer just about tracking your income and expenses—it’s about making smarter financial decisions every day. AI tools for personal finance use artificial intelligence to analyze your financial habits, automate repetitive tasks, identify spending patterns, and provide personalized recommendations that help you budget better, save more, and achieve your financial goals faster. Unlike traditional budgeting apps that simply record transactions, AI-powered tools learn from your financial behavior over time and generate actionable insights based on your unique spending habits.

Why Are AI Tools Changing Personal Finance?

The biggest advantage of AI is that it transforms financial data into meaningful insights. Instead of manually reviewing hundreds of transactions each month, AI automatically categorizes expenses, tracks recurring subscriptions, predicts upcoming bills, monitors cash flow, and identifies areas where you may be overspending. This allows users to focus less on manual calculations and more on making informed financial decisions.

Example: How AI Improves Money Management

Imagine your monthly income is $3,500.

CategoryAmount
Housing$1,200
Groceries$450
Transportation$300
Entertainment$350
Subscriptions$90
Savings$700
Other Expenses$410

Instead of simply displaying these numbers, an AI finance tool can analyze your spending habits and provide useful insights, such as identifying recurring subscriptions, highlighting categories that account for a large share of your monthly spending, or helping you understand how changes to your budget could affect your savings goals. The exact recommendations depend on the tool you use and your financial data.

Key Benefits of AI Personal Finance Tools
  • Automated Budgeting: Create smarter monthly budgets based on your spending history.
  • Expense Tracking: Automatically organize transactions into categories without manual work.
  • Cash Flow Forecasting: Estimate future income and expenses to help you prepare ahead.
  • Goal-Based Saving: Monitor progress toward financial goals with personalized suggestions.
  • Spending Analysis: Understand where your money goes and identify opportunities to improve your budget.

As AI continues to evolve, these tools are becoming valuable assistants for anyone who wants to spend less time managing money manually and more time making informed financial decisions. However, AI should support your financial planning—not replace your own judgment or professional advice when making major financial decisions.letest postGlobal Index Funds vs S&P 500: The Smarter Choice for Beginner Investors in 2026

2.How Do AI Tools for Personal Finance Work?

Understanding how AI Tools for Personal Finance work is the first step toward making smarter financial decisions. Unlike traditional budgeting apps that only record your transactions, AI-powered finance tools analyze your financial behavior, identify spending patterns, and generate personalized insights that help you budget better, save more, and improve your overall financial health. Whether you’re exploring AI Money Management or searching for the Best AI Finance Apps, understanding the technology behind these tools will help you choose the right solution for your needs.

From Financial Data to Smart Decisions

Every time you earn income, pay a bill, buy groceries, or use a credit card, you create financial data. AI collects the information you choose to provide, organizes it into meaningful categories, and transforms thousands of transactions into easy-to-understand insights. This is why AI Expense Tracking is far more efficient than manually reviewing bank statements or spreadsheets.

A Practical Budget Analysis Example

Imagine your monthly income is $4,500.

CategoryAmount
Income$4,500
Essential Expenses$2,700
Lifestyle Spending$1,000
Savings$800

Instead of simply displaying these numbers, an AI finance tool analyzes your spending habits and highlights where your money is being used. In this example, your lifestyle spending represents 22.2% of your income ($1,000 ÷ $4,500 × 100). If your financial goal is to save more, the AI may encourage you to review discretionary expenses while helping you build a more balanced budget through AI Budgeting Tools.

Why This Process Matters

AI doesn’t make financial decisions for you—it helps you make better ones. Whether your goal is AI Financial Planning, learning How to Create a Monthly Budget, or discovering the Best Free AI Tools for Personal Finance, AI transforms complex financial information into practical recommendations. By combining automation with personalized insights, these tools can help you spend less time managing money and more time achieving your financial goals.

3.How We Selected the Best AI Tools for Personal Finance

Not every AI finance app deserves a place on this list. Some tools focus on automation, while others specialize in budgeting, expense tracking, or financial planning. To ensure this guide is useful, every recommendation was evaluated using practical criteria that matter to real users—not just marketing claims. Whether you’re searching for the Best AI Finance Apps, AI Budgeting Tools, or a reliable AI Financial Assistant, understanding these selection standards will help you make a smarter choice.

Our Evaluation Criteria

Instead of ranking tools based on popularity alone, we focused on the features that directly affect your personal finance experience.

AI Capabilities

A quality AI finance tool should do more than display transactions. It should analyze spending patterns, identify recurring expenses, provide personalized insights, and support better AI Money Management through intelligent recommendations.

Budgeting & Expense Tracking

We evaluated how effectively each platform handles AI Expense Tracking, automatic transaction categorization, monthly budgeting, subscription monitoring, and spending analysis. A useful tool should reduce manual work while giving you a clear view of your financial habits.

Security, Privacy & Data Protection

Financial information is sensitive, so security was one of our highest priorities. We considered encryption, account protection, authentication features, privacy policies, and how responsibly each platform handles user data. A powerful AI tool should never compromise your financial privacy.

Ease of Use & Overall Value

Even the most advanced technology has little value if it’s difficult to use. We looked at interface design, setup process, learning curve, pricing, and the overall value each tool provides. Whether you’re new to AI Financial Planning or already using Best Free AI Tools for Personal Finance, the right platform should be easy to understand and practical for everyday use.

Why These Criteria Matter

Choosing the wrong AI finance tool can waste both time and money. By evaluating every platform using consistent criteria, you can compare features more confidently and select a solution that matches your financial goals instead of relying on advertising or popularity alone.

4.Quick Comparison of the Best AI Tools for Personal Finance

Choosing the right AI Tools for Personal Finance isn’t about finding the tool with the most features—it’s about finding the one that fits your financial goals. Some platforms are designed for budgeting, while others focus on expense tracking, financial planning, or AI-powered insights. Before exploring each tool in detail, this quick comparison will help you understand which type of solution may be the best fit for your needs.

Compare the Most Important Features

When comparing Best AI Finance Apps, don’t focus only on price. Evaluate each platform based on the features that will have the biggest impact on your daily money management.

FeatureWhy It Matters
AI BudgetingHelps create and adjust realistic monthly budgets.
Expense TrackingAutomatically organizes transactions into categories.
Financial InsightsIdentifies spending trends and opportunities to save.
Goal TrackingMonitors progress toward savings and financial goals.
SecurityProtects sensitive financial information.
PricingHelps determine whether the features justify the cost.

Which Tool Is Right for You?

For Beginners

If you’re new to AI-powered finance, prioritize tools with a simple interface, automatic setup, and clear budgeting recommendations. Exploring AI Budgeting Tools or How to Create a Monthly Budget is a good starting point before choosing advanced features.

For Better Money Management

If your goal is reducing unnecessary expenses and building healthier financial habits, look for platforms that offer AI Expense Tracking, AI Money Management, and personalized spending insights instead of basic transaction lists.

For Long-Term Financial Planning

If you’re focused on saving, investing, or achieving long-term goals, choose tools that support AI Financial Planning, Financial Goal Planning, and detailed cash flow analysis. These features can help you make more informed decisions as your financial needs grow.

Key Takeaway

The best AI finance tool isn’t necessarily the most expensive or the most popular. It’s the one that solves your biggest financial challenge, fits your budget, protects your data, and supports your long-term financial goals. Use this comparison as a starting point before reading the detailed reviews of each tool in the next section.letest post read 10 Best Financial Habits Every College Student Should Develop (2026)

5.How to Choose the Right AI Tools for Personal Finance

Choosing the best AI Tools for Personal Finance isn’t about selecting the app with the most features—it’s about finding the one that fits your financial goals, budget, and daily needs. A tool that works well for a student may not be the best choice for an investor or a freelancer. Before exploring the Best AI Finance Apps, it’s important to understand which features truly matter.

Identify Your Financial Goals

Start by asking yourself what problem you want AI to solve. Do you need better AI Budgeting Tools, accurate AI Expense Tracking, smarter AI Financial Planning, or an intelligent AI Financial Assistant that helps you manage money more efficiently? Choosing a tool based on your primary goal will save both time and money.

Questions to Ask Before Choosing

  • Does the tool fit my monthly budget?
  • Does it support my financial goals?
  • Is my financial data protected?
  • Is the interface easy to use?
  • Does it provide practical insights instead of just charts?

Compare Features Before You Decide

Don’t choose an AI tool based only on popularity. Compare budgeting, expense tracking, cash-flow forecasting, goal tracking, security, integrations, pricing, and ease of use. If your priority is AI Money Management, How to Create a Monthly Budget, Financial Goal Planning, or How to Save Money with AI, the right combination of features matters far more than the number of downloads.

Why Choosing the Right Tool Matters

The best AI finance tool is the one you’ll actually use consistently. A platform that matches your needs can help simplify budgeting, improve financial discipline, and support better long-term decisions. Once you know what to look for, comparing the top 10 AI tools becomes much easier and more meaningful.

6.Top 10 AI Tools for Personal Finance at a Glance

Before reading the detailed reviews, here’s a quick overview of the Best AI Finance Apps featured in this guide. Every tool has different strengths—some are designed for AI Budgeting Tools, while others excel in AI Expense Tracking, AI Financial Planning, or investment research. This summary helps you quickly identify which platform best matches your financial needs before diving into the full reviews.

Quick Comparison

AI ToolBest ForFree PlanIdeal User
ChatGPTAI Money Management✅Beginners & Professionals
ClaudeFinancial Research✅Students & Writers
Perplexity AIInvestment Research✅Investors
CleoBudgeting✅Beginners
Monarch MoneyFamily Budgeting❌Families
Copilot MoneyExpense Tracking❌iPhone Users
Rocket MoneySubscription Management✅Everyday Users
YNABBudget Planning❌Budget-Focused Users
OriginWealth Management❌Professionals
Quicken SimplifiComplete Personal Finance❌Advanced Users

How to Use This Comparison

Don’t choose a tool simply because it’s ranked first. Instead, compare each platform based on your financial goals. If you want better AI Budgeting Tools, focus on budgeting features. If your priority is AI Expense Tracking, compare automation and reporting capabilities. For long-term AI Financial Planning, consider goal tracking, forecasting, and financial insights rather than popularity alone.

Continue Reading

The following sections provide a detailed review of every tool, including its features, pricing, advantages, limitations, security, and overall value. If you’re looking for Best Free AI Tools for Personal Finance, How to Create a Monthly Budget, Financial Goal Planning, or How to Save Money with AI, each review will help you choose the right solution with confidence.

7.ChatGPT – Best AI Assistant for Personal Finance

Among all the AI Tools for Personal Finance, ChatGPT stands out because it helps users understand their finances instead of simply displaying numbers. From creating a monthly budget to explaining financial concepts and building personalized saving plans, ChatGPT acts as an intelligent financial assistant that supports better money decisions. Whether you’re exploring AI Budgeting Tools, AI Expense Tracking, or AI Financial Planning, ChatGPT can simplify complex financial tasks through natural conversations.

Why Choose ChatGPT?

Unlike many traditional finance apps, ChatGPT can answer questions, explain financial strategies, create personalized budgets, compare financial products, and help organize financial information based on your goals. If you’re learning How to Create a Monthly Budget, improving AI Money Management, or looking for the Best AI Finance Apps, ChatGPT offers flexibility that goes beyond standard budgeting software.

Key Features

  • Personalized budget creation
  • Financial education in simple language
  • Savings and debt repayment planning
  • Spending analysis using your provided data
  • Goal-based financial guidance
  • Easy-to-understand financial explanations

Real-World Example

Suppose your monthly income is $5,000, your total expenses are $3,900, and your savings target is $1,200.

Current Savings Capacity:

$5,000 − $3,900 = $1,100

You’re $100 short of your monthly savings goal. ChatGPT can help you review your budget, identify discretionary spending, and suggest practical adjustments to support Financial Goal Planning and How to Save Money with AI.

Who Should Use ChatGPT?

ChatGPT is ideal for students, professionals, freelancers, and anyone who wants practical guidance for AI Money Management, Best Free AI Tools for Personal Finance, and smarter everyday financial decisions without needing advanced financial knowledge.

8.Claude – Best AI Tool for Financial Research and Decision Support

If your goal is to understand financial topics in greater depth rather than simply track expenses, Claude is a strong choice. Among today’s Best AI Finance Apps, Claude excels at breaking down complex financial concepts, comparing investment ideas, summarizing reports, and helping users make informed decisions. It workClaudehttps://s particularly well alongside AI Financial Planning and AI Money Management by turning complicated information into clear, structured explanations.

Why Choose Claude?

Claude is designed for thoughtful analysis instead of quick answers alone. Whether you’re researching investment strategies, comparing financial products, or creating a long-term budget, it can organize large amounts of information into practical insights. If you’re interested in How to Create a Monthly Budget, Financial Goal Planning, or improving your financial knowledge, Claude can help simplify the learning process.

Key Features

  • Deep financial research assistance
  • Long-document analysis
  • Budget planning support
  • Investment comparison
  • Financial report summaries
  • Personalized financial explanations
  • Goal-based planning assistance

Practical Example

Suppose you’re comparing two investment options.

InvestmentExpected Annual ReturnRisk Level
Fund A8%Medium
Fund B11%High

Instead of recommending one option outright, Claude can help you compare the trade-offs, explain how risk and return relate, and organize the information into an easy-to-understand comparison. It supports better AI Financial Planning by helping you evaluate choices rather than making decisions for you.

Pros

  • Excellent for financial learning and research
  • Easy-to-understand explanations
  • Strong document analysis
  • Helpful for comparing financial options

Cons

  • Not a banking or budgeting application
  • Does not automatically connect to financial accounts

Best For

Students, investors, bloggers, researchers, and professionals looking to improve AI Money Management, explore Best Free AI Tools for Personal Finance, strengthen AI Budgeting Tools, and make better-informed financial decisions through deeper analysis.

9.Perplexity AI – Best AI Tool for Real-Time Financial Research

When you need up-to-date financial information, perplexity.ai/can be a useful research assistant. Unlike traditional budgeting apps, it helps you find and summarize current information from multiple sources, making it valuable for learning about markets, financial products, and personal finance topics. If you’re exploring Best AI Finance Apps, improving AI Financial Planning, or researching smarter money strategies, Perplexity AI can help you gather information more efficiently.

Why Choose Perplexity AI?

Perplexity AI is designed for research rather than budgeting. It can help you compare financial products, understand investment concepts, summarize articles, and answer finance-related questions with source-backed information. If you’re learning How to Create a Monthly Budget, researching AI Money Management, or comparing different financial options, it can save significant research time.

Key Features

  • Real-time financial research
  • Source-backed answers
  • Investment and market summaries
  • Product comparisons
  • Financial learning support
  • Fast information discovery
  • Easy-to-read explanations

Practical Example

Imagine you’re comparing two savings accounts.

OptionInterest RateAnnual Interest on $10,000*
Account A3.5%$350
Account B4.2%$420

*Illustrative calculation before taxes, fees, or compounding differences.

Instead of manually searching dozens of websites, Perplexity AI can help you collect relevant information, compare key features, and understand the differences more quickly. You should always verify important financial details with the official provider before making a decision.

Pros

  • Fast research with cited sources
  • Excellent for financial learning
  • Easy product comparisons
  • Simple and beginner-friendly interface

Cons

  • Not a budgeting application
  • Does not manage bank accounts or investments directly

Best For

Students, investors, bloggers, researchers, and anyone looking to strengthen AI Financial Planning, //investor.gov/ explore AI Expense Tracking solutions, discover Best Free AI Tools for Personal Finance, and make more informed financial decisions through efficient research.

Final Verdict: Which AI Tool for Personal Finance Should You Choose?

After comparing the 10 Best AI Tools to Manage Your Personal Finances in 2026, the right choice ultimately depends on your financial goals, experience level, and the features you value most. There isn’t a single tool that’s perfect for everyone. Some excel at budgeting, others at financial research, while a few are designed for long-term money management and planning.

Our Top Recommendations

If you’re looking for an all-around AI assistant for budgeting, financial education, and planning, ChatGPT is an excellent choice. For deeper document analysis and financial research, Claude offers strong reasoning capabilities. If your priority is real-time financial research with source-backed answers, Perplexity AI is one of the best options available.

Which Tool Matches Your Goal?

Final Thoughts

The best AI finance tool isn’t necessarily the one with the most features—it’s the one you’ll actually use consistently. Start with a tool that matches your current needs, learn its features, and build better financial habits over time. As your goals evolve, you can always switch to a platform that offers more advanced capabilities. Making informed financial decisions consistently is far more important than choosing the most popular app.

What is the best AI tool for personal finance in 2026?


The best AI Tool for Personal Finance depends on your financial goals. ChatGPT is ideal for budgeting and financial guidance, Claude is excellent for in-depth financial research, and Perplexity AI is a strong choice for real-time financial information. Budgeting-focused users may also prefer YNAB or Rocket Money.

Are AI tools for personal finance safe to use

Are AI tools for personal finance safe to use?Yes, most reputable AI Finance Apps use encryption and industry-standard security practices to protect user data. Before using any platform, review its privacy policy, enable two-factor authentication when available, and avoid sharing highly sensitive financial information unless necessary.

Can AI help me save more money?Yes. Modern AI Budgeting Tools

Can AI help me save more money?Yes. Modern AI Budgeting Tools analyze your spending habits, categorize expenses, identify recurring subscriptions, and provide personalized suggestions that may help you improve your budget and increase savings. AI should be used as a decision-support tool rather than a replacement for your own financial judgment.

Article Summtools for personal finance ary
AI tools for personal finance are transforming the way people manage money by simplifying budgeting, expense tracking, savings, and financial planning. In this guide, we explored how AI finance tools work, the key factors to consider before choosing one, and the 10 best AI tools for personal finance in 2026. We also compared their features, strengths, limitations, pricing, and ideal use cases to help you make an informed decision. Whether you’re a beginner looking for smarter budgeting or a professional seeking advanced financial insights, the right AI tool can save time, improve financial habits, and support better long-term money management. The best choice is the one that aligns with your financial goals, budget, and everyday needs.

10 Best Financial Habits Every College Student Should Develop (2026)

10 Best Financial Habits Every College Student Should Develop to Save Money, Budget Better, and Build Long-Term Wealth

INTRODUCTION

Starting college is exciting, but it also brings new financial responsibilities. For many students, this is the first time they have complete control over their money. Whether you receive a monthly allowance from your family, earn ₹10,000–₹20,000 ($100–$300) from a part-time job, or manage a scholarship, every financial decision you make today shapes your future.

1.Why Financial Habits Matter in College

College is more than a place to earn a degree—it’s where your financial future quietly begins. For many students, this is the first time they manage their own money, make independent financial decisions, and learn the real difference between needs and wants. Whether your monthly income comes from a scholarship, a part-time job, freelancing, or family support, the habits you develop today will shape your financial life long after graduation.

The 10 Best Financial Habits Every College Student Should Develop aren’t simply money-saving tips. They are lifelong principles that help you build discipline, reduce financial stress, avoid unnecessary debt, and create a strong foundation for financial independence. According to the Consumer Financial Protection Bureau (CFPB), students who learn budgeting and responsible money management early are more likely to achieve long-term financial stability.

The Long-Term Impact of Small Money Decisions

Many students believe that financial success depends on earning more money. In reality, it depends on making better decisions with the money you already have.

Imagine spending just ₹200 ($2.40) every day on coffee, food delivery, online shopping, or impulse purchases. It doesn’t feel expensive because it’s only one small transaction. However, over one year, that habit costs nearly ₹73,000 ($880+)—enough to buy a quality laptop, build an emergency fund, pay for professional certifications, or even start investing.

Now imagine doing the exact opposite.

Instead of spending that ₹200 every day, you save or invest it consistently. Without increasing your income, you’ve already created a financial system that works for you rather than against you.

This is why experts often say that wealth isn’t built by one big decision—it is built by thousands of small decisions repeated consistently.

A Simple Real-Life Example

Consider two college students who each receive ₹15,000 ($180) every month.

The first student spends money whenever they feel like it. They never check where their money goes and often run out of cash before the month ends.

The second student receives the same amount but saves 20% (₹3,000 / $36) before spending anything else. They follow a simple budget, review their expenses every weekend, and avoid unnecessary purchases.

After one year, both students earned exactly the same amount of money.

The only difference is that one developed financial stress, while the other developed financial freedom.

Why Building Financial Habits Early Gives You a Competitive Advantage

Good financial habits work like compound interest—the earlier you build them, the greater the rewards become over time.

Research from the OECD Financial Education shows that people with stronger financial literacy are more likely to save regularly, avoid unnecessary debt, and make informed financial decisions throughout their lives.

You don’t need a six-figure salary to start building wealth.

You need the discipline to make one smart financial decision today, then repeat it tomorrow, next week, next month, and next year.

Key Takeaway

Your salary may determine how much money enters your bank account.

Your financial habits determine how much of that money stays there.

Start building the right habits in college, and your future self will thank you for every smart financial decision you make today.

2. Create a Monthly Budget That Actually Works

A budget isn’t about restricting your life—it’s about giving every rupee and dollar a purpose. One of the biggest financial mistakes college students make is spending first and wondering where their money went at the end of the month. A simple monthly budget helps you stay in control, reduce financial stress, and make smarter decisions without sacrificing the things you enjoy.

Whether your monthly income is ₹10,000 ($120) or ₹25,000 ($300), budgeting ensures that your essential expenses, savings, and personal spending remain balanced. According to the Consumer Financial Protection Bureau (CFPB), creating and following a budget is one of the most effective ways to improve financial health and avoid unnecessary debt.

Why Every College Student Needs a Budget

Without a budget, it’s easy to underestimate small daily expenses. A few online orders, food deliveries, subscriptions, and impulse purchases may not seem expensive individually, but together they can consume a large portion of your monthly income.

A well-planned budget helps you:

  • Know exactly where your money goes.
  • Avoid overspending before the month ends.
  • Save consistently for future goals.
  • Prepare for unexpected expenses.
  • Spend with confidence instead of guilt.

A Simple Student Budget Example

CategoryRecommended AllocationExample (₹15,000 / $180)
Essential Expenses50%₹7,500 ($90)
Savings20%₹3,000 ($36)
Learning & Skill Development20%₹3,000 ($36)
Entertainment & Personal Spending10%₹1,500 ($18)

This isn’t a fixed rule. Adjust the percentages based on your income and responsibilities, but always make saving a priority before spending.

Budgeting Isn’t About Spending Less—It’s About Spending Smarter

Many students think budgeting means giving up everything they enjoy. In reality, budgeting gives you permission to spend on what truly matters while avoiding wasteful expenses that don’t improve your life.

Research from the OECD Financial Education shows that people who regularly plan and monitor their finances are more likely to achieve long-term financial security than those who spend without a plan.

A budget doesn’t limit your freedom—it protects your future by making every rupee and dollar work with purpose.

3. Save Money Before You Spend

One of the biggest differences between students who achieve financial stability and those who constantly struggle isn’t how much they earn—it’s when they choose to save. Most people spend first and save whatever is left at the end of the month. Unfortunately, for many college students, nothing is left to save.

Financially successful people follow a different approach known as “Pay Yourself First.” Instead of treating savings as an afterthought, they make it their first financial priority. Even if you can only save ₹100–₹300 ($1–$4) a day, that habit can grow into thousands of rupees or hundreds of dollars over time.

According to the Consumer Financial Protection Bureau (CFPB), automatically saving a portion of your income before spending can improve financial security and help you prepare for unexpected expenses.

What Does “Pay Yourself First” Really Mean?

The moment your monthly allowance, scholarship, freelance payment, or salary arrives, move a fixed percentage directly into your savings account before paying for anything else.

This simple habit changes your mindset from:

“I’ll save whatever is left.”

to

“I’ll spend only what’s left after saving.”

That small shift can completely transform your financial future.

How Much Should a College Student Save?

Monthly IncomeMinimum Savings (10%)Ideal Savings (20%)
₹10,000 ($120)₹1,000 ($12)₹2,000 ($24)
₹15,000 ($180)₹1,500 ($18)₹3,000 ($36)
₹20,000 ($240)₹2,000 ($24)₹4,000 ($48)
₹25,000 ($300)₹2,500 ($30)₹5,000 ($60)

Don’t worry if you can’t save 20% immediately. The most important goal is to build the habit of saving consistently, even if you start with a smaller amount.

Why Saving First Is More Powerful Than Saving Later

Imagine two students who each receive ₹15,000 ($180) every month.

Student A spends freely throughout the month and tries to save whatever remains. Most months, nothing is left.

Student B immediately transfers ₹3,000 ($36) into a savings account on the day the money arrives. They learn to live comfortably on the remaining ₹12,000 ($144).

After one year, Student B has saved ₹36,000 ($430+) without increasing their income. More importantly, they’ve built a habit that can continue for decades.

Research from the OECD Financial Education shows that consistent saving habits are strongly linked to better financial resilience, lower debt, and greater long-term financial confidence.

You don’t become wealthy because you save what’s left after spending. You build wealth by spending what’s left after saving.

4. Track Every Expense Without Making It Complicated

Many college students believe they don’t spend much money. However, the real problem isn’t always how much they spend—it’s not knowing where their money goes. Small daily expenses like coffee, food delivery, online subscriptions, and impulse purchases can quietly drain your budget without you noticing.

Tracking your expenses isn’t about recording every rupee forever. It’s about understanding your spending habits so you can make smarter financial decisions. According to the Consumer Financial Protection Bureau (CFPB), regularly monitoring your spending is one of the simplest ways to improve budgeting and avoid unnecessary financial stress.

A Simple Expense Tracking Method

CategoryExample
🍽️ Food & Drinks₹3,500 ($42)
🚕 Transportation₹1,200 ($14)
📚 Education₹2,000 ($24)
🎬 Entertainment₹1,000 ($12)
💰 Savings₹3,000 ($36)
📱 Other Expenses₹1,300 ($16)

You don’t need expensive apps to do this. A simple notes app, spreadsheet, or budgeting app is enough to record your daily spending for just 30 days. By the end of the month, you’ll clearly see where your money is going and which expenses can be reduced.

Pro Tip

At the end of every week, spend 10 minutes reviewing your expenses. This small habit helps you identify unnecessary spending before it becomes a long-term financial problem.

You can’t improve what you don’t measure. Tracking your expenses is the first step toward taking control of your money.

5. Build an Emergency Fund Before You Need It

Life is unpredictable. A medical emergency, laptop repair, unexpected travel, or a sudden loss of income can happen when you least expect it. Without savings, many college students rely on credit cards or borrow money from friends and family, creating unnecessary financial stress.

An emergency fund is money set aside specifically for unexpected expenses—not for shopping, vacations, or entertainment. According to the Consumer Financial Protection Bureau (CFPB), having emergency savings can help people avoid debt and recover from financial setbacks more quickly.

How Much Should a College Student Save?

Monthly ExpensesRecommended Emergency Fund
₹8,000 ($95)₹16,000–₹24,000 ($190–$285)
₹12,000 ($145)₹24,000–₹36,000 ($285–$430)
₹15,000 ($180)₹30,000–₹45,000 ($360–$540)
₹20,000 ($240)₹40,000–₹60,000 ($480–$720)

Don’t worry if you can’t build this amount immediately. Start by saving a small portion every month. Even ₹500–₹1,000 ($6–$12) saved consistently can grow into a reliable financial safety net over time.

Where Should You Keep Your Emergency Fund?

Keep this money in a separate savings account where it’s easy to access during emergencies but not so convenient that you’re tempted to spend it on everyday purchases.

An emergency fund doesn’t make you richer overnight—it gives you peace of mind when life doesn’t go according to plan.

6. Avoid Impulse Buying and Think Before You Spend

Impulse buying is one of the biggest reasons college students struggle to save money. Flash sales, limited-time offers, social media ads, and one-click online shopping make it easy to spend money on things you never planned to buy. While a single purchase may seem harmless, repeated impulse spending can quietly damage your monthly budget.

Building the habit of thinking before spending helps you stay in control of your money instead of letting emotions control your decisions. According to the Consumer Financial Protection Bureau (CFPB), creating a spending plan and avoiding emotional purchases are important steps toward better financial health.

The 24-Hour Rule

Before buying any non-essential item, wait 24 hours.

Ask yourself these simple questions:

  • Do I really need this, or do I just want it?
  • Will I still use it after one month?
  • Does this purchase fit my monthly budget?
  • Can this money be used for something more valuable?

Most impulse purchases lose their appeal after a day, helping you save money without feeling deprived.

Smart Spending Checklist

Before You BuyAsk Yourself
✅ Need or Want?Is this essential?
✅ Budget CheckCan I afford it without affecting my savings?
✅ Future ValueWill this improve my life or skills?
✅ 24-Hour RuleCan this purchase wait until tomorrow?

Every purchase is a financial decision. Spend with purpose today, and your future self will thank you tomorrow.

7. Start Investing Early—Even with a Small Amount

Many college students believe they need thousands of rupees or dollars before they can start investing. In reality, the most valuable advantage an investor has isn’t a large amount of money—it’s time. Starting early allows your investments more time to grow through the power of compounding.

You don’t have to begin with a large portfolio. Even investing ₹500–₹1,000 ($6–$12) every month can help you develop the habit of investing while learning how financial markets work. The goal during college isn’t to become rich overnight—it’s to become a disciplined long-term investor.

According to the U.S. Securities and Exchange Commission – Investor.gov, investing regularly over a long period and understanding compound growth are key principles for building long-term wealth.

What Should College Students Focus On?

Before investing, make sure you have:

  • ✅ A monthly budget
  • ✅ Consistent savings
  • ✅ An emergency fund
  • ✅ Basic investment knowledge

Once these foundations are in place, you can gradually begin your investing journey.

Investment HabitWhy It Matters
Invest Every MonthBuilds discipline and consistency
Think Long-TermReduces emotional decisions
Keep LearningHelps you make smarter investment choices
Avoid “Get Rich Quick” SchemesProtects your money from unnecessary risks

A Long-Term Mindset Wins

Successful investing isn’t about predicting tomorrow’s market. It’s about staying patient, investing consistently, and allowing time to work in your favor.

The best time to start investing was yesterday. The second-best time is today. Small investments made consistently can grow into significant wealth over the long term.

8. Avoid High-Interest Debt and Borrow Responsibly

Debt isn’t always bad, but high-interest debt can quickly become a financial burden—especially for college students with limited income. Many students borrow money for non-essential purchases, use credit cards carelessly, or take personal loans without understanding how interest works. These small decisions can create long-term financial stress.

Learning to borrow responsibly is one of the best financial habits every college student should develop. If you need to borrow money, make sure it’s for an important purpose such as education, an emergency, or something that genuinely improves your future—not for impulse shopping or luxury purchases.

According to the Consumer Financial Protection Bureau (CFPB), understanding interest rates, repayment terms, and borrowing limits can help consumers avoid unnecessary debt and protect their financial well-being.

Good Debt vs. Bad Debt

Type of DebtSmart or Risky?Example
📚 Education Loan✅ Good (when planned wisely)College tuition or skill development
🏥 Emergency Medical Loan✅ GoodUnexpected medical expenses
📱 Buying the Latest Phone on Credit❌ RiskyNon-essential purchase
🛍️ Shopping with Borrowed Money❌ RiskyClothes, gadgets, luxury items

Borrow Only When Necessary

Before taking any loan or using a credit card, ask yourself:

  • Do I really need this money?
  • Can I comfortably repay it on time?
  • Will this borrowing improve my future or just satisfy a temporary desire?

If the answer is no, it’s usually better to wait, save, and pay with your own money.

Debt can be a useful financial tool when used wisely—but when used carelessly, it can delay your financial freedom for years.

9. Set Clear Financial Goals and Review Your Progress

Without a clear goal, it’s easy to spend money without thinking about the future. Financial goals give your money a purpose and help you stay motivated, even when it’s tempting to make unnecessary purchases. Whether your goal is building an emergency fund, buying a laptop, starting to invest, or graduating without debt, having a written plan makes it much easier to stay on track.

The best financial habits every college student should develop include setting both short-term and long-term goals. According to the Consumer Financial Protection Bureau (CFPB), people who write down their financial goals and regularly review their progress are more likely to achieve them than those who simply keep goals in their mind.

Set SMART Financial Goals

Your financial goals should be Specific, Measurable, Achievable, Relevant, and Time-bound (SMART).

GoalTargetTime Frame
💰 Build an Emergency Fund₹30,000 ($360)12 Months
💻 Buy a Laptop₹60,000 ($720)18 Months
📈 Start Investing₹1,000/monthThis Month
📚 Skill DevelopmentComplete 2 Online Courses6 Months

Review Your Goals Every Month

At the end of each month, ask yourself:

  • ✅ Did I stay within my budget?
  • ✅ Did I save the amount I planned?
  • ✅ Am I getting closer to my financial goal?
  • ✅ What financial mistake can I avoid next month?

Even if your progress is slow, consistency matters more than perfection.

A goal without a plan is only a wish. Give every rupee and every dollar a purpose, and your financial future will become much clearer.

10. Review Your Finances Every Month and Keep Improving

Building good financial habits isn’t a one-time task—it’s an ongoing process. Even the best budget won’t help if you never review it. That’s why one of the best financial habits every college student should develop is setting aside a few minutes every month to evaluate their financial progress.

A monthly financial review helps you understand what’s working, identify unnecessary expenses, improve your savings, and make better decisions for the next month. According to the Consumer Financial Protection Bureau (CFPB), regularly reviewing your budget, savings, and financial goals can improve money management and reduce financial stress over time.

Your 15-Minute Monthly Money Review

At the end of each month, answer these questions honestly:

Review QuestionYour Goal
💰 Did I stay within my monthly budget?Yes
📊 Did I save at least 10–20% of my income?Yes
🛒 What was my biggest unnecessary expense?Identify & reduce it
🎯 Am I closer to my financial goals?Measure your progress
📚 What financial lesson did I learn this month?Improve next month

You don’t need complicated spreadsheets or expensive apps. A notebook, spreadsheet, or budgeting app is enough to review your finances in just 15 minutes every month.

Small Improvements Lead to Big Results

If you improve your financial habits by just 1% every month, you’ll make significantly better financial decisions over the course of a year. Review your progress, celebrate small wins, learn from mistakes, and keep moving forward.

Financial success isn’t about being perfect every month—it’s about becoming a little smarter with your money every single month.

### Can college students become financially independent while studying?

Yes. Financial independence doesn’t happen overnight, but college students can begin building it by following a budget, saving consistently, developing valuable skills, earning through part-time work or freelancing, and avoiding unnecessary debt. The earlier you start, the stronger your financial future becomes.

What is the 50/30/20 budgeting rule for college students?

The 50/30/20 budgeting rule recommends using **50%** of your income for essential needs, **30%** for personal wants, and **20%** for savings or investments. It’s a simple budgeting framework that helps college students manage money more effectively and build healthy financial habits.

How much emergency savings should a college student have?

A good starting goal is to save enough to cover **one to three months of essential expenses**. If that’s not possible, begin with a smaller target such as **₹10,000–₹20,000 ($120–$240)** and increase your emergency fund gradually through consistent monthly savings.

### Which financial skill should every college student learn first?

Budgeting is the most important financial skill for college students. Once you understand how to manage your income and expenses, it becomes much easier to save money, avoid debt, invest wisely, and achieve your long-term financial goals.

## ConclusionDeveloping strong financial habits during college is one of the smartest investments you can make for your future. By creating a budget, saving consistently, tracking expenses, avoiding unnecessary debt, and setting clear financial goals, you’ll build a solid foundation for long-term financial success.Remember, financial freedom doesn’t depend on how much you earn—it depends on how wisely you manage your money. Start with one habit, stay consistent, and improve a little every month. Over time, these small actions can lead to greater financial confidence, stability, and lasting wealth.**The best financial habits you build today can shape a more secure and successful tomorrow.**

Best Investments for College Students with $100: A Complete Beginner’s Guide (2026)

introduction

Best Investments for College Students with $100 might sound impossible if you’re living on a tight student budget—but what if your first $100 could become the beginning of long-term wealth?

The truth is, you don’t need thousands of dollars to start investing. Thanks to modern investment platforms, college students can begin investing with as little as $100 while learning valuable financial skills for the future.

In this complete beginner’s guide, you’ll discover the Best Investments for College Students with $100, learn how to choose the right investment, avoid costly beginner mistakes, and build a smart investing strategy that can grow with you for years to come.

Why Should College Students Start Investing with $100?

Many people think Best Investments for College Students with $100 is just another finance topic, but it’s actually about building a strong financial future with a small amount of money. You don’t need thousands of dollars to start investing. What matters most is starting early, learning consistently, and allowing time to work in your favor.

Why $100 Is More Than Enough to Start

Starting with $100 helps you build confidence and practical investing experience without taking unnecessary financial risks. Many modern brokerage platforms allow beginners to invest in ETFs, index funds, mutual funds, and fractional shares with a small investment.

What Can You Invest In?

  • Index Funds
  • ETFs (Exchange-Traded Funds)
  • Mutual Funds
  • Fractional Shares
  • High-Yield Savings Accounts

Before making your first investment, spending time with Investment Basics for Beginners can help you understand how markets work and make smarter decisions.

The Biggest Advantage College Students Have

Most people believe money is the biggest advantage in investing. In reality, time is your greatest asset. The earlier you begin, the more opportunity your investments have to grow through compounding.

Why Starting Early Matters

  • More years for your investments to grow.
  • Small investments can become significant over time.
  • Less pressure to invest large amounts later in life.
  • Better opportunity to recover from market downturns.

Learning about Compound Interest is one of the best ways to understand why starting with $100 today can be more valuable than waiting until you have thousands of dollars.

Build Financial Habits That Last a Lifetime

Finding the Best Investments for College Students with $100 is only the first step. Long-term success depends on developing smart financial habits that you continue after graduation.

Essential Habits Every Student Investor Should Build

  • Invest consistently.
  • Create a monthly budget.
  • Reinvest your returns whenever possible.
  • Keep learning through trusted resources like Investopedia, Morningstar, and the Vanguard Learning Center.
  • Understand Investment Diversification before building your portfolio.

Focus on Learning Before Chasing Profits

Many beginners expect quick profits and become disappointed when markets fluctuate. Successful investors focus on gaining knowledge first and returns second. The more you learn today, the better your investment decisions will be in the future.Global Index Funds vs S&P 500: The Smarter Choice for Beginner Investors in 2026

Things to Do Before Investing Your First $100

Before choosing the Best Investments for College Students with $100, you should prepare yourself financially. Even the best investment can become a bad decision if you invest without a plan. These simple steps will help you protect your money and make smarter investment decisions from the beginning.

Set a Clear Financial Goal

Don’t invest just because everyone else is investing. Decide whether your goal is long-term wealth, saving for future education, buying a laptop, or achieving financial independence. A clear goal helps you choose the right investment strategy and stay focused.

Questions to Ask Yourself

  • Why am I investing?
  • When will I need this money?
  • How much risk can I take?

Create a Small Emergency Fund

Before investing your first $100, keep some cash aside for emergencies. This prevents you from selling your investments during unexpected situations like medical expenses or urgent travel.

A Good Starting Target

  • Save at least $100–$300.
  • Keep it in a safe savings account.
  • Use it only for real emergencies.

Understand Your Risk Tolerance

Every investment carries some level of risk. Some investments offer higher growth but greater volatility, while others are more stable. Learning your Risk Tolerance helps you make better investment choices instead of following trends.

Simple Risk Check

  • Can you leave your money invested for 5 years?
  • Will you stay calm if the market falls?
  • Are you investing for short-term or long-term goals?

Learn Before You Invest

Knowledge is one of the best investments you’ll ever make. Spend time learning from trusted resources like Investopedia, https://www.investor.gov/and before investing your money. The more you learn today, the fewer mistakes you’ll make tomorrow.Related Reading I Need to Make $100 as a Student 7 Easy Ways That Actually Work

Best Investment Options for College Students with $100

Choosing the Best Investments for College Students with $100 isn’t about chasing the highest returns—it’s about selecting investments that match your financial goals, risk tolerance, and time horizon. Even with just $100, you can build a diversified portfolio and start your wealth-building journey.

Index Funds – Best for Long-Term Growth

Index Funds are one of the smartest choices for beginners because they invest in hundreds of companies at once. They offer diversification, low fees, and strong long-term growth potential.

Why Choose Index Funds?

  • Low investment risk
  • Broad diversification
  • Low expense ratio
  • Beginner-friendly

Learn more from Investopedia and S&P 500.

ETFs – Flexible and Affordable Investing

ETFs work like stocks but provide the diversification of mutual funds. They’re easy to buy, low-cost, and perfect for students starting with $100.

Key Benefits

  • Low fees
  • Easy trading
  • Diversified portfolio
  • Long-term growth

Explore ETF Investing and Morningstar for deeper insights.

Fractional Shares – Invest in Top Companies

With Fractional Shares, you can own a small piece of companies like Apple or Microsoft without buying a full share.

Best For

  • Small budgets
  • First-time investors
  • Long-term investing

Understand how Fractional Investing works before getting started.

High-Yield Savings Account – Safety First

If you may need your money soon, a High-Yield Savings Account offers a safer place to keep your savings while earning interest.

Best For

  • Emergency funds
  • Short-term goals
  • Low-risk investors

Compare options using Bankrate.

Which Investment Is Right for You?

The Best Investments for College Students with $100 depend on your personal goals.

  • Long-term growth → Index Funds
  • Flexibility → ETFs
  • Individual companies → Fractional Shares
  • Maximum safety → High-Yield Savings Account

Before investing, continue learning through Investopedia, https://www.investor.gov/ and https://www.morningstar.com/the Vanguard Learning Center to make smarter financial decisions.Releted post Top 10 Finance Skills That Can Help Students Earn Money in Real Life

How to Build Your First $100 Investment Portfolio

After understanding the Best Investments for College Students with $100, the next step is creating a simple portfolio. A portfolio is a collection of investments that helps you reduce risk while giving your money the opportunity to grow over time. Instead of investing your entire $100 in one place, spreading it across different assets can be a smarter strategy.

A Simple $100 Portfolio Example

Investment OptionAllocationAmount
Index Fund50%$50
ETF30%$30
Fractional Shares20%$20

Why This Portfolio Works

  • Reduces investment risk through diversification.
  • Gives exposure to both the overall market and individual companies.
  • Beginner-friendly and easy to manage.
  • Helps build long-term investing habits.

To understand portfolio building, learn about Asset Allocation and Diversification before making your first investment.

Invest Consistently Instead of Waiting

Your first $100 is only the beginning. If you continue investing even a small amount every month, your portfolio can grow significantly over time. This strategy is known as Dollar-Cost Averaging, where you invest regularly regardless of market conditions.

Monthly Investment Example

Monthly Investment1 Year5 Years
$25$300 Invested$1,500 Invested
$50$600 Invested$3,000 Invested
$100$1,200 Invested$6,000 Invested

Continue improving your investing knowledge through https://www.morningstar.com/portfolios andhttps://www.schwab.com/learn Investor.gov, and the Vanguard Learning Center while reviewing your portfolio once or twice a year.

Common Mistakes College Students Should Avoid When Investing $100

Choosing the Best Investments for College Students with $100 is only the beginning. Many beginners lose money not because they choose the wrong investment, but because they make avoidable mistakes. Understanding these common mistakes can help you invest with more confidence and build long-term wealth.

Investing Without a Clear Goal

Many students start investing simply because everyone else is doing it. Before investing, decide whether your goal is long-term wealth, passive income, or gaining investing experience. A clear goal helps you make better financial decisions.

Ask Yourself Before Investing

  • Why am I investing?
  • How long can I keep this money invested?
  • What is my financial goal?

Trying to Get Rich Quickly

One of the biggest mistakes beginners make is chasing quick profits. Successful investing is based on patience, consistency, and long-term thinking—not overnight success.

Focus on Long-Term Growth

  • Invest regularly.
  • Ignore short-term market noise.
  • Stay invested during market ups and downs.

Learn more from Behavioral Finance.

Ignoring Diversification

Putting your entire $100 into a single stock increases risk. Diversifying your investments through index funds or ETFs can provide better stability and reduce the impact of market volatility.

A Smarter Strategy

  • Diversify your investments.
  • Review your portfolio yearly.
  • Avoid emotional investing.

Explore Morningstar to compare funds and portfolios.

Final Takeaway

The Best Investments for College Students with $100 are the ones that match your goals, fit your risk tolerance, and help you stay invested consistently. Start small, keep learning, and remain patient. Over time, those small investments can become the foundation of lasting financial success.

Frequently Asked Questions (FAQs)

Can college students really start investing with just $100?

Yes. Many modern investment platforms allow college students to start investing with as little as $100. You can invest in Index Funds, ETFs, or Fractional Shares, making it easier to begin your investing journey without needing a large amount of money.

What is the best investment for college students with $100?

For most beginners, Index Funds are often considered one of the Best Investments for College Students with $100 because they offer diversification, lower risk, and long-term growth potential. However, the best choice depends on your financial goals and risk tolerance.

Can I lose money if I invest $100?

Yes. Every investment carries some level of risk, especially in the stock market. However, investing in diversified assets like Index Funds or ETFs and staying invested for the long term can help reduce risk over time.

4. Should I choose Index Funds or ETFs as a beginner?

Both are excellent options for beginners. Index Funds are ideal for long-term, hands-off investing, while ETFs offer more flexibility because they can be traded throughout the day. Your choice should depend on your investing style and financial goals.

Conclusion
Finding the Best Investments for College Students with $100 doesn’t require a large budget—it requires the right mindset and a smart strategy. By starting early, choosing beginner-friendly investments like Index Funds or ETFs, and investing consistently, you can build a strong financial foundation for the future.
Remember, successful investing isn’t about getting rich overnight. It’s about making informed decisions, staying patient, and allowing your investments to grow over time. Even your first $100 can be the beginning of a lifelong wealth-building journey.
Related Articles
How to Start Investing with Little Money
Best Budgeting Tips for College Students
Index Funds vs ETFs for Beginners

Global Index Funds vs S&P 500: The Smarter Choice for Beginner Investors in 2026

Global Index Funds vs S&P 500 comparison for beginner investors showing diversification, returns, and long-term growth potential.

introduction

Global Index Funds vs S&P 500 is one of the most common questions beginners ask when starting their investing journey. While both investment options offer diversification and long-term growth potential, they differ in terms of global exposure, risk, and returns. In this guide, we’ll compare Global Index Funds and the S&P 500 in simple terms to help you decide which option may be the better choice for your financial goals.

What Is a Global Index Fund?

1. How Does a Global Index Fund Work?

A Global Index Fund is an investment fund that allows investors to own a small share of hundreds or even thousands of companies around the world through a single investment. Instead of spending time researching individual stocks, investors can simply buy a Global Index Fund and instantly gain exposure to global markets.

For example, imagine you invest $100 per month in a Global Index Fund. Over 10 years, you would contribute $12,000 of your own money. If the fund earns an average annual return of 8%, your investment could grow to approximately $18,000–$19,000. This example shows how long-term investing and compounding can help grow wealth over time.

Most Global Index Funds track major indexes such as the MSCI World Index or the FTSE All-World Index. These indexes contain 1,000+ companies from 20+ countries, providing investors with broad diversification across different economies and industries.

A typical Global Index Fund may include global giants such as Apple, Microsoft, Nvidia, Amazon, and many other multinational corporations. Instead of relying on the success of just 1 company, investors gain exposure to hundreds or thousands of businesses through a single fund.

One of the biggest advantages of a Global Index Fund is portfolio diversification. If one country or sector performs poorly, strong performance from other regions may help balance overall returns. This is why many long-term investors prefer diversified funds over individual stock picking.

Another important benefit is passive investing. Because the fund simply follows an index, management costs are often lower than actively managed funds. A difference of just 1% per year in fees can potentially save investors thousands of dollars over a 20–30 year investment period.

For beginners looking to build long-term wealth, a Global Index Fund offers a simple way to invest globally, reduce risk through diversification, and participate in the growth of the world’s largest companies without constantly monitoring the stock market.Safe Investment Guide for Students During War Economic Crisis

What Is the S&P 500?

1. Definition of the S&P 500

The S&P 500 is one of the most popular stock market indexes in the world. It tracks the performance of approximately 500 of the largest publicly traded U.S. companies. Instead of investing in a single company, investors can gain exposure to hundreds of leading businesses through an S&P 500 index fund or ETF.

The index includes companies from multiple sectors, including technology, healthcare, finance, consumer goods, and energy. Some of the largest holdings often include Apple, Microsoft, Nvidia, Amazon, and other industry leaders.

To learn more about the index, visit the official S&P 500 Index page.

2. How Does the S&P 500 Work?

The S&P 500 is weighted by market capitalization, which means larger companies have a greater impact on the index’s performance. When major companies perform well, the overall index tends to rise.

For example, if an investor contributes $200 per month into an S&P 500 index fund, they would invest $2,400 per year. Over 20 years, that equals $48,000 in contributions. Assuming an average annual return of 10%, the investment could potentially grow to more than $150,000 through the power of long-term compounding.

Many investors choose the S&P 500 because it provides exposure to some of the most profitable companies in the world while requiring very little ongoing management.

Learn more about Market Capitalization and how index weighting works.

3. 3 Key Benefits of Investing in the S&P 500

Benefit #1: Strong Historical Performance

The S&P 500 has historically delivered attractive long-term returns, making it a popular choice for retirement and wealth-building portfolios.

Benefit #2: Low-Cost Investing

Most S&P 500 index funds have very low expense ratios. Saving even 0.50%–1% annually in fees can make a significant difference over a 20–30 year investment period.

Benefit #3: Exposure to World-Class Companies

Investors gain access to some of the world’s most successful businesses through a single investment rather than purchasing dozens of individual stocks.

To better understand index investing, explore this guide on Index Funds.

Global Index Funds vs S&P 500: Key Differences

1. Diversification: Which Investment Offers More Exposure?

One of the biggest differences between Global Index Funds vs S&P 500 is diversification. A Global Index Fund provides exposure to companies from multiple countries, while the S&P 500 focuses only on large U.S. companies.

For example, if you invest $10,000 in a Global Index Fund, your money may be spread across 20–50 countries and 1,000+ companies. In contrast, a $10,000 investment in the S&P 500 is invested entirely in the U.S. market through approximately 500 companies.

Investors looking for broader international exposure often prefer Global Index Funds, while those who believe in the long-term strength of the U.S. economy may prefer the S&P 500.

Learn more about Portfolio Diversification.

2. Returns and Growth Potential

When comparing Global Index Funds vs S&P 500, returns are one of the most important factors. Historically, the S&P 500 has often delivered higher returns because many of the world’s largest technology and growth companies are based in the United States.

Imagine two investors each invest $500 per month for 20 years.

  • Investor A chooses a Global Index Fund with an average annual return of 8%.
  • Investor B chooses the S&P 500 with an average annual return of 10%.

After 20 years:

  • Global Index Fund ≈ $294,000
  • S&P 500 ≈ $382,000

This example shows how even a small difference in annual returns can create a large gap over time through compounding.

You can learn more about Compound Interest and its impact on long-term investing.

3. Risk: Which Option Is Safer for Beginners?

Risk is another major consideration in Global Index Funds vs S&P 500. A Global Index Fund reduces dependence on a single country because investments are spread across multiple economies. If one region experiences a slowdown, other markets may help balance performance.

On the other hand, the S&P 500 depends entirely on the U.S. market. While the United States has historically been one of the strongest economies, investors face concentration risk by relying on a single country.

Risk Factor #1: Geographic Risk

A Global Index Fund spreads risk globally, while the S&P 500 is concentrated in the United States.

Risk Factor #2: Currency Risk

Global investors may face currency fluctuations when investing internationally. Understanding Foreign Exchange Risk is important before investing globally.

Risk Factor #3: Market Concentration

The S&P 500 can become heavily influenced by a small number of large technology companies, which may increase concentration risk during certain market conditions.

For beginners, both options can be excellent long-term investments, but the right choice depends on whether you prioritize global diversification or greater exposure to the U.S. market.

Global Index Funds vs S&P 500: Key Differences

1. Diversification Comparison

One of the biggest differences between Global Index Funds vs S&P 500 is diversification. A Global Index Fund invests across multiple countries and industries, while the S&P 500 focuses only on large U.S. companies.

For example, if you invest $10,000 in a Global Index Fund, your money may be spread across 1,000+ companies in 20–50 countries. In comparison, a $10,000 investment in the S&P 500 provides exposure to around 500 U.S. companies.

Investors who want maximum diversification often prefer Global Index Funds, while those seeking concentrated exposure to America’s largest companies may choose the S&P 500.

2. Returns and Growth Potential

Historically, the S&P 500 has delivered stronger returns than many international markets because it includes some of the world’s most profitable companies.

Suppose two investors contribute $500 per month for 20 years.

  • Investor A chooses a Global Index Fund with an average return of 8%.
  • Investor B chooses the S&P 500 with an average return of 10%.

After 20 years:

  • Global Index Fund ≈ $294,000
  • S&P 500 ≈ $382,000

This creates a difference of approximately $88,000, despite both investors contributing the same amount of money.

3. Global Index Fund vs S&P 500 Comparison Chart

FeatureGlobal Index FundS&P 500
Number of Companies1,000+Around 500
Countries Covered20–50+ CountriesUnited States Only
DiversificationVery HighHigh
Global ExposureExcellentLimited
Historical Return Potential8–10%10–12%
Risk LevelModerateModerate to High
Currency RiskYesLow
Expense RatioLowVery Low
Best ForGlobal DiversificationU.S. Growth
Beginner FriendlyYesYes

Quick Verdict

✔ Choose a Global Index Fund if you want worldwide diversification and lower dependence on a single country.

✔ Choose the S&P 500 if you want stronger exposure to America’s largest companies and higher historical growth potential.

✔ Many experienced investors combine both investments to benefit from global diversification and long-term U.S. market growth.

Final Verdict: Global Index Funds or S&P 500?

Which Investment Is the Smarter Choice for Beginners?

After comparing Global Index Funds vs S&P 500, the truth is that both can be excellent long-term investments. The better option depends on your investment goals, risk tolerance, and how much diversification you want in your portfolio.

A Global Index Fund is ideal for investors who want exposure to companies from around the world through a single investment. Instead of depending on one country, your money is spread across multiple economies and industries. This broader diversification can help reduce country-specific risk over the long term.

On the other hand, the S&P 500 focuses entirely on America’s largest companies. Historically, many of these businesses have delivered strong growth, making the S&P 500 one of the most popular investment choices for wealth building.

Example Portfolio Allocation

Suppose you have $10,000 to invest:

Option 1: Conservative Diversification

  • $7,000 in a Global Index Fund
  • $3,000 in the S&P 500

Best for investors who prioritize diversification.

Option 2: Balanced Strategy

  • $5,000 in a Global Index Fund
  • $5,000 in the S&P 500

Best for investors seeking a balance between global exposure and U.S. growth.

Option 3: Growth-Focused Strategy

  • $3,000 in a Global Index Fund
  • $7,000 in the S&P 500

Best for investors who strongly believe in long-term U.S. market growth.

Final Takeaway

If you want maximum diversification, choose a Global Index Fund.

If you want higher historical growth potential, choose the S&P 500.

If you cannot decide between the two, consider owning both. Many experienced investors combine Global Index Funds and the S&P 500 to create a diversified portfolio that benefits from worldwide market exposure and long-term U.S. economic growth.

For most beginners, consistency matters more than choosing the perfect fund. Investing regularly, staying invested for decades, and allowing compound growth to work over time are often more important than selecting one investment over another.Top Mutual Funds With 35%+ One-Year Returns — Deep Dive Analysis & Guide (2026 Data)

Summary

Both Global Index Funds and the S&P 500 are excellent investments for beginners. A Global Index Fund offers broader diversification by investing in companies across many countries, while the S&P 500 focuses on America’s largest and most successful businesses.

If your goal is global exposure and lower country-specific risk, a Global Index Fund may be the better choice. If you want stronger historical returns and believe in the long-term growth of the U.S. economy, the S&P 500 may be a better fit.

Ultimately, the best investment is the one you can consistently hold for the long term. Many successful investors even combine both to enjoy the benefits of global diversification and U.S. market growth.

### What is the main difference between a Global Index Fund and the S&P 500?

A Global Index Fund invests in companies from multiple countries around the world, providing broad international diversification. In contrast, the S&P 500 tracks approximately 500 of the largest publicly traded companies in the United States. The main difference is that a Global Index Fund offers global exposure, while the S&P 500 focuses entirely on the U.S. market.

Which investment is better for beginners?

Both can be excellent choices for beginners. A Global Index Fund is often preferred by investors who want maximum diversification and lower dependence on a single country. The S&P 500 may be a better option for those who believe in the long-term growth of the U.S. economy and want a simple, low-cost investment strategy.

Can I invest in both a Global Index Fund and the S&P 500?

Yes. Many experienced investors combine both investments in the same portfolio. This approach allows investors to benefit from global diversification while still maintaining strong exposure to leading U.S. companies. A balanced portfolio may help reduce risk while capturing growth opportunities from different regions of the world.